
 Butternut Squash Market | 2026-2036
Butternut Squash Market Size, Share, and Industry Trends Forecast 2026-2036
Butternut Squash Market Analysis
The EU Green Deal is hardening sustainability requirements for vegetable supply chains entering European markets. Del Monte Foods leverages its integrated sourcing network to secure consistent butternut squash volumes across multiple growing regions. Stahlbush Island Farms anchors its position through certified sustainable farming practices and frozen product specialization. Bonduelle competes aggressively in the European frozen vegetable segment with established retail distribution.
Butternut squash is a winter squash cultivar of Cucurbita moschata with elongated pear-shaped fruit, typically weighing two to five pounds, featuring orange flesh with sweet, nutty flavor and dense texture suited for roasting, pureeing, and soup applications. The fresh segment dominates value contribution due to perishability premiums and seasonal pricing volatility, while frozen formats sustain growth through extended shelf life and food service contract reliability. Puree applications occupy expanding positions in infant nutrition and prepared meal formulations where smooth consistency and natural sweetness reduce added sugar requirements.
The USDA enforces grading standards for squash quality and sizing that determine market access for domestic producers, while FDA food safety regulations govern processing, labeling, and pathogen control across fresh-cut and frozen operations. Organic certification through USDA-accredited bodies creates price-tier differentiation that channels margin pools toward certified growers. Stakeholders must monitor water allocation policies in California and Mexico's primary growing basins, as irrigation restrictions threaten supply continuity and reshape sourcing geography decisions.
Market Dynamics
Fresh produce procurement by North American food service chains is hardening demand for year-round supply consistency, forcing cultivation geography diversification and cold-chain infrastructure investment across multiple growing basins.
Growth Catalysts
- EU Green Deal sustainable agriculture mandates:The EU Green Deal's sustainable agriculture mandates are reshaping cultivation protocols across member states, creating certified supply lanes for compliant growers entering European markets.
- Infant nutrition puree demand:Puree applications occupy expanding positions in infant nutrition formulations where smooth consistency and natural sweetness reduce added sugar requirements.
- California-Mexico irrigation basins:Water allocation policies in California and Mexico's primary growing basins are accelerating sourcing geography decisions toward more resilient cultivation regions.
Market Restraints
- Perishability premiums in fresh segment:The fresh segment's perishability premiums and seasonal pricing volatility compress margin pools and limit price predictability for non-integrated distributors.
- USDA grading standard compliance costs:USDA grading standards for squash quality and sizing create market access barriers for smaller domestic producers lacking certification infrastructure.
- Processed potato and sweet potato substitution:Frozen sweet potato and processed potato products compete for similar food service contract slots, pressuring butternut squash volume commitments.
Strategic Opportunities
- Organic certification price-tier differentiation:Organic certification through USDA-accredited bodies channels margin pools toward certified growers, creating defendable premium positioning.
- Frozen format food service contract reliability:Frozen formats sustain growth through extended shelf life and food service contract reliability, opening institutional procurement channels.
- Cold-chain infrastructure investment in secondary markets:Seasonal consumption patterns in the United States drive cold-chain infrastructure investment, enabling year-round distribution to underpenetrated interior regions.
Industry Challenges
- FDA pathogen control compliance timelines:FDA food safety regulations governing processing, labeling, and pathogen control across fresh-cut and frozen operations extend facility certification timelines.
- Multi-region cultivation coordination complexity:Geographic sourcing diversification required for supply continuity creates agronomic coordination challenges across divergent climate zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butternut Squash Market |
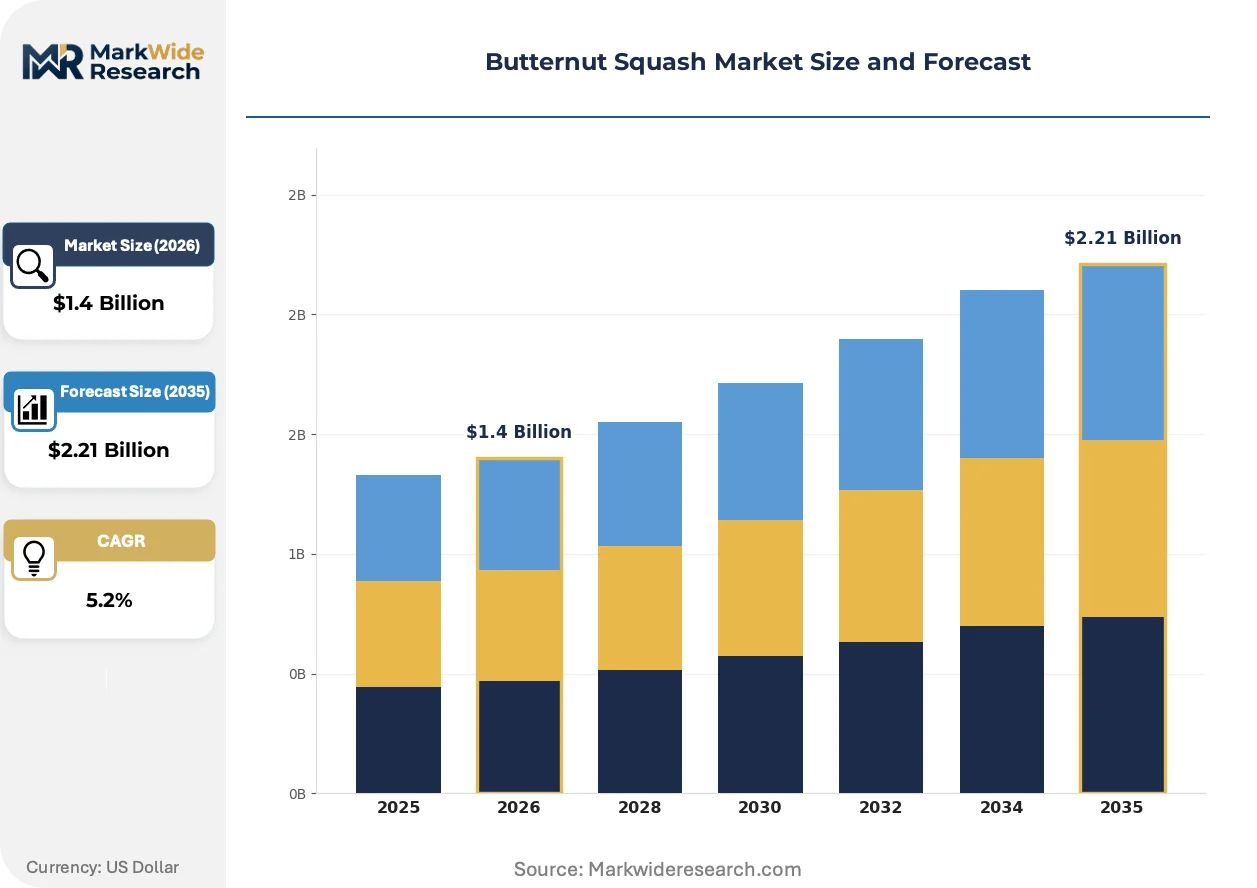
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Puree, Diced Form: Whole, Sliced, Cubed, Seeds Distribution Channel: Supermarkets, Online Retail, Farmers' Markets, Wholesalers End User: Food Service, Retail, Household, Culinarians |
| Companies Covered | ALDI, Stonehill Produce, JDM Food Group, Del Monte Foods, Bonduelle, Stahlbush Island Farms, Mackenzie, General Mills, Harris Seeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butternut Squash Market Emerging Trajectories
Controlled-environment agriculture and precision irrigation systems are rewriting cultivation economics, while regulatory frameworks harden sustainability requirements and buyer procurement models consolidate around contract reliability.
Controlled-environment agriculture with supplemental LED lighting and climate-controlled greenhouses is rewriting yield predictability for butternut squash cultivation. Large food service distributors and retail chains with year-round menu commitments are adopting greenhouse-sourced volumes at accelerating rates. This technology is compressing the traditional seasonality premium and enabling supply contracts previously impossible under field-grown constraints.
The EU Green Deal's Farm to Fork Strategy mandates pesticide reduction targets and soil health metrics that reshape import eligibility for vegetable suppliers. European frozen vegetable processors must now document cultivation practices across their entire supplier base to maintain retail distribution access. The frozen segment faces the steepest compliance burden as it sources across multiple continents to maintain volume.
Buyer consolidation among North American food service chains has compressed switching cycles and hardened contract reliability requirements. National restaurant chains now demand multi-year supply commitments with penalty clauses, displacing spot-market purchasing that dominated seasonal procurement. This pattern is most visible in the United States, where cold-chain infrastructure investment tracks directly against chain restaurant expansion timelines.
Butternut Squash Market Segmentation
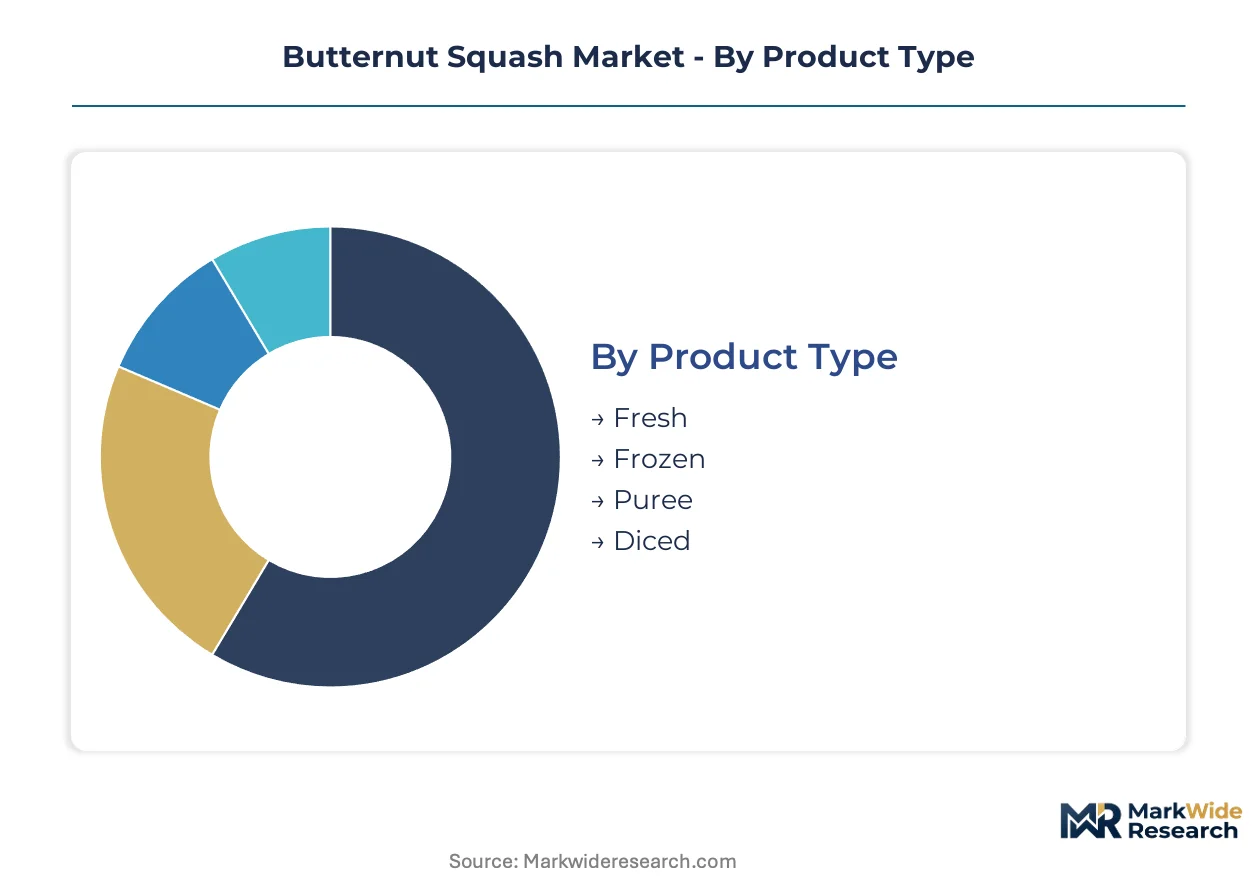
Segmentation in the butternut squash market reveals how supply chain configuration dictates margin capture across distinct product states and customer channels. Each dimension exposes different vulnerability profiles to perishability, regulatory compliance, and procurement consolidation pressures.
Product Type:
Supply concentration in fresh formats forces processors to absorb seasonal volatility through geographic diversification and cold-chain redundancy.
- Fresh:Field-harvested fruit with intact rind maintains cellular structure and flavor compounds but demands refrigerated logistics and rapid turnover. North American food service chains concentrate procurement here, driving year-round supply contracts that compress traditional seasonality premiums.
- Frozen:Blanched and individually quick-frozen segments retain nutritional density through extended shelf life. Institutional buyers in the United States favor this format for menu consistency, though EU Green Deal documentation requirements add compliance overhead for European-bound volumes.
- Puree:Thermally processed smooth consistency targets infant nutrition and prepared meal formulations.
- Diced:Pre-cut fresh or IQF formats reduce labor costs for commercial kitchens.
Fresh absorbs the bulk of installed capacity; frozen is expanding most quickly.
Form:
Processing depth determines which customer tiers can access butternut squash without specialized equipment or labor.
- Whole:Unprocessed fruit with full shelf life requires consumer-side preparation but commands lower per-unit cost. Retail households and independent restaurants in the United States source whole squash for cost control and preparation flexibility.
- Sliced:Uniform cross-sections enable consistent roasting times and portion control. Food service operations prioritize this format for speed-to-plate requirements in high-volume kitchen environments.
- Cubed:Pre-portioned chunks reduce kitchen labor and waste.
- Seeds:Roasted seed byproducts generate incremental revenue from processing waste streams.
Whole fruit dominates volume throughput; sliced formats climb the fastest as restaurant chains standardize prep protocols.
Distribution Channel:
Channel selection exposes suppliers to different working capital cycles and traceability documentation burdens.
- Supermarkets:Multi-banner retail networks demand consistent sizing, USDA grading compliance, and promotional slotting fees. California and Mexico growing regions concentrate supply here due to proximity to major US population corridors.
- Online Retail:Direct-to-consumer and third-party platform sales require specialized packaging for last-mile integrity. Cold-chain investment in secondary US markets enables expansion beyond traditional coastal demand centers.
- Farmers' Markets:Local procurement channels bypass conventional grading but limit scale.
- Wholesalers:Intermediate aggregators serve independent restaurants and smaller retail accounts.
Supermarkets absorb the bulk of installed capacity; online retail is expanding most quickly.
End User:
Customer type dictates contract structure, with institutional buyers hardening multi-year commitments and penalty clauses.
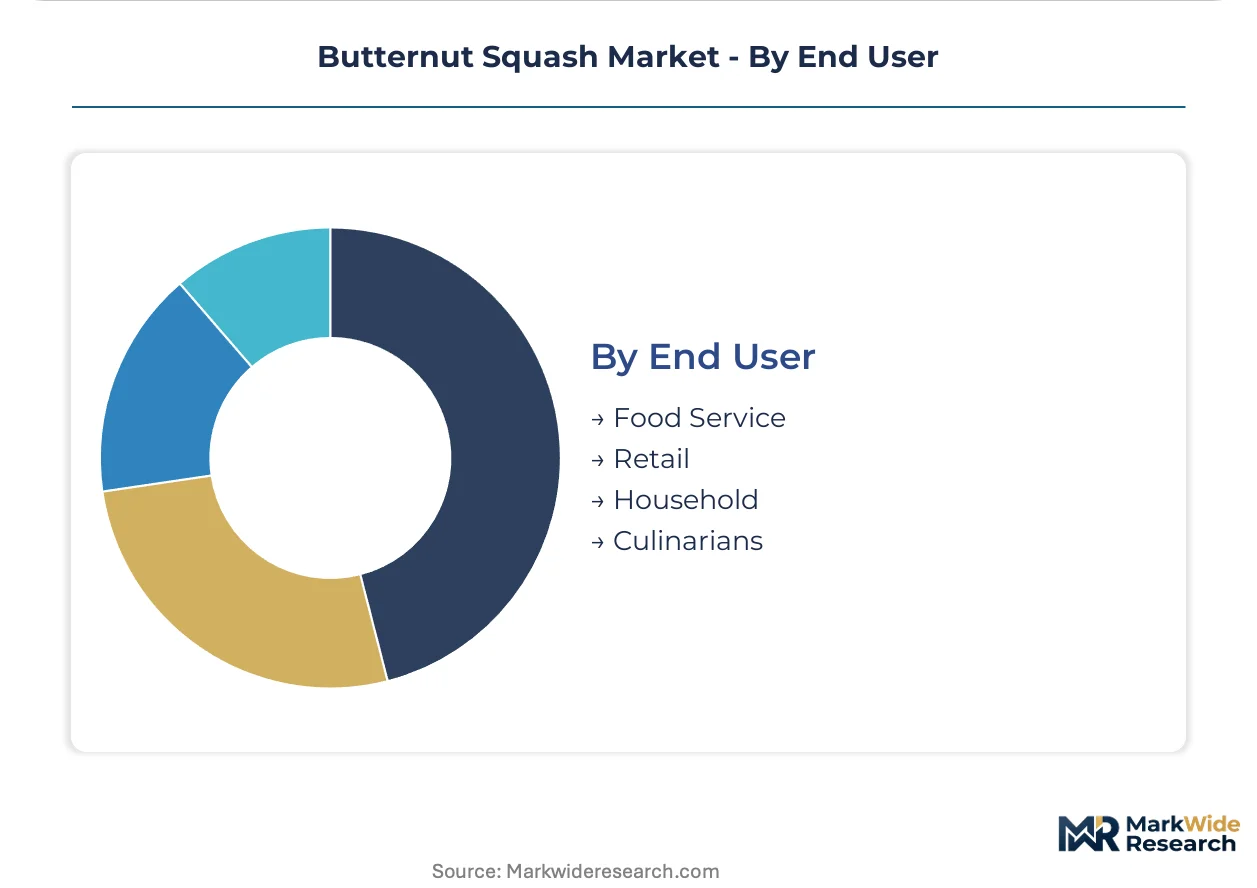
- Food Service:National restaurant chains and contract feeding operations demand specification-grade consistency with documented provenance. Buyer consolidation in the United States has compressed switching cycles and displaced spot-market purchasing.
- Retail:Grocery banners and specialty stores balance variety requirements against shrink management in fresh produce departments.
- Household:Direct consumer purchases concentrate in seasonal windows.
- Culinarians:Professional chefs and food manufacturers source for premium positioning.
Food service absorbs the bulk of installed capacity; retail channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in warm-climate growing basins while consumption clusters in temperate markets with established cold-chain networks. This geographic mismatch drives sourcing diversification and infrastructure investment across multiple cultivation regions.
United States
Year-round food service procurement from national restaurant chains hardens contract reliability requirements. USDA grading standards determine market access for domestic field-grown volumes. California's Central Valley and Mexico's Baja California peninsula anchor North American supply through complementary growing seasons.
France
Frozen vegetable processing for retail distribution demands documented provenance across supplier bases. EU Green Deal Farm to Fork Strategy mandates reshape import eligibility and cultivation protocol documentation. The Nord-Pas-de-Calais region hosts major frozen vegetable processing facilities serving European retail banners.
Mexico
Counter-seasonal production fills supply gaps during United States winter months. Water allocation policies in primary irrigation basins accelerate geographic sourcing decisions toward more resilient cultivation zones. Sinaloa and Guanajuato states concentrate field-grown volume for export-oriented supply contracts.
Canada
Controlled-environment agriculture adoption accelerates as greenhouse operators target year-round supply consistency. Health Canada and PMRA regulations govern pesticide residue limits and food safety compliance for imported fresh produce. Ontario's greenhouse corridor near Leamington expands supplemental LED lighting capacity for winter production.
Germany
Retail banner consolidation drives specification-grade consistency requirements for frozen vegetable procurement. EFSA and REACH documentation obligations add compliance overhead for suppliers entering European markets. Lower Saxony's vegetable processing cluster coordinates multi-source supply chains for private-label frozen product lines.
Butternut Squash Market Vendor Landscape
The competitive structure tilts toward diversified food conglomerates with integrated sourcing networks and specialized sustainable farming operators. Tiered positioning separates scale-driven processors with multi-continent supply bases from regional specialists emphasizing certified cultivation practices. Two strategic archetypes dominate: integrated food manufacturers leveraging backward sourcing control, and sustainability-certified farming operations capturing organic price premiums. Capacity expansion in controlled-environment agriculture and multi-year supply contract negotiations represent the dominant competitive moves reshaping procurement relationships.
Among diversified food conglomerates, Del Monte Foods and General Mills occupy positions spanning multiple product categories with sourcing infrastructure that secures consistent butternut squash volumes. Stahlbush Island Farms exemplifies the sustainability-certified specialist archetype, anchoring competitive positioning through certified farming practices and frozen format specialization. Bonduelle represents European-focused frozen vegetable processors competing through established retail distribution networks and compliance documentation capabilities for EU market access.
| Leading Market Players |
|---|
| ALDI |
| Stonehill Produce |
| JDM Food Group |
| Del Monte Foods |
| Bonduelle |
| Stahlbush Island Farms |
| Mackenzie |
| General Mills |
| Harris Seeds |
| Others |
Supply Flow & Price Mechanics
Controlled-environment agriculture with supplemental LED lighting is compressing traditional seasonality premiums while simultaneously concentrating supply leverage among greenhouse operators capable of year-round contract fulfillment. This technology shift redraws cost curves across field-grown and protected-cultivation systems, channeling procurement volume toward capital-intensive operators who capture pricing power through supply reliability guarantees.
Pricing Analysis
Margin tightening in the fresh segment reflects perishability premiums and seasonal pricing volatility that compress distributor margins during harvest windows. Three-tier pricing structure across premium organic, standard conventional, and economy-grade tiers separates USDA-certified organic growers from field-run volumes. Cost-down pressure on conventional field-grown supply accelerates because buyer consolidation among national restaurant chains demands multi-year commitments with penalty clauses. Food service chains exhibit highest price sensitivity due to contract rigidity, while infant nutrition puree manufacturers accept premium positioning for certified supply security.
Supply Chain Analysis
Direct-to-food-service channels handle institutional buyer demand through multi-year supply agreements with documented provenance requirements. Geographic supply concentration centers on California, Mexico, and Canada's Ontario greenhouse corridor, with complementary growing seasons enabling year-round North American availability. Raw material dependencies rest on irrigation water allocation, agricultural labor pools, and specialized packaging for cold-chain integrity. Single-source vulnerability concentrates in California's Central Valley, where drought restrictions threaten supply continuity. Distribution runs through refrigerated logistics networks serving supermarket banners and national restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU Green Deal Farm to Fork Strategy mandates erect barrier-to-entry moats for certified growers accessing European retail distribution.
For Market Incumbents: Anticipate water allocation policy tightening in California and Mexico by diversifying cultivation geography toward controlled-environment agriculture in Canada and secondary US growing basins. Defend margin position through backward integration into seed development and precision irrigation technology rather than spot-market volume exposure. Prioritize organic certification infrastructure investment to capture price-tier differentiation as conventional field-grown volumes face margin compression. For New Entrants and Emerging Players: Begin with frozen format specialization targeting institutional food service contracts where extended shelf life reduces perishability risk and enables contract reliability positioning. The most penetrable white space sits in online retail channels serving underpenetrated interior US regions where cold-chain infrastructure investment lags coastal demand centers. Pursue go-to-market angles emphasizing documented sustainable cultivation practices compliant with EU import eligibility requirements. For Investors and Strategic Acquirers: Re-rating potential sits with sustainability-certified farming operations given EU Green Deal documentation requirements reshaping competitive positioning for European market access. Long-term viability favors operators with captive greenhouse capacity and multi-region sourcing networks capable of withstanding climate volatility. Monitor water rights adjudication proceedings in California's Central Valley as an inflection indicator for supply geography restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Agriculture Expansion | Greenhouse operators with LED supplemental lighting capture year-round contract premiums previously impossible under field constraints. |
| Organic Certification Investment | USDA-accredited certification channels margin pools toward compliant growers as conventional volumes face price erosion. |
| Multi-Region Sourcing Diversification | Geographic spread across California, Mexico, and Canada insulates supply continuity against irrigation restriction shocks. |
| EU Green Deal Compliance Documentation | Farm to Fork Strategy pesticide reduction mandates reshape import eligibility for frozen vegetable processors serving European retail. |
| Direct-to-Food-Service Contracting | Multi-year supply agreements with penalty clauses displace spot-market purchasing among consolidated national restaurant chains. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with greenhouse operations managers, food service procurement directors, agricultural extension specialists, and frozen vegetable processing executives. USDA grading standards documentation, FDA food safety guidance, and EU Green Deal Farm to Fork Strategy publications provided regulatory framework validation. Bottom-up cultivation volume estimates triangulated against top-down food service contract value assessments.
Product type, form, distribution channel, and end user dimensions were modeled at segment-level granularity across the projection horizon. CAGRs derived from historical volume trajectories and forward-looking contract commitment analysis, with particular attention to controlled-environment agriculture adoption curves and irrigation policy scenario planning. Climate volatility assumptions and buyer consolidation patterns informed scenario-weighted outputs.
Underlying measurement precision varies by segment; fresh produce volumes carry tighter precision than emerging puree applications given established cold-chain tracking infrastructure. Forecasts reflect assumptions regarding water allocation policy continuity, labor availability in primary growing basins, and EU regulatory enforcement intensity. Periodic stress-testing of base assumptions against drought severity indices and trade policy developments is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
UAE Tomato Market
Vegetables
Potato Market
Vegetables
Global Mushroom Market
Vegetables
Garlic Market
Vegetables
Sprouts Market
Vegetables
Global Indoor Plant Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Fresh Mushroom Market
Vegetables
North America Peas Market
Vegetables
Dried Vegetable Market
Vegetables
Hydroponic Vegetable Market
Vegetables
Canada Greenhouse Horticulture Market
Vegetables
Squash Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
North America Microgreens Market
Vegetables
Dried Mushroom Market