
 Kraft Paper Tapes Market | 2026-2036
Kraft Paper Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Paper Tapes Market Foresight
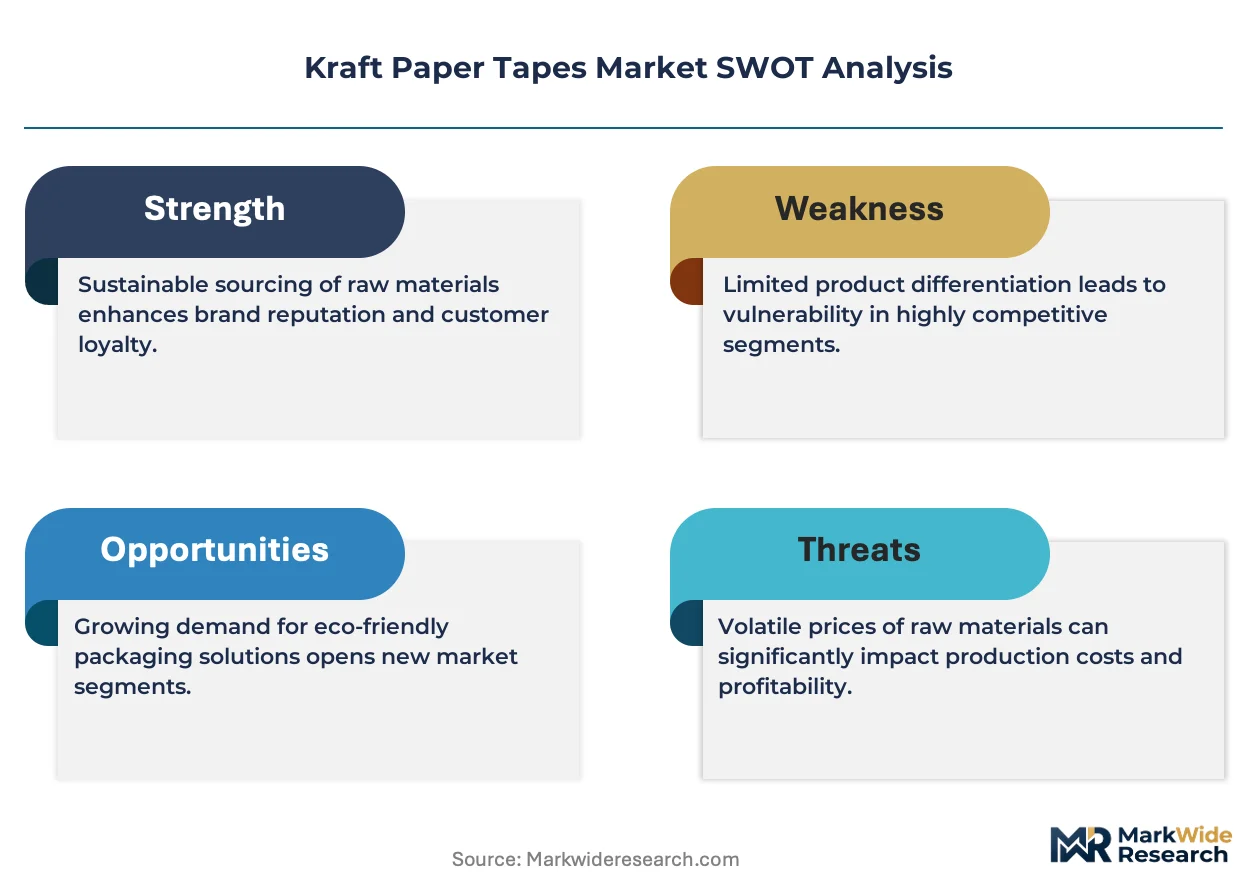
Asset-light leasing models for coating and slitting equipment are reshaping competitive entry in kraft paper tapes, allowing mid-tier converters to scale without capital-intensive infrastructure. 3M leverages its adhesive chemistry portfolio to command premium positioning in water-activated formulations. Tesa SE anchors European supply through integrated tape manufacturing in Germany. Shurtape Technologies specializes in pressure-sensitive industrial grades for corrugated sealing applications.
Kraft paper tape comprises a paper backing saturated with adhesive, typically manufactured through hot-melt or water-based coating processes at basis weights ranging from 60 to 200 grams per square meter, designed for carton sealing and fiber-based reinforcement. Reinforced kraft dominates value pools due to fiberglass or filament integration that tolerates heavy-load shipping. Water-activated kraft records the fastest expansion as e-commerce fulfillment centers phase out plastic alternatives. Standard kraft occupies mature volume share in general consumer packaging where price sensitivity limits margin expansion.
REACH compliance in Europe and FDA indirect food-contact regulations in the United States constrain adhesive formulation choices, pushing manufacturers toward water-based and bio-derived chemistries. The EU Green Deal packaging waste directives accelerate substitution of plastic tapes in cross-border shipping lanes. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and adhesive migration standards to anticipate reformulation costs and regional qualification timelines.
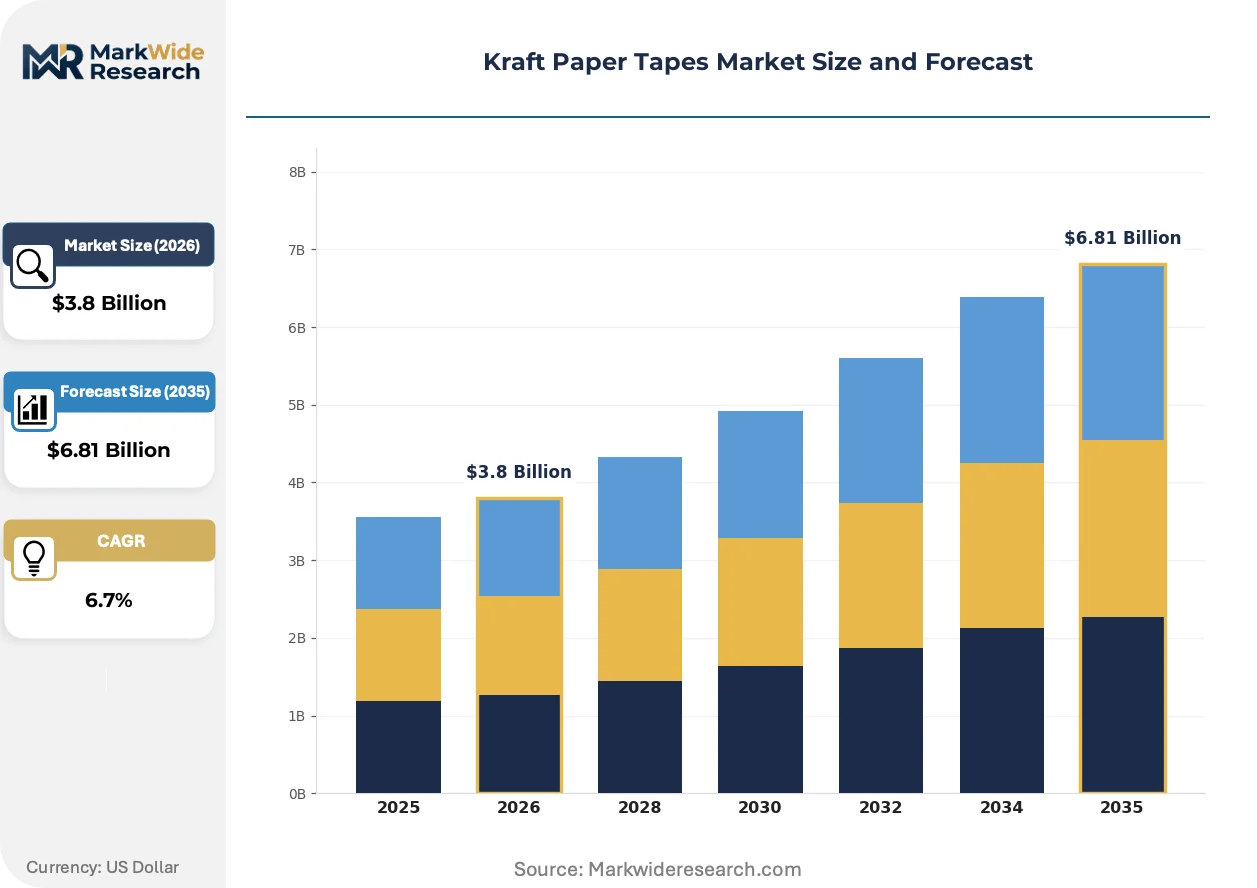
Market Dynamics
EU Green Deal packaging waste directives are forcing adhesive reformulation across European supply chains, compressing lead times for bio-derived tape qualification while automotive exporters in Germany accelerate procurement of reinforced kraft grades.
Growth Catalysts
- E-commerce fulfillment expansion:Warehouse automation in the United States and Germany is driving tape procurement volumes for carton sealing at automated packing stations.
- REACH compliance migration:ECHA pressure on solvent-based adhesives is redirecting converter investment toward water-activated chemistries and bio-based saturation systems.
- Automotive parts export packaging:German OEM supply chains require filament-reinforced kraft for heavy-load pallet stability in cross-border shipping lanes.
Market Restraints
- Pulp price volatility:Kraft paper backing costs fluctuate with Scandinavian softwood pulp contract pricing, squeezing converter margins on standard-grade products.
- Coating equipment concentration:Slitting and hot-melt coating machinery supply concentrates in Italy and Switzerland, creating capex bottlenecks for mid-tier entrants.
- Plastic tape residual substitution:Polypropylene hot-melt tapes retain cost advantage in price-sensitive consumer packaging segments, slowing kraft penetration.
Strategic Opportunities
- Indian pharmaceutical cold chain:Temperature-stable water-activated kraft formulations can displace plastic tapes in insulated shipper sealing for vaccine distribution.
- Extended Producer Responsibility frameworks:France and Germany's EPR packaging fee structures create cost parity for fiber-based versus plastic sealing solutions.
- Digital printing integration:Combination of water-activated adhesive with inline inkjet branding enables e-commerce sellers to merge security sealing with marketing messaging.
Industry Challenges
- Adhesive migration testing capacity:FDA indirect food-contact validation for kraft tape used in agricultural produce boxes requires specialized laboratory throughput that creates 12-18 month certification queues.
- Legacy slitting line reconfiguration:Converters with 1980s-era rewind equipment face integration friction when adding water-activated coating skids to existing hot-melt production footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Paper Tapes Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Kraft, Reinforced Kraft, Water-Activated Kraft, Printed Kraft End User: Packaging Industry, Crafting, Shipping & Logistics, Electrical Industry Adhesive Type: Hot Melt, Water-Based, Solvent-Based, Acrylic Paper Grade: Low Weight, Medium Weight, High Weight, Specialty Grade |
| Companies Covered | Tesa SE, Berry Global, 3M, Shurtape Technologies, Intertape Polymer Group, Nitto Denko, Henkel, Lintec Corporation, Avery Dennison, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Paper Tapes Market Shifts & Advancements
Active coating virtualization is compressing the boundary between tape manufacturing and end-use application, while regulatory chemistry constraints and procurement centralization reshape competitive positioning across converter tiers.
Water-activated adhesive saturation is virtualizing the traditional converter-distributor relationship by enabling direct-to-fulfillment-center formulation customization. Amazon and Zalando logistics hubs in Germany and Poland now specify viscosity and open-time parameters at procurement, bypassing standard SKU catalogs. This virtualization collapses inventory layers and forces coating houses to deploy modular saturation skids capable of 4-hour changeover cycles.
EU Green Deal packaging waste directives are mandating fiber-based minimum content thresholds for cross-border shipping materials by 2030. ECHA's restriction roadmap on petroleum-derived tackifiers is pushing adhesive houses toward rosin ester and starch-based alternatives. German automotive exporters face the tightest compliance windows, with BMW and Volkswagen supply chain audits now scoring tape suppliers on cradle-to-gate carbon intensity.
Centralized procurement at e-commerce platforms is consolidating tape specification authority away from individual warehouse operators. Amazon's European fulfillment network now issues continent-wide adhesive performance standards that override local converter relationships. This concentration is most visible in Poland and the Czech Republic, where regional packaging distributors have lost specification influence to Seattle-based category managers negotiating master supply agreements.
Kraft Paper Tapes Market Segmentation
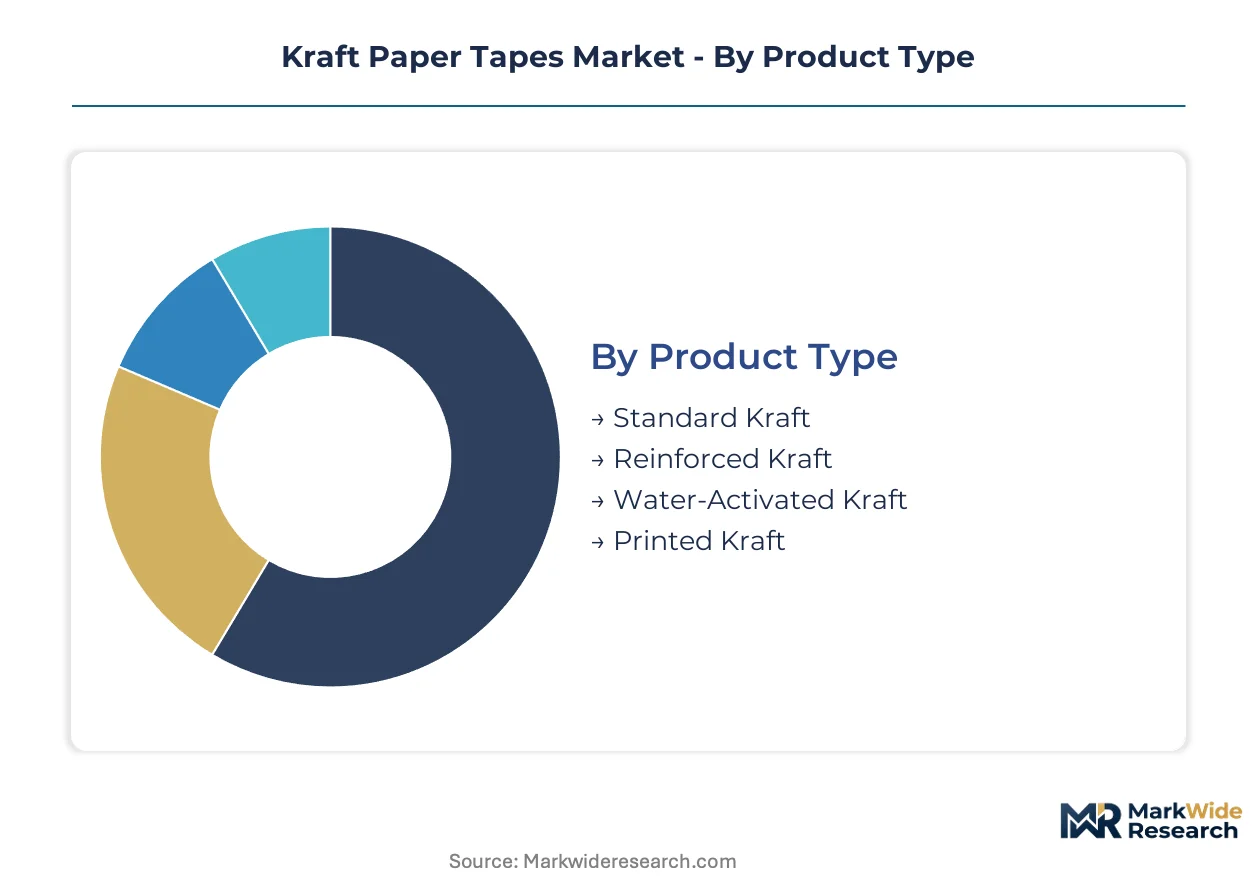
Segmentation in kraft paper tapes reveals how adhesive chemistry, backing specification, and end-use intensity create divergent margin structures. Each dimension carries distinct procurement patterns and qualification barriers that shape converter strategy.
Product Type:
Use-case spectrum spans from commodity carton sealing to engineered reinforcement for heavy-load logistics.
- Reinforced Kraft:Fiberglass or filament integration delivers tensile strength exceeding 50 pounds per inch for pallet stability. German automotive parts exporters specify this grade for cross-border heavy freight, with BMW and Volkswagen supply chains mandating cradle-to-gate carbon scoring in tape qualification.
- Water-Activated Kraft:Starch-based adhesive saturation creates permanent fiber-to-fiber bonds with corrugated board. E-commerce fulfillment centers in Poland and the Czech Republic are phasing in this grade to meet EU Green Deal packaging waste directives ahead of 2030 fiber-content thresholds.
- Standard Kraft:General-purpose hot-melt or solvent-based adhesion for consumer packaging where price sensitivity dominates procurement decisions.
- Printed Kraft:Inline branding capability merges security sealing with marketing messaging for direct-to-consumer shipments.
The dominant share belongs to Reinforced Kraft, while Water-Activated Kraft is closing the gap fastest.
End User:
Customer intensity varies from high-volume automated sealing stations to artisan-scale material consumption.
- Shipping & Logistics:Automated packing stations at Amazon and Zalando hubs drive procurement volumes exceeding standard SKU catalogs, with direct specification of viscosity and open-time parameters. Warehouse automation in Germany and the United States concentrates demand for water-activated formulations compatible with high-speed case sealers.
- Packaging Industry:Corrugated box manufacturers integrate tape sealing into finishing lines, with REACH compliance migration redirecting investment toward bio-derived saturation systems.
- Electrical Industry:Insulation and coil-winding applications require specific dielectric properties and thermal stability.
- Crafting:Low-volume decorative and structural applications favor standard kraft with aesthetic surface finishes.
Shipping & Logistics commands volume leadership, though Packaging Industry buyers are consolidating specification authority fastest.
Adhesive Type:
Chemistry selection determines regulatory qualification pathways and equipment compatibility for converters.
- Water-Based:Acrylic or starch dispersions satisfy REACH restrictions on petroleum-derived tackifiers. ECHA pressure on solvent-based alternatives accelerates converter migration toward rosin ester formulations with 4-hour coating skid changeover cycles.
- Hot Melt:Ethylene-vinyl acetate and metallocene polyolefin formulations dominate standard-grade production for speed-sensitive automated lines.
- Solvent-Based:Declining share due to ECHA restriction roadmaps and volatile organic compound emissions constraints.
- Acrylic:Pressure-sensitive variants for clean-removal applications in temporary holding and surface protection.
Water-Based chemistry is expanding most quickly, while Hot Melt retains installed-base dominance.
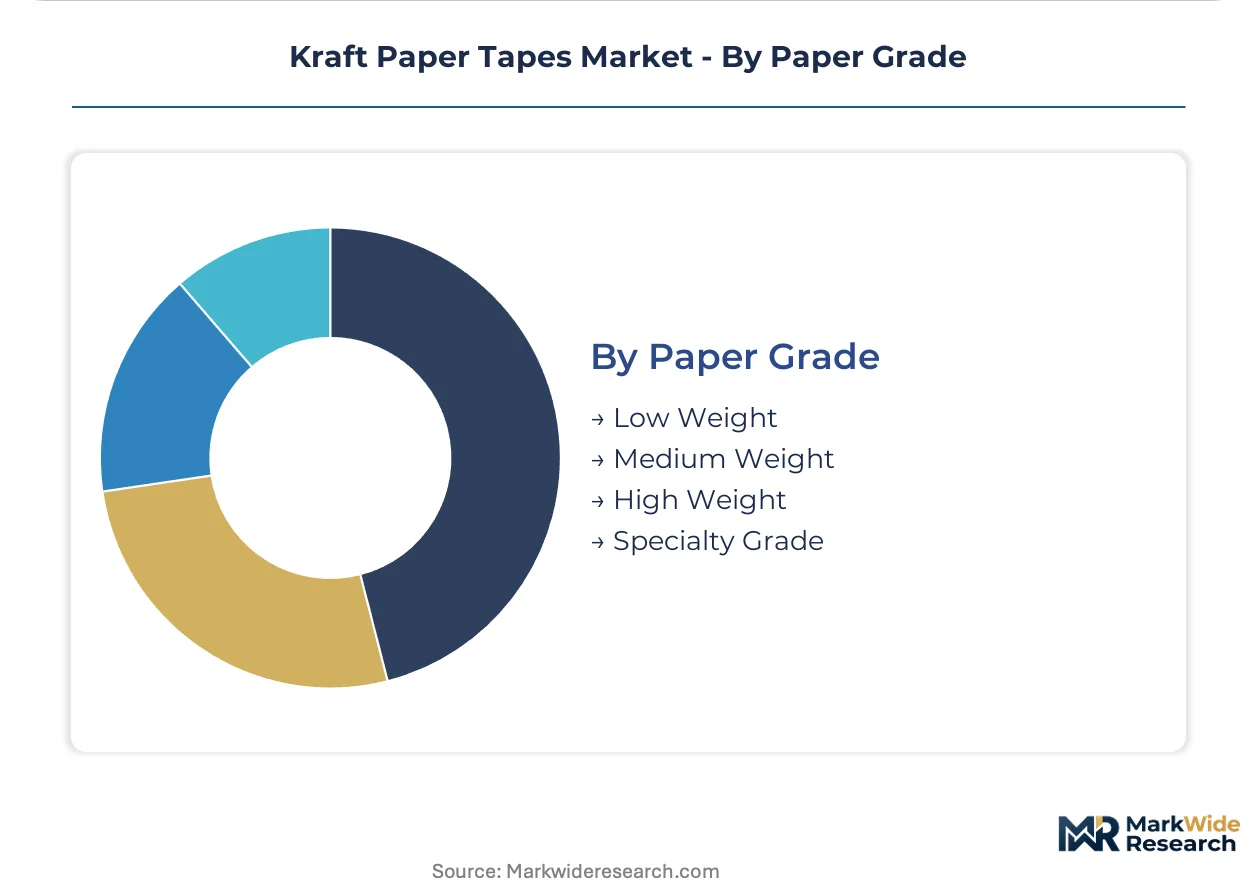
Paper Grade:
Basis weight selection maps directly to load-bearing requirements and printing compatibility.
- High Weight:150-200 grams per square meter backing tolerates extreme tensile stress in automotive and machinery export packaging. Scandinavian softwood pulp contract pricing volatility squeezes converter margins on this grade.
- Medium Weight:100-150 gsm standard for general industrial sealing with balanced cost-performance ratios.
- Specialty Grade:Chemically treated or coated surfaces for moisture resistance and FDA indirect food-contact compliance.
- Low Weight:60-100 gsm for lightweight consumer goods and decorative applications.
High Weight holds premium positioning, while Specialty Grade is climbing fastest on regulatory compliance demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing clusters drive kraft paper tape procurement patterns, with automotive supply chains and e-commerce fulfillment networks creating divergent demand profiles across major economies. Import dependency for specialty adhesive chemistries shapes regional competitive positioning.
Germany
BMW and Volkswagen supply chains mandate filament-reinforced kraft for heavy-load pallet stability in cross-border automotive parts shipping. EU Green Deal packaging waste directives compress qualification timelines for bio-derived tape formulations. Stuttgart and Wolfsburg industrial corridors concentrate converter capacity serving OEM export packaging specifications.
United States
Amazon and Walmart fulfillment center automation drives water-activated kraft procurement volumes exceeding standard SKU catalogs. FDA indirect food-contact regulations constrain adhesive migration standards for agricultural produce box sealing. Chicago and Dallas-Fort Worth logistics hubs specify viscosity parameters directly with coating houses, bypassing traditional distributor layers.
China
Domestic e-commerce platform consolidation at Alibaba and JD.com redirects tape specification authority toward centralized procurement teams. NMPA and GB standards for packaging materials accelerate substitution of solvent-based adhesives in coastal manufacturing zones. Yangtze River Delta converter clusters face pulp price volatility from Scandinavian softwood contract fluctuations.
India
Pharmaceutical cold chain expansion creates demand for temperature-stable water-activated formulations in vaccine distribution packaging. CDSCO and FSSAI compliance requirements for medical-grade sealing materials extend qualification cycles. Mumbai-Pune and Hyderabad industrial corridors develop converter capacity targeting insulated shipper applications.
Poland
Amazon and Zalando logistics hub concentration shifts procurement decisions from regional distributors to Seattle-based category managers. REACH compliance migration redirects converter investment toward water-based saturation systems. Wrocław and Poznań fulfillment centers specify open-time parameters at procurement, collapsing traditional inventory layers.
Kraft Paper Tapes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in adhesive chemistry and backing supply. The vendor base stratifies between multinational tape converters with integrated coating capacity and regional slitting houses dependent on third-party saturation. Three archetypes dominate: integrated chemical-tape manufacturers, asset-light leasing-based converters, and specialty adhesive formulators. Capacity expansion in modular coating skids and strategic partnerships for bio-derived tackifier supply represent the dominant competitive vectors.
Among integrated chemical-tape manufacturers, 3M leverages adhesive chemistry portfolios to anchor premium positioning in water-activated formulations. Tesa SE exemplifies European supply consolidation through integrated manufacturing footprints. Shurtape Technologies occupies a position among pressure-sensitive specialists targeting corrugated sealing automation.
| Leading Market Players |
|---|
| Tesa SE |
| Berry Global |
| 3M |
| Shurtape Technologies |
| Intertape Polymer Group |
| Nitto Denko |
| Henkel |
| Lintec Corporation |
| Avery Dennison |
| Others |
Supply & Pricing Matrix
Scandinavian softwood pulp contract concentration in Sweden and Finland anchors margin pool distribution downstream, with converter profitability tethered to basis weight selection and adhesive chemistry tier rather than finished tape branding.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on REACH compliance certification and volume scale, with German automotive exporters showing least sensitivity due to carbon-scoring mandates. Cost compression in standard-grade segments is intensifying because polypropylene tape alternatives retain cost advantage in price-sensitive consumer packaging.
Supply Chain Analysis
Extended payment terms from Italian and Swiss coating equipment suppliers strain working capital for mid-tier converters entering the market. Geographic supply concentrates in Germany, China, and the United States for finished tape conversion, while raw material dependencies draw from Scandinavian pulp, German adhesive resin, and Chinese fiberglass filament. Single-source vulnerability sits with hot-melt coating machinery supply. Distribution runs through regional slitting houses serving e-commerce fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging waste directives are disrupting established plastic tape supply chains, creating acceleration windows for fiber-based alternatives as 2030 compliance deadlines approach.
For Market Incumbents: Harden qualification protocols for water-activated formulations to defend against asset-light leasing entrants capturing mid-tier fulfillment contracts. Prioritize backward integration into bio-derived tackifier supply to secure rosin ester access before ECHA restrictions tighten. Carbon-scoring mandates from BMW and Volkswagen supply chains demand cradle-to-gate transparency investment. For New Entrants and Emerging Players: Indian pharmaceutical cold chain applications represent the most penetrable entry point for temperature-stable water-activated formulations displacing plastic tapes in vaccine distribution. Poland and Czech Republic Amazon fulfillment hubs offer specification influence gaps as Seattle-based procurement centralizes. Partner with modular coating skid lessors to bypass Italian equipment bottlenecks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional slitting houses holding 1980s-era rewind equipment facing water-activated reconfiguration friction. Five-to-ten year viability hinges on EPR framework expansion creating cost parity for fiber-based sealing. Monitor EU Green Deal fiber-content threshold enforcement as the signal for accelerated substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Coating Skid Deployment | Enables 4-hour changeover cycles for Amazon and Zalando direct specification contracts. |
| Bio-Derived Tackifier Partnership | Secures rosin ester supply ahead of ECHA petroleum-derived restriction roadmap implementation. |
| Carbon Scoring Certification | Qualifies tape suppliers for BMW and Volkswagen automotive export packaging mandates. |
| Water-Activated Formulation R&D | Addresses FDA indirect food-contact validation queues for agricultural produce box applications. |
| Asset-Light Leasing Expansion | Reduces capex barriers for mid-tier converters entering e-commerce fulfillment procurement. |
Research Methodology
A standing panel of coating equipment operators, adhesive formulators, corrugated box procurement managers, and e-commerce fulfillment logistics directors provided ongoing calibration. Primary interviews combined with secondary validation from customs trade data, EU ECHA restriction roadmaps, SEC converter filings, and Scandinavian pulp contract pricing indices. Bottom-up tape volume estimates triangulated against top-down packaging materials consumption models.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include product type tier, adhesive chemistry class, end-use intensity, and regional regulatory cluster. CAGRs derived from adhesive saturation capacity buildout trajectories and e-commerce fulfillment center automation deployment curves.
Macroeconomic conditions sit as an overlay; deviation in pulp commodity pricing, EU EPR fee structures, or automotive export volumes would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timing and substitution elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Strapping Tapes Market
Tapes
Global Non-Conductive Water Blocking Tape Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Removal Strips Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
Tapes Market
Tapes
Heat Release Tape Market
Tapes
Hand Wrappers Market
Tapes
Nylon Cable Ties Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Paper Masking Tapes Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
United States End-Of-Line Packaging Tape Market
Tapes
Differential Tapes Market
Tapes
Unidirectional Tapes Market