
 Global Hygiene Adhesives Market | 2026-2036
Global Hygiene Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hygiene Adhesives Market Intelligence
The European Union's Medical Device Regulation (MDR) is rebalancing the cost-of-entry calculus for new formulations by increasing compliance burdens. In this environment, Henkel leverages its significant R&D capabilities and global manufacturing footprint. H.B. Fuller differentiates through its focus on high-performance hot melt adhesives for specialized hygiene applications. Meanwhile, Dow sustains its market position through advanced polymer science and material innovation for base resins.
Hygiene adhesives are specialized bonding agents designed for constructing disposable absorbent products from nonwoven fabrics, films, and absorbent cores. These formulations, often utilizing hot melt technology, must provide secure bonds while ensuring skin safety and flexibility. Hot melt technology continues to lead due to its high-speed application compatibility on production lines. While the diapers application accounts for the largest volume, the wound care segment provides superior margin opportunities for specialized pressure-sensitive adhesives.
Product commercialization is governed by stringent regulatory frameworks. The US Food and Drug Administration (FDA) sets requirements for skin-contact materials, while the EU's REACH framework restricts certain chemical substances. Compliance with ISO 10993 standards for biocompatibility is also essential for market access in medical applications. Adhesive manufacturers must now strategically decide whether to invest in bio-based feedstocks or optimize existing petrochemical-based lines for cost-efficiency.
Market Dynamics
The imperative to comply with increasingly stringent materials safety regulations, particularly in Europe, is the central force shaping the hygiene adhesives market. This pressure is concentrating demand toward formulations with documented biocompatibility and lower volatile organic compound profiles.
Growth Catalysts
- Aging Demographics:Greater longevity in developed economies like Japan and Germany directly increases the consumer base for adult incontinence products, a primary volume driver for specialized hot melt adhesives.
- Healthcare Sector Growth:Rapid expansion of healthcare infrastructure and services in China creates substantial demand for medical-grade adhesives used in wound care and other disposable medical products.
- Margin Opportunities in Wound Care:The wound care segment offers superior margins for advanced pressure-sensitive adhesives that provide secure, yet gentle, skin contact, attracting formulation development resources.
Market Restraints
- Feedstock Price Volatility:The market's reliance on petrochemical-based feedstocks, such as base resins and polymers, exposes manufacturers to significant price fluctuations tied to global oil and gas markets.
- Regulatory Compliance Costs:Adherence to the EU's REACH and MDR frameworks elevates the cost and time required for product development, testing, and market authorization, creating barriers for smaller formulators.
- Performance Trade-offs of Bio-alternatives:Current bio-based feedstocks often present performance compromises in areas like bond strength or application speed compared to established petrochemical-based adhesives, limiting their widespread adoption.
Strategic Opportunities
- Bio-Based Formulations:Developing adhesives from renewable feedstocks helps meet brand owner sustainability goals and address regulatory pressures surrounding VOCs, particularly under the EU Green Deal.
- Specialized Medical Applications:There is significant white space in formulating adhesives for niche, high-value medical devices and advanced wound care systems that require specific adhesion and biocompatibility.
- Emerging Market Penetration:Expanding into markets like Brazil and India, where disposable hygiene product adoption is growing, offers significant volume growth potential for standard-tier formulations.
Industry Challenges
- Certification Timelines:Navigating the lengthy and complex process for achieving biocompatibility certification under standards like ISO 10993 can significantly delay the commercialization of new adhesive formulations.
- Capital Investment for Modernization:Upgrading production lines to accommodate new bio-based polymers or to achieve lower VOC emissions requires substantial capital expenditure, challenging manufacturers focused on cost-efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hygiene Adhesives Market |
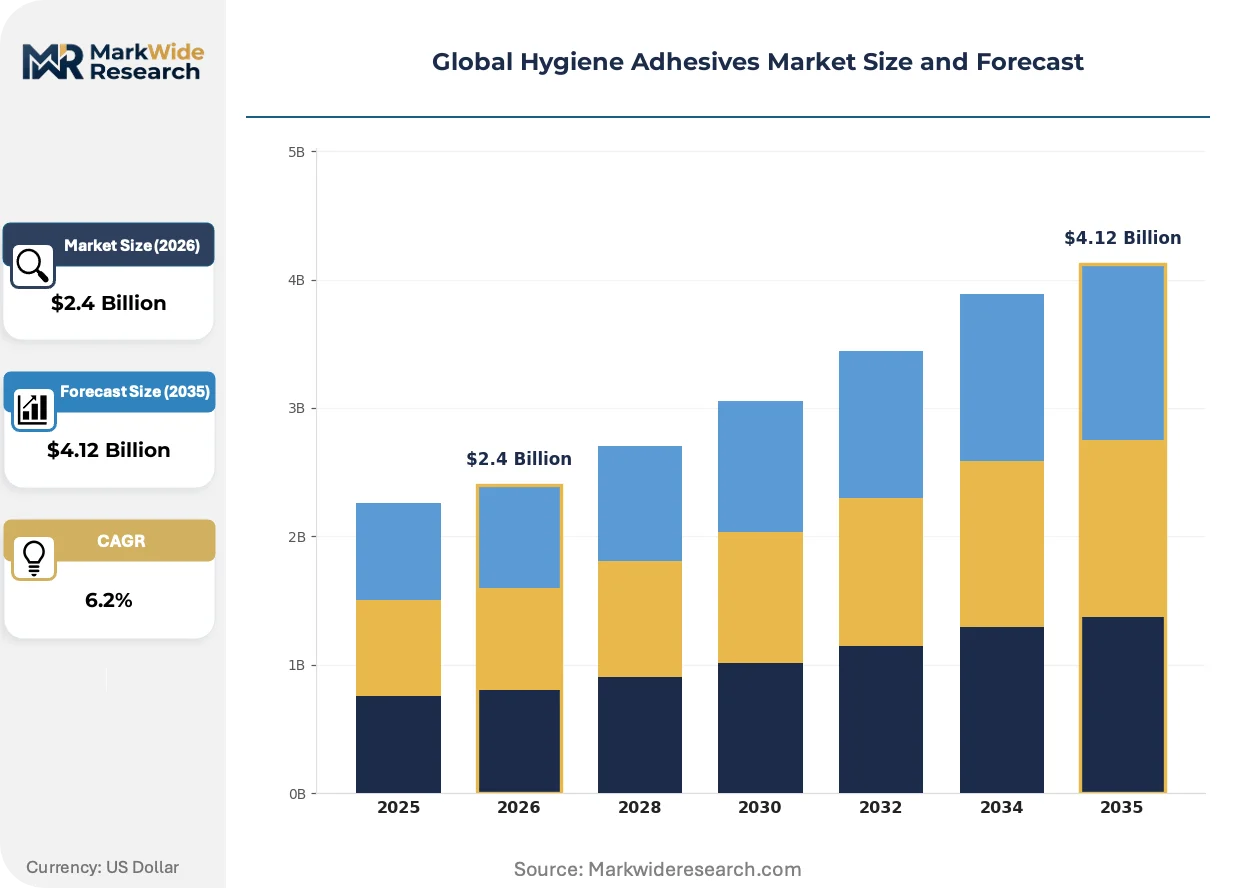
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Ethylene Vinyl Acetate, Acrylic Application: Medical Tapes, Wound Care, Hygiene Products, Diapers End User: Hospitals, Clinics, Pharmaceutical Companies, Consumer Goods Technology: Hot Melt, Pressure Sensitive, Water-Based, Solvent-Based |
| Companies Covered | 3M, Henkel, H.B. Fuller, Arkema, Dow, Synthomer, Bostik, Avery Dennison, Sika, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hygiene Adhesives Market Strategic Shifts & Innovations
Formulation science is navigating a complex intersection of material safety, production efficiency, and sustainability mandates. This dynamic forces a strategic re-evaluation of polymer science, from base resins to final adhesive properties, to meet evolving end-market expectations.
Low-VOC hot melt adhesives provide secure bonding with minimal emissions, addressing skin safety and environmental concerns. Manufacturers of premium baby diapers and adult incontinence products are adopting these formulations to meet stricter regulatory standards. Consequently, formulations engineered for biocompatibility are overtaking older, commodity-grade adhesives in high-value hygiene applications.
The European Union’s Medical Device Regulation (MDR) tightens rules for market access, demanding more extensive clinical data and biocompatibility proof. This regulation increases the compliance burden for all materials, including adhesives, used in medical-contact applications. Adhesive formulators targeting the EU wound care market must therefore invest heavily in ISO 10993 testing and documentation.
A clear consumer preference for products with transparent sustainability and safety credentials is emerging. This shift disrupts traditional purchasing criteria based on cost, favoring suppliers with certified bio-based or low-VOC options. This pattern is most pronounced in North American and European markets for feminine hygiene products and baby diapers.
Global Hygiene Adhesives Market Segmentation
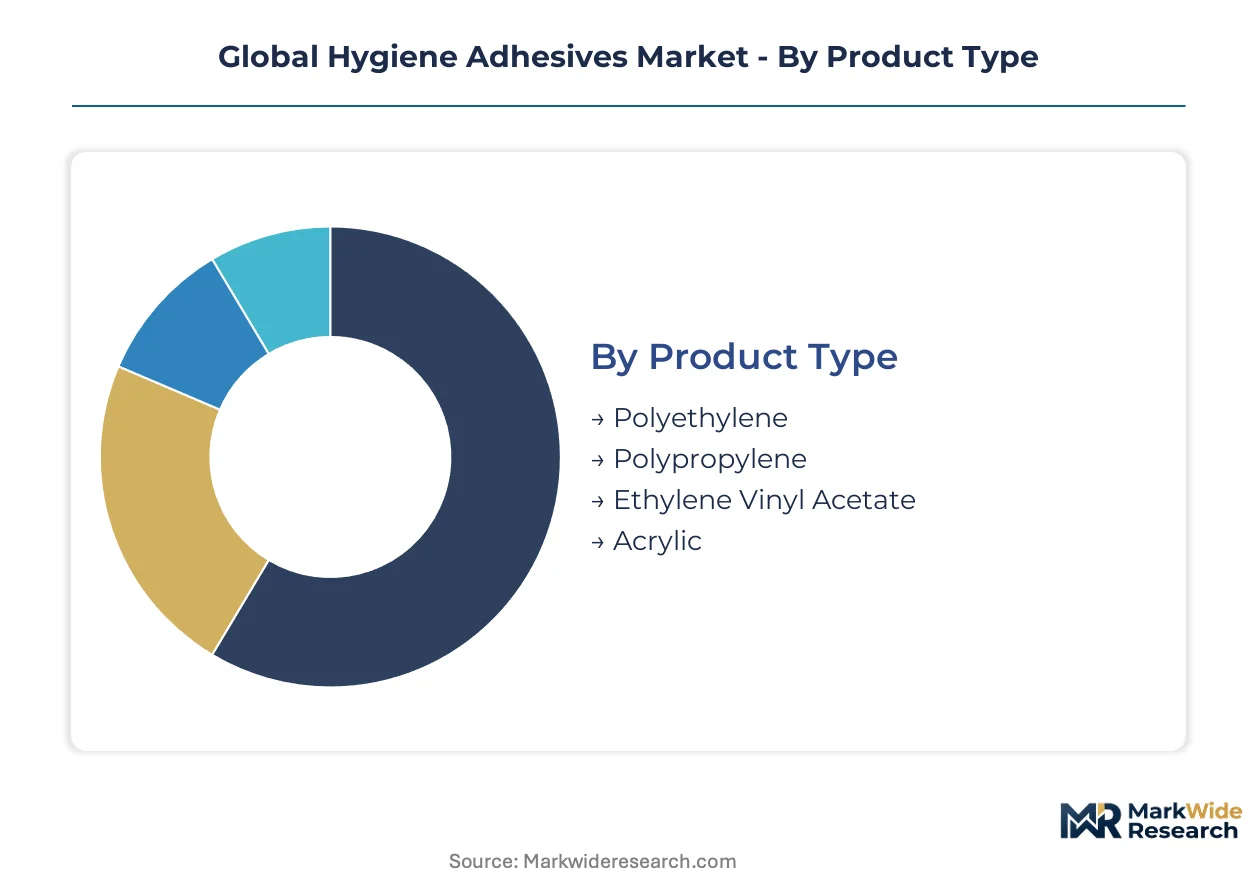
The hygiene adhesives market is categorized by distinct product types, applications, end-users, and technologies, each demanding specific material properties and regulatory compliance. Understanding these segments is crucial for manufacturers to align their R&D and commercial strategies with evolving market needs.
Product Type:
Hygiene adhesive manufacturers are continually evaluating their material portfolios, often driven by the need to upgrade formulations for enhanced performance or to replace older chemistries facing regulatory scrutiny.
- Polyethylene:Polyethylene-based adhesives offer excellent adhesion to nonwovens and films, providing cost-effective solutions for high-volume disposable hygiene products. Demand is concentrating in Asian markets, particularly China, driven by the expanding production of baby diapers and adult incontinence products.
- Acrylic:Acrylic adhesives provide superior skin compatibility and breathability, making them suitable for sensitive medical applications requiring long-term wear. Regulatory pressures in Europe are pushing formulators toward these lower volatile organic compound options for medical tapes and wound care products.
- Polypropylene:Polypropylene adhesives are valued for their strong bond strength and versatility across various substrates in hygiene product manufacturing.
- Ethylene Vinyl Acetate:Ethylene Vinyl Acetate formulations offer good flexibility and adhesion, finding use in a range of disposable absorbent product components.
Volume placements concentrate in Polyethylene; the faster expansion belongs to Acrylic.
Application:
The diverse applications for hygiene adhesives dictate specific performance requirements, ranging from high-speed production lines to delicate skin contact.
- Diapers:This segment represents the largest volume consumption for hygiene adhesives, requiring formulations that ensure secure construction, skin safety, and high-speed application on automated lines. Global demand for baby diapers, particularly in emerging economies like India, drives innovation in cost-effective and high-performance adhesives.
- Wound Care:Adhesives for wound care demand exceptional biocompatibility, gentle removal properties, and secure adhesion to skin, often requiring pressure-sensitive formulations. The stringent ISO 10993 standards and EU MDR regulation influence product development in this high-margin segment.
- Hygiene Products:This category includes feminine hygiene products and adult incontinence products, requiring adhesives that offer comfort, discretion, and reliable performance.
- Medical Tapes:Specialized adhesives for medical tapes must adhere securely to skin while allowing for breathability and minimizing irritation.
While Diapers command significant volume, the Wound Care segment exhibits the steepest expansion trajectory.
End User:
Each end-user segment for hygiene adhesives possesses distinct purchasing criteria, influencing material selection and compliance needs.
- Consumer Goods:Manufacturers of consumer goods, primarily disposable hygiene products, represent the largest end-user segment, prioritizing cost-efficiency and high-volume supply. These companies often seek adhesives compliant with regional standards like the US FDA for skin-contact materials.
- Hospitals:Hospitals procure medical-grade adhesives, often integrated into devices or dressings, with a strong emphasis on biocompatibility and performance in clinical settings. The regulatory landscape, including the EU MDR, heavily influences procurement decisions in this sector.
- Pharmaceutical Companies:These companies utilize specialized adhesives for drug delivery patches, transdermal systems, and other medical devices where material purity and stability are paramount.
- Clinics:Clinics use a variety of medical adhesives for minor procedures, wound dressings, and patient care, often focusing on ease of use and patient comfort.
Consumer Goods manufacturers represent the largest purchasing block, with Pharmaceutical Companies seeking the most specialized formulations.
Technology:
Technological advancements in adhesive formulation continue to drive efficiency and safety, with established methods coexisting with innovative approaches.
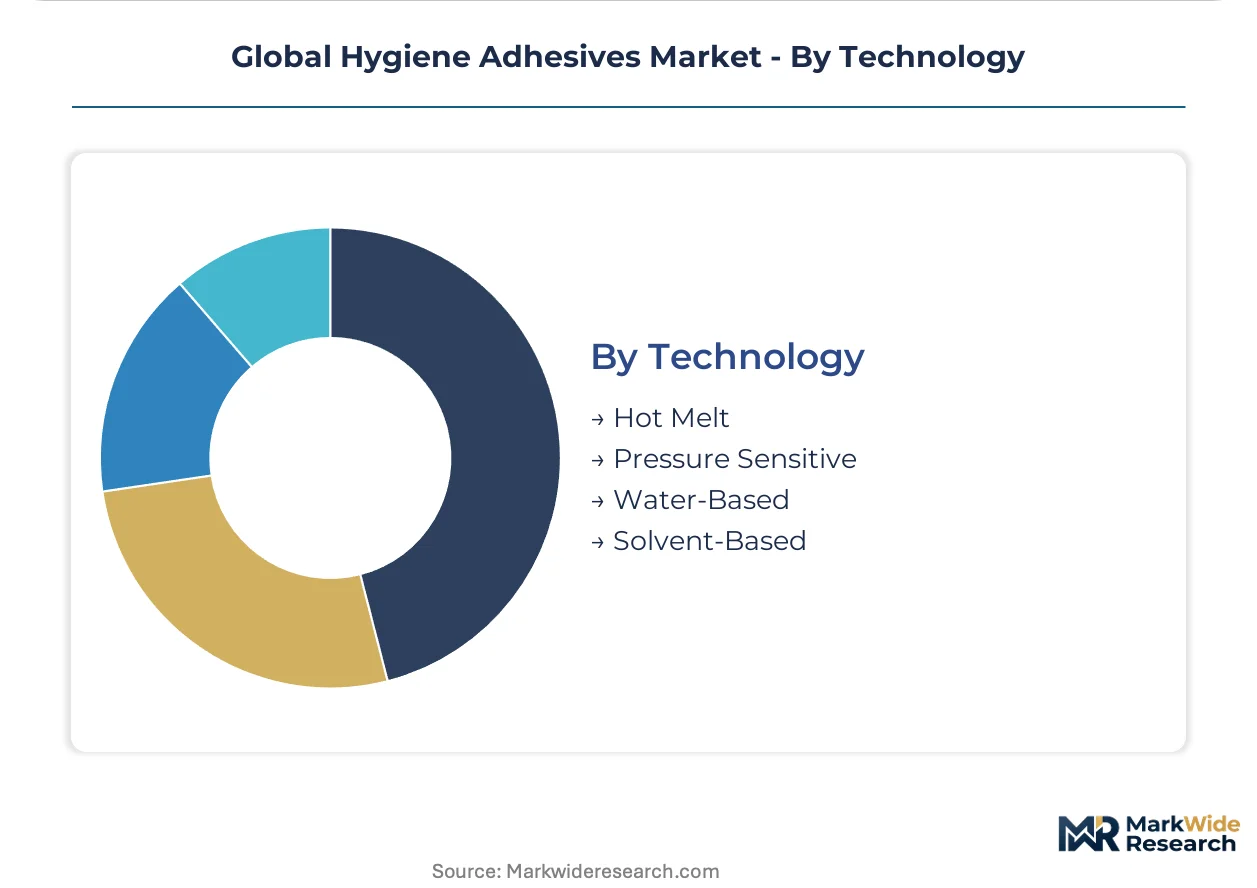
- Hot Melt:Hot melt adhesives dominate the hygiene market due to their rapid setting times, high-speed application capabilities, and solvent-free nature. Continuous innovation focuses on improving bond strength, flexibility, and reducing volatile organic compound emissions to meet global regulatory demands.
- Pressure Sensitive:Pressure sensitive adhesives provide immediate tack and form a bond upon light pressure, making them ideal for wound care, medical tapes, and other applications requiring gentle skin contact. Compliance with biocompatibility standards like ISO 10993 is critical for these formulations.
- Water-Based:Water-based adhesives offer environmental advantages due to lower volatile organic compound content and are gaining traction in specific hygiene applications.
- Solvent-Based:Solvent-based adhesives provide strong bonds but face increasing regulatory scrutiny due to environmental and safety concerns regarding volatile organic compound emissions.
Hot Melt technology dominates application volume, while Pressure Sensitive adhesives capture higher value in specialized niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for hygiene adhesives is concentrating in key global markets, driven by demographic shifts and expanding healthcare infrastructure. China’s expanding healthcare sector and aging population significantly boost consumption. European regulatory mandates also reshape formulation requirements.
China
China's expanding healthcare infrastructure and aging demographic drive substantial demand for hygiene adhesives. The national GB standards influence material selection for medical-grade products. Manufacturing hubs in the Yangtze River Delta continue to increase production capacity for disposable hygiene goods.
Germany
Germany exhibits strong demand for adult incontinence products due to its aging population and high longevity. The EU REACH framework and MDR heavily influence adhesive formulations for biocompatibility. Specialty chemical clusters in North Rhine-Westphalia focus on developing low-VOC solutions for the European market.
India
India’s burgeoning population and increasing adoption of baby diapers create significant volume growth potential for standard-tier hygiene adhesives. The Bureau of Indian Standards (BIS) sets quality benchmarks for consumer goods, including disposable hygiene items. Manufacturing facilities in Maharashtra are expanding to meet the rising domestic demand.
United States
United States demand for hygiene adhesives stems from premium baby diapers and the high-margin wound care segment. The US Food and Drug Administration (FDA) sets strict requirements for skin-contact materials and medical devices. Research and development centers along the Northeast Corridor innovate advanced pressure-sensitive adhesives.
Japan
Japan’s exceptionally aging demographic directly increases the consumer base for adult incontinence products, driving specialized hot melt adhesive consumption. The Pharmaceuticals and Medical Devices Agency (PMDA) and JIS standards guide medical application development. Manufacturers in the Kansai region focus on high-performance, skin-safe formulations.
Global Hygiene Adhesives Market Key Industry Players
European producers anchor one tier; North American specialists hold another, shaping the global hygiene adhesives market structure. The market exhibits a tiered consolidation, with large chemical conglomerates operating alongside specialized formulators. Strategic archetypes include diversified chemical giants offering broad portfolios, focused adhesive specialists targeting niche applications, and regional manufacturers serving local demand. Companies frequently employ capacity expansion and strategic partnerships to maintain competitive positioning and market share.
On the premium-tier vector, Henkel exemplifies a diversified chemical giant leveraging significant R&D capabilities and a global manufacturing footprint. H.B. Fuller, an adhesive specialist, differentiates through its focus on high-performance hot melt adhesives for specialized hygiene applications. Dow, a materials science company, anchors the market through advanced polymer science and material innovation for base resins. These firms collectively represent the strategic depth and technological breadth required to navigate stringent regulatory frameworks and evolving customer demands across hygiene adhesive segments.
| Leading Market Players |
|---|
| 3M |
| Henkel |
| H.B. Fuller |
| Arkema |
| Dow |
| Synthomer |
| Bostik |
| Avery Dennison |
| Sika |
| Others |
Cost & Logistics Intelligence
The distinct performance tiers evident in hygiene adhesives, from commodity-grade polyethylene to specialized acrylics, manifest in varied pricing structures and supply chain configurations.
Pricing Analysis
Volume-driven segments like diapers typically operate on transactional, per-unit pricing, while specialized wound care applications command value-based pricing. Price differentiation often stems from the certification level, such as ISO 10993 compliance, and the degree of customization required for specific skin-contact applications. Cost compression in standard-tier formulations intensifies due to competitive pressures from Asian manufacturers. Consumer goods manufacturers exhibit the highest price sensitivity, whereas pharmaceutical companies prioritize performance and compliance over cost.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly mandated by brand owners to mitigate supply disruptions and ensure regulatory compliance. Geographic supply concentration centers in China for high-volume disposable hygiene goods production, Germany for specialty chemical clusters, and India for baby diaper manufacturing. Raw material dependencies include petrochemical-based resins like polyethylene and polypropylene, along with advanced specialty polymers such as acrylics. Feedstock price volatility tied to global oil and gas markets represents a significant structural risk. Distribution runs through direct supply from adhesive manufacturers to large hygiene product producers, supplemented by specialized distributors for medical-grade formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hygiene adhesives market presents a supply-constrained narrative, with specialized polymer production capacity acting as a bottleneck propping pricing for advanced formulations.
For Market Incumbents: Lock in long-term supply agreements with key raw material suppliers to buffer against petrochemical price volatility. Invest significantly in research and development for next-generation bio-based formulations, addressing the threat posed by emerging sustainable alternatives. Expand global manufacturing footprint in high-growth regions like China and India. Prioritize certification investment for ISO 10993 and regional regulatory frameworks like the EU MDR.
For New Entrants and Emerging Players: A significant price-point gap exists between premium, certified medical-grade adhesives and standard, high-volume formulations, creating opportunities for focused innovation. Target niche medical devices requiring specific adhesion profiles and advanced wound care systems as white-space opportunities. Emerging markets such as Brazil and India represent penetrable segments for standard-tier adhesive formulations. Partner with medical device startups for co-development of specialized adhesive solutions as a go-to-market strategy.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized adhesive formulators with robust intellectual property portfolios and established regulatory compliance expertise. Long-term viability hinges on continuous innovation in biocompatible and sustainable materials over the next decade. Acquisition target archetypes include mid-sized companies possessing strong R&D capabilities in pressure-sensitive or low-VOC formulations. Accelerating M&A activity targeting bio-based adhesive technology developers is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production volume for high-demand regions like China, securing market share. |
| Bio-based Formulation R&D | Addresses regulatory pressures and brand owner sustainability goals for a greener product portfolio. |
| Regulatory Compliance Investment | Ensures market access in stringent regions like the EU for medical and skin-contact applications. |
| Strategic Partnerships | Accelerates market penetration in emerging economies through local manufacturing and distribution alliances. |
| Niche Medical Application Development | Captures higher margins in specialized wound care and device segments with unique performance needs. |
Research Approach
Multi-period observation of regulatory shifts and material science advancements anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with R&D directors, procurement managers at hygiene product manufacturers, regulatory affairs specialists, and medical device engineers. Secondary data sources included EU REACH and MDR documentation, US FDA guidance, ISO standards, trade association reports, and company financial filings. The analysis employed both bottom-up market sizing from production data and top-down validation against revenue reports.
Segment-weighting across product type, application, end-user, and technology dimensions informed the quantitative modeling over the projection horizon. The analytical framework considered polyethylene, acrylics, diapers, wound care, consumer goods, hot melt, and pressure-sensitive adhesives, alongside regional regulatory frameworks. Compound annual growth rates were derived from historical growth patterns and projected adoption rates of advanced formulations. Key forecast inputs included raw material price forecasts and demographic shifts impacting adult incontinence product demand.
Inputs from published regulatory documents and primary interviews were available through the study window; gaps in real-time production capacity data introduce uncertainty bands around volume forecasts. Forecasts reflect assumptions regarding regulatory enforcement and technological development. Deviation in the pace of bio-based material commercialization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Italy Adhesives Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
North America Electronics Adhesives Market
Adhesives & Sealants
Global Methyl Acrylate Market
Adhesives & Sealants
UV Glue Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market