
 Italy Compound Feed Market | 2026-2036
Italy Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Compound Feed Market Foresight
Modular premix-to-complete-feed bundling is expanding buyer choice across Italian livestock operations. Cargill Inc leverages its European supply network to anchor northern distribution corridors. Nutreco N.V. specializes in aquaculture feed formulations for Mediterranean sea bass and sea bream producers. Alltech Inc competes through yeast-based additive technology leadership in gut health segments.
Compound feed denotes industrially manufactured mixtures of cereals, protein meals, fats, oils, and nutritional additives formulated to specified crude protein, energy, and mineral parameters for targeted livestock performance. Italian mills grind and pellet these formulations to achieve standardized digestibility and storage stability for commercial farming operations. Ruminant feed occupies the largest value pool given Italy's dairy herd concentration, while aquaculture feed represents the fastest-expanding category driven by marine finfish production growth in coastal regions. Additive segments command premium positioning as farmers seek productivity gains amid input cost pressures.
EU Green Deal frameworks and EFSA feed additive authorizations shape ingredient approval pathways and sustainability compliance costs for Italian manufacturers. Italy's Ministry of Health enforces national feed hygiene standards transposing EU Regulation 183/2005, with regional veterinary services conducting facility inspections across production sites. BSI certification requirements for quality management add another compliance layer for export-oriented mills. Stakeholders must monitor evolving mycotoxin maximum levels and deforestation-free sourcing mandates to secure supply continuity and market access.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing sourcing timelines for Italian compound feed mills while mandating deforestation-free ingredient verification across supply chains.
Growth Catalysts
- Precision Ruminant Nutrition:Dairy cattle operations in Lombardy and Emilia-Romagna demand protein-optimized formulations that boost milk yield per hectare.
- EFSA Additive Pathways:Accelerated authorizations for yeast-based gut health additives enable Italian mills to differentiate through functional feed claims.
- Po Valley Livestock Integration:Large-scale procurement volumes from vertically coordinated farms in northern Italy concentrate demand for bulk compound feed contracts.
Market Restraints
- Soybean Meal Price Volatility:Italian mills remain exposed to Brazilian and Argentine export fluctuations, compressing margin buffers on protein-intensive formulations.
- EU Deforestation Regulation:Mandatory geolocation traceability for imported palm oil and soy increases compliance overhead for coastal processing facilities.
- Phosphate Rock Supply Concentration:Dependence on Moroccan and Chinese mineral sources creates input vulnerability for mineral premix production.
Strategic Opportunities
- Sicilian Aquaculture Expansion:Sea bass and sea bream cage farming along the Mediterranean coast demands specialized marine protein formulations with limited domestic supply.
- Regional Circular Feed Mandates:Italy's National Recovery and Resilience Plan incentivizes insect protein and food-waste-to-feed conversion technologies.
- Digital Feed Formulation Platforms:Cloud-based least-cost optimization tools enable mid-tier mills to compete with multinational pricing precision.
Industry Challenges
- Mycotoxin Testing Capacity:Regional veterinary laboratories face backlogs on aflatoxin and DON screening, delaying batch releases during harvest seasons.
- BSI Certification Timelines:Quality management audits for export-oriented mills stretch 8-14 months, freezing facility upgrades until accreditation completes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Compound Feed Market |
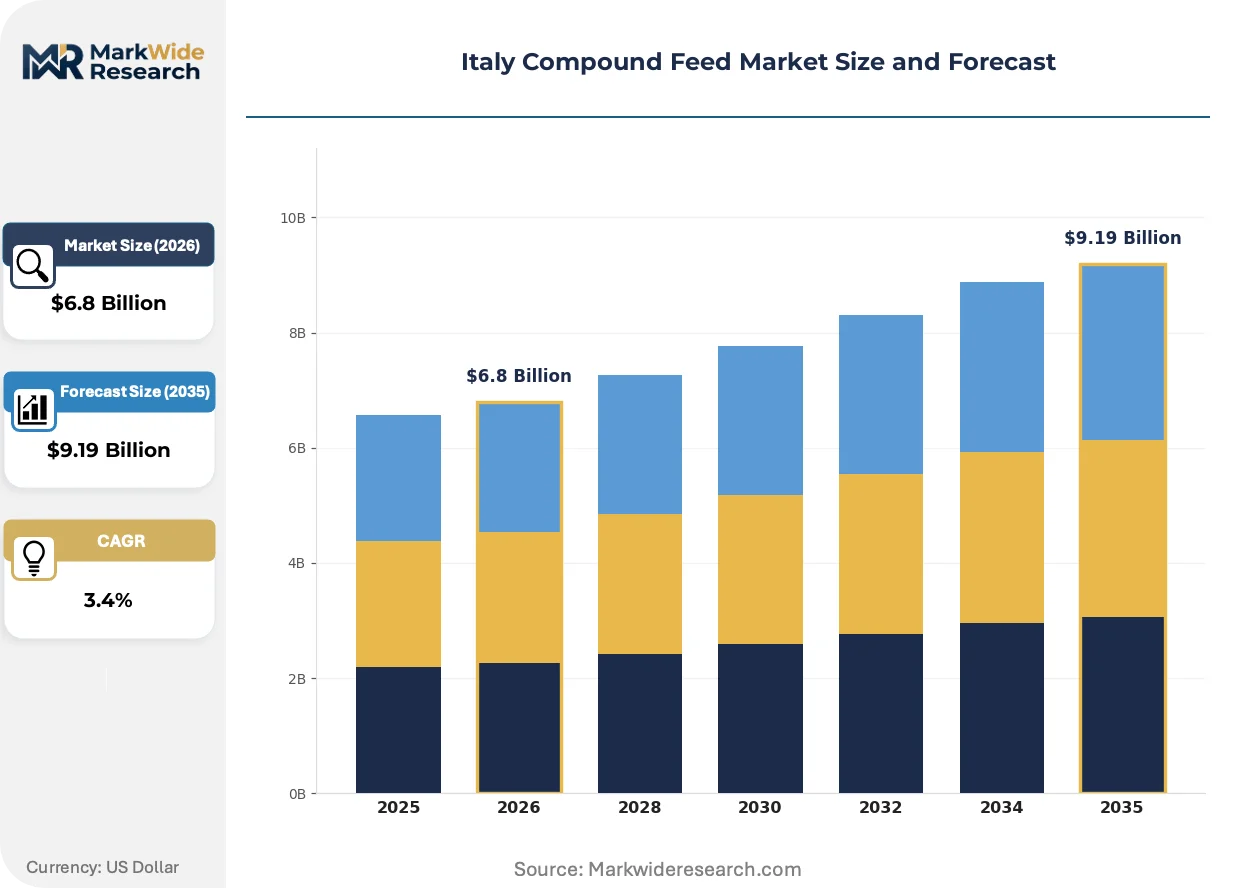
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.19 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Ruminant Feed, Aquaculture Feed, Swine Feed Ingredient Type: Cereal Grains, Protein Meals, Additives, Fats & Oils End User: Farmers, Livestock Suppliers, Feed Manufacturers, Agricultural Cooperatives Distribution Channel: Online Retail, Direct Sales, Distributors, Farm Supply Stores |
| Companies Covered | Archer Daniels Midland Company, Alltech Inc, Cargill Inc, Land O' Lakes Inc, Nutreco N.V., DeKalb Feeds, Heiskell & Co, Kent Feeds, Land O Lakes Purina, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Compound Feed Market Shifts & Advancements
Italian compound feed manufacturing is pivoting toward precision-formulation platforms that integrate real-time ingredient analytics with automated batch control systems.
Near-infrared spectroscopy coupled with machine learning algorithms is electrifying quality assurance workflows at northern Italian mills. Large dairy cooperatives in Lombardy deploy these systems for instant crude protein verification. The technology is compressing lab turnaround from days to minutes while reducing formulation variance penalties.
EU Green Deal sustainability reporting under CSRD now mandates Scope 3 emissions disclosure for feed ingredient sourcing. Italian manufacturers must document embedded carbon in imported soy and palm derivatives. Mills serving export markets are prioritizing certified deforestation-free supply chains to maintain EU market access.
Consolidated procurement through farmer cooperatives is displacing fragmented spot purchasing across the Po Valley. Dairy and swine operations in Emilia-Romagna now contract annual volumes through integrated supply agreements. This concentration is most visible in Parma and Modena provinces where processor-owned feed mills anchor vertical coordination.
Italy Compound Feed Market Segmentation
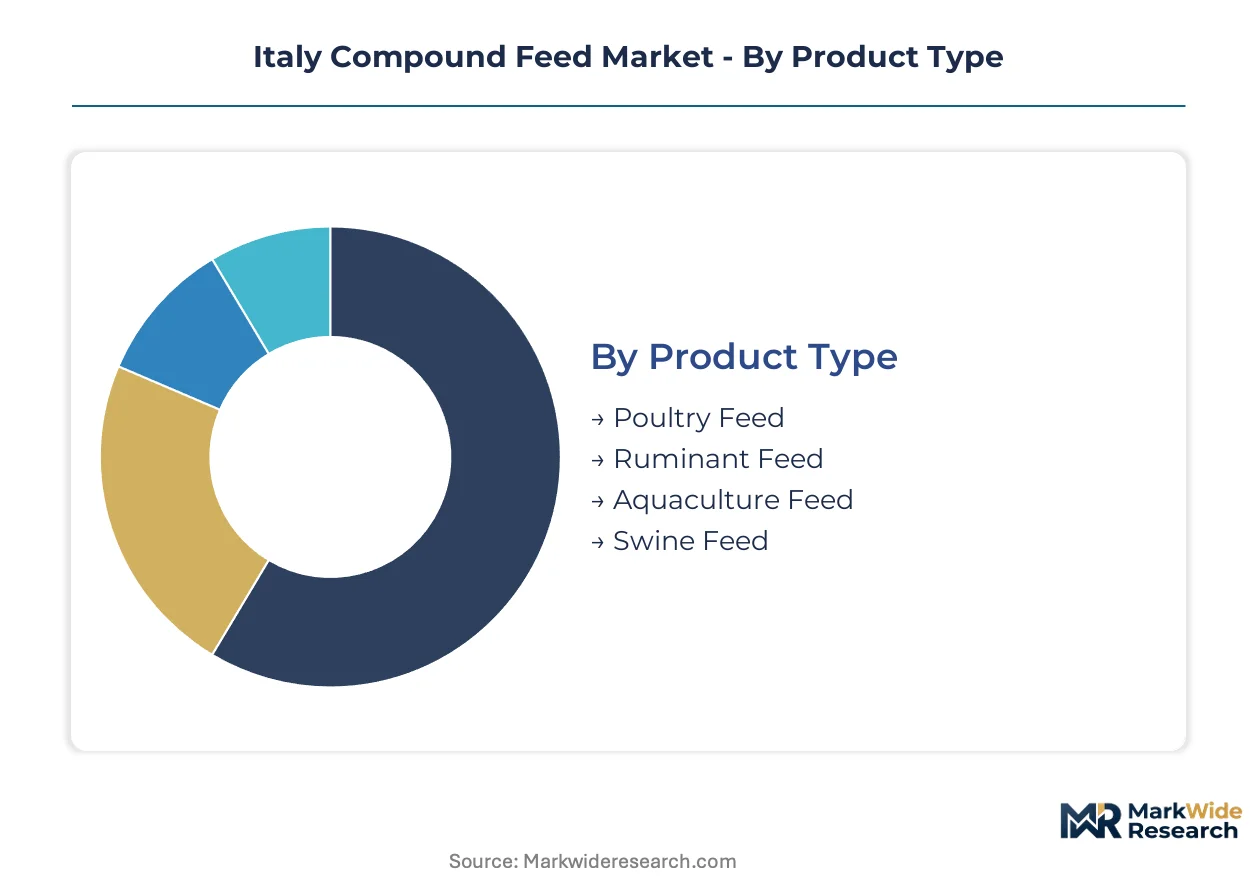
Italian compound feed segmentation reflects the Po Valley's livestock concentration and the Mediterranean coastline's aquaculture expansion. Distinct formulation requirements across species and procurement patterns among cooperatives versus independent farms create tiered demand pools.
Product Type:
Ruminant feed commands the largest volume base, while aquaculture formulations capture the steepest premium margins.
- Ruminant Feed:Precision-formulated mixtures of maize silage, soybean meal, and mineral premixes calibrated for dairy cattle milk yield optimization. Demand concentrates in Lombardy and Emilia-Romagna, where large-scale dairy cooperatives procure through annual bulk contracts tied to milk production quotas.
- Aquaculture Feed:High-protein extruded pellets incorporating fish meal and marine oils formulated for sea bass and sea bream growth rates. Sicilian cage farming operations along the Mediterranean coast drive procurement, though domestic supply remains limited and import-dependent.
- Poultry Feed:Energy-dense formulations with balanced amino acid profiles for broiler and layer operations in Veneto and Piedmont.
- Swine Feed:Cereal-soybean blends with lysine supplementation serving integrated pork production in Emilia-Romagna.
Mature deployment sits with ruminant feed. Newer deployment is concentrated in aquaculture feed.
Ingredient Type:
Commodity inputs dominate tonnage, while functional additives command disproportionate margin contribution.
- Cereal Grains:Maize, wheat, and barley constitute the caloric foundation of Italian formulations, typically comprising 50-60% of finished feed mass. Domestic cultivation in the Po Valley supplies approximately half of milling requirements, with the balance imported from France and Ukraine.
- Additives:Yeast derivatives, enzymes, and mycotoxin binders deliver functional claims around gut health and feed conversion efficiency. Northern Italian mills leverage EFSA-approved additive portfolios to differentiate formulations for premium dairy contracts.
- Protein Meals:Soybean meal from South American origins provides essential amino acids, though EU Deforestation Regulation traceability requirements now constrain sourcing flexibility.
- Fats & Oils:Palm oil and tallow supply energy density, with sustainability certification increasingly mandatory for export-oriented production.
Ingredient sourcing maturity clusters in cereal grains. Innovation investment is concentrating in additives.
End User:
Procurement scale separates integrated cooperatives from fragmented independent operations.
- Agricultural Cooperatives:Vertically coordinated dairy and swine associations in Parma and Modena provinces negotiate annual compound feed volumes through processor-owned mills. These entities capture economies of scale and quality consistency unavailable to smaller buyers.
- Feed Manufacturers:Independent mills serving mid-tier livestock operations formulate to customer specifications, competing on least-cost optimization and local delivery reliability.
- Farmers:Independent dairy and poultry operators purchase through spot markets or short-term contracts, price-sensitive and formulation-flexible.
- Livestock Suppliers:Breeding stock enterprises require specialized starter and grower formulations for genetic performance.
Procurement consolidation is advancing fastest among agricultural cooperatives. Fragmented purchasing persists with independent farmers.
Distribution Channel:
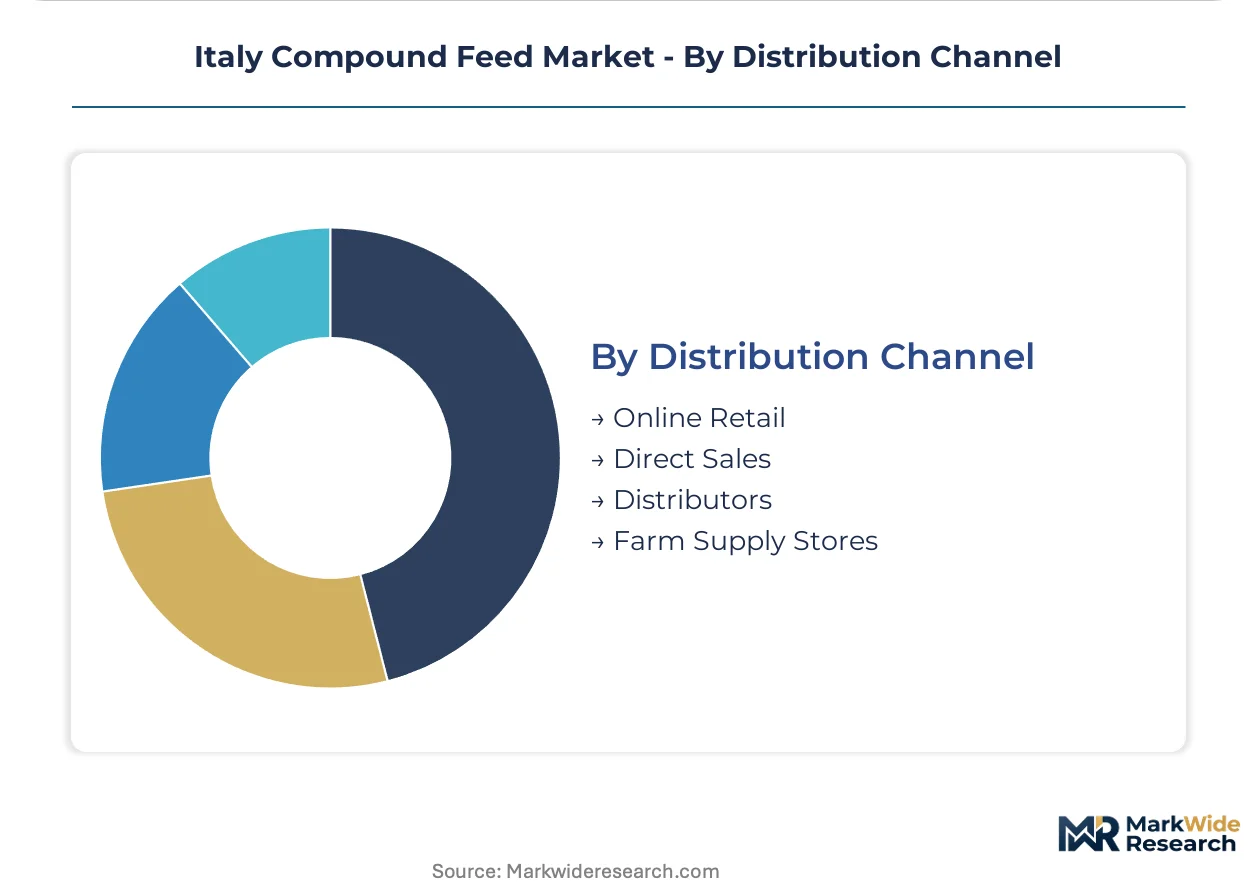
Physical infrastructure still dominates tonnage movement, though digital platforms are penetrating smaller accounts.
- Direct Sales:Major mills contract directly with large cooperatives and integrated processors, bypassing intermediaries to capture margin and secure volume commitments. Cargill and Nutreco leverage European supply networks for direct delivery across northern Italy.
- Distributors:Regional wholesalers maintain inventory positions and technical service capabilities for mid-tier livestock operations in secondary provinces.
- Farm Supply Stores:Local retailers serve smallholder poultry and hobby farming segments with bagged feed and nutritional supplements.
- Online Retail:E-commerce platforms are emerging for specialty additives and small-batch formulations, though bulk compound feed remains logistically constrained.
Direct sales anchor volume flows. Digital channels are expanding most quickly in specialty additive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Italian Zona Economica Speciale (ZES) framework and regional industrial incentives concentrate compound feed manufacturing capacity across northern agricultural corridors. Sub-regional specialization reflects livestock density gradients and coastal aquaculture development.
Lombardy
Dairy cooperatives in the Po Valley drive bulk procurement of protein-optimized ruminant formulations. EFSA feed additive authorizations enable regional mills to incorporate yeast-based gut health enhancers into premium dairy contracts. Milan and Brescia provinces host vertically integrated feed mills serving Parmigiano-Reggiano supply chains.
Emilia-Romagna
Swine and dairy operations in Parma and Modena provinces negotiate annual volume contracts through processor-owned facilities. Italy's Ministry of Health enforces national feed hygiene standards with regional veterinary inspections across production sites. Bologna anchors distribution networks connecting Po Valley livestock clusters with Adriatic port terminals.
Veneto
Broiler and layer operations in Verona and Vicenza provinces sustain demand for energy-dense poultry formulations. EU Green Deal Farm to Fork traceability requirements constrain sourcing flexibility for imported soybean meal. Padua hosts research partnerships between regional mills and veterinary institutes on mycotoxin mitigation protocols.
Sicily
Sea bass and sea bream cage farming along the Mediterranean coast generates procurement of high-protein extruded aquafeeds. EU Deforestation Regulation geolocation mandates increase compliance overhead for palm oil and fish meal imports. Mazara del Vallo and Trapani concentrate marine finfish production with limited domestic feed supply.
Piedmont
Mixed livestock operations in Turin and Cuneo provinces balance dairy, beef, and poultry feed requirements. BSI certification timelines for quality management stretch facility upgrade cycles across export-oriented mills. Alessandria province maintains cereal grain processing infrastructure supplying regional formulation facilities.
Italy Compound Feed Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Italy's compound feed value chain. The market exhibits tiered concentration with multinational processors anchoring northern distribution corridors while regional mills serve mid-tier accounts. Three archetypes dominate: agricultural trading houses with European supply networks, aquaculture-focused nutrition specialists, and yeast-technology additive innovators. Consolidation proceeds through cooperative-processor vertical coordination and digital formulation platform licensing.
Among diversified agricultural conglomerates, Cargill Inc and Archer Daniels Midland Company occupy positions anchored by continental supply infrastructure. Nutreco N.V. exemplifies the aquaculture specialization archetype with Mediterranean marine feed expertise. Alltech Inc represents yeast-based additive technology leadership in functional nutrition segments. These three entities collectively illustrate the competitive vectors shaping procurement relationships with Italian livestock cooperatives and independent farming operations.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Alltech Inc |
| Cargill Inc |
| Land O' Lakes Inc |
| Nutreco N.V. |
| DeKalb Feeds |
| Heiskell & Co |
| Kent Feeds |
| Land O Lakes Purina |
| Others |
Supply & Pricing Matrix
The EU Green Deal's deforestation-free sourcing mandate gates qualified supply access and premium-tier pricing eligibility for Italian compound feed mills, forcing buyers to absorb certification premiums or forfeit export market participation.
Pricing Analysis
Margin tightening in standard-grade formulations reflects Brazilian soybean meal price volatility and EU Deforestation Regulation compliance overhead. Three-tier pricing structure across premium EFSA-certified, standard commercial, and economy spot-market levels separates dairy cooperatives from independent farmers. Premium-tier buyers in Lombardy show lowest price sensitivity due to milk quota economics, while spot-market independents in secondary provinces face acute cost-down pressure.
Supply Chain Analysis
Regional distribution centers in Milan and Bologna anchor hub-and-spoke patterns connecting Po Valley livestock clusters with Adriatic port terminals. Raw material sourcing draws from Brazilian soybean crushing, Moroccan phosphate rock, and Ukrainian maize corridors. Single-source vulnerability concentrates in South American protein meal origins. Distribution runs through processor-owned mill networks for cooperative volumes, with independent distributors serving fragmented farm accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian compound feed manufacturing is consolidating around sustainability-compliant supply chains, with EU Deforestation Regulation enforcement forcing subscale mills toward acquisition or exit.
For Market Incumbents: To counter margin compression from traceability compliance costs, anchor deforestation-free supply agreements with Brazilian and Argentine crushing facilities, and deepen backward integration into Po Valley cereal processing to capture captive grain supply. For New Entrants and Emerging Players: The price-point gap between premium-certified aquafeed and economy ruminant formulations offers entry space. Target Sicilian sea bass and sea bream cage operations with specialized marine protein formulations, leveraging digital least-cost optimization platforms to match multinational pricing precision without legacy infrastructure overhead. For Investors and Strategic Acquirers: Accelerated cooperative-processor vertical coordination in Parma and Modena provinces is the leading indicator that mid-tier independent mill assets will trade at distressed multiples. Position for five-to-ten-year horizon consolidation by acquiring BSI-certified facilities with established EFSA additive portfolios, watching mycotoxin testing laboratory backlogs as the signal for regulatory enforcement intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Deforestation-Free Supply Certification | EU Green Deal compliance secures market access for export-oriented Italian mills. |
| Precision Formulation Platform Licensing | Cloud-based least-cost tools enable mid-tier mills to match Cargill pricing precision. |
| Insect Protein Facility Investment | Italy's National Recovery and Resilience Plan subsidizes circular feed conversion technologies. |
| Aquaculture Feed Capacity Expansion | Sicilian sea bass production growth outpaces domestic marine formulation supply. |
| Vertical Coordination with Dairy Cooperatives | Processor-owned mill networks in Emilia-Romagna lock in annual volume commitments. |
Research Methodology
Trade flow databases, EFSA additive authorization registries, and EU customs declarations formed the secondary backbone, cross-referenced with primary interviews involving feed mill procurement directors, dairy cooperative supply managers, veterinary laboratory heads, and port logistics operators. Bottom-up volume estimates from regional production capacity and top-down demand validation from livestock census data were triangulated to constrain forecast variance.
Bottom-up modeling aggregated facility-level production capacity across Lombardy, Emilia-Romagna, Veneto, and Sicily, while top-down analysis calibrated against EU agricultural output statistics across the projection horizon. Segmentation dimensions included livestock species, ingredient functional category, procurement scale tier, and sub-regional distribution corridor. CAGRs were derived from elasticity-adjusted demand projections incorporating milk yield optimization trends and marine finfish production growth curves.
Inputs from veterinary inspection records and cooperative procurement disclosures were available through the study window; gaps in real-time mycotoxin testing throughput data introduce uncertainty bands around harvest-season supply estimates. Forecasts reflect documented assumptions on regulatory enforcement timelines and commodity price trajectory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
US Greenhouse Horticulture Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
American Ginseng Market
Agriculture and Agri Products
Alfalfa Pellets Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Elaeis Guineensis Kernel Oil Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
Marine Seaweed Market