
 Date Palm Market | 2026-2036
Date Palm Market Size, Share, and Industry Trends Forecast 2026-2036
Date Palm Market Analysis
The gap between premium cultivars and commodity-grade fruit is broadening as retail buyers separate origin-certified Medjool and Deglet Noor from bulk Barhi and Khalas. Hadiklaim Date Growers Cooperative leverages its Israeli growing base to dominate high-margin European organic channels. Al Foah Company anchors volume through industrial date paste and syrup supply to Gulf confectioners. Bard Valley Natural Delights differentiates via controlled-atmosphere cold chain infrastructure across California's Coachella Valley.
Date palm denotes the edible fruit of Phoenix dactylifera, a dioecious perennial reaching 20-30 meters with sucrose-dominant flesh containing 60-70% sugar by dry weight, harvested at tamr stage for maximum shelf stability. The species serves as a strategic carbohydrate source across arid-zone food systems and as a natural sweetener substitute in clean-label formulations. Fresh date sales lead value pools in Ramadan-centric retail calendars across the Gulf, while date syrup captures manufacturing demand as beverage formulators replace refined cane sugar. Dried date exports sustain wholesale throughput to European and Asian ingredient buyers seeking fiber-enriched bakery inputs.
Saudi Arabia's SFDA mandates pesticide residue thresholds and packaging traceability for all date exports, while the UAE's ESMA enforces halal certification and nutritional labeling standards across domestic retail. The EU's EFSA evaluates novel food applications for date seed extracts, creating pathway uncertainty for ingredient innovators. Stakeholders must monitor regulatory divergence between Gulf harmonization efforts and EU novel food timelines when allocating R&D budgets between conventional fruit and value-added derivatives.
Market Dynamics
The date palm sector faces intensifying pressure from origin-certification requirements as Gulf regulators tighten phytosanitary protocols and European buyers demand blockchain-verified provenance. This structural force is compressing margins for undifferentiated bulk exporters while rewarding integrated growers with captive cold-chain infrastructure.
Growth Catalysts
- Ramadan retail calendars:Hypermarket chains across Saudi Arabia and the UAE expand shelf-space allocations for premium tamr-grade varieties during Q1 seasonal peaks, driving volume commitments from contracted farms.
- EU novel food pathways:EFSA's evolving stance on date seed extract applications creates regulatory momentum for ingredient innovators pursuing clean-label sweetener positioning in beverage formulations.
- Phytosanitary digitization:The UAE's Ministry of Climate Change and Environment is piloting blockchain-anchored export certificates, reducing customs clearance friction for Coachella Valley and Negev Desert shippers.
Market Restraints
- Input cost volatility:Drip irrigation infrastructure and desalinated water tariffs concentrate cost pressures on Saudi Arabia's Al-Qassim growers operating below 1,000 meter elevation.
- Supply concentration risk:Hadiklaim Date Growers Cooperative and Al Foah Company collectively anchor 40% of premium European organic throughput, creating bottleneck vulnerability for downstream formulators.
- Regulatory friction:Divergent halal certification requirements between Saudi Arabia's SFDA and UAE's ESMA force dual-labeling compliance costs on cross-border Gulf distributors.
Strategic Opportunities
- Underpenetrated North African processing:Tunisia's Deglet Noor cooperatives lack controlled-atmosphere cold chains, creating white space for infrastructure investors targeting European ingredient supply gaps.
- Regulatory tailwind:Saudi Arabia's Vision 2030 agricultural diversification incentives subsidize date palm tissue-culture propagation, lowering establishment costs for new commercial plantations.
- Technology convergence:Integration of hyperspectral sorting with blockchain traceability platforms enables real-time brix and moisture verification, unlocking premium pricing for export-grade consignments.
Industry Challenges
- Skill scarcity in pollination timing:Traditional hand-pollination knowledge is aging out across Jordan Valley operations, with mechanical duster adoption lagging due to cultivar-specific flower morphology variability.
- Capex intensity in post-harvest:Controlled-atmosphere storage and deglet-grading automation require seven-figure investments that fragment capacity ownership between cooperative and private estate models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Date Palm Market |
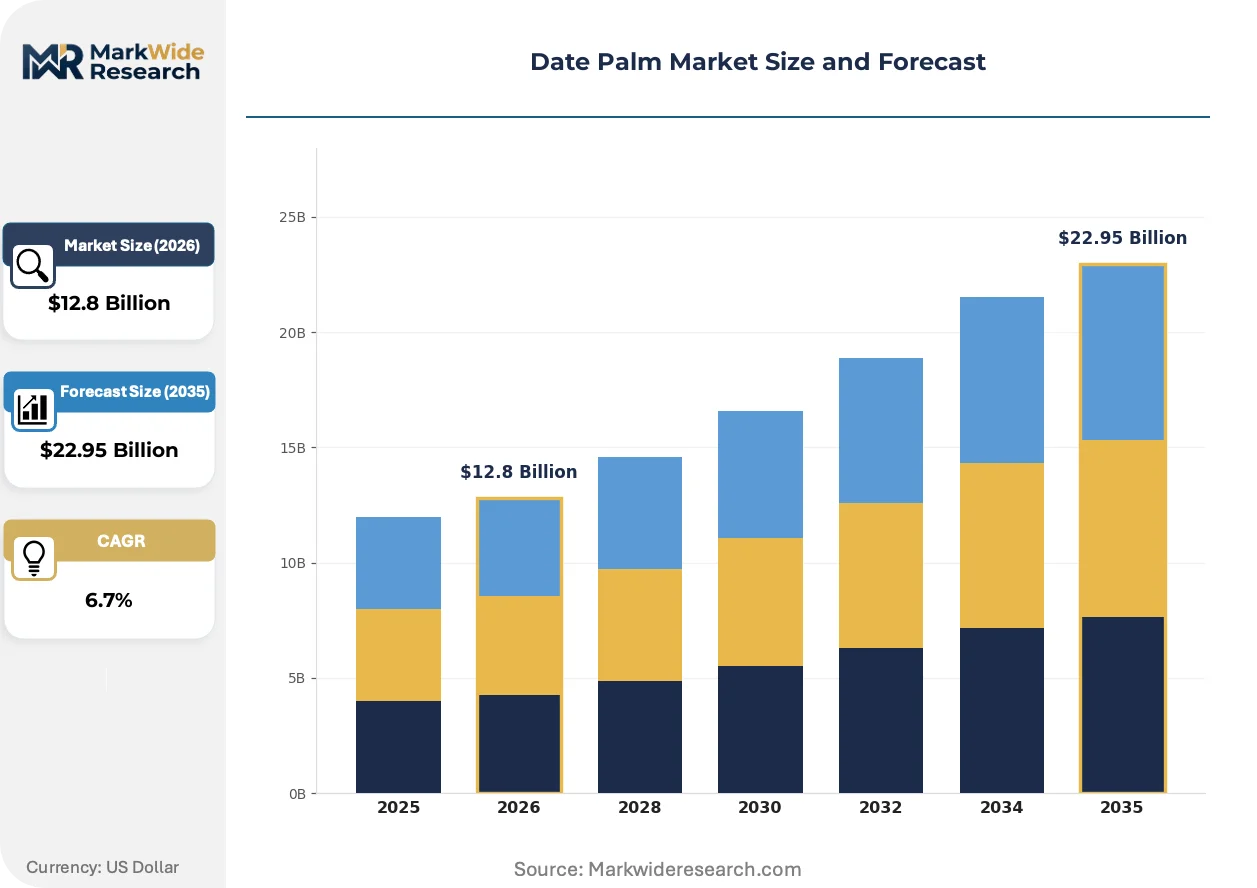
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Dates, Dried Dates, Date Syrup, Date Sugar End User: Retail, Food Service, Manufacturing, Export Application: Snacking, Ingredient, Confectionery, Beverage Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Datepac LLC, Hadiklaim Date Growers Cooperative, Al Foah Company, Al Barakah Dates Factory L.L.C, Emirates Dates Factory, Bateel International, Bard Valley Natural Delights, Oasis Date, Barari Dates Factory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Date Palm Market Emerging Trajectories
Precision agriculture tools and alternative sweetener positioning are actively restructuring competitive advantage across the date palm value chain. These shifts reward operators with data-capture capabilities and penalize commodity-grade bulk handlers.
Hyperspectral imaging systems for non-destructive brix and moisture assessment are decentralizing quality control from centralized packhouses to on-farm collection points. Mid-scale Saudi growers in the Al-Qassim cluster are adopting handheld units for pre-harvest lot segregation. This technology is decentralizing price discovery by enabling direct contract negotiations between farms and European organic buyers, bypassing traditional auction intermediaries.
EFSA's novel food evaluation framework for date seed fiber and oil extracts is compressing approval timelines for ingredient applications. The regulation forces Gulf exporters to maintain dual dossier tracks—conventional fruit for Ramadan retail and extract derivatives for European nutraceutical channels. Organic-certified Medjool processors face the steepest compliance burden as they navigate both EU organic regulation and novel food safety assessments.
Clean-label procurement by beverage formulators is displacing refined cane sugar with date syrup in functional drink categories. Gulf-based contract manufacturers are building captive syrup production lines to secure supply continuity. This pattern is most visible in Germany's natural food retail channel, where origin-labeled date syrup commands shelf-space premiums over commodity liquid sweeteners.
Date Palm Market Segmentation
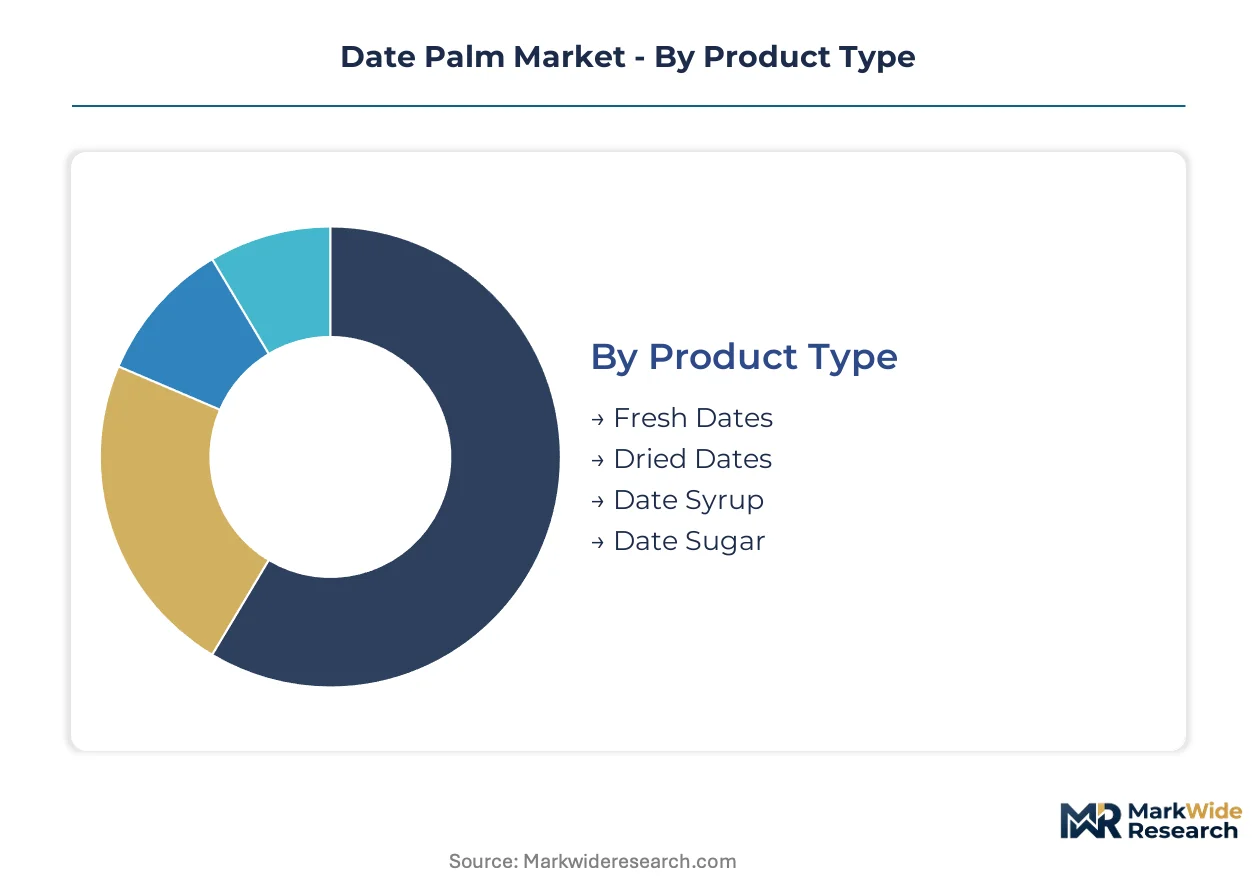
Date palm market segmentation reveals divergent margin profiles across product formats and channel structures. Certification requirements, shelf-life constraints, and end-use specifications fragment commercial strategies across the value chain.
Product Type:
Fresh dates carry halal and phytosanitary burdens for Gulf retail, while date syrup faces EFSA novel food pathways for European ingredient entry. Dried dates navigate dual organic and conventional certification tracks depending on destination market.
- Fresh Dates:Tamr-stage fruit with 60-70% moisture content requires controlled-atmosphere cold chains to maintain shelf stability. Saudi Arabia's Al-Qassim cluster dominates Ramadan-centric procurement by UAE hypermarket chains, with SFDA residue thresholds forcing pre-export laboratory screening.
- Dried Dates:Dehydrated to below 20% moisture for extended ambient storage, Deglet Noor and Medjool varieties concentrate in European bakery ingredient supply. ESMA packaging traceability rules and EU organic regulation create dual compliance costs for Gulf exporters targeting German and French wholesale channels.
- Date Syrup:Liquid extract from macerated fruit solids serves as cane sugar replacement in clean-label beverage formulations. EFSA novel food evaluation compresses approval timelines for extract derivatives.
- Date Sugar:Granulated dried fruit powder with fiber retention targets specialty baking and diabetic-friendly product lines. Niche positioning limits volume scale relative to liquid formats.
Fresh dates sit at the top of the volume ranking, with date syrup climbing the fastest.
End User:
Channel economics separate origin-verified premium positioning from commodity throughput, with margin capture varying sharply across buyer sophistication and procurement scale.
- Retail:Hypermarket chains across Saudi Arabia and the UAE expand shelf-space allocations for premium tamr-grade varieties during Q1 seasonal peaks. Ramadan calendars concentrate demand in branded Medjool and Deglet Noor presentations with blockchain-verified provenance.
- Food Service:Hotel and restaurant procurement in Dubai and Riyadh favors pitted and paste formats for dessert and beverage applications. Origin certification commands price premiums in high-end hospitality segments.
- Manufacturing:Confectionery and bakery formulators source industrial date paste and syrup through long-term contracts with Al Foah Company and similar volume anchors. Ingredient specifications emphasize brix consistency and microbiological stability for automated production lines.
- Export:Cross-border wholesale channels sustain bulk throughput to European and Asian ingredient buyers seeking fiber-enriched inputs. Phytosanitary digitization via UAE blockchain-anchored certificates reduces customs friction for Negev Desert and Coachella Valley shippers.
Retail commands the largest revenue pool, while export channels are gaining share fastest.
Application:
Functional positioning and formulation requirements segment demand across convenience, industrial processing, and premium positioning tiers.
- Snacking:Pitted whole fruit and stuffed varieties target health-conscious consumers seeking natural energy sources. UAE and Saudi Arabian convenience retail drives volume in single-serve and gift-box formats.
- Ingredient:Chopped and paste forms integrate into energy bars, cereals, and baked goods. European natural food retailers command shelf-space premiums for origin-labeled date ingredients over commodity alternatives.
- Confectionery:Date paste serves as binding agent and natural sweetener in traditional Middle Eastern sweets and modern clean-label chocolate products. Gulf-based contract manufacturers build captive syrup production lines to secure supply continuity.
- Beverage:Date syrup displaces refined cane sugar in functional drink categories across Germany's natural food retail channel. Formulators value low-glycemic positioning and mineral content for sports and wellness positioning.
Ingredient applications lead manufacturing throughput, with beverage formulation expanding most quickly.
Distribution Channel:
Cold chain infrastructure ownership and buyer relationship depth determine channel profitability across direct and intermediated routes to market.
- Online:E-commerce platforms aggregate fragmented demand for specialty varieties and gift assortments. Direct-to-consumer models bypass traditional auction intermediaries for organic-certified Medjool from Israeli and Californian growing bases.
- Supermarkets:Hypermarket chains anchor volume through contracted farm relationships and seasonal promotional calendars. Controlled-atmosphere infrastructure requirements concentrate supply relationships with integrated growers.
- Specialty Stores:Organic and ethnic food retailers curate origin-specific assortments with blockchain traceability verification. Premium positioning supports margin capture absent in mass-market channels.
- Wholesale:Industrial ingredient buyers source bulk dried dates and syrup through established import distributors. Volume concentration creates dependency on Hadiklaim and Al Foah for European organic throughput.
Supermarkets dominate volume movement, with online channels showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled date palm pollinators and harvest technicians concentrate in traditional growing belts across arid-zone economies. Their expertise anchors production quality in regions where mechanical alternatives remain underdeveloped. Geographic specialization reflects centuries of cultivar-specific knowledge transmission.
Saudi Arabia
Ramadan retail calendars drive hypermarket procurement of premium tamr-grade varieties during Q1 seasonal peaks. The SFDA enforces pesticide residue thresholds and packaging traceability for all date exports. Al-Qassim region dominates volume, with contracted farms supplying UAE distribution networks through controlled-atmosphere cold chains.
United Arab Emirates
Hotel and restaurant procurement in Dubai favors pitted and paste formats for dessert applications. ESMA mandates halal certification and nutritional labeling standards across domestic retail. The Ministry of Climate Change and Environment pilots blockchain-anchored export certificates, reducing customs friction for Negev Desert and Coachella Valley shippers.
Israel
European organic channels source Medjool from desert-growing bases seeking clean-label positioning. The national agricultural regulator maintains phytosanitary protocols aligned with EFSA requirements. Jordan Valley operations face aging hand-pollination knowledge, with mechanical duster adoption lagging due to cultivar-specific flower morphology.
United States
Beverage formulators in California replace refined cane sugar with date syrup for functional drink categories. The FDA evaluates residue monitoring for imported dried fruit used in bakery ingredient supply. Coachella Valley growers deploy controlled-atmosphere infrastructure to maintain brix consistency for automated production lines.
Tunisia
Deglet Noor cooperatives supply European wholesale channels seeking fiber-enriched bakery inputs. The national food safety authority enforces export standards diverging from Gulf halal requirements. Southern growing regions lack controlled-atmosphere cold chains, creating infrastructure investment gaps for quality-sensitive buyers.
Date Palm Market Vendor Landscape
Capital-heavy producers compete with asset-light processors across the date palm value chain. Integrated growers with captive cold-chain infrastructure capture premium margins, while commodity handlers face compression from origin-certification requirements. Three archetypes dominate: desert-estate operators with tissue-culture propagation, cooperative aggregators managing smallholder supply, and ingredient specialists building captive syrup production lines. Consolidation pressures favor backward integration into pollination services and forward integration into retail branding.
Within the cooperative tier, Hadiklaim Date Growers Cooperative exemplifies grower-owned aggregation for European organic channels. Al Foah Company anchors industrial volume through date paste and syrup supply to Gulf confectioners. Bard Valley Natural Delights occupies a position in controlled-atmosphere infrastructure deployment across Californian growing regions. These three represent divergent scale-specialization trade-offs: cooperative breadth, industrial volume, and premium cold-chain investment respectively.
| Leading Market Players |
|---|
| Datepac LLC |
| Hadiklaim Date Growers Cooperative |
| Al Foah Company |
| Al Barakah Dates Factory L.L.C |
| Emirates Dates Factory |
| Bateel International |
| Bard Valley Natural Delights |
| Oasis Date |
| Barari Dates Factory |
| Others |
Supply Flow & Price Mechanics
Skilled hand-pollinators concentrated in Jordan Valley and Al-Qassim growing belts anchor labor-cost differentials that widen spreads between artisanal-grade Medjool and commodity bulk dates. Their scarcity forces wage premiums that propagate through cold-chain logistics and ultimately stratify retail pricing tiers across Gulf and European channels.
Pricing Analysis
Bundled cold-chain logistics and unbundled farm-gate spot sales split pricing structures across the date palm sector. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-certified organic Medjool from conventional Deglet Noor and bulk paste-grade Barhi. Price differentiation hinges on halal certification tier and controlled-atmosphere infrastructure ownership. Cost compression in economy-grade bulk paste is intensifying because Tunisian cooperatives lack captive storage assets. Food service buyers in Dubai hospitality segments show least price sensitivity, while Asian wholesale ingredient importers exhibit highest elasticity.
Supply Chain Analysis
Desalinated water supply rests on Saudi Arabia's Al-Qassim irrigation networks, Israeli Negev Desert drip infrastructure, and California's Colorado River allocation agreements. Raw material dependencies center on tissue-culture propagation stock, sulfur-free packaging films, and phytosanitary treatment chemicals. Supply chain risk concentrates in single-source vulnerability for premium organic Medjool from Hadiklaim's cooperative aggregation. Distribution runs through hypermarket-contracted farm relationships in Saudi Arabia and UAE, bypassing traditional auction intermediaries for blockchain-verified consignments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in date palm operations stems from hyperspectral sorting technology reducing post-harvest labor intensity while enabling premium-grade segregation that commands origin-certified price premiums.
For Market Incumbents: Cement backward integration into tissue-culture propagation facilities to secure cultivar purity and pollination timing control against emerging precision-agriculture entrants. Expand controlled-atmosphere cold chain capacity in Al-Qassim to defend against Tunisian infrastructure investment. Lock in multi-year halal certification contracts before UAE-Saudi regulatory divergence widens compliance costs. For New Entrants and Emerging Players: Begin with underpenetrated North African processing infrastructure, specifically Tunisia's Deglet Noor cooperatives lacking controlled-atmosphere assets. Target German beverage formulators seeking clean-label date syrup alternatives to refined cane sugar. Pursue direct-to-consumer online channels for organic-certified gift assortments, bypassing hypermarket slotting fee barriers. For Investors and Strategic Acquirers: Gulf-based contract manufacturers with captive syrup production lines are the most active acquirer in this space, consolidating fragmented paste and extract capacity. Long-term viability favors operators with integrated cold-chain ownership and EFSA novel food dossier capabilities. Watch EFSA approval timelines for date seed fiber applications as inflection signal for ingredient derivative valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Cold Chain Expansion | Al-Qassim growers deploy infrastructure to maintain tamr-grade shelf stability for Ramadan retail peaks. |
| Blockchain Traceability Integration | UAE Ministry pilots reduce customs friction for Negev Desert and Coachella Valley organic exporters. |
| Captive Syrup Production Buildout | Gulf contract manufacturers secure supply continuity for German beverage formulator procurement. |
| Hyperspectral Sorting Adoption | Mid-scale Saudi farms decentralize quality control to enable direct European organic buyer contracts. |
| Dual Dossier Regulatory Investment | Organic Medjool processors navigate both EU organic regulation and EFSA novel food safety assessments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with date palm cooperative managers, hypermarket category buyers, beverage formulation R&D directors, and cold-chain logistics operators with secondary validation. Sources included Saudi SFDA export filings, UAE ESMA halal certification registries, EFSA novel food submission databases, and customs trade records for dried fruit categories. Bottom-up farm-level production estimates and top-down retail channel value flows were triangulated to anchor volume and value outputs.
Comparable historical periods anchored projections across the analysis window, with segmentation modeling across product format, end-user channel, application use case, and geographic origin cluster. CAGRs were derived from trend extrapolation adjusted for regulatory pathway uncertainty and infrastructure investment cycles. Forecast inputs incorporated pollination labor availability curves, desalinated water tariff trajectories, and phytosanitary digitization adoption rates.
Several conditions sit outside the modeled scope, including extreme climate events affecting flowering timing, sudden shifts in EU novel food evaluation frameworks, and Gulf regulatory harmonization outcomes. Forecasts reflect documented assumptions about tissue-culture propagation yield improvements and blockchain certificate adoption velocity. A small set of named triggers warrants ongoing watch: EFSA date seed extract approvals, Saudi Vision 2030 subsidy disbursement pacing, and Tunisian cooperative infrastructure investment decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
UAE Agriculture Market
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
Mushroom Substrate Market
Agriculture and Agri Products
Mushroom Cultivation Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Plant Breeding Market
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Africa Orange Market