
 US Residential Organic Compost Market | 2026-2036
US Residential Organic Compost Market Size, Share, and Industry Trends Forecast 2026-2036
US Residential Organic Compost Market Intelligence
State-level landfill diversion mandates, such as California's SB 1383, are realigning the cost-of-entry calculus for new compost producers. This regulatory pressure creates opportunities for established operators like Agromin, which leverages its extensive processing infrastructure in the Western US. Meanwhile, Cedar Grove dominates the Pacific Northwest market through its closed-loop collection and composting services. Vermont Compost Company specializes in high-nutrient blends for dedicated gardeners across the Northeast.
Residential organic compost is a soil amendment derived from the controlled decomposition of materials like yard trimmings and food scraps. The final product must meet quality criteria, including pathogen reduction and heavy metal limits under frameworks like the US Composting Council's STA program, to enhance soil fertility. While compost bins represent the largest product type segment, demand for specialized worm composters is increasing. Garden fertilization remains the primary application, with vegetable cultivation driving sales of nutrient-specific blends.
The market operates under EPA goals for waste reduction and USDA National Organic Program standards for certification. State environmental agencies, such as California's CalRecycle, enforce organic waste diversion mandates that stimulate local supply. The critical decision for producers is whether to meet local municipal standards or invest in national organic certifications for broader market access.
Market Dynamics
The central dynamic shaping the US residential organic compost market is the intersection of state-level landfill diversion mandates and a rising consumer preference for organic gardening, which together stimulate both supply of feedstock and end-user product demand.
Growth Catalysts
- State-Level Mandates:Regulations such as California's SB 1383 compel municipalities to divert organic waste from landfills, creating a reliable, large-scale feedstock supply for compost producers and building local consumer awareness.
- Home Vegetable Cultivation:A surge in home gardening, particularly for food production, drives demand for nutrient-rich, certified organic compost to improve soil health and plant yields without synthetic chemicals.
- USDA Organic Certification:The USDA National Organic Program provides a clear standard for compost used in organic farming and gardening, enabling producers to access a premium market segment willing to pay for certified inputs.
Market Restraints
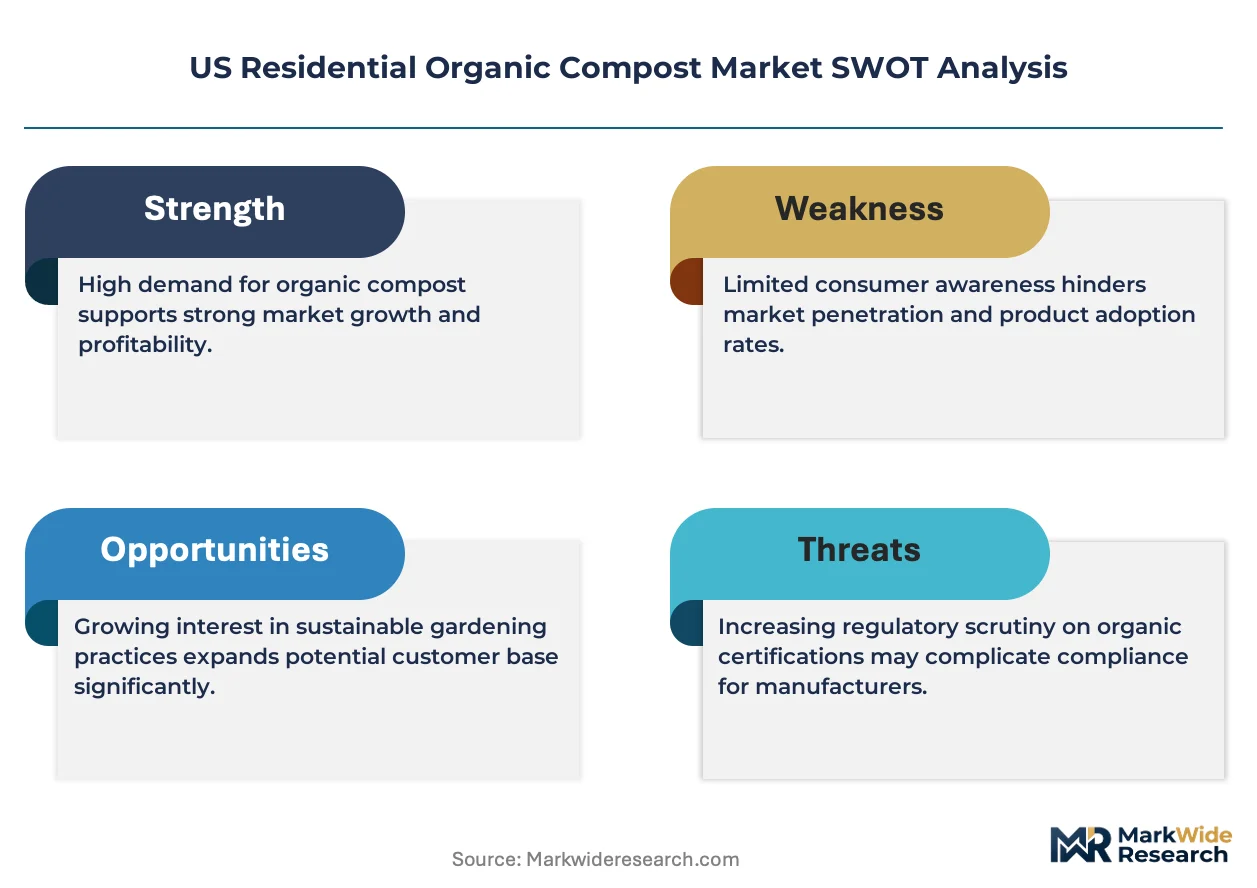
- Feedstock Contamination:The presence of plastics, glass, and other non-compostable materials in municipal green waste streams significantly increases sorting and processing costs, impacting producer margins and final product quality.
- High Logistics Costs:The low value-to-weight ratio of compost makes long-distance transportation economically unviable, limiting a producer's market reach to a specific geographic radius and creating fragmented local markets.
- Competition from Substitutes:Synthetic fertilizers and non-organic soil amendments remain widely available and are often cheaper alternatives for consumers less focused on organic certification, limiting market penetration in some segments.
Strategic Opportunities
- Geographic Expansion:There is significant potential for market entry in the US Southeast and Midwest, where municipal organic collection programs are less mature compared to the West Coast and Northeast.
- Specialized Product Blends:Development of custom compost formulations for specific applications like container gardening, lawn care, or erosion control opens new revenue streams beyond general-purpose garden soil amendments.
- Direct-to-Consumer Models:Subscription-based delivery services for bagged compost can bypass traditional retail channels, building brand loyalty and capturing higher margins directly from dedicated home gardeners across the US.
Industry Challenges
- Regulatory Patchwork Navigation:Producers face the complexity of adhering to a mix of local and state-level environmental regulations, such as those from CalRecycle, alongside voluntary national standards like the USCC's STA program.
- Seasonal Demand Fluctuations:Production and inventory management must contend with intense seasonal demand peaks in spring and fall, creating operational bottlenecks and cash flow challenges during off-season periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Residential Organic Compost Market |
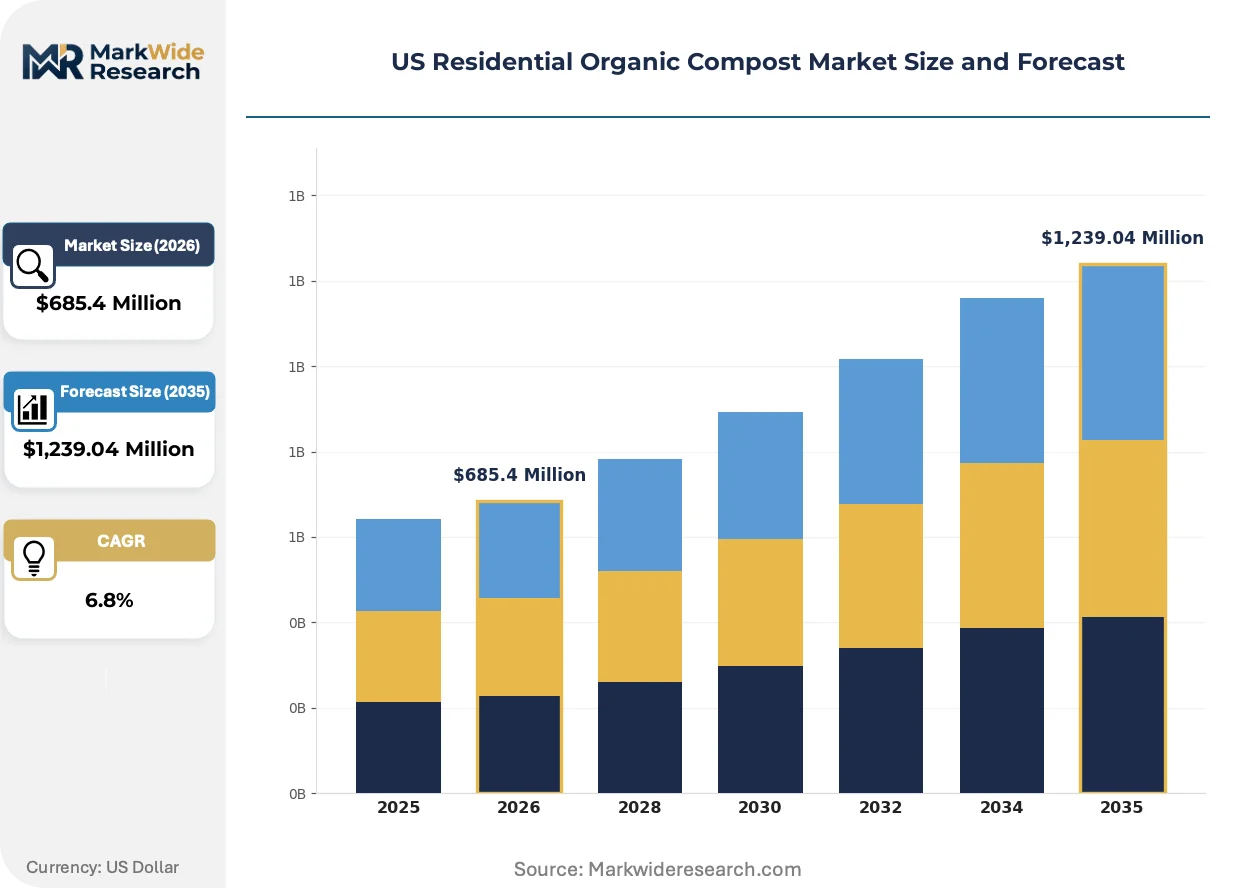
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost Bins, Worm Composters, Bokashi Systems, Liquid Compost Application: Garden Fertilization, Lawn Care, Vegetable Cultivation, Floral Arrangement End User: Home Gardeners, Landscape Professionals, Community Gardens, Urban Farmers Distribution Channel: Online Retail, Garden Centers, Home Improvement Stores, Local Markets |
| Companies Covered | Atlas Organics, Garden-Ville, Malibu Compost, Vermont Compost Company, Dairy Doo, American Composting, Inc., Blue Ribbon Organics, Agromin, Cedar Grove, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Residential Organic Compost Market Strategic Shifts & Innovations
The market's evolution is defined by a convergence of data-driven soil science with more efficient processing methods. These advancements are scaling in response to a complex and growing web of US environmental regulations.
In-situ sensor technology provides real-time data on temperature, moisture, and microbial activity within compost piles. Dedicated home gardeners and boutique urban farms are early adopters, using smart composters and associated apps. This integration of IoT monitoring is unifying the art of traditional composting with the science of soil chemistry, enabling consistent production of performance-specific blends.
The EPA's National Recycling Strategy sets goals for reducing food waste sent to US landfills. This federal guidance encourages states to adopt policies that increase the volume of organic feedstock available for composting. The bagged compost segment is most affected, as producers must scale operations to process this influx while maintaining quality.
A key demand-side shift is consumer preference for products with the US Composting Council's Seal of Testing Assurance (STA). This disrupts sales of unverified bulk material, as buyers choose certified bagged compost guaranteeing safety and nutrient analysis. The trend is most pronounced among organic vegetable gardeners in the Pacific Northwest and Northeast.
US Residential Organic Compost Market Segmentation
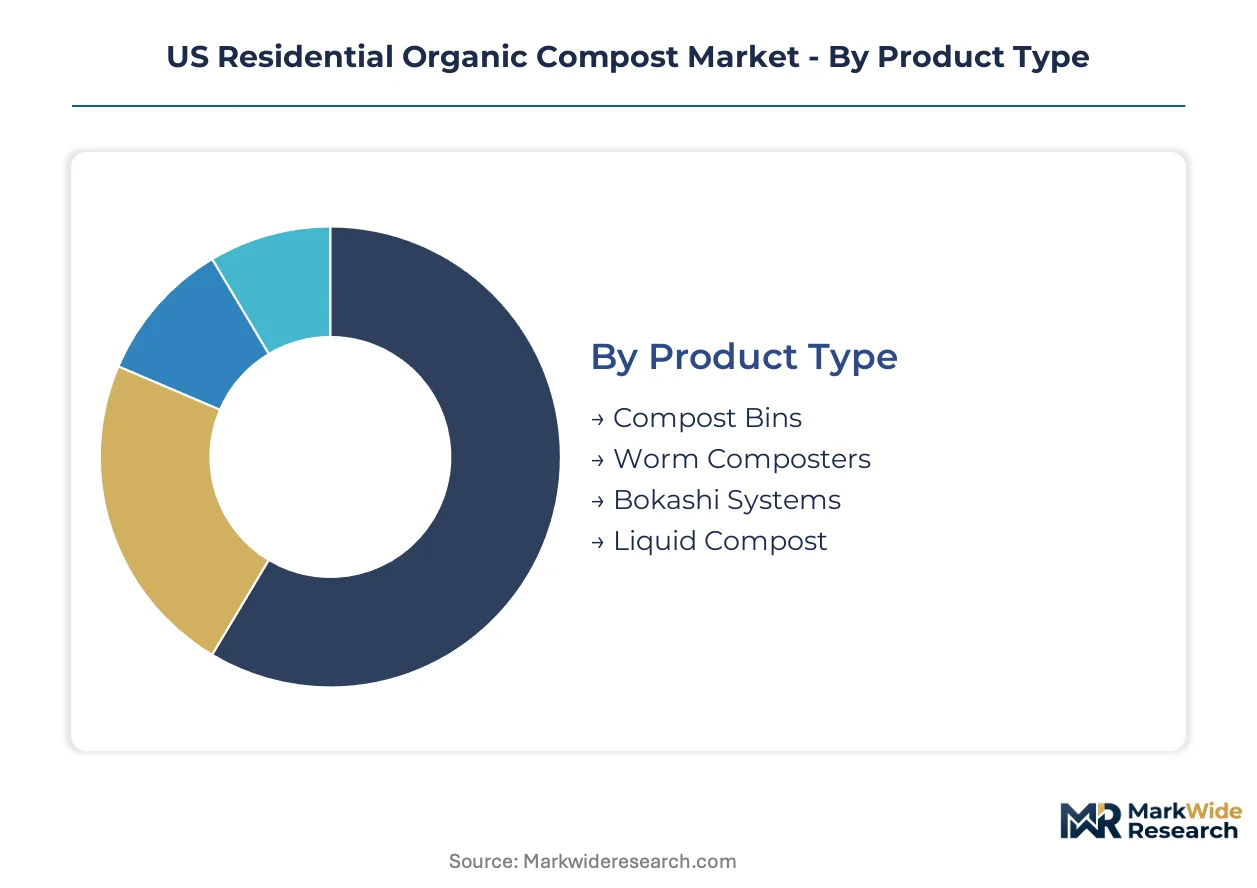
The US residential organic compost market exhibits diverse segmentation, reflecting varied consumer needs and product functionalities. Understanding these categories is crucial for producers aiming to align offerings with specific demand patterns across the country.
Product Type:
Consumers prioritize product type based on ease of use, space availability, and desired composting method.
- Compost Bins:These are enclosed structures designed for aerobic decomposition of organic matter, typically yard trimmings and food scraps. Demand for compost bins remains strong among general home gardeners seeking a traditional, cost-effective composting solution for larger volumes of waste.
- Worm Composters:Also known as vermicomposting systems, these units utilize specific worm species, primarily red wigglers, to break down food waste into nutrient-rich castings. Increasing interest from urban dwellers and dedicated organic gardeners drives sales of worm composters, valued for their efficiency in small spaces and high-quality output.
- Bokashi Systems:This anaerobic fermentation method uses inoculated bran to pickle food scraps, including meat and dairy, before burial or addition to a traditional compost pile. Bokashi systems appeal to consumers seeking to process a wider range of food waste with minimal odor.
- Liquid Compost:This category includes compost tea or extracts, produced by steeping finished compost in water to create a nutrient-rich liquid fertilizer. Liquid compost is favored by gardeners for its immediate nutrient availability and ease of application to plants.
Volume sits with Compost Bins; growth tilts toward Worm Composters.
Application:
The application segment highlights where residential organic compost is primarily utilized, influencing product formulation and marketing efforts.
- Garden Fertilization:This application involves incorporating compost into garden beds to enrich soil structure, improve water retention, and supply essential plant nutrients. Home gardeners widely use compost for general garden fertilization to support plant vigor.
- Vegetable Cultivation:Specifically focuses on using organic compost to enhance soil for growing edible plants, often requiring nutrient-specific blends for optimal yields. A surge in home vegetable cultivation drives significant demand for certified organic compost inputs.
- Lawn Care:Compost is applied to lawns as a top dressing to improve turf health, reduce the need for synthetic fertilizers, and enhance soil microbial activity. This application is gaining traction among environmentally conscious homeowners.
- Floral Arrangement:Compost is sometimes used in specialized potting mixes or as a soil amendment for ornamental plants and flowers, promoting vibrant blooms and robust growth. Boutique nurseries and dedicated flower enthusiasts represent this niche.
Demand for Garden Fertilization remains consistent, while Vegetable Cultivation exhibits significant expansion.
End User:
Understanding the end-user base helps producers tailor product specifications, packaging, and distribution strategies for maximum market penetration.
- Home Gardeners:This segment includes individuals who cultivate plants for personal enjoyment, food production, or aesthetic purposes in their residential spaces. Rising adoption among home gardeners, particularly for food production, drives substantial compost sales across the US.
- Urban Farmers:These individuals or groups cultivate food in urban environments, often utilizing small plots, rooftops, or vertical farming systems. Urban farmers seek high-quality, nutrient-dense compost for intensive cultivation in limited spaces.
- Landscape Professionals:This group comprises businesses or individuals offering landscaping, gardening, and property maintenance services to residential clients. Landscape professionals purchase compost for large-scale soil amendment and planting projects.
- Community Gardens:These are shared green spaces where individuals or groups cultivate plots, often in urban or suburban settings, fostering community engagement and local food production. Community gardens represent a collective purchasing segment for bulk compost.
The largest customer base resides in Home Gardeners, with Urban Farmers showing the steepest expansion trajectory.
Distribution Channel:
The choice of distribution channel impacts market reach, pricing strategies, and brand visibility for residential organic compost products.
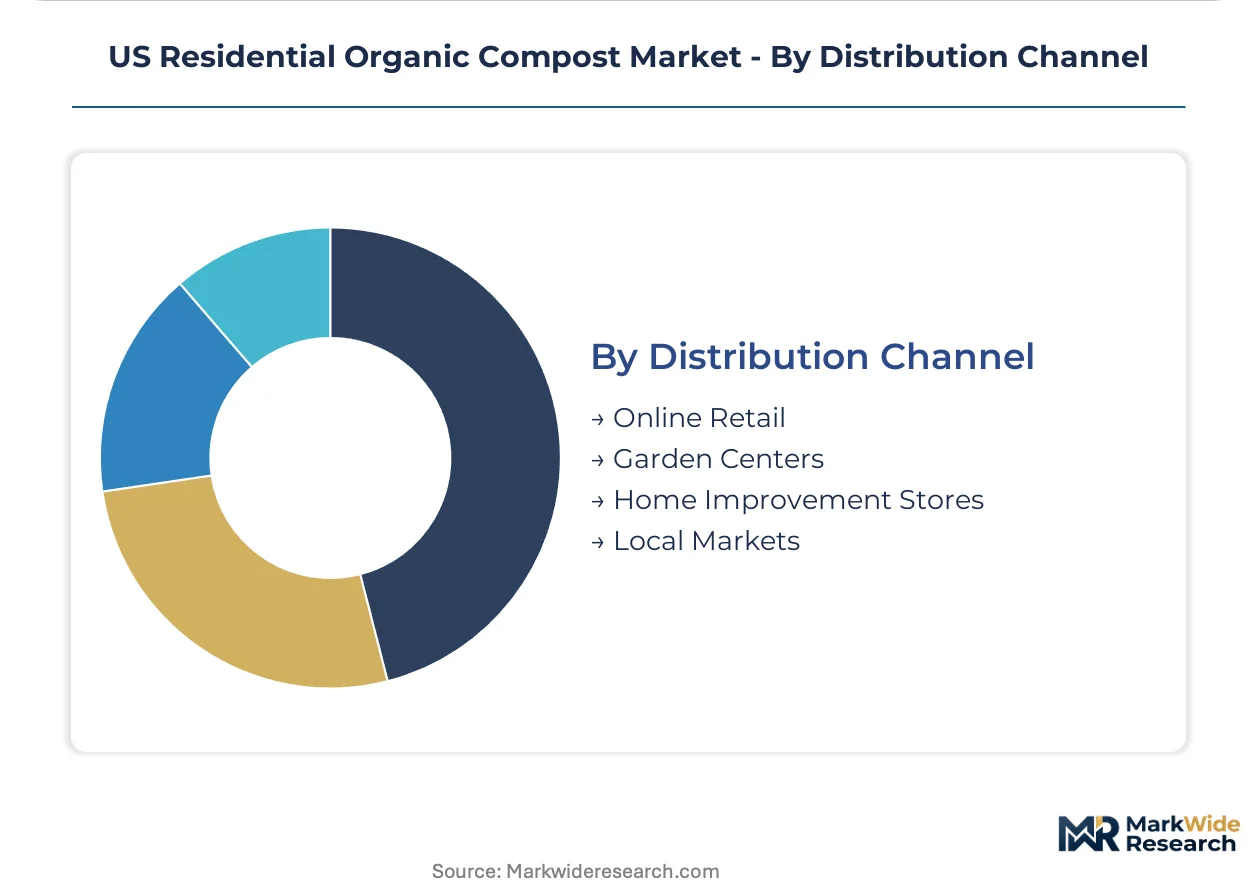
- Garden Centers:These specialized retail outlets offer a wide range of gardening supplies, including various types of compost, providing expert advice and product selection. Garden centers serve as a primary point of sale for many home gardeners seeking quality compost.
- Online Retail:E-commerce platforms allow consumers to purchase bagged compost and composting systems for home delivery, offering convenience and broader product availability. Online retail is expanding, particularly for specialized compost blends and worm composters across the US.
- Home Improvement Stores:Large retailers like Lowe's or Home Depot carry general-purpose compost and soil amendments, catering to a broad customer base with accessible locations. These stores offer convenience for homeowners undertaking various home and garden projects.
- Local Markets:Farmers' markets, community co-ops, and direct-from-producer sales represent local channels for compost, often emphasizing locally sourced and produced organic materials. These markets appeal to consumers prioritizing local economies and sustainable practices.
Traditional sales channels dominate through Garden Centers, but Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
States with aggressive organic waste diversion goals drive significant activity in the US residential organic compost market. These mandates, particularly in coastal regions, stimulate both feedstock supply and end-user demand for compost products. Regulatory frameworks are shaping the competitive landscape by creating localized opportunities for producers.
California
Home vegetable cultivation and strong environmental consciousness drive compost demand across California. The state's SB 1383 mandate compels municipalities to divert organic waste from landfills. CalRecycle's enforcement in the Central Valley stimulates localized supply chains and processing infrastructure development.
Pacific Northwest
Dedicated organic gardeners and a strong consumer preference for certified products characterize the Pacific Northwest market. Local municipal organic collection programs support established operators like Cedar Grove. Seattle and Portland exhibit high adoption of closed-loop composting services and premium compost blends.
Northeast
Demand for high-nutrient blends in specialized gardening and urban farming supports the Northeast market. State environmental agencies encourage food waste diversion initiatives across the region. Vermont Compost Company serves dedicated gardeners across the Northeast with specialized, performance-specific products.
Southeast
Emerging interest in home gardening and a growing awareness of soil health represent key demand drivers in the Southeast. Municipal organic collection programs are less mature compared to other regions, but EPA goals provide federal guidance. Atlanta and Miami metros represent areas with expanding residential composting initiatives.
US Residential Organic Compost Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the US residential organic compost market. The market structure remains fragmented, with strong regional players dominating specific geographic areas. Strategic archetypes include large-scale waste processors, niche organic blend providers, and integrated closed-loop service operators. Companies pursue geographic expansion and specialized product blends to differentiate their offerings.
Specialists in organic compost production, such as Vermont Compost Company, exemplify a focus on high-nutrient blends for dedicated gardeners. Large-scale processors like Agromin occupy a position leveraging extensive infrastructure for efficient material handling across the Western US. Cedar Grove sits within the integrated service provider archetype, dominating the Pacific Northwest through closed-loop collection and composting services.
| Leading Market Players |
|---|
| Atlas Organics |
| Garden-Ville |
| Malibu Compost |
| Vermont Compost Company |
| Dairy Doo |
| American Composting, Inc. |
| Blue Ribbon Organics |
| Agromin |
| Cedar Grove |
| Others |
Cost & Logistics Intelligence
Landfill tipping fees, as a named cost benchmark, cascade through the US residential organic compost supply chain, influencing feedstock acquisition costs and ultimately shaping end-product pricing tiers.
Pricing Analysis
Lead-time-driven pricing offers premium for certified blends with immediate availability, while bulk or uncertified compost often sees spot market discounts. Pricing stratifies across premium, standard, and economy tiers based on US Composting Council STA certification and USDA organic standards. Geographic delivery cost represents a significant price differentiation driver due to compost's low value-to-weight ratio. Pricing softness in economy segments stems from competition with cheaper synthetic fertilizers. Dedicated organic vegetable cultivators exhibit lower price sensitivity for nutrient-specific blends compared to general home gardeners.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the fragmented US residential organic compost supply chain. Supply concentrates in California, the Pacific Northwest, and the Northeast due to robust organic waste diversion mandates. The market relies heavily on municipal food scraps and yard trimmings as primary raw material dependencies. Feedstock contamination represents a critical supply chain risk, increasing processing costs. Distribution runs through garden centers for specialized products and home improvement stores for general-purpose compost, alongside expanding online retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US residential organic compost market presents a consolidation play, driven by increasing regulatory complexity and the high capital expenditure required for advanced feedstock processing.
For Market Incumbents: Deepen vertical integration into feedstock collection and processing to control quality and cost. Expand certified product lines, particularly those meeting USDA organic standards, to capture premium market segments. Invest in advanced sorting technologies to mitigate feedstock contamination, a persistent threat to margins. Leverage existing infrastructure for geographic expansion into less mature US Southeast and Midwest markets.
For New Entrants and Emerging Players: California's SB 1383 in the US West Coast opens a window for localized processing and specialized compost blends. Target underpenetrated US Southeast and Midwest regions with emerging municipal programs. Develop custom compost formulations for niche applications like container gardening or specific crop cultivation. Implement direct-to-consumer subscription models for urban farmers seeking consistent, high-quality inputs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional waste processors with established municipal contracts in the US Northeast. Long-term viability rests on the increasing adoption of state-level organic waste diversion mandates across the country. Seek acquisition targets that are vertically integrated mid-cap specialists with strong regional collection networks and processing capabilities. The expansion of state-level food waste bans beyond coastal regions represents a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Emerging Regions | Increases market penetration and leverages growing municipal organic waste streams in the US Southeast. |
| Backward Integration into Feedstock Processing | Enhances quality control and reduces operational costs associated with contaminated municipal inputs. |
| USDA Organic Certification for New Blends | Unlocks access to premium market segments like dedicated organic vegetable cultivators across the US. |
| Direct-to-Consumer Subscription Model Launch | Builds brand loyalty and captures higher margins from dedicated home gardeners and urban farmers. |
| Development of Specialized Product Formulations | Addresses specific application needs like lawn care or container gardening, diversifying revenue streams. |
Research Approach
Independent corroboration across industry reports, government publications, and academic research underwrites the qualitative findings and quantitative projections for this study. Primary interviews with compost producers, waste management executives, home gardening experts, and municipal program managers provided critical insights. Secondary data sources included USDA National Organic Program standards, US Composting Council data, and CalRecycle reports. The analysis utilized both bottom-up assessments of production capacities and top-down market sizing approaches.
The analytical framework anchored the forecast window to historical market performance and observed regulatory shifts across the analysis window. Segmentation dimensions modeled included product type, application, end-user, distribution channel, and regional regulatory environment. Compound annual growth rates derived from projected demand drivers like home vegetable cultivation and supply-side capacity additions. Key forecast inputs included state-level landfill diversion mandates and evolving consumer preferences for organic gardening practices.
Caveats apply where new environmental regulations, significant shifts in feedstock availability, or unforeseen technological disruptions could materially shift the outlook. Risk factors include feedstock contamination levels, fluctuating transportation costs, and substitute product competition. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
Beet Pulp Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Sugar Beet Market
Agriculture and Agri Products
Colombia Agriculture Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
US Greenhouse Horticulture Market
Agriculture and Agri Products
Germany Animal Protein Market