
 United Kingdom Animal Protein Market | 2026-2036
United Kingdom Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Animal Protein Market Analytics
Market Dynamics
Supermarket supply chains is reconfiguring around shorter domestic sourcing loops and direct farm partnerships. Arla Foods AmbA anchors its position through cooperative dairy-protein integration across British farmland. Glanbia PLC extends its ingredient technology leadership into whey and casein derivatives for sports nutrition. Kerry Group PLC differentiates through flavor-protein systems tailored to UK food manufacturers.
Product Landscape
Animal protein encompasses tissue-derived proteins from livestock including cattle, swine, poultry, and ovine species, typically characterized by complete amino acid profiles and digestibility coefficients exceeding plant alternatives. These proteins serve as foundational inputs for human nutrition, pet food formulation, and industrial biotechnology across British manufacturing. Poultry leads volume throughput due to shorter production cycles and lower feed conversion ratios, while processed forms capture expanding margin pools through ready-meal and convenience formats. Fresh beef and lamb retain premium positioning in supermarket and food service channels where provenance labeling commands price separation.
Regulatory Environment
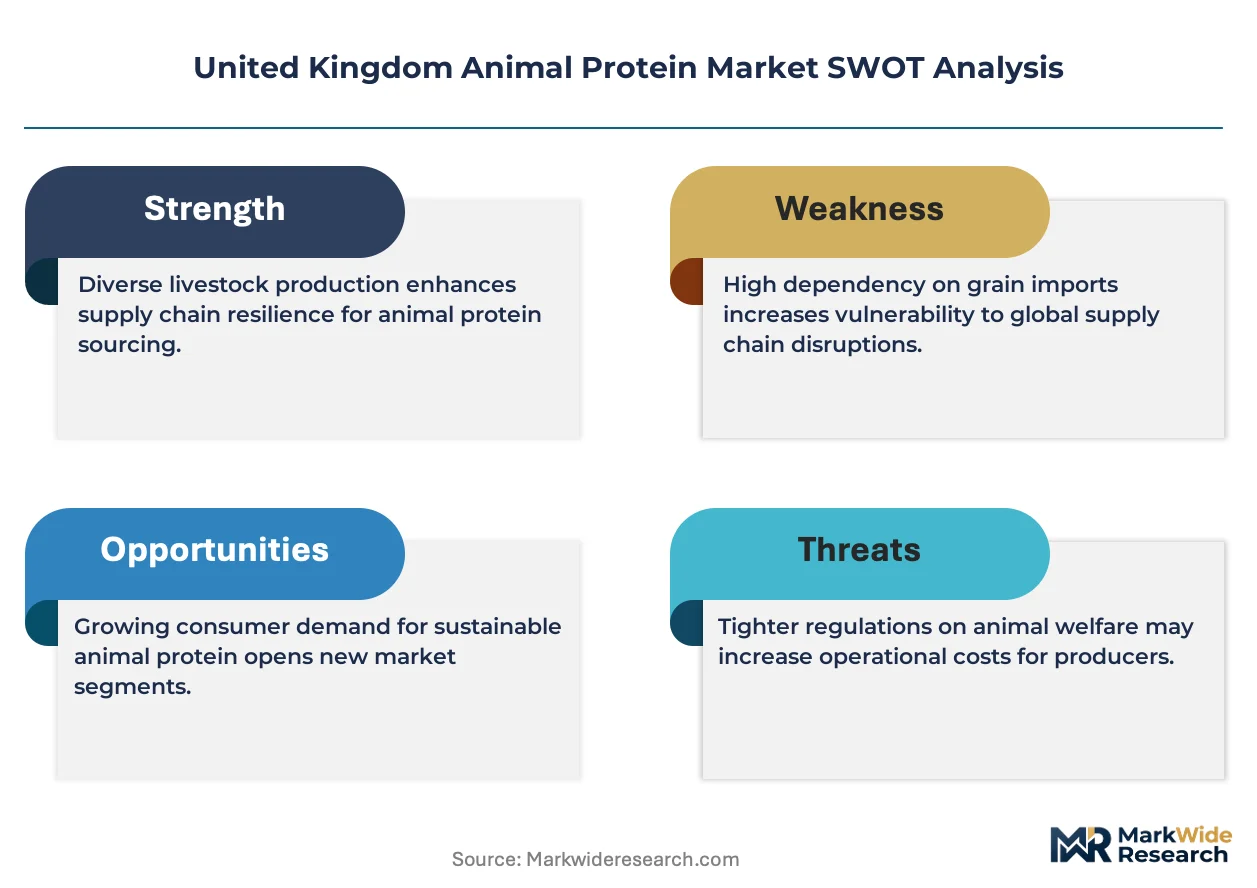
DEFRA oversees livestock welfare standards and slaughterhouse compliance under retained EU regulations, while the Food Standards Agency enforces labeling integrity and allergen controls across distribution channels. The Competition and Markets Authority monitors consolidation risks among major processors to preserve supplier choice for British farmers. Stakeholders must track evolving carbon accounting rules for scope three emissions and their eventual pass-through to protein pricing structures.
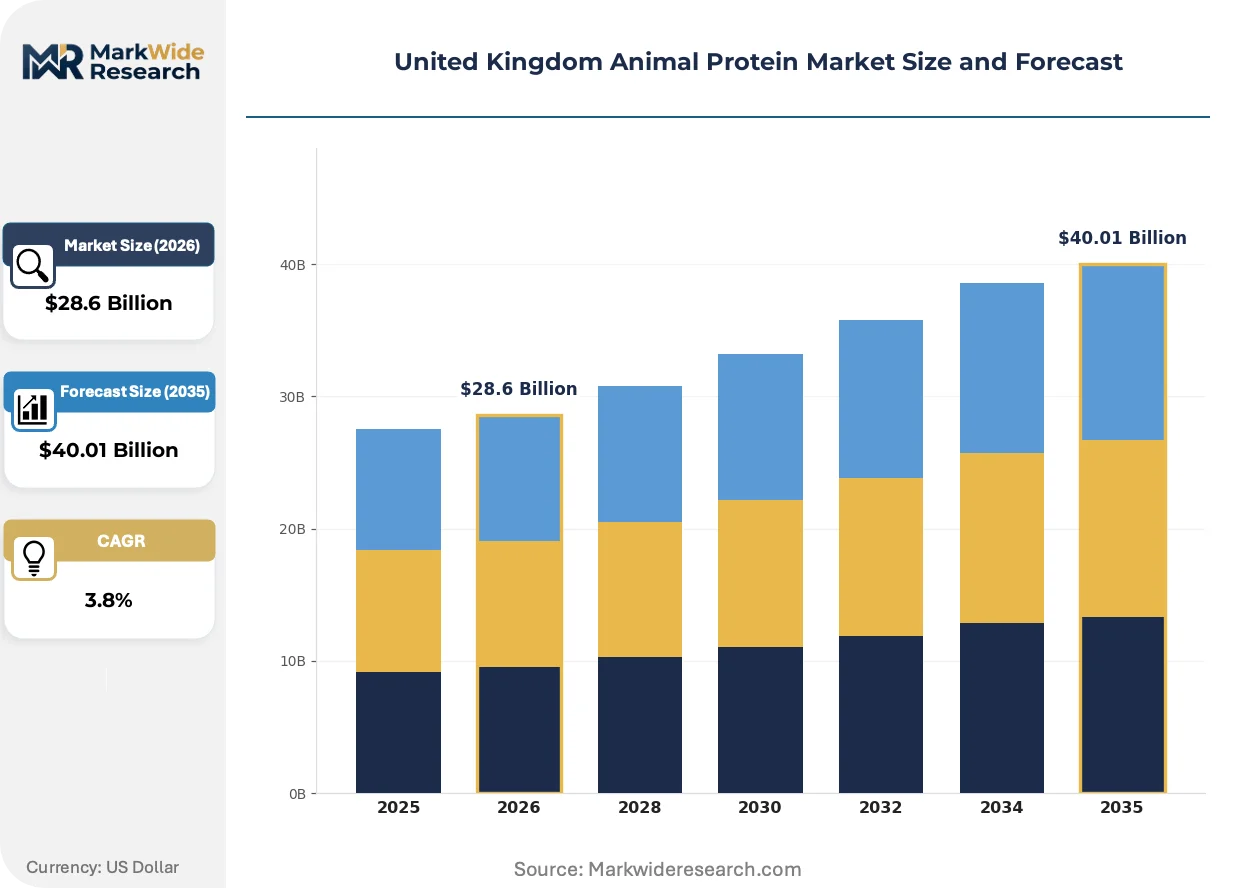
Market Dynamics
DEFRA's post-Brexit agricultural subsidy reforms are redirecting farm output toward domestic protein supply chains, compressing traditional import dependency while supermarket procurement consolidates around shorter sourcing loops and direct farm partnerships across England and Scotland.
Growth Catalysts
- Food service expansion:Operators across Greater London's restaurant and hospitality corridor are expanding menus with premium cuts, pulling additional volume through domestic channels.
- DEFRA subsidy redirection:Post-Brexit agricultural payment reforms are incentivizing British farmers to prioritize protein production for domestic supply chains over export-oriented commodity crops.
- Provenance labeling premiums:Fresh beef and lamb with geographic origin certification command measurable price separation in supermarket channels, rewarding domestic sourcing investments.
Market Restraints
- Feed input volatility:Compound feed costs fluctuate with global grain markets, squeezing margins for cattle and swine producers dependent on imported soy and maize.
- Slaughterhouse concentration:Processing capacity concentrates in a limited number of large-scale facilities, creating geographic supply bottlenecks during seasonal peaks.
- Scope three carbon accounting:Pending DEFRA regulations on supply chain emissions measurement threaten to impose compliance costs without established certification infrastructure.
Strategic Opportunities
- Whey and casein derivative expansion:Sports nutrition and functional food applications offer margin expansion beyond commodity dairy proteins.
- Scottish Highlands sourcing:Underdeveloped ovine production in northern Scotland presents volume growth potential with distinct provenance positioning.
- Direct farm partnerships:Supermarket supply chains are bypassing traditional wholesale intermediaries, creating captive sourcing relationships with preferred producers.
Industry Challenges
- Veterinary talent scarcity:Large-animal veterinary capacity concentrates in southern England, leaving northern production regions underserved for herd health management.
- Cold chain capex requirements:Shorter domestic sourcing loops demand upgraded refrigerated distribution infrastructure from farm gate to retail shelf.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Animal Protein Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $40.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb Form: Fresh, Frozen, Processed, Canned Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers End User: Households, Food Service, Retailers, Industries |
| Companies Covered | Koninklijke FrieslandCampina NV, Carbery Food Ingredients Limited, Arla Foods AmbA, Insect Technology Group Holdings UK Limited, Agrial Enterprise, Glanbia PLC, Darling Ingredients Inc., Jellice Pioneer Private Limited, Kerry Group PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Animal Protein Market Evolving Landscape
Precision fermentation and cellular agriculture are beginning to intersect with conventional livestock supply chains, while regulatory frameworks and procurement models adapt to new protein production paradigms across British manufacturing.
Cellular agriculture technology is hybridizing traditional livestock production with lab-grown tissue cultivation, enabling novel protein formats that blend conventional and cultivated inputs. Early adopters in premium food service channels are testing hybrid products at limited scale. This convergence is compressing the boundary between commodity livestock and biotechnology supply chains.
DEFRA's evolving carbon accounting rules for scope three emissions are forcing processors to document supply chain emissions from farm to retail. The Food Standards Agency is developing labeling protocols to accommodate these measurements. Beef and lamb supply chains face the steepest compliance burden due to methane-intensive production profiles.
Buyer concentration among major supermarket groups is consolidating procurement decisions into fewer headquarters-level category managers. Direct sourcing agreements are displacing traditional livestock auction markets as the primary price discovery mechanism. This shift concentrates negotiating leverage in Greater London and the Midlands distribution corridors.
United Kingdom Animal Protein Market Segmentation
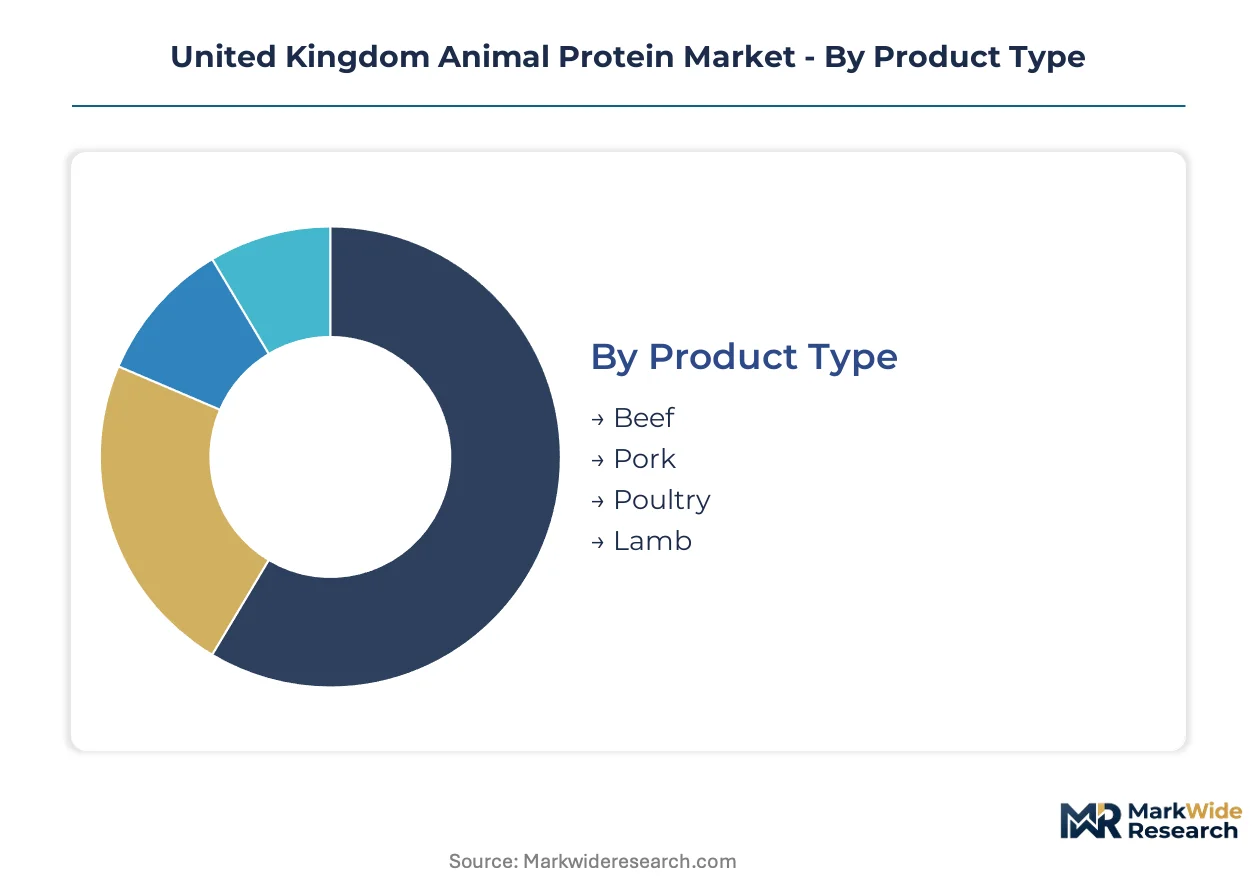
Segmentation in the United Kingdom Animal Protein Market reveals distinct operational rhythms and margin profiles across protein categories. Each dimension exposes different pressure points in procurement, cold chain logistics, and regulatory compliance that shape competitive positioning.
Product Type:
Poultry cycles from hatch to slaughter in six weeks, compressing working capital requirements and price volatility exposure. Beef demands eighteen to thirty-six month finishing periods, tying up land and feed resources across multiple seasons. Lamb occupies intermediate ground with seasonal breeding constraints. Pork sits between poultry speed and cattle capital intensity.
- Poultry:Broiler production achieves complete turnover in forty-two days, enabling rapid supply response to demand shifts. Greater London food service operators pull disproportionate volume through domestic channels, though imported feed soy exposes margins to currency fluctuations.
- Beef:Grass-fed and grain-finished systems span eighteen to thirty-six months from breeding to processing, creating extended capital lock-up. Scottish Highland and Welsh hill farms supply premium provenance-certified cuts commanding measurable price separation in supermarket channels.
- Pork:Six-month production cycles balance throughput speed with bacon and ham processing versatility. East Anglian concentration of finishing units creates geographic supply bottlenecks during seasonal peaks.
- Lamb:Seasonal breeding patterns restrict year-round supply consistency, though distinct Highland and Welsh origin certifications support premium positioning. Northern England and Scottish Borders producers dominate volume.
Poultry anchors the volume base while beef gains share at the steepest rate among premium-positioned segments.
Form:
Cost tiers separate segments by cold chain infrastructure requirements and value-add processing intensity. Fresh products demand continuous refrigeration and compressed shelf windows. Frozen and processed forms amortize infrastructure across extended holding periods. Canned represents legacy preservation with declining household penetration.
- Fresh:Unprocessed muscle tissue retains complete amino acid profiles and commands highest per-kilogram pricing. Supermarket channels in Greater London and the Midlands corridor concentrate demand, where provenance labeling drives measurable price separation.
- Processed:Value-added formats including sausages, burgers, and ready-meal components capture expanding margin pools. Food service operators across England's hospitality corridor pull volume through domestic manufacturing partnerships.
- Frozen:Extended shelf stability reduces spoilage risk for retailers while enabling bulk procurement. Wholesaler and food service channels dominate offtake, particularly for poultry portions.
- Canned:Heat-sterilized preservation extends shelf life to three to five years with ambient storage. Household penetration concentrates in older demographics and emergency stockpiling segments.
Fresh forms dominate value capture while processed products expand most quickly through convenience-oriented channels.
Distribution Channel:
Customer type concentration varies sharply across procurement models. Supermarket headquarters-level category managers now displace traditional livestock auctions as primary price discovery mechanisms. Convenience stores and online retail serve fragmented demand with higher per-unit logistics costs. Wholesalers intermediate between processors and food service at thinning margins.
- Supermarkets:Tesco, Sainsbury's, Asda, and Morrisons concentrate over seventy percent of British household protein procurement through direct farm partnerships. Category managers in Greater London and Midlands distribution corridors negotiate exclusive supply agreements bypassing traditional wholesale intermediaries.
- Food Service:Restaurant, hotel, and institutional operators across Greater London's hospitality corridor demand consistent portion-controlled supply. Direct processor relationships are displacing traditional wholesale purchasing.
- Online Retail:Ocado and Amazon Fresh platforms aggregate fragmented household demand with refrigerated last-mile delivery. Premium cuts and subscription boxes represent fastest-expanding sub-segments.
- Convenience Stores:Limited cold chain capacity restricts assortment to frozen and extended-shelf-life processed formats. Urban locations in northern England and Scotland show strongest penetration.
Supermarket direct sourcing anchors procurement volume while online retail climbs the fastest among emerging channels.
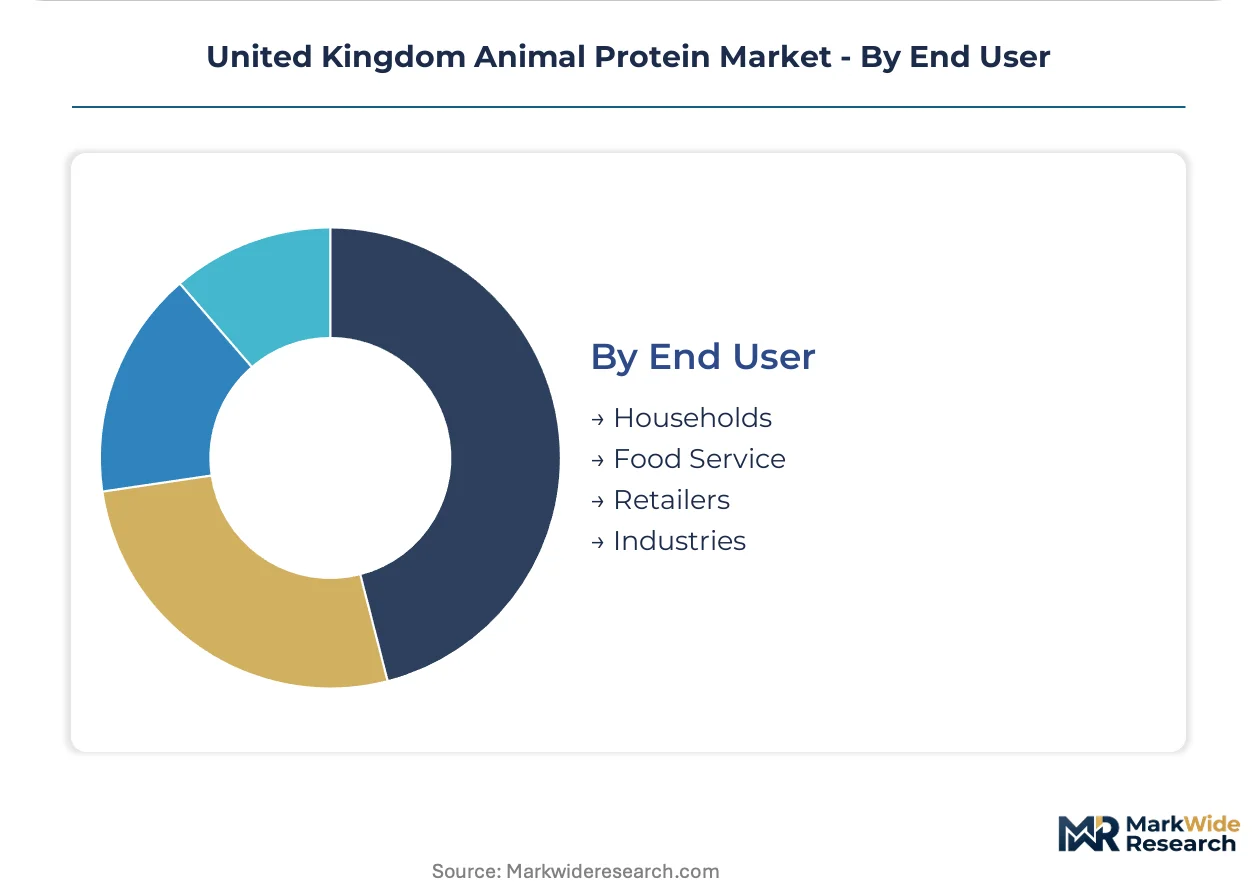
End User:
Application requirements segment demand by volume scale and specification precision. Households prioritize convenience and provenance signaling. Food service demands consistent quality grading and portion control. Industrial users seek functional protein properties for ingredient applications. Retailers intermediate with private-label development.
- Households:Domestic consumption prioritizes convenience formats, provenance certification, and health-positioned cuts such as lean beef and skinless poultry. Greater London and South East England concentrate highest per-capita expenditure.
- Food Service:Restaurants, hotels, and catering operations demand consistent portion weights and quality grading for menu cost control. Premium steakhouse and gastropub channels in England's hospitality corridor drive demand for aged beef and heritage breed lamb.
- Industries:Pet food manufacturers, pharmaceutical extractors, and biotechnology processors purchase rendered meals, collagen, and enzyme feedstocks. Functional protein specifications dominate procurement criteria over culinary quality.
- Retailers:Supermarket private-label development and convenience store supply represent intermediary demand with specification requirements set by downstream household and food service customers.
Household consumption anchors demand volume while food service gains share at the steepest rate through premium menu expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DEFRA's post-Brexit agricultural subsidy reforms are redirecting farm output toward domestic protein supply chains across England, Scotland, Wales, and Northern Ireland. Sub-regional production clusters concentrate around distinct livestock specializations and cold chain infrastructure. Each region exhibits differentiated regulatory exposure and procurement channel concentration.
Greater London and Southeast England
Restaurant and hospitality operators across Greater London's corridor are expanding menus with premium cuts, pulling additional volume through domestic channels. The Food Standards Agency enforces labeling integrity and allergen controls across distribution networks. Category managers in Greater London negotiate exclusive supply agreements with direct farm partnerships bypassing traditional wholesale intermediaries.
Midlands
Supermarket headquarters-level procurement concentrates in the Midlands distribution corridors where direct sourcing agreements displace traditional livestock auction markets. DEFRA oversees livestock welfare standards and slaughterhouse compliance under retained EU regulations. Cold chain infrastructure upgrades connect farm gate to retail shelf across Staffordshire and Leicestershire processing clusters.
Scotland
Scottish Highland and Borders producers dominate ovine volume with distinct provenance certifications supporting premium positioning. The Competition and Markets Authority monitors consolidation risks among major processors to preserve supplier choice for Scottish farmers. Edinburgh and Glasgow food service channels test hybrid cellular agriculture products at limited scale.
Wales
Welsh hill farms supply premium provenance-certified beef cuts commanding measurable price separation in supermarket channels. DEFRA's evolving carbon accounting rules for scope three emissions impose compliance documentation requirements from farm to retail. Aberystwyth and Bangor veterinary services face capacity constraints serving northern production regions.
Northern England
East Anglian concentration of pork finishing units creates geographic supply bottlenecks during seasonal peaks. Pending DEFRA regulations on supply chain emissions measurement threaten to impose compliance costs without established certification infrastructure. Yorkshire and Cumbria processors extend ingredient technology leadership into whey derivatives for sports nutrition applications.
United Kingdom Animal Protein Market Competitive Landscape
On the supply side, the industry is consolidating around cooperative dairy-protein integration, ingredient technology specialists, and flavor-protein system developers. Three strategic archetypes dominate: dairy cooperatives with backward farm control, ingredient technology platforms, and integrated flavor-protein solution providers. Competitive moves concentrate on direct farm partnerships and portfolio diversification into whey and casein derivatives.
Within the cooperative tier, Arla Foods AmbA and FrieslandCampina exemplify farmer-owned structures with captive milk supply. Glanbia PLC and Kerry Group PLC occupy positions as ingredient technology specialists extending into functional protein applications. Carbery Food Ingredients represents the Irish dairy-protein processing archetype with cooperative ownership structures.
| Leading Market Players |
|---|
| Koninklijke FrieslandCampina NV |
| Carbery Food Ingredients Limited |
| Arla Foods AmbA |
| Insect Technology Group Holdings UK Limited |
| Agrial Enterprise |
| Glanbia PLC |
| Darling Ingredients Inc. |
| Jellice Pioneer Private Limited |
| Kerry Group PLC |
| Others |
Value Network & Pricing Analysis
Slaughterhouse undercapacity across northern England and Scottish Borders compresses processor negotiating leverage while amplifying farmgate price volatility. DEFRA's subsidy redirection tightens domestic supply availability, forcing buyers to absorb cost pass-throughs or accept longer procurement lead times from alternative regions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates provenance-certified Highland lamb and aged beef from commodity poultry and undifferentiated pork. Price differentiation hinges on geographic origin certification and volume scale, with supermarket category managers extracting steepest discounts for bulk frozen poultry commitments. Cost compression in standard-tier beef is intensifying because compound feed imports track sterling weakness against dollar-denominated soy markets. Food service operators in Greater London's hospitality corridor demonstrate least price sensitivity, while northern England convenience stores serving frozen formats face margin erosion from refrigerated last-mile logistics.
Supply Chain Analysis
Extended payment terms from Tesco and Sainsbury's headquarters procurement teams strain working capital for Scottish Highland lamb producers, accelerating cooperative consolidation among smaller finishers. Geographic supply concentration centers on England's East Anglian pork belt, Scottish Borders ovine operations, and Welsh hill beef farms. Raw material dependencies draw from imported Brazilian soy, Ukrainian sunflower meal, and domestic wheat feedstock. Single-source vulnerability concentrates in compound feed milling capacity controlled by three national blenders. Distribution runs through Midlands cold chain hubs connecting farm gate to retail shelf.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Animal Protein Market reads as a cyclical recovery anchored to DEFRA's agricultural subsidy redirection tightening domestic protein availability. Farmgate price inflation signals the upswing phase, rewarding operators with captive supply relationships.
For Market Incumbents: Harden defensibility by securing exclusive direct farm partnerships across Scottish Highlands and Welsh hill regions before competitor procurement consolidation accelerates. Invest in cold chain infrastructure upgrades linking northern England processing clusters to Midlands distribution corridors. Cellular agriculture substitution threats in premium food service channels demand early positioning through hybrid product development with Edinburgh and Glasgow test kitchens.
For New Entrants and Emerging Players: Establish a beachhead in whey and casein derivative sports nutrition applications where Glanbia and Kerry Group have not fully saturated functional protein positioning. Underdeveloped ovine production in northern Scotland presents volume growth potential with distinct provenance certification leverage. A direct-to-food-service go-to-market angle bypasses supermarket procurement concentration entirely.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cooperative dairy-protein processors with captive milk supply and long-term ingredient technology contracts. Five-to-ten year viability favors operators with backward integration into rendering and collagen extraction capabilities. The signal to watch as inflection indicator is DEFRA's scope three carbon accounting implementation timeline and its pass-through to protein pricing structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Farm Partnership Expansion | Tesco and Sainsbury's category managers bypass traditional livestock auctions for captive supply security. |
| Whey Derivative Capacity Buildout | Sports nutrition applications in Yorkshire and Cumbria extend margin capture beyond commodity dairy. |
| Highland Provenance Certification Investment | Scottish Borders ovine producers command measurable price separation in Greater London channels. |
| Cold Chain Infrastructure Upgrade | Refrigerated distribution from Staffordshire and Leicestershire clusters reduces spoilage risk. |
| Hybrid Cellular Agriculture Testing | Edinburgh and Glasgow food service channels pilot lab-grown tissue blends at limited premium scale. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with supermarket category managers, food service procurement directors, cooperative dairy board executives, and DEFRA agricultural policy officers. Secondary validation drew from Food Standards Agency labeling protocols, Competition and Markets Authority consolidation filings, DEFRA agricultural statistics, and British Meat Processors Association trade data. Bottom-up volume modeling across protein categories triangulated against top-down expenditure surveys from Greater London and Southeast England household panels.
Calibration against historical price discovery mechanisms anchored projections across the analysis window. Segmentation dimensions modeled include livestock species, product form, distribution channel concentration, and end-user application requirements. CAGRs were derived from rolling average growth trajectories adjusted for subsidy policy phase-ins and feed cost volatility assumptions. Industry-specific forecast inputs incorporated veterinary service capacity constraints and slaughterhouse utilization rates.
Stress conditions across sterling currency fluctuation, Brazilian soy export restrictions, and cellular agriculture regulatory approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about DEFRA payment scheme continuity and carbon accounting implementation sequencing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Singapore Floriculture Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
China Animal Protein Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Europe Compound Feed Market
Agriculture and Agri Products
Compound Horse Feedstuff Market