
 Asia-Pacific Rapeseed Oil Market | 2026-2036
Asia-Pacific Rapeseed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Rapeseed Oil Market Analytics
Supermarket and wholesale procurement networks across Southeast Asia are rewriting how rapeseed oil reaches food manufacturers and household buyers. Wilmar International Ltd leverages its integrated crushing and refining footprint across Malaysia and Indonesia to sustain supply continuity. Bunge Limited competes through port-advantaged origination in Australia, while Thai Vegetable Oil Public Co., Ltd. anchors domestic Thai demand with specialized refined product lines.
Asia-Pacific rapeseed oil is a triglyceride vegetable oil extracted from Brassica napus seeds, containing roughly 7% saturated fat, 61% monounsaturated oleic acid, and 19% polyunsaturated linoleic acid, with a smoke point of 230°C in refined form that suits high-temperature food processing. Its primary commercial purpose spans edible cooking medium, biodiesel feedstock, and cosmetic emollient base across the region. Refined oil dominates volume flows due to neutral flavor and extended shelf stability, while organic oil commands premium positioning among health-conscious urban consumers in South Korea and Japan. Biofuels represents the fastest-expanding end user as Indonesia and Malaysia advance blending mandates, though food industry absorption still captures the largest margin pool.
China's SAMR enforces GB/T 1536 standards for rapeseed oil quality and labeling, while India's FSSAI mandates fortification and contaminant limits that reshape product formulation requirements across the subcontinent. Australia's TGA and FSANZ frameworks govern oil imports and health claims, creating compliance gateways for regional traders. Stakeholders must monitor how Indonesia's B35 biodiesel mandate and prospective B40 escalation redirect crush volumes away from food channels toward fuel blending.
Market Dynamics
Indonesia's escalating biodiesel blending mandates are systematically redirecting rapeseed crush volumes away from food channels toward fuel production, compressing edible oil supply availability across Southeast Asian markets.
Growth Catalysts
- Indonesia's B35 mandate:The Ministry of Energy and Mineral Resources enforces 35% palm oil-based biodiesel blending, with prospective B40 escalation creating sustained feedstock demand that absorbs regional crush capacity and stabilizes farmer offtake pricing.
- Food processors:Chinese and Indian manufacturers expand rapeseed oil procurement for high-temperature frying and bakery applications, drawn by the refined oil's 230°C smoke point and neutral flavor profile that preserves end-product taste integrity.
- GB/T 1536 standards:China's SAMR enforces progressively tighter quality and labeling requirements that accelerate facility modernization and consolidate supply around certified producers capable of meeting contaminant limits.
Market Restraints
- Seed price volatility:Australian canola seed costs fluctuate with La Niña-driven yield variability, squeezing crusher margins and forcing pass-through pricing that erodes food manufacturer contract stability.
- Crushing concentration:Eastern Chinese provinces and India's Punjab-Haryana belt host disproportionate processing capacity, creating geographic supply vulnerability during monsoon logistics disruptions or regional lockdowns.
- Soybean oil substitution:South American soybean oil imports undercut rapeseed pricing in bulk food service channels, particularly where flavor neutrality matters less than cost minimization.
Strategic Opportunities
- Vietnam food service:Underpenetrated central and northern provinces lack dedicated rapeseed distribution infrastructure, presenting first-mover advantage for port-advantaged suppliers establishing Ho Chi Minh City-Da Nang distribution corridors.
- Cosmetic emollient base:South Korean and Japanese formulators seek high-oleic rapeseed derivatives for K-beauty and pharmaceutical topical applications, commanding premium positioning outside commodity edible oil channels.
- FSSAI fortification mandates:India's mandatory vitamin A and D enrichment creates technical service partnerships between oil refiners and premix suppliers, locking in multi-year supply contracts with institutional buyers.
Industry Challenges
- Refinery technician scarcity:Deodorization and winterization process expertise concentrates among aging workforces in Chinese state-owned enterprises, constraining new facility commissioning across emerging Southeast Asian crush sites.
- Organic certification timelines:Japan's JAS and South Korea's organic equivalency recognition requires 36-month field history documentation, delaying premium product launches and tying up working capital in transition-phase inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Rapeseed Oil Market |
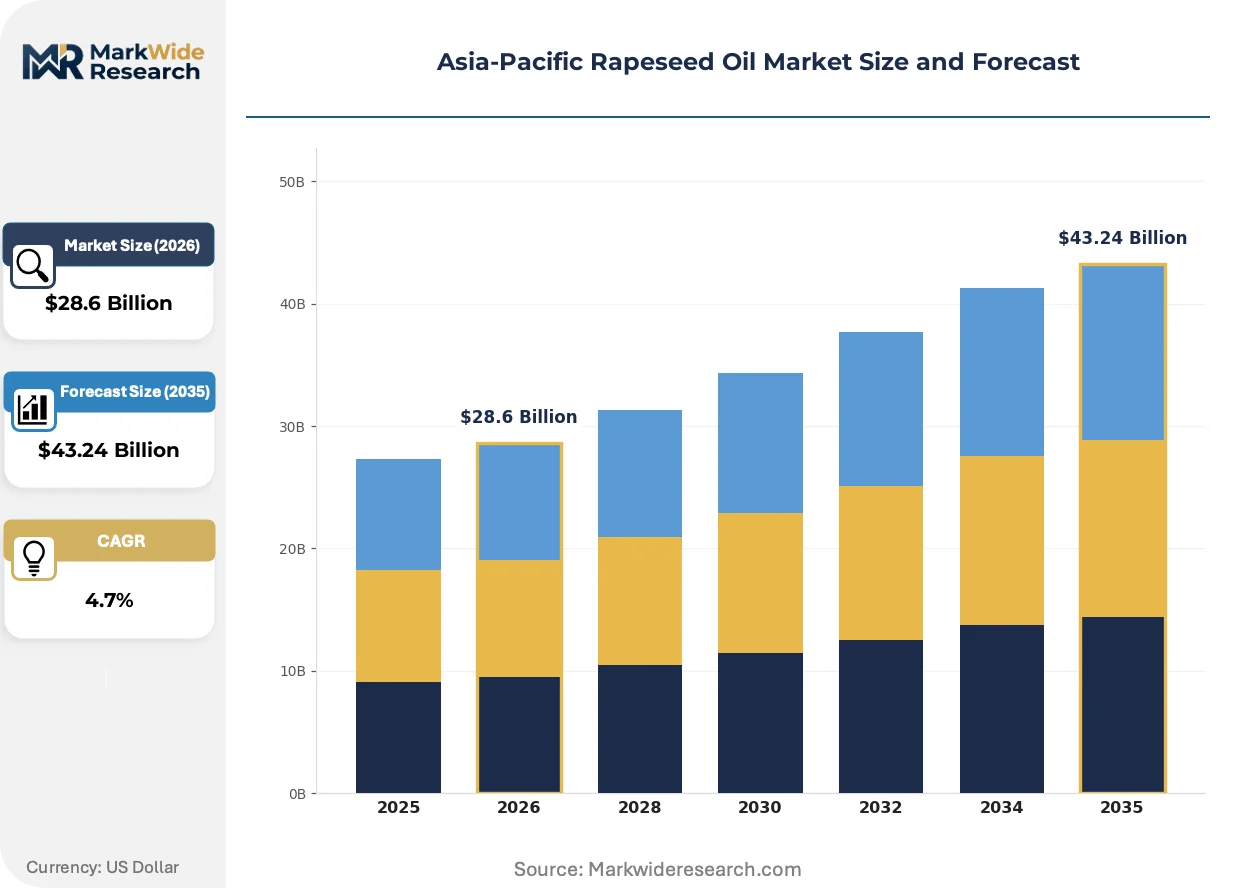
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Food Industry, Cosmetics, Biofuels, Animal Feed Product Type: Refined Oil, Crude Oil, Organic Oil, Blended Oil Distribution Channel: Supermarkets, Online Retail, Wholesale, Direct Sales Packaging Type: Bottles, Cans, Tetra Packs, Bulk Packaging |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Bunge Limited, Louis Dreyfus Company, ConAgra Foods Inc, Wilmar International Ltd, COFCO Group, Thai Vegetable Oil Public Co., Ltd., Ola Oils, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Rapeseed Oil Market Evolving Landscape
Physical and chemical refining process improvements are compressing operational expenditure while regulatory pressure on trans-fat content accelerates formulation reformulation across Asia-Pacific food manufacturing.
Membrane filtration systems for degumming and bleaching are rendering obsolete traditional acid-neutralization and bleaching earth-intensive processes. Malaysian and Indonesian integrated palm-rapeseed refiners deploy ceramic membrane arrays that cut water consumption and solid waste generation. This technology is rendering obsolete legacy caustic refining configurations that dominated twentieth-century plant design.
China's SAMR enforcement of GB 28050 nutrition labeling rules tightens trans-fat disclosure requirements for prepackaged foods. Reformulation pressure cascades to oil suppliers demanding lower-linolenic acid rapeseed varieties. Food manufacturers in Shanghai and Guangzhou accelerate high-oleic low-linolenic (HOLL) oil adoption to preempt regulatory non-compliance and consumer rejection.
Consolidated procurement by Southeast Asian quick-service restaurant chains compresses supplier bases and extends contract durations. Central kitchen operators in Bangkok and Jakarta negotiate direct refinery relationships, bypassing traditional wholesale intermediaries. Thailand and Indonesia exhibit the most visible channel restructuring as multinational food service brands impose supplier audit and traceability requirements that smaller traders cannot satisfy.
Asia-Pacific Rapeseed Oil Market Segmentation
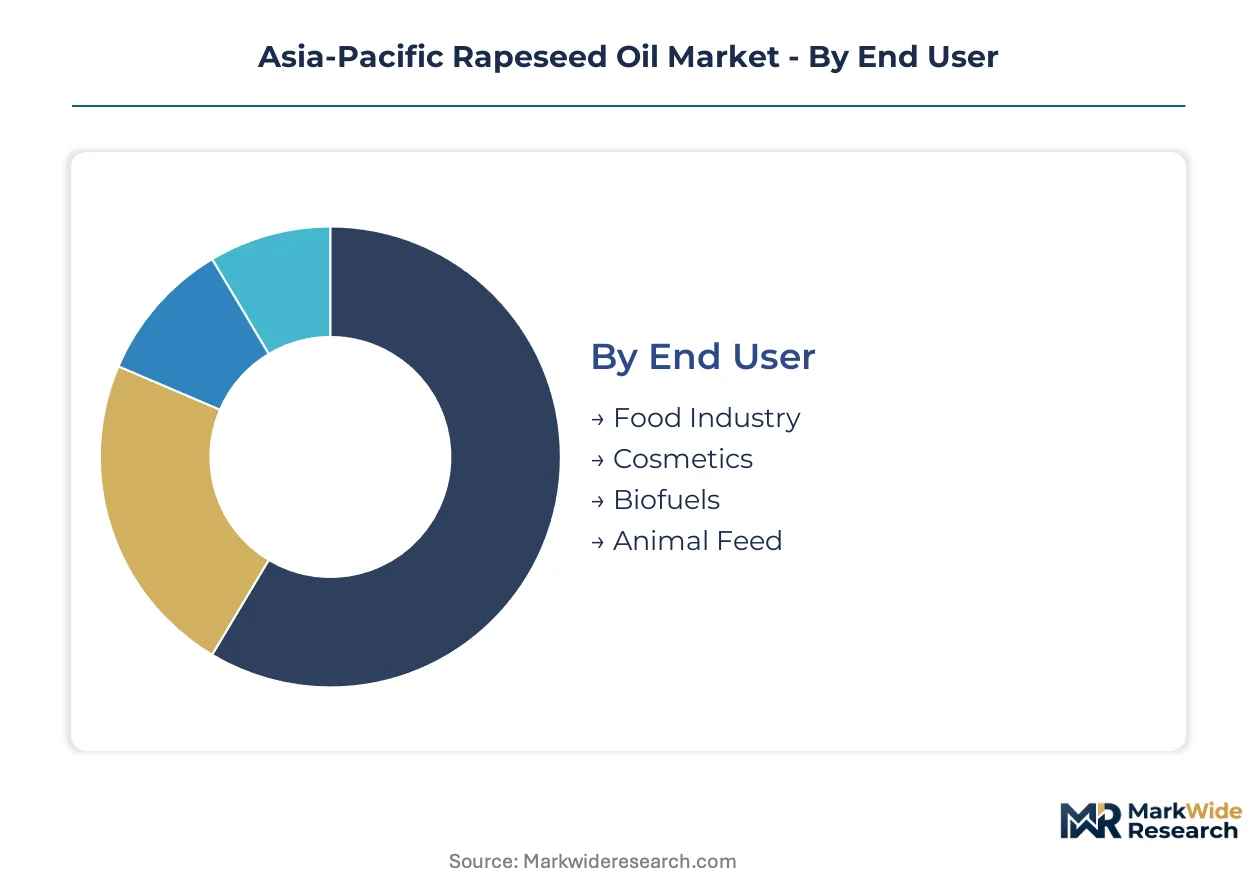
Segmentation across the Asia-Pacific rapeseed oil market reveals how product specifications, channel structures, and end-use requirements fragment procurement patterns. Buyers in food manufacturing, biodiesel production, and cosmetics formulation each impose distinct quality, volume, and certification demands that reshape supplier positioning.
End User:
Application intensity spans commodity-scale food processing to specialized cosmetic formulation, with each use case imposing distinct fatty acid profiles and purity thresholds.
- Food Industry:High-temperature frying and bakery applications in China and India absorb the largest volume flows. The refined oil's 230°C smoke point and neutral flavor preserve end-product integrity across extended production runs.
- Biofuels:Indonesia's B35 mandate and prospective B40 escalation redirect crush capacity toward fuel blending. This segment absorbs regional seed supply that might otherwise enter edible channels, tightening food-grade availability.
- Cosmetics:South Korean and Japanese formulators source high-oleic derivatives for K-beauty emollient bases.
- Animal Feed:Rapeseed meal byproducts from crushing operations supply protein inputs to livestock operations across Australia's dairy belt.
Established volume favors food industry absorption; emerging adoption favors biofuels feedstock conversion.
Product Type:
Processing depth determines shelf stability, flavor neutrality, and price positioning across buyer categories.
- Refined Oil:Deodorization and winterization remove phospholipids and free fatty acids, yielding extended storage life. Chinese food processors in Shanghai and Guangzhou specify this grade for consistent frying performance.
- Organic Oil:Japan's JAS and South Korea's organic equivalency recognition commands 36-month field history documentation. Urban health-conscious consumers in Seoul and Tokyo pay premium positioning for certified product lines.
- Crude Oil:Crushers in India's Punjab-Haryana belt ship minimally processed volumes to regional refiners.
- Blended Oil:Formulators mix rapeseed with soybean or palm fractions to achieve target price-performance ratios.
Refined oil dominates procurement tonnage; organic certification captures margin expansion.
Distribution Channel:
Channel selection reflects buyer scale, urgency requirements, and traceability needs across fragmented supply networks.
- Supermarkets:Retail shelf placement in Bangkok and Jakarta concentrates on 1-5 liter bottles for household cooking. Centralized distribution through modern trade formats reduces price volatility exposure for urban consumers.
- Wholesale:Food manufacturers in Vietnam's central provinces source through Ho Chi Minh City intermediaries. Bulk procurement contracts lock in quarterly pricing for restaurant chains and institutional kitchens.
- Online Retail:E-commerce platforms in South Korea and Japan deliver specialty organic grades to health-focused households.
- Direct Sales:Crush facilities in eastern China provinces contract directly with large-scale food processors.
Wholesale channels move the heaviest volume; online retail is climbing the fastest.
Packaging Type:
Container selection aligns with use-case scale, shelf-life requirements, and logistics constraints across diverse buyer segments.
- Bulk Packaging:Flexitanks and ISO tank containers serve biodiesel blenders in Indonesia and Malaysia. Direct refinery-to-facility delivery eliminates intermediate handling costs for fuel producers.
- Bottles:PET and glass formats dominate household retail across Southeast Asian supermarkets. One to five liter sizes balance purchase frequency with storage practicality for urban apartments.
- Cans:Metal containers protect against oxidation in tropical humidity for export shipments.
- Tetra Packs:Aseptic cartons extend unopened shelf life for premium organic lines in Japanese convenience retail.
Bulk packaging commands industrial procurement; bottle formats anchor consumer-facing distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's deep-water container terminals and the Yangtze River inland waterway network anchor Asia-Pacific rapeseed oil trade flows. These multimodal corridors connect crushing facilities in eastern China to refining clusters along the coast and onward to Southeast Asian markets.
China
Food processors in Shanghai and Guangzhou expand procurement for high-temperature frying applications. SAMR enforces GB/T 1536 quality standards that tighten contaminant limits and accelerate facility consolidation. Crushing capacity clusters in Jiangsu and Zhejiang provinces where integrated refiners supply packaged oil to domestic retail chains.
India
Punjab-Haryana belt crushers serve bakery and snack manufacturers across Delhi-NCR and Mumbai. FSSAI mandates vitamin A and D fortification that reshapes refinery formulation partnerships with premix suppliers. Port-based import terminals in Mundra and Kandla handle Australian canola seed arrivals during domestic off-seasons.
Indonesia
Biodiesel blenders in Java and Sumatra absorb crush volumes under the B35 mandate with prospective B40 escalation. The Ministry of Energy and Mineral Resources enforces blending quotas that redirect feedstock away from edible channels. Integrated palm-rapeseed refiners in Surabaya optimize multi-feedstock flexibility for fuel production.
Japan
Tokyo and Osaka metropolitan consumers drive organic oil demand through JAS-certified retail channels. METI oversees import quality frameworks that govern health claim substantiation for functional oil products. Kobe port facilities handle bulk arrivals for downstream cosmetic emollient formulation in Osaka industrial zones.
Australia
Canola seed exporters in Western Australia and New South Wales supply Asian crush markets through Fremantle and Newcastle port terminals. FSANZ and TGA frameworks govern export certification and contaminant testing protocols. La Niña-driven yield variability in the Wheatbelt region creates pricing volatility that transmits to Asian contract negotiations.
Asia-Pacific Rapeseed Oil Market Competitive Landscape
On the supply side, the industry is moderately consolidated around integrated agribusiness conglomerates with origination-to-refinery footprints. Tier-one traders crush and refine at scale across multiple geographies while regional specialists anchor domestic procurement networks. Strategic archetypes include port-advantaged originators, integrated crush-refine operators, and niche organic certifiers. Competitive moves center on backward integration into seed origination and geographic expansion through distribution corridor establishment.
Among Singapore-based integrated operators, Wilmar International Ltd exemplifies the multi-commodity refiner archetype with integrated crushing and refining footprints spanning Malaysia and Indonesia. Bunge Limited represents the port-advantaged originator model through Australian export terminal access. Thai Vegetable Oil Public Co., Ltd. anchors domestic Thai demand with specialized refined product lines, occupying a position within Southeast Asian specialty oil formulation.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Bunge Limited |
| Louis Dreyfus Company |
| ConAgra Foods Inc |
| Wilmar International Ltd |
| COFCO Group |
| Thai Vegetable Oil Public Co., Ltd. |
| Ola Oils |
| Others |
Value Network & Pricing Analysis
La Niña-driven yield variability in Australia's Wheatbelt determines both the spread between contract and spot pricing tiers and the geographic routing of seed shipments through Asian crush corridors. This climate risk compresses crusher margins during drought cycles while forcing food manufacturers toward longer-term offtake agreements that lock in supply security at premium pricing.
Pricing Analysis
Volume-discount tiering separates long-term contract buyers from spot market purchasers across Indonesian and Malaysian crush facilities. Price differentiation hinges on JAS organic certification status and quarterly volume commitments above 5,000 metric tons. Cost compression in standard refined grades is intensifying because South American soybean oil undercuts rapeseed in bulk food service channels. Quick-service restaurant chains exhibit the highest price sensitivity, while cosmetic formulators in Osaka and Seoul accept substantial premiums for high-oleic derivatives.
Supply Chain Analysis
Upstream feedstock flows draw from Australian canola seed exports, Canadian prairie harvests, and domestic Chinese production in Jiangsu and Zhejiang provinces. Crush operations rest on hexane solvent extraction equipment, degumming centrifuges, and nickel catalyst hydrogenation units. Single-source vulnerability concentrates in eastern Chinese provinces where monsoon logistics disruptions strand seed deliveries. Distribution runs through Ho Chi Minh City and Jakarta port terminals for Southeast Asian food manufacturers, with direct refinery relationships bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across end-use specifications—food-grade contaminant limits, biodiesel feedstock purity, and cosmetic-grade fatty acid profiles—creates defendable niches for specialists who anchor in one certification tier rather than competing across all three.
For Market Incumbents: Build regulatory compliance moats around FSSAI fortification partnerships and GB/T 1536 certification infrastructure that smaller crushers cannot replicate. Integrate backward into Australian canola origination through Fremantle port terminal access to neutralize La Niña price volatility. Lock in multi-year technical service contracts with Indian premix suppliers that embed refiners into institutional buyer supply chains. For New Entrants and Emerging Players: Pursue underpenetrated central and northern Vietnamese provinces lacking dedicated rapeseed distribution infrastructure, establishing Da Nang corridor access before port-advantaged incumbents consolidate routes. Target cosmetic emollient formulation in South Korean K-beauty supply chains where premium positioning exceeds commodity edible oil margins by substantial multiples. Lead with JAS organic certification to capture Tokyo and Seoul health-conscious household segments. For Investors and Strategic Acquirers: Indonesia's prospective B40 biodiesel escalation reshapes the acquisition landscape by redirecting crush capacity toward fuel blending and tightening food-grade availability. Long-term viability favors integrated palm-rapeseed refiners with multi-feedstock flexibility across Surabaya and Java processing clusters. Acquire targets with established port-advantaged origination in Australia and demonstrated compliance with China's SAMR contaminant limits. Watch for B40 implementation announcements as the signal indicating accelerated feedstock competition between edible and fuel channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Origination | Australian port terminal access neutralizes La Niña-driven yield volatility for Asian crush operations. |
| FSSAI Fortification Partnership | Technical service contracts with Indian premix suppliers embed refiners into institutional buyer supply chains. |
| Multi-Feedstock Refinery Configuration | Integrated palm-rapeseed facilities in Surabaya optimize flexibility between edible oil and biodiesel production. |
| JAS Organic Certification Investment | Thirty-six-month field history documentation unlocks premium positioning in Tokyo and Seoul retail channels. |
| Direct Refinery Relationship Expansion | Bypassing Ho Chi Minh City intermediaries captures margin from Vietnamese quick-service restaurant procurement consolidation. |
Research Methodology
The analysis maps refined oil, organic certified, crude, and blended product categories, each validated through crush facility managers, food manufacturer procurement leads, biodiesel blender technical directors, and cosmetic formulator R&D heads. Primary interview findings triangulate against customs trade records, FSSAI fortification compliance databases, GB standards enforcement bulletins, and Indonesian Ministry of Energy blending mandate disclosures. Bottom-up volume builds from named crush facility capacities aggregate with top-down trade flow verification.
Assumptions hold Indonesia's B35 mandate enforcement constant while modeling prospective B40 escalation as a sensitivity scenario across the projection horizon. Segmentation dimensions span processing depth, end-use application intensity, distribution channel structure, and packaging format. CAGRs derive from compound growth trajectory analysis applied to historical trade flow baselines. Forecast inputs incorporate canola seed yield variability patterns and regulatory compliance cost trajectories for contaminant limit tightening.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated palm oil conglomerates or Australian export terminal operators would shift outcomes substantially. Cross-checking against Indonesian Ministry of Energy biodiesel blending quota announcements and FSSAI fortification enforcement intensity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
North America Aloe Vera Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Europe Alfalfa Hay Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Cage Free Eggs Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market