
 Netherlands Commercial Greenhouse Market | 2026-2036
Netherlands Commercial Greenhouse Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Commercial Greenhouse Market Insights
CE marking under the EU Machinery Directive is collapsing the qualification cycle for imported greenhouse automation equipment, compressing vendor entry timelines from months to weeks. Dalsem B.V. leverages its in-house steel fabrication to control structural component costs across Dutch turnkey projects. Certhon B.V. anchors its competitive stance through deep specialization in semi-closed greenhouse architectures that optimize energy recovery. Priva B.V. dominates climate control software integration, extending its platform from sensor networks to cloud-based crop management dashboards.
Netherlands commercial greenhouse infrastructure comprises steel-framed, glass-clad enclosures engineered to maintain precise microclimates through integrated heating, cooling, and ventilation subsystems, typically achieving 85-95% light transmission through diffuse glass coatings. These structures serve the primary commercial purpose of enabling controlled-environment agriculture for high-value crop production regardless of external weather conditions. Hydroponic systems lead technology deployment among Dutch growers due to water-use efficiency mandates, while LED lighting segments capture expanding margin pools as electricity costs reshape grow-light economics. Vegetable production anchors application demand through tomato and cucumber cultivation, though floral cultivation segments sustain premium pricing through specialized climate protocols for orchids and roses.
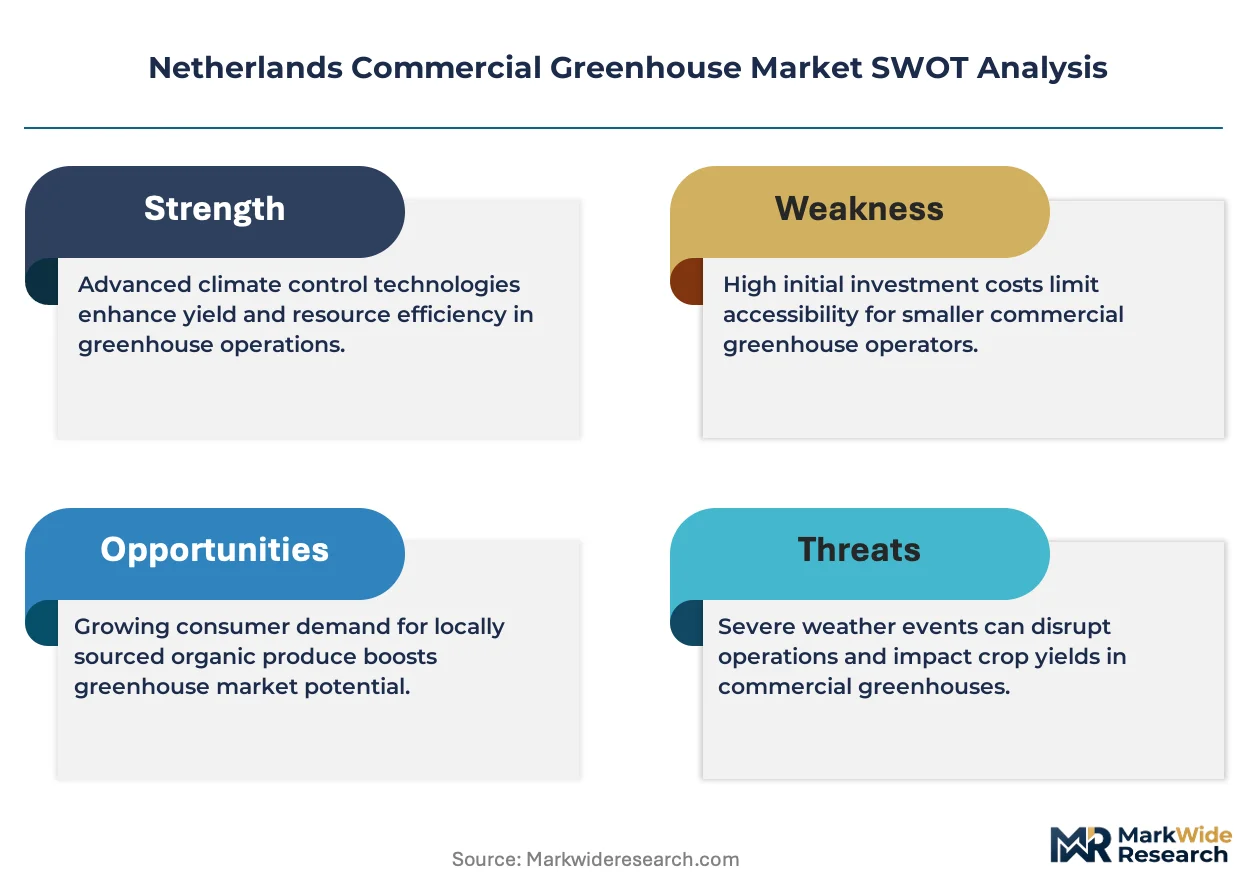
The Dutch Ministry of Agriculture enforces Plant Protection Product regulations that restrict chemical residue thresholds, pushing growers toward bio-pesticide integration and biological control systems. BIS-equivalent standards through KIWA certification govern structural wind-load requirements for glasshouse frameworks in coastal provinces exposed to North Sea storm patterns. Stakeholders must monitor whether proposed EU Soil Monitoring Directive amendments will mandate additional substrate reporting obligations for soil-based operations.
Market Dynamics
Stringent nitrogen reduction mandates under the Dutch PAS framework are forcing wholesale migration toward closed-loop cultivation systems, compressing capital deployment timelines and favoring vendors with turnkey integration capabilities.
Growth Catalysts
- Fresh produce retailer consolidation:Supermarket chains demand year-round supply reliability, driving investment in climate-controlled infrastructure that insulates against seasonal volatility.
- EU F-Gas Regulation phase-down:Refrigerant restrictions accelerate heat pump adoption in greenhouse climate systems, creating retrofit demand across Westland clusters.
- Hydroponic water efficiency:Substrate-based cultivation cuts water consumption versus soil methods, aligning with municipal extraction limits in drought-prone southern provinces.
Market Restraints
- Steel price volatility:Structural framework costs fluctuate with global scrap metal markets, squeezing margins for turnkey greenhouse constructors.
- Single-source LED dependency:Grow-light semiconductor supply concentrates among East Asian foundries, exposing Dutch operators to shipping disruptions.
- Glass thermal conductivity limits:Conventional glazing materials cap energy recovery efficiency regardless of HVAC sophistication.
Strategic Opportunities
- Biological control integration:Beneficial insect propagation services unlock recurring revenue streams beyond hardware sales.
- Westland cluster densification:Proximity to Rotterdam logistics infrastructure enables same-day fresh produce distribution to UK and German retail buyers.
- EU Soil Monitoring Directive alignment:Substrate reporting mandates favor operations with established data collection infrastructure.
Industry Challenges
- Climate engineering talent scarcity:Horticultural universities graduate insufficient technicians to operate integrated sensor-irrigation-HVAC systems.
- CE marking timeline compression:Machinery Directive compliance cycles strain smaller automation vendors lacking dedicated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Commercial Greenhouse Market |
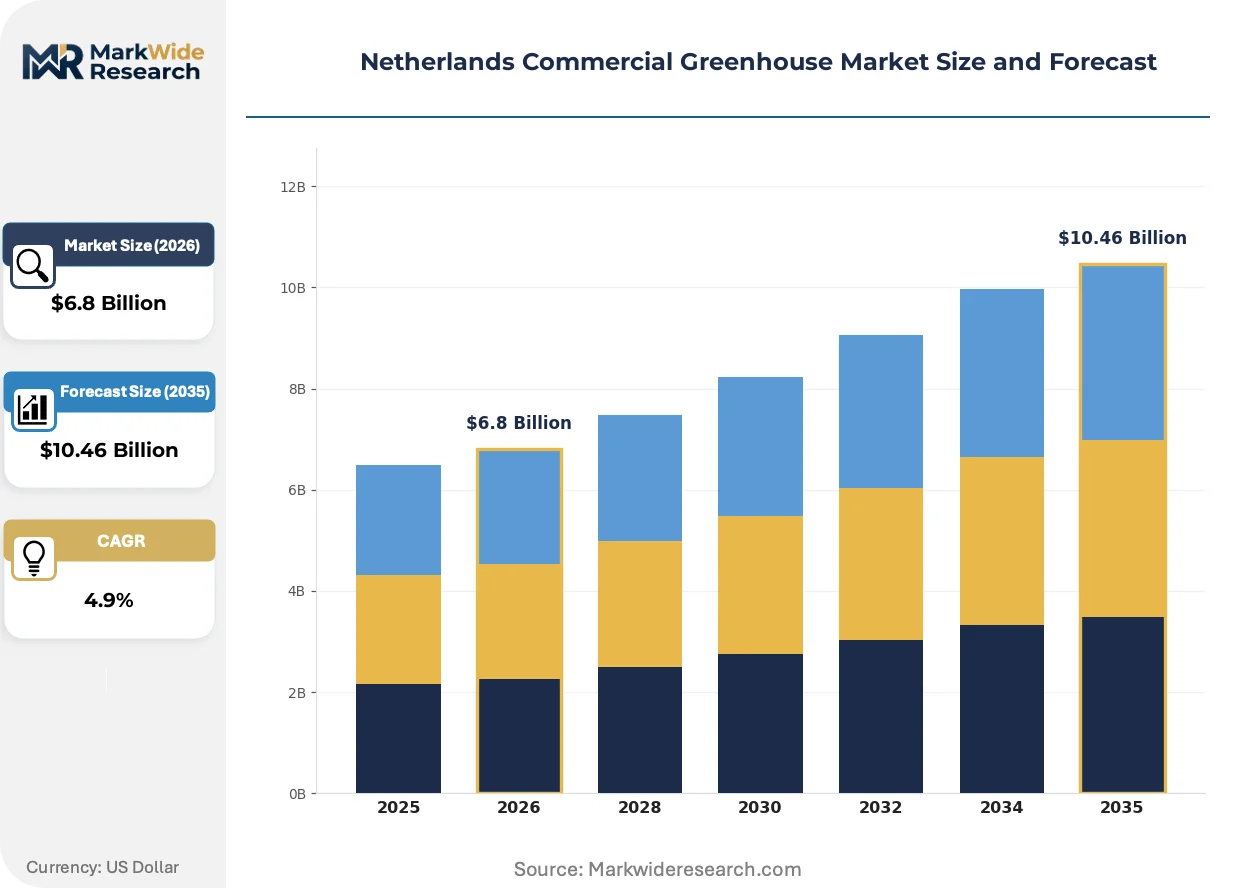
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroponics, Aeroponics, Soil-based, Bio-pesticides Technology: LED Lighting, Climate Control Systems, Hydroponic Systems, Automation Solutions End User: Retailers, Wholesalers, Distributors, Exporters Application: Vegetable Production, Floral Cultivation, Herbs Growing, Fruit Production |
| Companies Covered | Dalsem B.V., Certhon B.V., DutchGreenhouses B.V., Havecon Horticulture Projects B.V., LOGIQS B.V., Priva B.V., Hoogendoorn Growth Management B.V., Van der Hoeven Horticultural Projects B.V., Gakon Netafim, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Commercial Greenhouse Market Trends and Innovations
Automation architectures are fragmenting into modular subsystems that growers assemble rather than purchasing monolithic turnkey installations, reshaping vendor competitive dynamics toward interoperability dominance.
Diffuse glass coating technology is decomposing the historical trade-off between light transmission volume and distribution uniformity. Westland tomato operations now specify 90% transmission with 75% diffusion ratios, enabling deeper canopy penetration without scorching upper leaves. This specification shift is compressing premium pricing for conventional clear-glass suppliers.
The Dutch Ministry of Agriculture's Plant Protection Product residue thresholds are tightening chemical input allowances. Growers respond by retrofitting biological control infrastructure—banker plant systems and predatory mite propagation chambers—into existing greenhouse footprints. Floral cultivation segments face the steepest compliance costs due to rose and orchid sensitivity to biological agent compatibility.
Retailer procurement teams now contract directly with greenhouse cooperatives for fixed-volume, fixed-price produce supply agreements. Traditional auction-based distribution through FloraHolland declines as Albert Heijn and Jumbo Supermarkten seek supply chain transparency. This channel compression is most advanced in vine tomato categories where traceability requirements are strictest.
Netherlands Commercial Greenhouse Market Segmentation
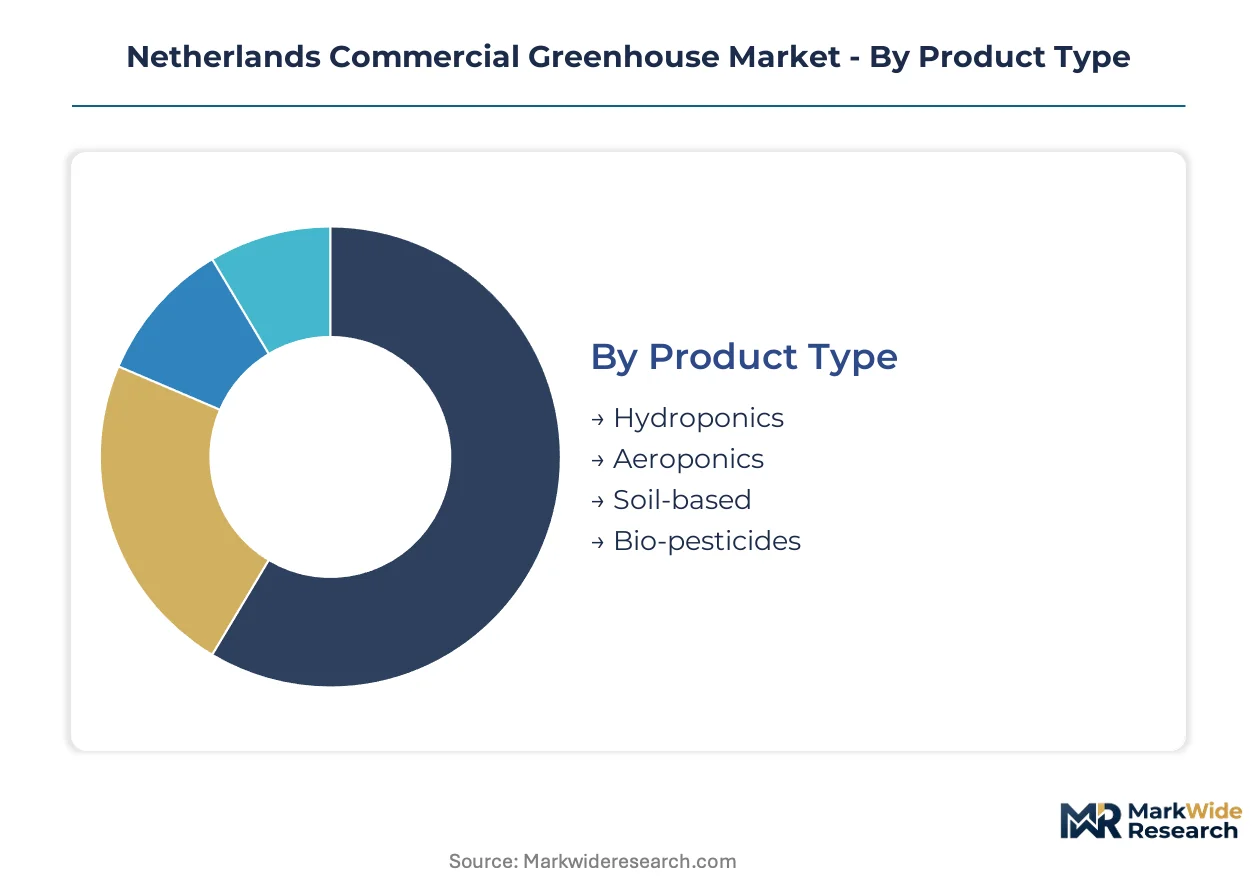
Segmentation in the Netherlands commercial greenhouse market reveals how regulatory pressures and retailer procurement patterns concentrate investment across specific technology configurations and cultivation methods. Understanding these divisions exposes where capital deployment aligns with PAS nitrogen mandates and EU F-Gas phase-down timelines.
Product Type:
PAS framework nitrogen reduction thresholds differentiate cultivation system compliance burdens and capital intensity requirements across Dutch greenhouse operations.
- Hydroponics:Substrate-based systems circulate nutrient solutions through inert growing media, achieving closed-loop water recirculation. Westland tomato cooperatives concentrate demand here as municipal extraction limits tighten in drought-prone southern provinces, with compliance costs favoring operations with existing infrastructure.
- Aeroponics:Mist-based nutrient delivery suspends root systems in controlled environments, maximizing oxygen exposure and minimizing water use. Emerging adoption clusters around high-value herb operations in Noord-Brabant where input precision justifies capital intensity, though technical complexity limits deployment scale.
- Soil-based:Traditional substrate cultivation faces escalating compliance costs under proposed EU Soil Monitoring Directive reporting obligations.
- Bio-pesticides:Biological control agents replace synthetic chemical inputs to meet Plant Protection Product residue thresholds.
Established volume favors Hydroponics; emerging adoption favors Aeroponics.
Technology:
Cost tier stratification separates premium integrated platforms from modular point solutions as grower capital constraints reshape procurement patterns.
- LED Lighting:Semiconductor-based grow-lights enable spectral tuning for crop-specific photomorphogenic responses. Electricity cost pressures concentrate retrofit demand in Westland clusters where legacy high-pressure sodium installations dominate, though East Asian foundry concentration creates supply vulnerability.
- Climate Control Systems:Integrated HVAC platforms manage temperature, humidity, and CO2 enrichment through sensor-network feedback loops. Premium pricing concentrates among vendors offering cloud-based crop management dashboards that integrate with Priva software architectures.
- Hydroponic Systems:Nutrient delivery infrastructure spans drip irrigation to deep water culture configurations.
- Automation Solutions:Robotic harvesting and transplanting equipment addresses labor scarcity in dense greenhouse clusters.
LED Lighting commands the steepest expansion trajectory; Climate Control Systems anchor recurring revenue streams.
End User:
Customer type fragmentation tracks channel compression as procurement authority shifts from traditional auction mechanisms to direct retail contracting.
- Retailers:Supermarket chains including Albert Heijn and Jumbo Supermarkten negotiate fixed-volume, fixed-price produce agreements directly with greenhouse cooperatives. Traceability requirements concentrate investment in climate-controlled infrastructure that insulates against seasonal volatility.
- Wholesalers:Traditional intermediaries face margin compression as retailer procurement teams internalize sourcing relationships.
- Distributors:Logistics specialists manage cold-chain integrity for same-day fresh produce delivery to UK and German buyers.
- Exporters:Rotterdam-proximate operations leverage port infrastructure for continental European market access.
Retailer direct contracting gains share fastest; Wholesaler intermediary roles face structural decline.
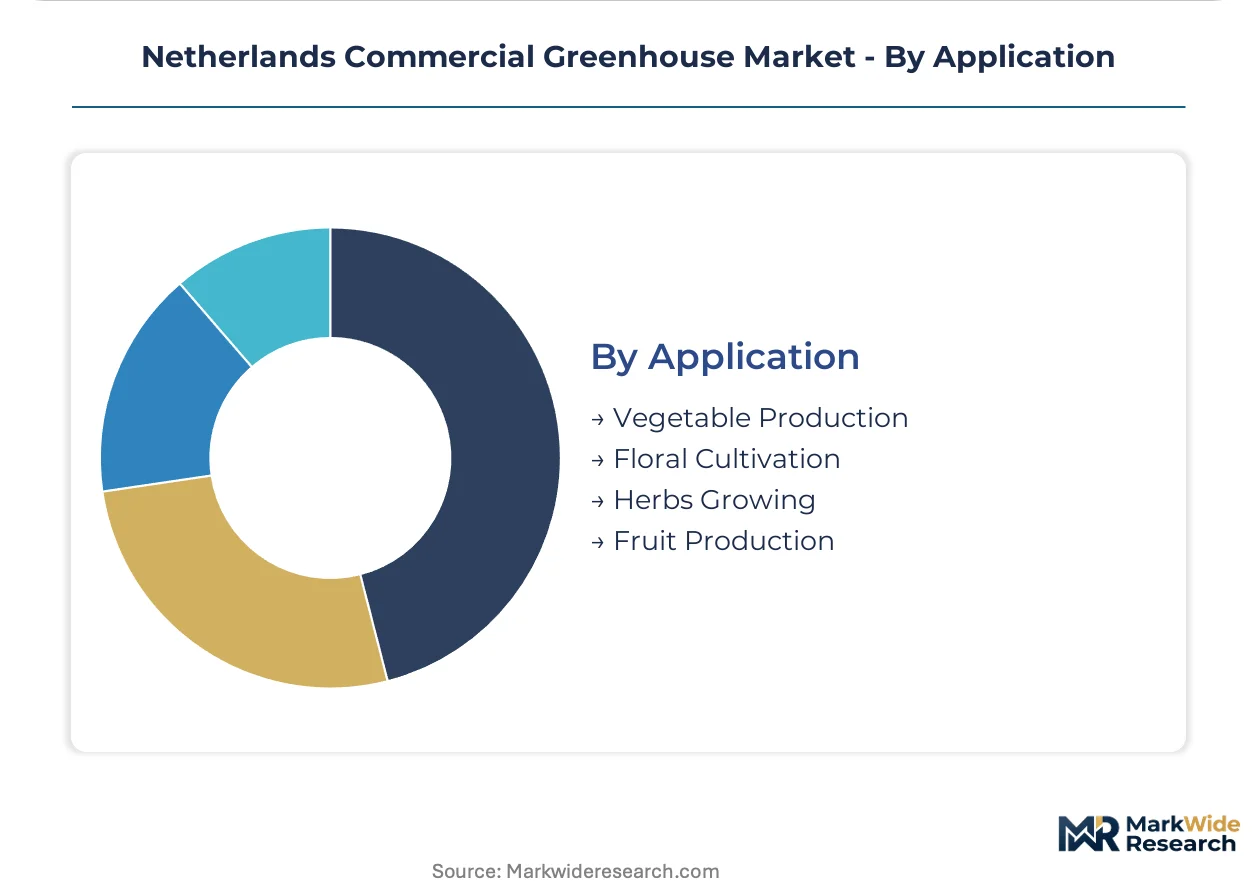
Application:
Margin differentiation separates commodity vegetable production from premium floral cultivation where specialized climate protocols sustain pricing power.
- Vegetable Production:Tomato and cucumber cultivation anchors volume demand through standardized climate protocols. Westland operations concentrate here, with vine tomato categories facing strictest traceability requirements from retailer procurement teams.
- Floral Cultivation:Rose and orchid production requires precise humidity and temperature management for bud development and color fixation. Premium pricing sustains investment in biological control infrastructure despite steeper compliance costs from agent compatibility constraints.
- Herbs Growing:Basil and leafy green operations favor compact system footprints for rapid crop turnover.
- Fruit Production:Strawberry and soft fruit cultivation expands under protected environments.
Vegetable Production anchors absolute volume; Floral Cultivation sustains margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam port complex anchors Dutch greenhouse logistics, enabling same-day produce distribution to UK and German retail buyers through integrated cold-chain infrastructure.
Westland Municipality
Fresh produce retailer consolidation drives capital deployment into climate-controlled infrastructure across the densest greenhouse cluster nationwide. The Dutch Ministry of Agriculture enforces PAS framework nitrogen reduction thresholds that mandate closed-loop system migration. Naaldwijk and Monster host the highest concentration of tomato and cucumber operations, with cooperatives retrofitting biological control infrastructure to meet residue limits.
North Brabant
High-value herb cultivation concentrates in compact aeroponic systems for rapid crop turnover. The EU F-Gas Regulation phase-down accelerates heat pump adoption in greenhouse climate systems. Eindhoven-proximate operations leverage technical university partnerships for automation integration, though technical complexity limits deployment scale.
Limburg
Floral cultivation segments sustain premium pricing through specialized climate protocols for orchids and roses. Plant Protection Product regulations restrict chemical residue thresholds, pushing growers toward bio-pesticide integration. Venlo greenhouse cooperatives face steepest compliance costs from biological agent compatibility constraints.
Flevoland
Vegetable production anchors volume demand through standardized climate protocols for vine tomatoes. Municipal extraction limits in drought-prone southern provinces favor hydroponic water efficiency investments. Almere operations concentrate substrate-based cultivation achieving closed-loop water recirculation.
Groningen
Emerging greenhouse development clusters around geothermal heating infrastructure for energy cost reduction. KIWA certification governs structural wind-load requirements for glasshouse frameworks exposed to North Sea storm patterns. Northern Netherlands operations benefit from lower land costs while building distribution relationships with German wholesale buyers.
Netherlands Commercial Greenhouse Market Competitive Landscape
Listed leaders compete with private specialists across integrated system delivery, with family-owned fabricators holding structural share in steel-framed greenhouse construction. The vendor base separates into turnkey integrators, component specialists, and software platform providers. Three archetypes dominate: steel fabricators controlling structural costs, climate engineers optimizing energy recovery, and automation vendors compressing regulatory compliance timelines. Competitive moves concentrate on backward integration into captive steel supply and cloud-based platform extension.
Within the turnkey integrator tier, Dalsem B.V. and Certhon B.V. exemplify divergent specialization strategies, with the former representing in-house fabrication control and the latter anchoring semi-closed architecture expertise. Among software-centric operators, Priva B.V. occupies a position as climate control platform standard-setter, extending sensor-network integration into crop management dashboards. These three entities sit within distinct competitive vectors—structural cost, energy engineering, and data infrastructure—rather than direct overlap.
| Leading Market Players |
|---|
| Dalsem B.V. |
| Certhon B.V. |
| DutchGreenhouses B.V. |
| Havecon Horticulture Projects B.V. |
| LOGIQS B.V. |
| Priva B.V. |
| Hoogendoorn Growth Management B.V. |
| Van der Hoeven Horticultural Projects B.V. |
| Gakon Netafim |
| Others |
Pricing and Supply Chain Analysis
Sixteen-week lead times for East Asian LED semiconductor shipments compress Dutch greenhouse operators' inventory buffers to under thirty days, tethering pricing power to foundry capacity allocation rather than local demand conditions. This supply-side constraint concentrates margin pressure on retrofit projects where spectral-tuning specifications lock buyers into single-source dependencies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates turnkey integrators with captive steel fabrication from modular component vendors and bare-hardware suppliers. Premium tiers capture value through CE-marked automation bundles and cloud-based climate dashboard integration, while economy tiers compete on structural steel cost per square meter. Pricing pressure stems from global scrap metal volatility squeezing framework margins. Retailer procurement teams exhibit lowest price sensitivity due to traceability-driven specification requirements, whereas independent growers face acute cost pressure on HVAC retrofits.
Supply Chain Analysis
Rotterdam port congestion during peak horticultural equipment import windows amplifies landed cost variability for Chinese steel components and Taiwanese LED modules. Dutch greenhouse construction draws from German structural steel, Chinese semiconductor foundries, and Belgian glass coating specialists. Single-source vulnerability concentrates in East Asian grow-light semiconductor supply. Distribution runs through Westland cooperative procurement consortia coordinating synchronized equipment upgrades across clustered operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as Priva's climate control software architecture becomes the interoperability standard for third-party sensor and actuator integration. This ecosystem shift rewards vendors who build modular subsystems around open API specifications rather than monolithic turnkey offerings.
For Market Incumbents: Fortify backward integration into captive steel supply to offset scrap metal volatility squeezing Dalsem's structural cost advantage. Deepen certification investment in KIWA wind-load standards for coastal North Sea exposures where storm frequency intensifies replacement demand. Defend against modular subsystem vendors by extending cloud platform subscription bundles that lock growers into recurring revenue relationships.
For New Entrants and Emerging Players: Differentiate on biological control integration services targeting Limburg rose cooperatives facing steepest Plant Protection Product compliance costs. Penetrate the aeroponic herb segment in Noord-Brabant where technical complexity limits incumbent scale. Pursue direct contracting with Albert Heijn procurement teams seeking supply chain transparency bypassing traditional FloraHolland auction channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned steel fabricators lacking climate engineering software capabilities but controlling Westland installation relationships. Long-term viability hinges on PAS nitrogen mandate enforcement sustaining closed-loop system migration. Monitor EU Soil Monitoring Directive amendment progress as the signal indicating substrate reporting infrastructure valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Supply | Captive fabrication capacity insulates Dalsem from global scrap metal price swings. |
| Biological Control Service Launch | Recurring revenue streams unlock margin expansion beyond hardware installation cycles. |
| Cloud Platform API Standardization | Priva's dashboard dominance creates ecosystem lock-in for third-party device vendors. |
| Westland Cooperative Procurement Consortia | Synchronized upgrade cycles concentrate buyer power against equipment suppliers. |
| CE Marking Pre-Certification Investment | Compressed compliance timelines favor vendors with dedicated regulatory affairs functions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Dutch Ministry of Agriculture policy filings, EU F-Gas Regulation implementation guidance, and Westland municipal extraction limit records. Primary interviews engaged greenhouse operations managers, Priva software integration specialists, Certhon climate engineering leads, and Albert Heijn produce procurement directors. Secondary validation drew from KIWA certification databases, FloraHolland auction volume reports, and Rotterdam port customs records. Bottom-up equipment deployment tallies triangulated against top-down sector investment estimates from agricultural lender disbursement data.
Segmentation dimensions modeled span cultivation system type, technology tier, end-user procurement channel, and application crop category across the projection horizon. CAGRs derived from installed base growth rates adjusted for PAS nitrogen mandate compliance deadlines and EU F-Gas heat pump retrofit timelines. Industry-specific forecast inputs incorporate municipal water extraction limit enforcement intensity and retailer direct contracting penetration rates.
Forecasts assume regulatory continuity in Dutch PAS nitrogen reduction thresholds and EU F-Gas phase-down schedules; material policy shifts would require re-modeling capital deployment trajectories. Practitioners should keep alternative scenarios live as EU Soil Monitoring Directive amendment progress and East Asian semiconductor supply stability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Asia-Pacific Artificial Humus Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Elaeis Guineensis Kernel Oil Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Mushroom Cultivation Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Japan Floriculture Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Algeria Agriculture Market
Agriculture and Agri Products
Cut Flower Market