
 North America Compound Feed Market | 2026-2036
North America Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
North America Compound Feed Market Analytics
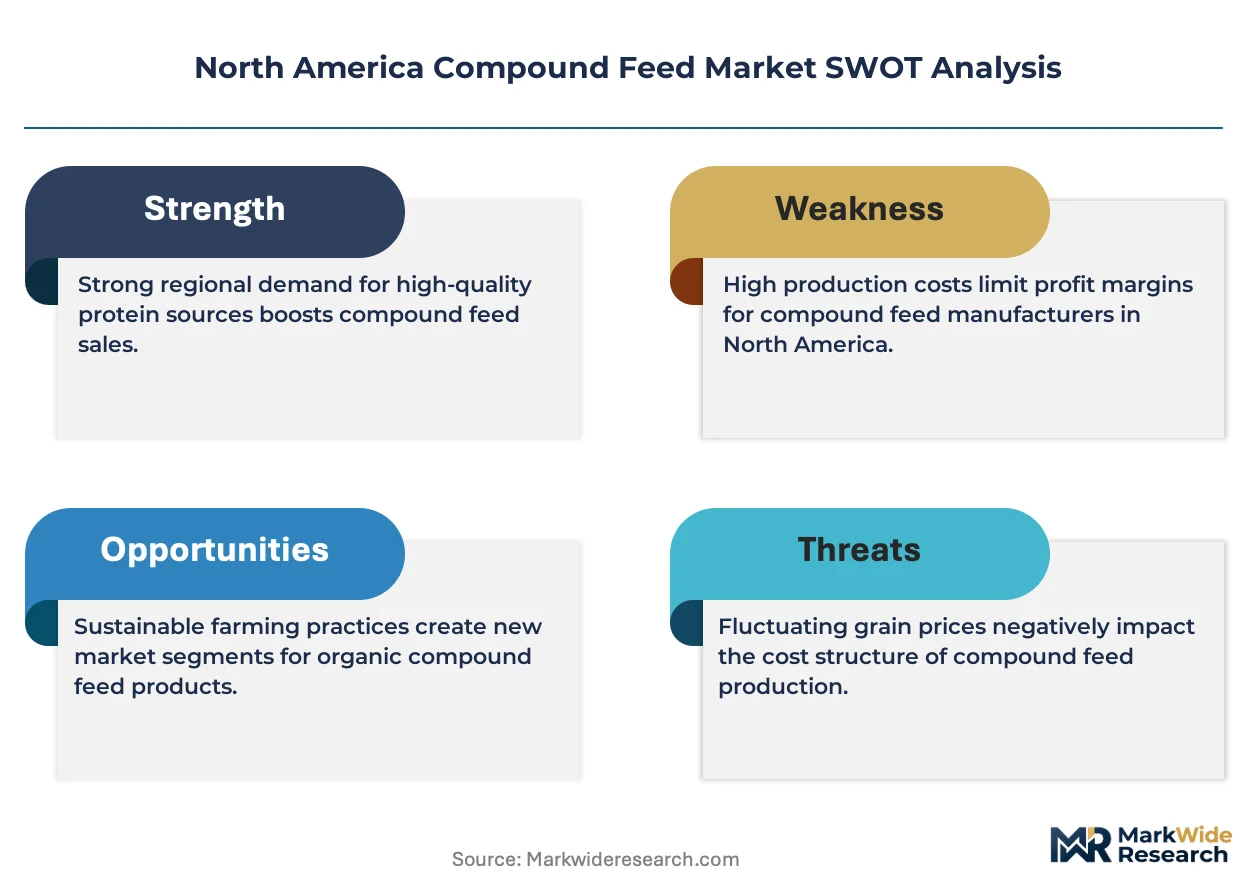
The EPA's revised Clean Water Act enforcement for concentrated animal feeding operations is restructuring compound feed demand across North America by mandating lower phosphorus and nitrogen outputs in manure. Cargill Inc leverages its vertically integrated grain handling network to control input costs across the Upper Midwest. Archer Daniels Midland Company sustains its position through massive corn processing capacity that anchors regional feed ingredient supply. Land O'Lakes Inc differentiates via cooperative ownership structures that lock in dairy farm customer loyalty across Wisconsin and Minnesota.
Compound feed refers to nutritionally complete mixtures formulated from grains, protein meals, vitamins, and minerals, typically processed through pelleting or extrusion to achieve specified crude protein, energy density, and digestibility parameters for targeted livestock species. Poultry feed occupies the largest product type position due to vertically integrated broiler operations concentrated in the southeastern United States. Swine feed represents the fastest-growing category as Iowa and North Carolina operations expand finishing capacity. The feed composition segment sees margin pools concentrating in specialty vitamin and mineral premixes where formulation precision commands premium pricing.
The FDA's Veterinary Feed Directive governs antibiotic usage in medicated feeds, while the USDA's National Organic Program shapes certification requirements for organic livestock feed channels. State-level environmental regulations in California and North Carolina impose additional nutrient management planning obligations on large-scale livestock operations. Stakeholders must monitor evolving EPA water quality standards and FDA guidance on novel feed additives to anticipate formulation shifts that will redefine competitive positioning in ingredient sourcing and premix services.
Market Dynamics
The EPA's revised Clean Water Act enforcement for concentrated animal feeding operations is restructuring compound feed formulation requirements by mandating lower phosphorus and nitrogen outputs in manure, forcing mills to reformulate protein and mineral content.
Growth Catalysts
- Precision Livestock Farming:Sensor-based feeding systems in Wisconsin and Minnesota dairy operations are optimizing feed conversion ratios through real-time intake monitoring and automated ration adjustments.
- USDA National Organic Program:Certification requirements for organic livestock feed channels are expanding addressable market for non-GMO and antibiotic-free formulation segments across Upper Midwest cooperative networks.
- Corn Belt Infrastructure Clustering:Feed milling capacity concentrated in Iowa, Illinois, and Nebraska leverages proximity to grain supply, reducing inbound logistics costs for bulk ingredient procurement.
Market Restraints
- Soybean Meal Price Volatility:Protein input costs fluctuate with South American crop yields and export competition, compressing premix margin pools for independent compounders.
- Phosphorus Regulation Stringency:State-level nutrient management planning obligations in North Carolina and California impose formulation constraints that increase specialty mineral premix costs.
- Alternative Protein Substitution:Insect meal and single-cell protein technologies threaten conventional soybean and fishmeal demand in premium poultry and aquaculture feed channels.
Strategic Opportunities
- Canadian Prairie Expansion:Underpenetrated feed milling infrastructure in Alberta and Saskatchewan offers greenfield capacity deployment adjacent to expanding beef cattle finishing operations.
- FDA Novel Feed Additive Pathway:Accelerated approval frameworks for enzyme and probiotic formulations create first-mover advantage in gut health optimization segments.
- Direct-to-Farm Digital Platforms:E-commerce procurement channels bypass traditional distributor networks, capturing margin compression value for mid-size dairy and swine operations.
Industry Challenges
- Formulation Chemist Talent Scarcity:Specialized expertise in low-phosphorus ration balancing and amino acid optimization remains concentrated among legacy mill technical staff nearing retirement.
- Medicated Feed Compliance Complexity:Veterinary Feed Directive record-keeping requirements demand capital investment in batch tracking software and audit trail infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Compound Feed Market |
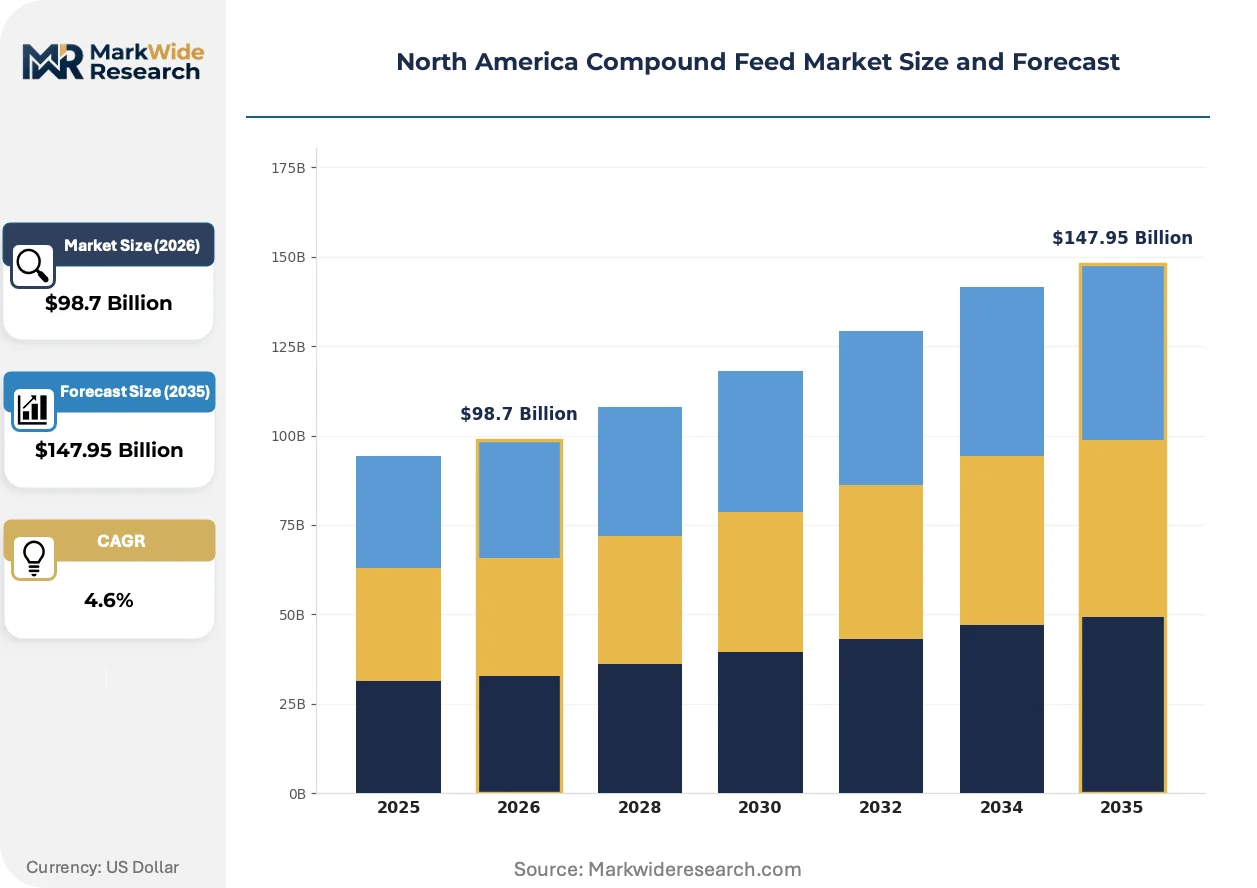
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $147.95 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Swine Feed, Ruminant Feed, Aquaculture Feed Feed Composition: Grains, Protein Meals, Vitamins, Minerals Distribution Channel: Farmers, Cooperatives, Retailers, Online Platforms End User: Livestock Farms, Aquaculture Farms, Feed Manufacturers, Pet Owners |
| Companies Covered | Cargill Inc, Archer Daniels Midland Company, Land O'Lakes Inc, Alltech Inc, Nutreco N.V., Tyson Foods, Charoen Pokphand Foods, ForFarmers B.V., De Heus B.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Compound Feed Market Evolving Landscape
Digital formulation platforms and novel ingredient processing are compressing development cycles for species-specific rations while regulatory pressure on nutrient runoff accelerates precision feeding adoption.
Near-infrared spectroscopy coupled with cloud-based ration optimization software is unifying ingredient quality assessment with real-time formulation adjustments. Large integrated poultry operations in the southeastern United States deploy these systems at receiving bays to reject off-spec grain before it enters production streams. The technology is unifying procurement and quality control functions that previously operated in siloed departments, reducing formulation variance and shrink.
The FDA's Veterinary Feed Directive continues tightening antibiotic usage documentation requirements for medicated feeds, forcing mills to segregate production lines and extend batch retention sampling. This regulatory friction disproportionately burdens mid-size independent compounders lacking dedicated compliance infrastructure. Iowa and North Carolina swine operations are responding by consolidating supplier relationships toward vertically integrated feed manufacturers with captive veterinary oversight.
Buyer concentration among thousand-head-plus dairy operations is compressing procurement cycles from annual contracts to quarterly price renegotiations with formula adjustment clauses. Traditional feed distributors with siloed sales and logistics functions face disintermediation as direct mill relationships offer volume-tiered pricing and dedicated nutritionist support. This pattern is most visible across Wisconsin and Minnesota where cooperative ownership structures historically dominated but now compete with national compounders offering integrated risk management tools.
North America Compound Feed Market Segmentation
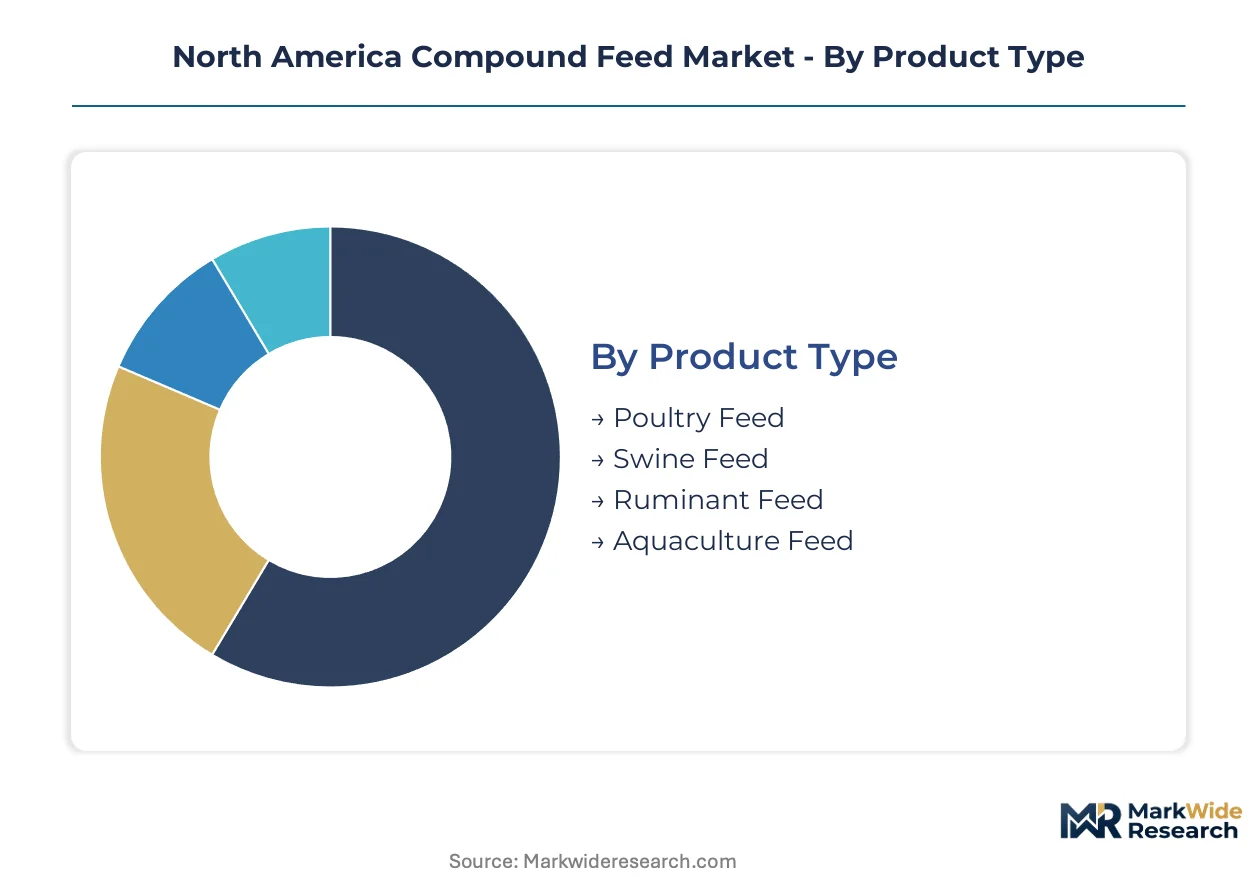
Compound feed segmentation in North America tracks how formulation complexity, procurement patterns, and end-use concentration create distinct margin pools across the value chain. Category boundaries increasingly blur as integrated operations internalize multiple steps.
Product Type:
Volume concentration sits with poultry and ruminant categories, while premium growth concentrates in specialized aquaculture and precision-formulated swine segments.
- Poultry Feed:Corn-soybean meal base formulations dominate, with crude protein specifications typically ranging 18-22% for broiler starter rations. Vertically integrated operations across Georgia, Arkansas, and Alabama drive procurement consolidation toward captive mill networks that bypass traditional distribution.
- Swine Feed:Phase-feeding protocols with lysine-optimized grower-finisher rations reduce nitrogen excretion to meet EPA discharge limits. Iowa and North Carolina expansion in thousand-head-plus finishing barns is accelerating demand for customized amino acid premixes and enzyme-supplemented diets.
- Ruminant Feed:Dairy concentrates and beef backgrounding rations leverage regional forage availability across Wisconsin, Minnesota, and the Texas Panhandle.
- Aquaculture Feed:High-protein extruded formulations for catfish and salmonid operations command formulation precision premiums in Mississippi Delta and Pacific Northwest coastal zones.
Mature deployment sits with poultry feed. Newer deployment is concentrated in aquaculture feed.
Feed Composition:
Cost tier separation runs from bulk grain commodities through precision-manufactured vitamin premixes where technical specification drives pricing power.
- Grains:Corn and sorghum provide metabolizable energy foundations, with test weight and moisture specifications determining inclusion rates. Corn Belt elevators in Iowa, Illinois, and Nebraska supply 70% of regional starch inputs through origination networks that compounders access via forward contracting.
- Protein Meals:Soybean meal, canola meal, and distiller's dried grains supply amino acid profiles, with South American crop cycles creating price volatility that Midwest mills hedge through crush margin positions.
- Vitamins:Fat-soluble A, D, E, K and water-soluble B-complex micro-premixes require formulation chemist expertise and stability testing under FDA food additive regulations.
- Minerals:Macro-minerals (calcium, phosphorus, salt) and trace elements (selenium, zinc, copper) face phosphorus regulation constraints in North Carolina and California watersheds.
Commodity deployment concentrates in grains. Precision deployment is expanding fastest in vitamin and mineral premixes.
Distribution Channel:
Customer scale determines channel selection, with procurement sophistication separating direct mill relationships from intermediary-dependent smaller operations.
- Farmers:Thousand-head-plus dairy and swine operations negotiate quarterly formula-adjusted contracts with dedicated nutritionist support, bypassing traditional distributors entirely.
- Cooperatives:Member-owned purchasing networks across Wisconsin and Minnesota retain loyalty through risk management tools and shared ownership structures, though national compounders now compete aggressively.
- Retailers:Farm supply stores and regional distributors serve sub-500-head livestock operations with bagged feed and limited technical service.
- Online Platforms:Direct-to-farm digital procurement channels capture margin compression value for mid-size operations seeking price transparency and automated reordering.
Traditional deployment sits with cooperatives. Platform-based deployment is climbing the fastest.
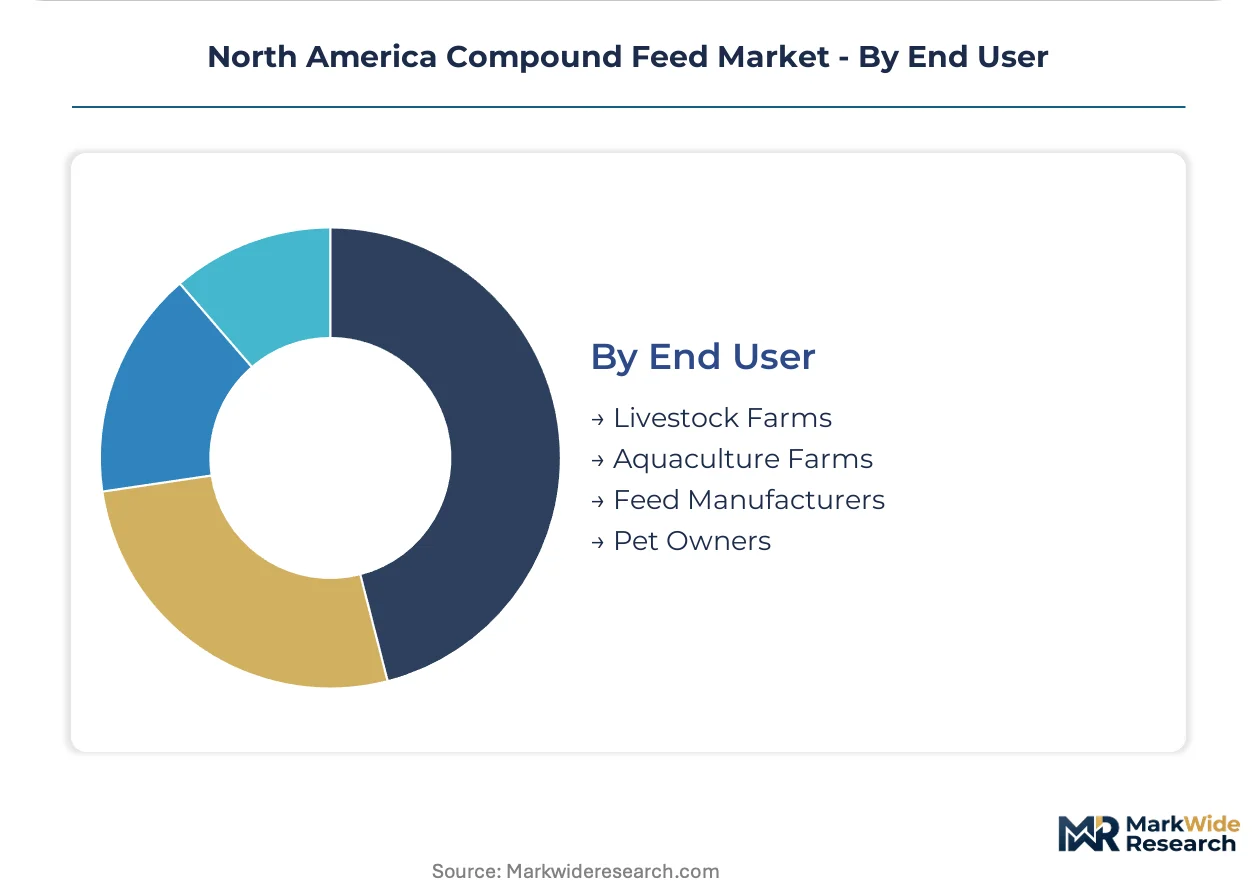
End User:
Integration depth separates captive feed manufacturing from external procurement, with regulatory compliance burden driving consolidation toward specialized suppliers.
- Livestock Farms:Beef cattle backgrounding and dairy operations across the Upper Midwest and Great Plains represent volume concentration, with on-farm mixing declining as formulation complexity increases.
- Aquaculture Farms:Catfish ponds in Mississippi and recirculating salmonid systems in Maine and British Columbia demand species-specific extruded feeds with precise lipid profiles.
- Feed Manufacturers:Independent compounders in the Corn Belt face margin compression from integrated grain-handler competitors with captive origination.
- Pet Owners:Premium dog and cat food channels represent specialty co-manufacturing opportunity with human-grade ingredient specifications.
Volume deployment sits with livestock farms. Specialty deployment is gaining share fastest in aquaculture farms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Des Moines anchors North American compound feed manufacturing capacity, with Iowa's corn processing corridor supplying starch inputs to integrated poultry and swine operations across the Upper Midwest.
United States
Georgia, Arkansas, and Alabama house vertically integrated broiler operations that consolidate procurement toward captive mill networks. The FDA's Veterinary Feed Directive tightens antibiotic documentation requirements, forcing production line segregation. Wisconsin and Minnesota dairy cooperatives now compete with national compounders offering integrated risk management tools.
Canada
Alberta and Saskatchewan present underpenetrated feed milling infrastructure adjacent to expanding beef cattle finishing operations. Health Canada and PMRA regulate novel feed additives through accelerated approval frameworks. Prairie grain handlers are deploying greenfield capacity to capture margin compression from direct-to-farm procurement channels.
Mexico
Sonora and Jalisco concentrate poultry integration with U.S.-aligned feed formulation standards. The country's national agricultural regulator enforces residue monitoring for export-bound livestock products. Guanajuato's swine belt is attracting cross-border investment in amino acid premix facilities.
North America Compound Feed Market Competitive Landscape
The competitive structure tilts toward grain-handler conglomerates with captive origination networks. Consolidation pressures independent compounders lacking dedicated compliance infrastructure for Veterinary Feed Directive batch tracking. Three archetypes dominate: vertically integrated grain processors, cooperative-owned regional networks, and specialty premix formulators. M&A activity targets mid-size independents in the Corn Belt, while capacity expansion concentrates in Canadian Prairie greenfield sites.
Among U.S.-based conglomerates, Cargill Inc exemplifies the grain-handler archetype through upstream control over origination networks. Archer Daniels Midland Company occupies a similar position anchored by massive corn processing capacity. Land O'Lakes Inc represents the cooperative structure, locking in dairy farm loyalty across Wisconsin and Minnesota through member ownership. These three entities illustrate how input cost control and customer captivity separate sustainable margin pools from commodity-compounded feed operations.
| Leading Market Players |
|---|
| Cargill Inc |
| Archer Daniels Midland Company |
| Land O'Lakes Inc |
| Alltech Inc |
| Nutreco N.V. |
| Tyson Foods |
| Charoen Pokphand Foods |
| ForFarmers B.V. |
| De Heus B.V. |
| Others |
Value Network & Pricing Analysis
Near-infrared spectroscopy coupled with cloud-based ration optimization is compressing formulation variance while concentrating procurement power among thousand-head-plus dairy operations across Wisconsin and Minnesota. This technology shift simultaneously reduces shrink costs for integrated mills and accelerates price renegotiation cycles from annual to quarterly terms.
Pricing Analysis
Yield-linked pricing anchors compound feed contracts, with dairy operations paying premiums for rations delivering demonstrable milk production improvements per pound of dry matter intake. Three-tier pricing structure across premium, standard, and economy levels separates amino acid-optimized precision diets from commodity corn-soy base formulations. Pricing pressure stems from soybean meal volatility driven by South American export competition, compressing premix margins for independent compounders. Sub-500-head livestock operations served through farm supply retailers exhibit highest price sensitivity, while vertically integrated poultry operations in Georgia and Alabama leverage volume-tiered direct contracts to lock in cost advantages.
Supply Chain Analysis
USDA National Organic Program certification gates access to premium organic livestock feed channels, requiring documented non-GMO ingredient provenance and antibiotic-free production line segregation. Supply concentrates in the United States Corn Belt, with Canada and Mexico as secondary production nodes for specialized aquaculture and beef finishing rations. Corn, soybean meal, and distiller's dried grains form the raw material foundation, with South American crop cycles creating price volatility that Midwest mills hedge through crush positions. Tariff exposure on imported amino acids and specialty vitamins threatens formulation cost stability. Distribution runs through vertically integrated captive mill networks for large operations, while cooperatives and direct-to-farm digital platforms serve mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision livestock farming sensor networks are displacing manual ration adjustment protocols across North American dairy operations, creating technology-transition winners and legacy-formulation losers.
For Market Incumbents: Deploy backward integration into grain origination networks to lock in corn and soybean meal cost advantages against South American price volatility. Consolidate formulation chemist talent pools through targeted recruitment in Wisconsin and Minnesota dairy corridors to address impending retirement waves. Channel control through direct-to-farm digital platforms defends against cooperative disintermediation.
For New Entrants and Emerging Players: Mid-size dairy operations in the 500-1,000 head range represent the most penetrable white-space segment, currently underserved between cooperative networks and national compounder direct contracts. Alberta and Saskatchewan beef finishing expansion offers greenfield capacity deployment adjacent to underpenetrated feed milling infrastructure. Partner with precision agriculture equipment distributors to bundle sensor-based feeding systems with customized ration formulations.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by grain-handler conglomerates seeking captive origination networks and FDA-compliant medicated feed infrastructure. Long-term viability favors compounders with vertically integrated supply chains and dedicated compliance architecture for Veterinary Feed Directive batch tracking. Monitor EPA water quality standard revisions as inflection indicators for accelerated low-phosphorus formulation adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill and ADM leverage Iowa and Illinois elevator networks to compress input costs below independent compounder benchmarks. |
| Precision Feeding Technology Deployment | Sensor-based intake monitoring in Wisconsin dairy barns optimizes feed conversion ratios through real-time ration adjustments. |
| Low-Phosphorus Formulation Development | Specialized mineral premixes meet EPA Clean Water Act discharge limits for North Carolina and California watershed operations. |
| Direct-to-Farm Digital Platform Launch | E-commerce procurement channels bypass traditional distributors to capture margin compression value for mid-size swine operations. |
| Organic Certification Infrastructure Investment | USDA National Organic Program compliance opens premium pricing channels across Upper Midwest cooperative networks. |
Research Methodology
USDA National Agricultural Statistics Service reports, EPA enforcement documentation, and FDA Veterinary Feed Directive guidance documents formed the secondary backbone for this analysis. Primary interviews with feed mill operations managers, dairy nutrition consultants, cooperative procurement directors, and grain elevator origination specialists validated secondary findings. Bottom-up volume estimates from state-level livestock inventory data triangulated against top-down compound feed production statistics from Corn Belt processing corridors.
Historical trendline analysis of livestock herd expansion patterns and feed conversion ratio improvements informed projection assumptions across the analysis window. Segmentation modeling tracked product type, feed composition tier, distribution channel, and end-use integration depth. CAGRs derived from weighted average growth across dairy, beef, swine, poultry, and aquaculture demand trajectories, with corn price volatility and phosphorus regulation stringency as scenario inputs.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting South American soybean meal import flows and accelerated adoption timelines for insect protein substitution technologies. Forecasts reflect documented assumptions about regulatory enforcement consistency and livestock herd expansion rates. Stakeholders should weight assumptions against their own operating context and regional feed grain basis relationships.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
South America Swine Feed Premix Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Rice-Based Products Market
Agriculture and Agri Products
Taro Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
Organic Cassava Flour Market
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
Compound Feed Market