
 Bias Tire Market | 2026-2036
Bias Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Bias Tire Market Analysis
Fleet operators and aftermarket providers is bifurcating demand away from traditional OEM channels in the bias tire trade. Goodyear leverages its captive distribution network to sustain replacement volume in North American agricultural markets. Sumitomo Rubber Industries anchors its position through backward integration into cord fabric production, insulating margin pools from commodity volatility. Michelin competes on R&D intensity, specializing in heat-resistant compounds for tropical climates where bias construction retains cost advantages.
Bias tires employ crisscrossed ply cords running at alternating angles between 30 and 40 degrees to the bead, with multiple rubber layers reinforcing the sidewall and tread for load-bearing flexibility. This construction tolerates lower inflation pressures and resists puncture damage in off-road conditions, making it standard for agricultural implements and certain heavy truck rear axles. Agricultural tires generate the deepest margin pools among product types due to seasonal replacement cycles and specialized sizing requirements that limit commoditization. Off-road application demand outpaces on-road segments in growth velocity, driven by mining and construction activity in emerging economies where retread compatibility extends tire life cycles.
The US Department of Transportation's Federal Motor Carrier Safety Administration enforces tread depth and construction standards that bias tires must meet for interstate commerce, while EPA guidelines on volatile organic compound emissions from tire manufacturing constrain solvent-based processing methods. India's Bureau of Indian Standards mandates load rating certifications that determine market access for domestic producers and imports alike. Stakeholders must monitor evolving retreadability standards and regional labeling requirements that will determine which construction formats retain regulatory permission across key shipping corridors.
Market Dynamics
Cost-sensitive fleet operators in emerging economies are consolidating procurement around bias construction for heavy-load rear axles, compressing radial tire penetration in specific commercial vehicle segments where load flexibility outweighs highway efficiency priorities.
Growth Catalysts
- EU F-Gas Regulation:REACH compliance mandates are accelerating material innovation in European tire compounds, creating specification differentiation that rewards producers with advanced rubber formulation capabilities.
- Agricultural implement manufacturers:Field durability requirements in seasonal planting and harvesting cycles generate predictable replacement demand for specialized bias constructions with reinforced sidewall designs.
- India's commercial vehicle replacement sector:Cost-sensitive fleet operators in heavy-load applications favor bias construction over radial alternatives, concentrating volume in aftermarket channels.
Market Restraints
- Natural rubber price volatility:Input cost swings from Southeast Asian supply concentration compress margin stability for producers without captive plantation access or synthetic substitution pathways.
- Radial tire substitution:Highway-focused logistics operators in developed economies are migrating to radial construction for fuel efficiency gains, structurally limiting bias tire addressable market expansion.
- REACH substance restrictions:European chemical compliance is disqualifying legacy rubber additives and processing aids, forcing reformulation investments that smaller producers cannot absorb.
Strategic Opportunities
- Brazilian mining corridor expansion:Off-road vehicle fleets in iron ore and copper extraction zones require retread-compatible bias construction with puncture-resistant tread compounds.
- Retread technology convergence:Cold-cure retreading systems combined with digital tread monitoring are extending bias tire life cycles in commercial trucking applications.
- India's PLI scheme for auto components:Domestic manufacturing incentives are attracting capacity investment for bias tire production serving regional export markets.
Industry Challenges
- Skilled compounder shortage:Formulation expertise for heat-resistant tropical climate specifications is concentrating at legacy producers, constraining new entrant technical capabilities.
- Multi-jurisdiction certification timelines:India's BIS load rating approvals and US DOT FMCSA construction standards require parallel testing protocols that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bias Tire Market |
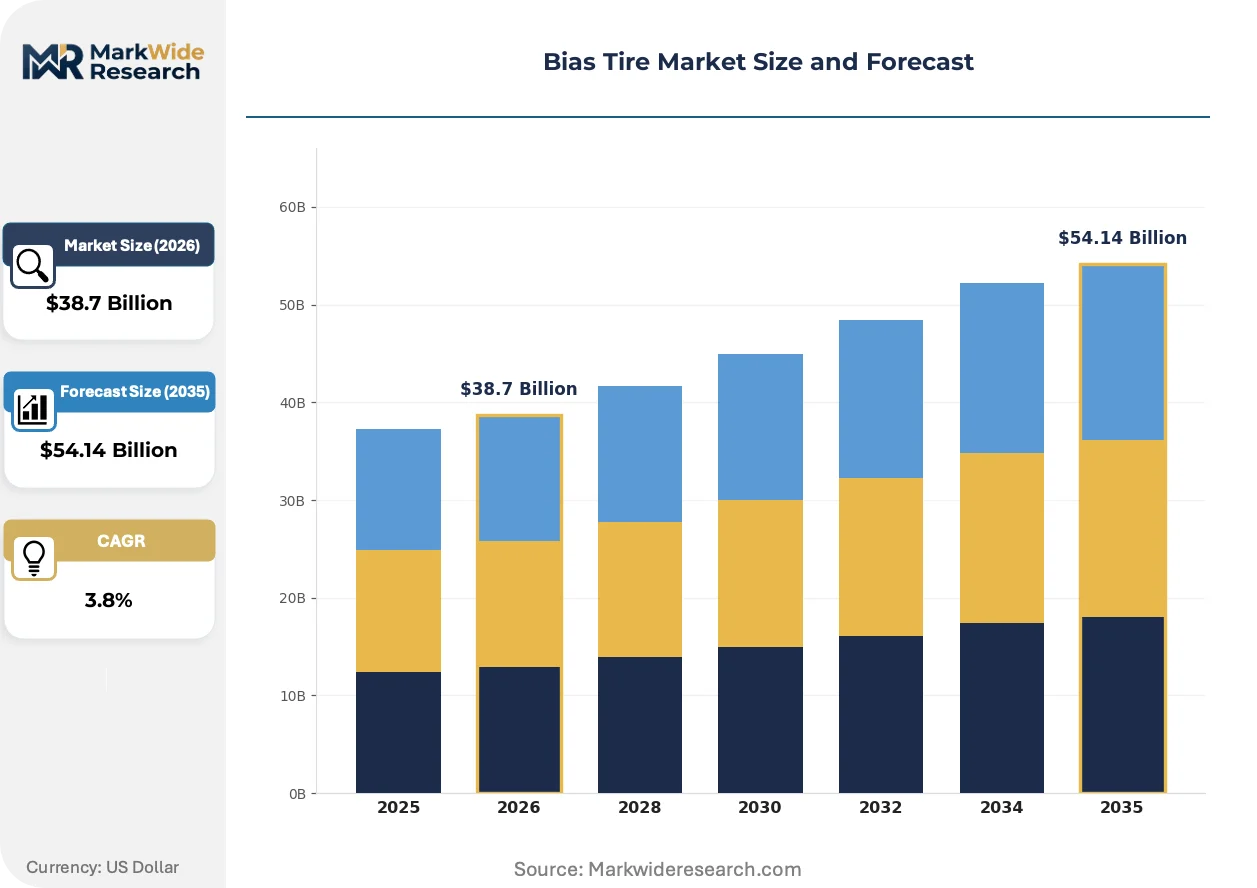
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $54.14 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Tires, Light Truck Tires, Heavy Truck Tires, Agricultural Tires Application: On-Road, Off-Road, Industrial, Agricultural End User: OEMs, Aftermarket Providers, Retailers, Fleets Distribution Channel: Online, Retail, Wholesalers, Distributors |
| Companies Covered | Goodyear, Sumitomo Rubber Industries, Michelin, Yokohama, Shanghai Huayi, Bridgestone, Pirelli, Hankook, Continental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bias Tire Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are converging to reshape bias tire construction methods, with producers racing to substitute restricted additives while maintaining structural integrity under variable inflation pressures.
Aramid fiber reinforcement is replacing traditional nylon cord in high-load agricultural tire plies, delivering superior puncture resistance at reduced weight. Brazilian sugarcane harvester fleets and Australian wheat combine operators are specifying aramid-reinforced constructions for extended field service intervals. This fiber substitution is miniaturizing the performance gap between bias and radial construction in specific off-road segments where flexibility remains paramount.
REACH authorization requirements for rubber processing chemicals are forcing systematic substitution of aromatic oils and specific vulcanization accelerators across European production facilities. Tire producers serving EU agricultural and industrial equipment OEMs are reformulating compound recipes to maintain elasticity and heat dissipation properties. The regulation's substance restriction schedule is compressing technical development timelines for mid-tier producers lacking in-house toxicology assessment capabilities.
Fleet operators in India's long-haul trucking corridors are unbundling tire procurement from vehicle acquisition, creating independent aftermarket specification authority previously held by OEM channel partners. Regional tire distributors in Maharashtra and Tamil Nadu are building direct relationships with transport cooperatives, displacing traditional dealer networks. This channel restructuring is most visible in heavy commercial vehicle segments where replacement volume exceeds new vehicle tire fitment by substantial margins.
Bias Tire Market Segmentation
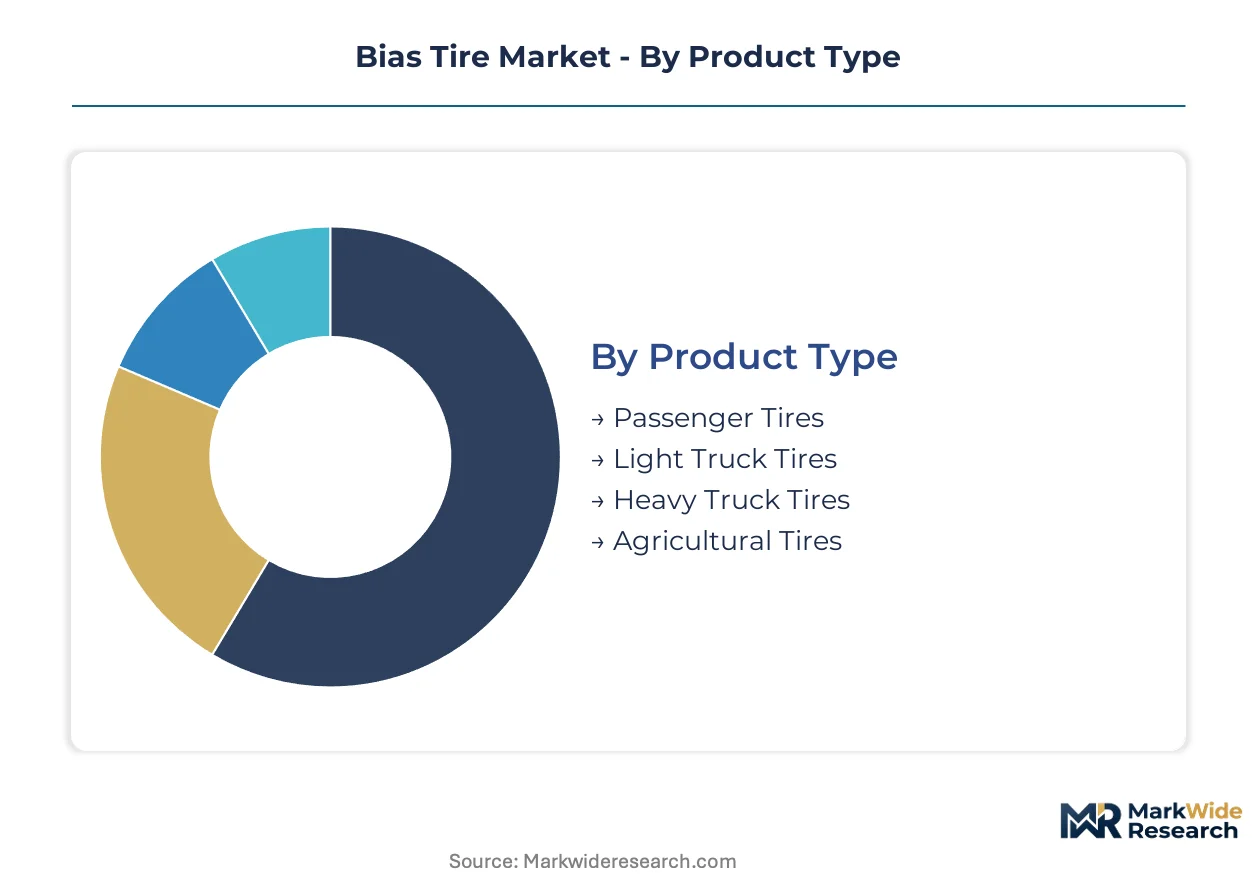
Segmentation in the bias tire market reveals where radial substitution pressure concentrates most intensely and where construction advantages preserve incumbent positions. Understanding these fault lines enables producers to allocate R&D resources toward defensible applications while managing decline in vulnerable categories.
Product Type:
Radial tire substitution pressure varies dramatically across product categories, with highway-facing segments experiencing accelerated displacement while off-road specializations retain structural advantages.
- Agricultural Tires:Reinforced sidewall designs with crisscrossed nylon or aramid plies tolerate low inflation pressures for field traction. Brazilian sugarcane harvester fleets and Australian wheat combine operators generate replacement demand through seasonal wear cycles that favor flexibility over rolling resistance.
- Heavy Truck Tires:Rear axle applications in India's long-haul corridors favor bias construction for load-bearing capacity at lower acquisition cost. Fleet operators in Maharashtra and Tamil Nadu specify these for weight-flexible operations where highway speed remains secondary to cargo volume.
- Light Truck Tires:Mixed-use vehicles in emerging economy construction zones balance on-road mileage with off-road durability requirements.
- Passenger Tires:Radial construction dominates private vehicle applications where ride comfort and fuel efficiency determine purchasing decisions.
Agricultural tires anchor the volume base while heavy truck tires gain share at the steepest rate among commercially viable segments.
Application:
Cost tier differentiation separates applications where bias construction commands premium positioning from those relegated to commodity replacement cycles.
- Off-Road:Mining and construction fleets in Brazil's iron ore extraction zones require puncture-resistant tread compounds compatible with cold-cure retreading systems. The performance requirements here validate higher compound investments that radial alternatives struggle to match at equivalent price points.
- Agricultural:Seasonal planting and harvesting equipment imposes intermittent loading patterns that bias construction accommodates through variable inflation tolerance. Field durability specifications from implement manufacturers create captive demand with limited radial crossover.
- Industrial:Material handling equipment and port operations utilize bias construction for maneuverability in confined spaces with surface debris exposure.
- On-Road:Highway logistics applications face relentless radial substitution as fuel efficiency regulations tighten and fleet operators prioritize rolling resistance metrics.
Off-road applications anchor the margin base while agricultural use expands most quickly among bias-preserved categories.
End User:
Procurement authority migration from OEMs to independent operators is restructuring volume concentration across end-user categories.
- Fleets:India's transport cooperatives in Maharashtra and Tamil Nadu now specify tires independently from vehicle acquisition, consolidating procurement power previously fragmented across dealer networks. Direct distributor relationships enable specification authority that favors bias construction for heavy-load rear axles.
- Aftermarket Providers:Regional distributors serving commercial vehicle replacement channels capture volume exceeding new vehicle fitment by substantial margins in India's heavy truck segments.
- OEMs:Agricultural implement manufacturers maintain specification control for original fitment but face growing aftermarket independence.
- Retailers:Fragmented storefront networks serve price-sensitive replacement demand in rural and semi-urban corridors with limited brand loyalty.
Fleets anchor the decision-making power shift while aftermarket providers capture the steepest volume trajectory.
Distribution Channel:
Supply concentration patterns determine which channels can sustain technical consultation services necessary for specification-intensive segments.
- Distributors:Direct relationships with fleet operators and agricultural implement manufacturers enable technical specification support for complex sizing requirements. Maharashtra and Tamil Nadu regional networks exemplify this consolidation.
- Wholesalers:Volume aggregation for price-sensitive replacement demand in India's commercial vehicle corridors compresses margin but sustains throughput.
- Retail:Physical storefronts serve immediate replacement needs with limited technical consultation capability.
- Online:Digital procurement channels gain traction in standardized sizing segments where specification complexity remains minimal.
Distributors anchor the technical service infrastructure while online channels climb the fastest among emerging alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminal underwrites Brazil's agricultural equipment export corridor, connecting São Paulo state's harvester manufacturing clusters to global replacement tire demand. India's Jawaharlal Nehru Port Trust anchors South Asian commercial vehicle parts distribution, funneling bias tire imports to Maharashtra and Tamil Nadu aftermarket networks.
United States
Midwestern corn belt harvester fleets generate seasonal replacement demand for reinforced sidewall constructions. The Department of Transportation's Federal Motor Carrier Safety Administration enforces tread depth standards that bias tires must meet for interstate heavy truck rear axles. Iowa and Illinois implement dealerships coordinate procurement with agricultural OEMs for original fitment specifications.
Brazil
Iron ore extraction fleets in Minas Gerais require puncture-resistant tread compounds compatible with cold-cure retreading systems. ANVISA chemical substance monitoring influences rubber additive selection for domestic tire producers. São Paulo state's sugarcane harvester operators specify aramid-reinforced constructions for extended field service intervals.
India
Maharashtra transport cooperatives now specify tires independently from vehicle acquisition, consolidating procurement power for heavy-load rear axle applications. The Bureau of Indian Standards mandates load rating certifications that determine market access for domestic producers and imports. Tamil Nadu regional distributors build direct relationships with fleet operators, displacing traditional dealer networks.
Germany
Agricultural machinery OEMs in Baden-Württemberg specify heat-resistant compounds for tropical climate export equipment. The KBA enforces EU F-Gas Regulation compliance and REACH substance restrictions that disqualify legacy rubber additives. Bavarian tire producers reformulate compound recipes to maintain elasticity under evolving chemical authorization schedules.
China
Construction equipment manufacturers in Shandong Province procure bias construction for maneuverability in surface debris conditions. GB standards and MIIT industrial policy guidelines constrain solvent-based processing methods in manufacturing facilities. Yangtze River Delta port operations utilize bias construction for material handling equipment in confined spaces.
Bias Tire Market Vendor Landscape
Listed leaders compete with private specialists across capital access and operational agility dimensions. The market structures around three tiers: integrated multinationals with captive distribution, regional manufacturers with backward integration into cord fabric, and price-focused assemblers serving replacement channels. Dominant competitive moves include strategic partnerships with agricultural implement OEMs and geographic expansion into mining corridor markets.
Among Japanese producers, Sumitomo Rubber Industries exemplifies the backward-integrated archetype through in-house cord fabric production, insulating margin pools from commodity volatility. Michelin occupies a position representing R&D-intensive specialization, while Goodyear anchors the captive distribution model serving North American agricultural markets. Bridgestone and Yokohama sit within the tier of scale-driven competitors with diversified regional footprints.
| Leading Market Players |
|---|
| Goodyear |
| Sumitomo Rubber Industries |
| Michelin |
| Yokohama |
| Shanghai Huayi |
| Bridgestone |
| Pirelli |
| Hankook |
| Continental |
| Others |
Supply Flow & Price Mechanics
India's BIS load rating certifications gate both supplier qualification and price differentiation simultaneously, forcing domestic producers and importers to absorb parallel testing costs that tier market access by compliance depth rather than manufacturing scale alone.
Pricing Analysis
Volume-discount tiering structures separate aramid-reinforced agricultural specifications from standard nylon-ply constructions for heavy truck rear axles. Pricing stratifies across premium, standard, and economy tiers where certification grade and captive cord fabric production anchor differentiation. Cost compression in economy-grade heavy truck segments intensifies as Maharashtra transport cooperatives consolidate procurement power. Fleet operators in India's long-haul corridors exhibit highest price sensitivity, while Brazilian mining fleets purchasing puncture-resistant tread compounds show lowest elasticity due to retread compatibility requirements.
Supply Chain Analysis
Strategic stockpiling of natural rubber dominates over just-in-time preferences given Southeast Asian supply concentration and harvest seasonality. Manufacturing draws from Thailand, Indonesia, and Vietnam for latex feedstock while cord fabric production centers in Japan and India. Single-source vulnerability in aramid fiber supply from DuPont and Teijin concentrates risk for premium agricultural tire specifications. Distribution runs through captive dealer networks serving North American agricultural OEMs and independent distributors in India's commercial vehicle corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against radial tire incursion in highway-facing segments, requiring incumbents to fortify positions where bias construction retains structural advantages.
For Market Incumbents: Consolidate backward integration into cord fabric production to insulate margin pools from natural rubber volatility, mirroring Sumitomo Rubber Industries' captive supply model. Deepen specification partnerships with Baden-Württemberg agricultural machinery OEMs for tropical climate export equipment, locking in heat-resistant compound demand against REACH-driven reformulation costs.
For New Entrants and Emerging Players: Technical specification support gaps in India's regional distributor networks present white-space entry points where incumbent dealer relationships fragment. Target Maharashtra and Tamil Nadu transport cooperatives with direct procurement platforms, bypassing traditional OEM channel control. Lead with cold-cure retreading service bundling to capture fleet loyalty in heavy commercial vehicle replacement cycles.
For Investors and Strategic Acquirers: EU F-Gas Regulation substance restriction schedules reshape the acquisition landscape by disqualifying mid-tier producers lacking in-house toxicology assessment capabilities. Long-term viability favors targets with REACH-compliant formulation libraries and established BIS certification pathways for Indian market access. Watch aramid fiber substitution rates in Brazilian sugarcane harvester fleets as the inflection signal for premium bias construction durability acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cord Fabric | Captive nylon and aramid supply insulates margin stability from commodity swings. |
| REACH-Compliant Compound Reformulation | ECHA authorization requirements force systematic substitution of restricted rubber processing chemicals. |
| Cold-Cure Retreading Technology Deployment | Digital tread monitoring extends bias tire life cycles in India's long-haul trucking corridors. |
| Direct Fleet Distributor Relationships | Maharashtra transport cooperatives now specify tires independently from vehicle acquisition channels. |
| Aramid Fiber Reinforcement Adoption | Brazilian sugarcane harvester operators specify aramid plies for extended field service intervals. |
Methodological Framework
Operator-level perspectives from agricultural implement procurement managers, heavy fleet maintenance directors, tire compound R&D leads, and regional distribution channel heads anchored the qualitative base. Primary fieldwork combined with secondary validation from customs trade records, BIS certification databases, ECHA substance restriction schedules, and SEC filings of listed tire producers. Bottom-up volume modeling across product type, application, end user, and distribution channel segments triangulated against top-down macroeconomic indicators.
Sensitivity analysis tested forecast robustness across natural rubber price volatility scenarios and radial substitution rate assumptions over the projection horizon. Segmentation dimensions modeled include product construction type, off-road versus on-road application, fleet versus aftermarket procurement authority, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for seasonal replacement cycle intensity and mining corridor expansion patterns in Brazilian iron ore extraction zones.
Underlying assumptions cover REACH substance authorization timelines, BIS load rating certification stability, and aramid fiber supply continuity, with deviation risk concentrated in EU chemical policy acceleration and Southeast Asian natural rubber harvest disruptions. Revision becomes warranted when radial tire cost parity crosses threshold levels in India's heavy commercial vehicle segments or when retreadability standards tighten across key shipping corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Solid Tire Market
Tires and Wheels
Asia-Pacific Alloy Wheels Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Global Commercial Vehicle Run Flat Tire Inserts Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Tire Bead Wire Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
GCC Tire Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Automotive Carbon Wheels Market
Tires and Wheels
Wheel Market