
 Asia-Pacific Alloy Wheels Market | 2026-2036
Asia-Pacific Alloy Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Alloy Wheels Market Insights
JIS D 4103 certification for automotive light alloy wheels is rotating competitive access across the Asia-Pacific supplier base. CITIC Dicastal Wheel Manufacturing Co leverages captive aluminum smelting and casting capacity to anchor its position in domestic Chinese OEM supply chains. Enkei Corporation sustains technology leadership through flow-forming expertise and motorsport-derived design validation. Topy Industries Limited dominates forged wheel production for premium Japanese and Korean passenger vehicle platforms.
Asia-Pacific alloy wheels are structural automotive components typically cast or forged from aluminum-magnesium alloys to achieve strength-to-weight ratios exceeding 150 MPa per kg/m³, with primary purpose of reducing unsprung mass to improve fuel efficiency and handling dynamics. Cast wheels occupy the highest volume share across passenger vehicle OEM fitment due to lower unit economics and established die-casting infrastructure. Forged wheels represent the fastest-expanding product type as performance segments and electric vehicle platforms prioritize mass reduction and fatigue resistance. Aftermarket application channels capture elevated margin pools through customization services and brand premiums that OEM channels cannot replicate.
China's MIIT enforces GB/T 5334 and GB/T 15704 standards governing wheel fatigue testing and dynamic radial load requirements, while India's BIS mandates IS 9436 certification for domestic market access, creating dual compliance burdens for pan-Asia suppliers. Japan's METI administers JIS standards that effectively gate premium OEM supply relationships with Toyota, Honda, and Nissan. Stakeholders must monitor divergence between Chinese domestic standards and harmonized international frameworks as export competitiveness hinges on multi-jurisdictional certification breadth.
Market Dynamics
Passenger vehicle electrification across China, Japan, and South Korea is forcing alloy wheel suppliers to redesign for higher static loads and brake thermal management, compressing product development cycles while tightening performance validation requirements.
Growth Catalysts
- MIIT Fuel-Consumption Standards:China's Ministry of Industry and Information Technology mandates progressively stricter fleet efficiency targets, compelling OEMs to specify lighter forged wheels for mass reduction credits.
- Flow-Forming Technology Diffusion:Hybrid manufacturing processes combining casting with rotational forging are penetrating mid-market passenger segments previously served by conventional gravity casting.
- Yangtze River Delta Cluster Density:Co-location of aluminum smelters, wheel foundries, and machining centers within 200 kilometers of Shanghai reduces logistics friction for domestic Chinese OEM supply chains.
Market Restraints
- Primary Aluminum Price Volatility:Shanghai Futures Exchange aluminum contract fluctuations transmit directly to wheel manufacturer margins, with limited pass-through power in long-term OEM contracts.
- JIS Certification Concentration:METI-administered JIS D 4103 testing capacity resides predominantly within Japan, creating bottlenecked access for non-Japanese suppliers seeking premium OEM qualification.
- Steel Wheel Substitution in Commercial Vehicles:Heavy-duty truck and bus fleets in India and Southeast Asia continue specifying steel wheels for cost-driven fleet procurement, capping alloy penetration in commercial segments.
Strategic Opportunities
- India BIS IS 9436 Compliance Gap:Domestic Indian testing infrastructure for fatigue and impact certification remains underdeveloped, creating first-mover advantage for suppliers establishing in-country validation laboratories.
- EV Platform Thermal Management:Electric vehicle brake systems generate sustained heat loads requiring thermally conductive wheel designs, opening specification windows for advanced aluminum-silicon alloys.
- Aftermarket Customization Channels:Direct-to-consumer digital platforms in Australia and South Korea enable margin capture through personalized finish and sizing configurations unavailable through OEM distribution.
Industry Challenges
- Multi-Jurisdictional Certification Burden:Suppliers serving China, Japan, and India simultaneously must maintain parallel testing protocols for GB/T, JIS, and BIS standards, extending product launch timelines.
- Skilled Die-Casting Technician Scarcity:Gravity and low-pressure casting expertise concentrated in aging workforces across Japanese and Korean supplier bases constrains production scaling for new programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Alloy Wheels Market |
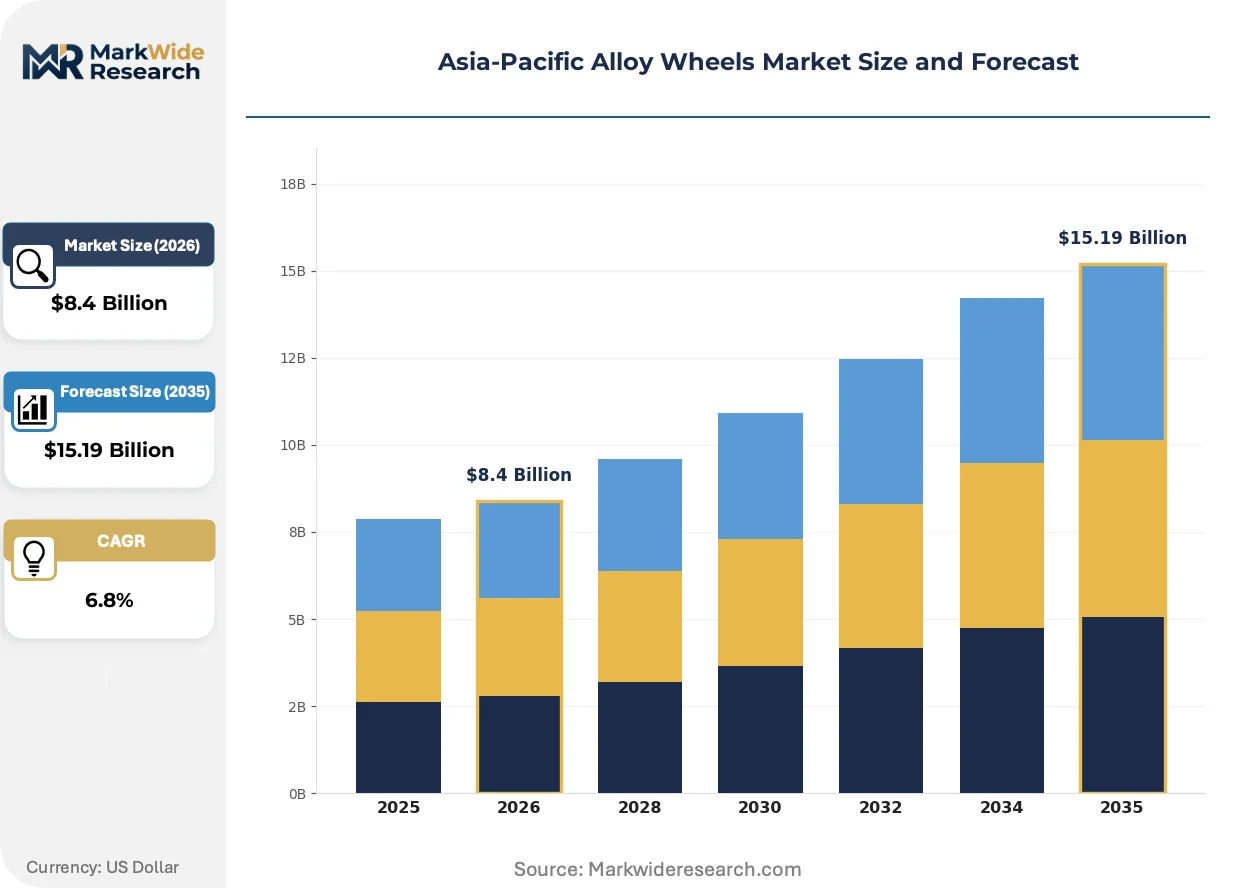
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forged, Cast, Multi-piece, Rim Application: Passenger Vehicles, Commercial Vehicles, Motorsports, Aftermarket Size: 15 Inch, 17 Inch, 18 Inch, 20 Inch Material: Aluminum, Magnesium, Alloy, Others |
| Companies Covered | Lizhong Group, Topy Industries Limited, CITIC Dicastal Wheel Manufacturing Co, Maxion Wheels, Wanfeng Group Co. Ltd., Enkei Corporation, Foshan Nanhai Zhongnan Aluminium Wheel Co., Ltd., Uno Minda, Wheels India Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Alloy Wheels Market Trends and Innovations
Wheel manufacturing processes are bifurcating between high-volume automated casting lines and flexible forged-wheel cells, with digital thread integration connecting design simulation directly to production parameter adjustment.
Flow-forming technology is fragmenting the traditional cast-versus-forged dichotomy by enabling intermediate strength-to-weight ratios at unit economics approaching die casting. Korean and Chinese tier-one suppliers are retrofitting existing casting lines with spin-forming stations to capture EV platform specifications. This hybrid approach is fragmenting supplier tiering, allowing mid-scale manufacturers to contest segments previously gated by pure forging capacity.
China's GB/T 5334 and GB/T 15704 fatigue testing protocols are tightening radial and cornering load requirements beyond harmonized UNECE R124 standards, creating technical divergence for export-oriented suppliers. Wheel manufacturers must now maintain separate validation datasets for domestic Chinese fitment versus international markets. This regulatory divergence is fragmenting product engineering resources and compressing platform commonality strategies for pan-Asia OEMs.
Direct procurement relationships between passenger vehicle OEMs and specialized wheel manufacturers are displacing traditional tier-one module supplier intermediation in Japan and South Korea. Hyundai-Kia and Toyota are issuing wheel-specific technical specifications and conducting direct supplier audits, unbundling wheels from suspension module contracts. This channel restructuring is most visible in premium platform launches where design differentiation carries brand weight.
Asia-Pacific Alloy Wheels Market Segmentation
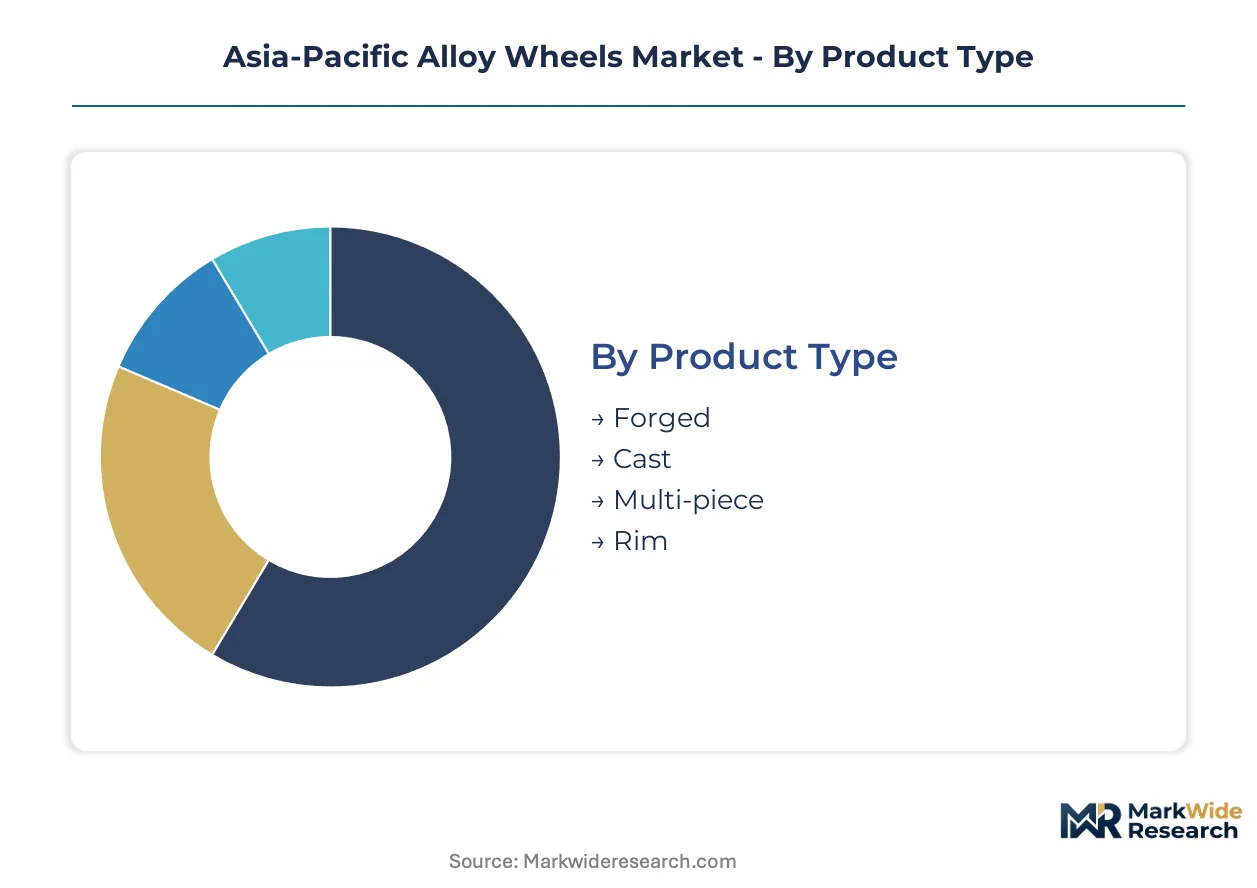
Segmentation in the Asia-Pacific alloy wheels market tracks how regulatory pressure, vehicle electrification, and manufacturing economics split demand across incompatible technical specifications. Each dimension carries distinct certification burdens and margin profiles that reshape supplier positioning.
Product Type:
GB/T 5334 fatigue protocols and JIS D 4103 impact standards create divergent qualification pathways that privilege certain manufacturing methods over others in specific national markets.
- Cast:Gravity and low-pressure die-casting dominates passenger vehicle OEM fitment through established infrastructure and unit economics suited to high-volume programs. Demand concentrates in China's Yangtze River Delta foundry cluster, where domestic suppliers leverage co-located aluminum smelting to meet MIIT fleet efficiency mandates without forging cost premiums.
- Forged:Rotational forging and press-forging achieve strength-to-weight ratios exceeding 200 MPa per kg/m³ through aligned grain structure, serving EV platforms where unsprung mass reduction extends range. Adoption accelerates in South Korea and Japan where Hyundai-Kia and Toyota specify forged wheels for premium electric architectures subject to METI thermal management requirements.
- Multi-piece:Modular construction permits diameter-width combinations unavailable in monoblock designs, capturing aftermarket customization demand in Australia and South Korea.
- Rim:Separable rim-barrel configurations enable field repairability for commercial fleet operators in India and Southeast Asia.
Established volume favors Cast; emerging adoption favors Forged.
Application:
Channel economics separate OEM procurement governed by long-term supply agreements from aftermarket transactions commanding brand premiums through direct digital distribution.
- Passenger Vehicles:OEM fitment accounts for dominant volume across China, Japan, and South Korea, with direct procurement relationships displacing traditional tier-one module supplier intermediation. BIS IS 9436 certification requirements in India and GB/T standards in China create parallel validation datasets that fragment engineering resources.
- Aftermarket:Custom finish and sizing configurations unavailable through OEM distribution capture elevated margins via direct-to-consumer platforms, with Australian and South Korean digital channels leading channel restructuring.
- Commercial Vehicles:Heavy-duty truck and bus fleets in India and Southeast Asia continue specifying steel wheels for cost-driven procurement, capping alloy penetration despite BIS regulatory frameworks.
- Motorsports:FIA-sanctioned competition validates design methodologies that transfer to production wheel programs, with Enkei and Topy leveraging motorsport-derived testing for JIS qualification.
OEM channels dominate absolute volume; aftermarket delivers superior unit economics.
Size:
Wheel diameter specification tracks brake system thermal mass requirements and styling differentiation across vehicle platform tiers.
- 18 Inch:Balances brake clearance and ride comfort for mid-market passenger segments, representing the volume anchor across Chinese domestic OEM specifications.
- 20 Inch:Premium platform styling differentiation and EV brake thermal management requirements drive specification, climbing fastest in South Korean and Japanese luxury electric architectures.
- 17 Inch:Compact and subcompact vehicle fitment maintains share in India and Southeast Asia where cost sensitivity constrains specification.
- 15 Inch:Entry-level vehicle and commercial fleet applications persist in price-driven procurement environments.
Mid-size specifications anchor production planning; larger diameters expand with EV platform proliferation.
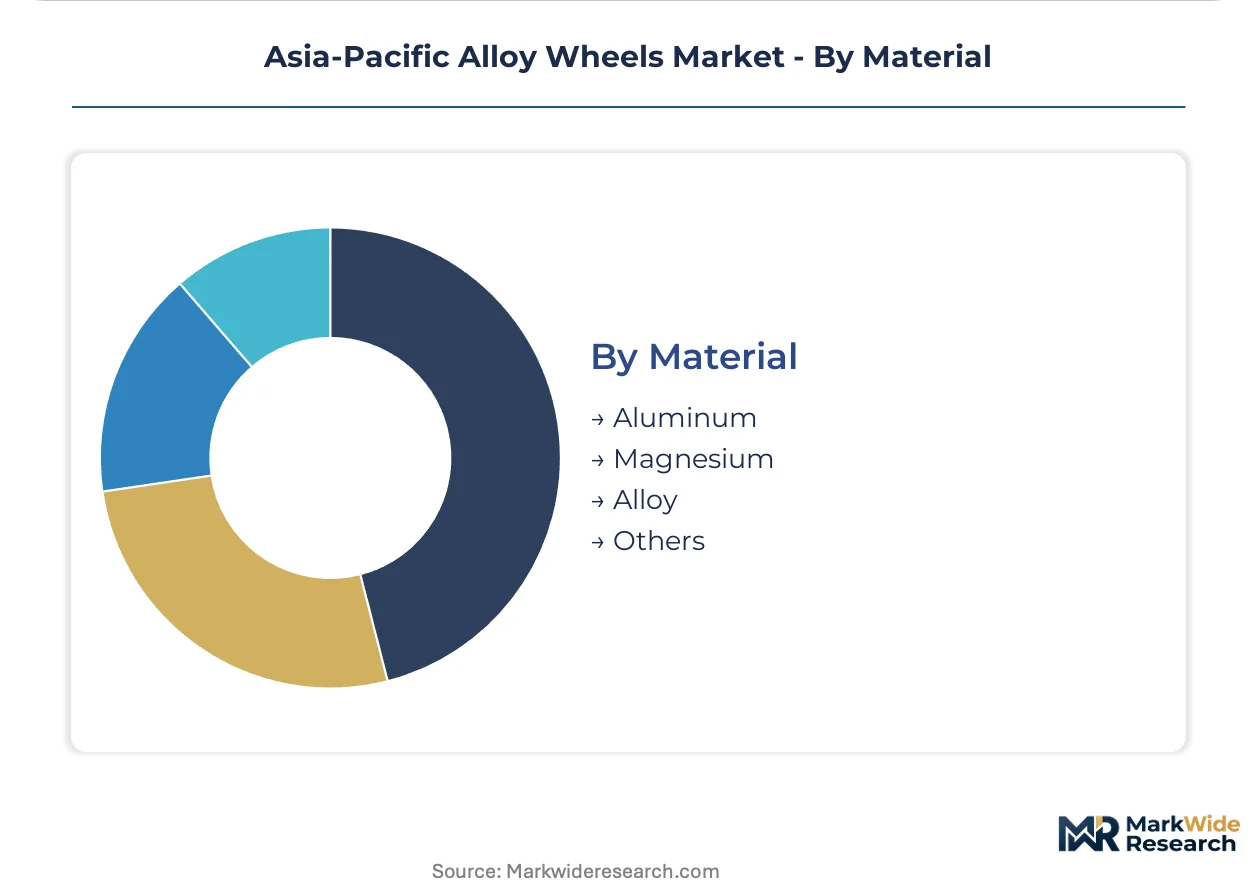
Material:
Alloy composition determines thermal conductivity, fatigue resistance, and recyclability credentials under tightening circular economy frameworks.
- Aluminum:A356.0 and A357.0 aluminum-silicon-magnesium alloys dominate through castability, corrosion resistance, and established recycling infrastructure across Asia-Pacific smelter networks.
- Magnesium:AZ91D and AM60B alloys achieve 30% mass reduction versus aluminum at equivalent stiffness, gaining specification in motorsport and limited premium EV programs subject to flammability mitigation requirements.
- Alloy:Proprietary aluminum-magnesium-silicon formulations optimize specific strength for flow-forming hybrid processes penetrating mid-market segments.
- Others:Carbon fiber reinforced polymer and titanium alloys occupy niche motorsport applications outside mass-market qualification pathways.
Aluminum maintains supply security; magnesium offers steepest mass reduction trajectory for qualified applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT fuel-consumption standards and BIS certification mandates are redrawing supplier geography across the Asia-Pacific alloy wheels market. National regulators enforce divergent testing protocols that fragment production footprints and concentrate investment in compliant manufacturing clusters.
China
Domestic OEMs specify forged wheels for mass reduction credits under tightening MIIT fleet efficiency mandates. GB/T 5334 and GB/T 15704 fatigue testing requirements exceed harmonized international standards, forcing export-oriented suppliers to maintain parallel validation datasets. The Yangtze River Delta automotive cluster co-locates aluminum smelters, foundries, and machining centers within 200 kilometers of Shanghai.
Japan
Hyundai-Kia and Toyota direct procurement relationships displace traditional tier-one module suppliers for premium platform launches. METI-administered JIS D 4103 certification gates access to Toyota, Honda, and Nissan supply chains. Kanto and Chubu industrial corridors concentrate flow-forming expertise and motorsport-derived design validation capabilities.
India
Heavy-duty truck and bus fleets continue specifying steel wheels for cost-driven procurement, capping alloy penetration in commercial segments despite BIS regulatory frameworks. BIS mandates IS 9436 certification for domestic market access, while domestic testing infrastructure for fatigue and impact certification remains underdeveloped. Tamil Nadu and Maharashtra automotive corridors attract first-mover suppliers establishing in-country validation laboratories.
South Korea
Electric vehicle brake thermal management requirements drive specification of advanced aluminum-silicon alloys for sustained heat load dissipation. MFDS-aligned technical specifications govern automotive component qualification pathways. Seoul Capital Area suppliers retrofit casting lines with spin-forming stations to capture EV platform specifications.
Australia
Direct-to-consumer digital platforms enable aftermarket margin capture through personalized finish and sizing configurations unavailable through OEM distribution. Import compliance with UNECE R124 standards governs market access for non-domestic suppliers. New South Wales and Victoria urban centers concentrate customization demand for premium passenger vehicle segments.
Asia-Pacific Alloy Wheels Market Competitive Landscape
Listed leaders compete with private specialists across certification breadth and captive raw material access. The supplier base organizes around three archetypes: state-linked aluminum smelters with backward integration into casting, Japanese precision manufacturers with JIS qualification dominance, and Indian commercial vehicle specialists with steel-to-alloy transition exposure. Competitive moves concentrate on multi-jurisdictional certification expansion and flow-forming technology retrofitting of existing casting infrastructure.
Among China-based fabricators, CITIC Dicastal Wheel Manufacturing Co exemplifies state-linked vertical integration from aluminum smelting through finished wheel production. Topy Industries Limited occupies a position within the Japanese forged wheel tier serving premium passenger vehicle platforms. Enkei Corporation represents flow-forming technology leadership derived from motorsport validation methodologies. Lizhong Group and Wanfeng Group Co. Ltd. anchor the private specialist tier competing on scale economics in gravity and low-pressure die-casting segments.
| Leading Market Players |
|---|
| Lizhong Group |
| Topy Industries Limited |
| CITIC Dicastal Wheel Manufacturing Co |
| Maxion Wheels |
| Wanfeng Group Co. Ltd. |
| Enkei Corporation |
| Foshan Nanhai Zhongnan Aluminium Wheel Co., Ltd. |
| Uno Minda |
| Wheels India Limited |
| Others |
Pricing and Supply Chain Analysis
Sixty-day aluminum inventory cycles at Yangtze River Delta foundries directly feed pricing power into long-term OEM contracts, compressing margin buffers when Shanghai Futures Exchange volatility spikes. This lead-time exposure concentrates negotiation leverage among smelter-integrated suppliers while forcing pure-play wheel manufacturers toward spot-market hedging.
Pricing Analysis
Certification level creates the primary spread between JIS-qualified forged wheels commanding OEM premiums and uncertified cast products serving aftermarket channels. Three-tier pricing structure across premium forged, standard flow-formed, and economy gravity-cast levels tracks material input costs with limited pass-through elasticity in annual supply agreements. Cost compression in economy cast segments is intensifying because Indian and Southeast Asian fleet buyers prioritize steel wheel substitution savings. Aftermarket customization channels exhibit lowest price sensitivity, while commercial vehicle procurement teams in India drive hardest bargain terms.
Supply Chain Analysis
China and Japan anchor primary aluminum smelting and precision forging capacity across the Asia-Pacific alloy wheel supply base. Wheel manufacturers draw from A356.0 aluminum-silicon-magnesium alloy feedstock, magnesium AZ91D ingots for premium applications, and specialized die-casting tooling concentrated in aging Japanese and Korean technician workforces. Single-source vulnerability concentrates in JIS D 4103 testing capacity residing predominantly within Japan. Distribution runs through direct OEM procurement relationships displacing traditional tier-one module supplier intermediation in premium passenger vehicle segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel wheel substitution in commercial vehicle fleets threatens alloy penetration rates, forcing incumbents to defend specification share through total-cost-of-ownership validation and lightweighting credit monetization.
For Market Incumbents: Shield forged wheel margins by securing captive aluminum smelting capacity in China's Yangtze River Delta cluster, insulating against Shanghai Futures Exchange volatility. Accelerate JIS D 4103 certification maintenance to preserve Toyota, Honda, and Nissan supply relationships against Korean flow-forming competitors. Flow-forming technology retrofitting represents the priority capacity investment lever for mid-market segment defense. For New Entrants and Emerging Players: BIS IS 9436 certification fast-track through Tamil Nadu or Maharashtra validation laboratories unlocks first-mover positioning in India's underdeveloped domestic testing infrastructure. Target aftermarket customization channels in Australia and South Korea where direct-to-consumer digital platforms enable margin capture unavailable through OEM distribution. Motorsport-derived design validation methodology offers credible go-to-market positioning for premium segment entry. For Investors and Strategic Acquirers: Long-term, this sits as a materials-transition play because electrification-driven unsprung mass reduction requirements structurally expand forged wheel specification share. Acquisition targets cluster around mid-scale Chinese suppliers with flow-forming retrofit potential and established GB/T compliance datasets. Watch for divergence between Chinese domestic standards and harmonized international frameworks as inflection signal requiring portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Flow-Forming Technology Retrofit | Hybrid manufacturing processes enable mid-market manufacturers to contest EV platform specifications previously gated by pure forging capacity. |
| JIS D 4103 Certification Expansion | METI-administered testing capacity access preserves premium OEM supply relationships with Toyota, Honda, and Nissan. |
| Yangtze River Delta Smelter Integration | Co-located aluminum production within 200 kilometers of Shanghai reduces logistics friction and input cost volatility. |
| India BIS IS 9436 Laboratory Establishment | Domestic validation infrastructure addresses compliance gap and accelerates market access for pan-Asia suppliers. |
| Direct-to-Consumer Digital Platform Launch | Australian and South Korean customization channels capture brand premiums through personalized finish configurations. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and aluminum smelter operations managers, then refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of MIIT regulatory filings, BIS certification registries, JIS standard documentation, and vehicle production databases from IHS Markit. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the Asia-Pacific region.
Variance decomposition separates volume growth from price-mix effects across product type, application channel, wheel diameter specification, and alloy composition dimensions. CAGRs derive from regression-adjusted trend extrapolation incorporating MIIT fleet efficiency mandate phase-ins, EV platform launch timelines, and aluminum price elasticity assumptions. Modeled inputs include brake thermal management requirements for electric architectures and circular economy recycling rate projections.
The analysis sits within stated boundaries; outcomes outside sustained MIIT enforcement intensity, JIS certification capacity expansion, or primary aluminum supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation pace and OEM platform specification timelines. Recalibration cycles align with material shifts in electrification penetration rates and multi-jurisdictional certification divergence patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Truck and Bus Tires Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Ground Support Equipment Tires Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Indirect Tire Pressure Monitoring System Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Rail Road Wheels Market