
 Alloy Wheels Market | 2026-2036
Alloy Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Alloy Wheels Market Analysis
Aftermarket distribution is fragmenting as digital direct-to-consumer platforms and specialized tire-and-wheel retailers compete for share of consumer purchases. Maxion Wheels sustains manufacturing scale across multiple continents through vertically integrated casting operations. ENKEI Corporation specializes in motorsport-grade flow-formed rims, leveraging technical credibility from racing series to anchor premium aftermarket positioning. BORBET GmbH dominates European OEM supply relationships through decades of platform-specific engineering partnerships.
Alloy wheels are non-ferrous metal rims, typically cast or forged from aluminum or magnesium alloys with specific gravity ranging from 2.6 to 2.8 g/cm³, engineered to reduce unsprung mass while maintaining structural integrity under cyclic loading. Their primary commercial purpose centers on improving vehicle fuel efficiency, handling response, and brake thermal management across passenger and commercial applications. Cast aluminum configurations occupy the highest volume tier in passenger vehicle fitments, while forged variants command concentrated margin pools in performance and luxury segments. Flow-formed products represent the fastest-expanding structural category, bridging weight savings between cast economy and forged premium tiers.
The EPA enforces fuel economy standards that directly incentivize OEM specification of lighter alloy wheels over steel alternatives, while NHTSA crashworthiness regulations mandate minimum fatigue and impact performance thresholds. The EU Green Deal's embodied carbon tracking requirements are reshaping supplier qualification criteria for wheels sold into European vehicle platforms. Stakeholders must monitor evolving alloy recycling mandates and carbon border adjustment mechanisms to preserve market access across major automotive production regions.
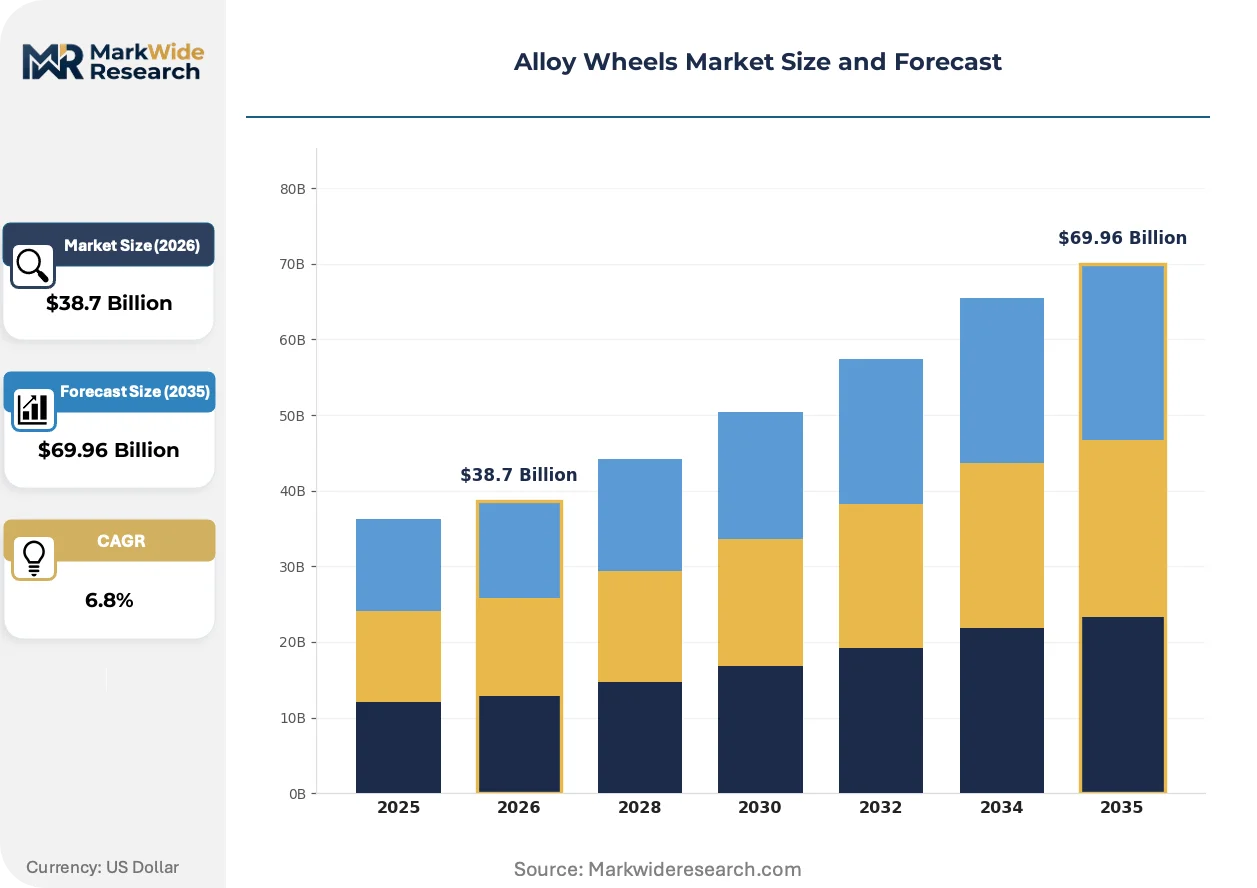
Market Dynamics
The EPA's tightened corporate average fuel economy standards are compelling automakers to prioritize mass reduction through aluminum wheel specification across electric and internal combustion platforms.
Growth Catalysts
- EPA Fuel Economy Mandates:US automakers face escalating penalties for fleet-wide inefficiency, accelerating OEM procurement of lightweight aluminum rims over steel alternatives.
- Electric Vehicle Platform Expansion:Battery-electric architectures demand maximum range efficiency, positioning forged and flow-formed wheels as standard fitments on premium EV lineups.
- German Performance Manufacturing:Stuttgart and Munich production clusters anchor European demand for forged wheels, with premium automakers sourcing locally for reduced logistics costs and just-in-time delivery.
Market Restraints
- Primary Aluminum Price Volatility:LME aluminum contract fluctuations compress margin predictability for cast wheel producers dependent on spot market ingot purchases.
- Chinese Supply Concentration:Die-casting capacity clusters in Zhejiang and Guangdong provinces create geographic risk exposure for Western OEMs seeking supply diversification.
- Magnesium Corrosion Limitations:Salt-spray performance thresholds in NHTSA testing protocols restrict magnesium alloy adoption despite superior specific gravity advantages.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentives for advanced automotive parts manufacturing attract wheel suppliers establishing localized forging and machining operations.
- EU Green Deal Embodied Carbon Tracking:Supplier qualification criteria now reward recycled content and low-carbon smelting processes, creating competitive differentiation for certified producers.
- Digital Direct-to-Consumer Platforms:Specialized tire-and-wheel e-commerce channels bypass traditional distributor markups, capturing margin expansion in aftermarket replacement cycles.
Industry Challenges
- Forging Technician Scarcity:Precision closed-die forging operations require specialized metallurgical expertise that outpaces vocational training pipeline output in established manufacturing regions.
- OEM Platform Certification Timelines:Wheel suppliers face 18-24 month validation cycles for new vehicle programs, locking working capital in pre-production tooling before volume contracts commence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alloy Wheels Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forged, Cast, Flow-Formed, Multi-Piece Material: Aluminum, Magnesium, Composite, Others Application: Passenger Vehicles, SUVs, Commercial Vehicles, Racing Finish Type: Glossy, Matte, Polished, Painted |
| Companies Covered | Maxion Wheels, ENKEI Corporation, Ronal Group, CITIC Dicastal, BORBET GmbH, Wheel Pros LLC, BBS Kraftfahrzeugtechnik AG, Kosei Aluminium Co., Ltd., Superior Industries International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alloy Wheels Market Emerging Trajectories
Flow-forming technology is compressing the weight-performance tradeoff that historically separated cast economy wheels from forged premium alternatives, reshaping competitive positioning across tiered product lines.
Flow-formed rim manufacturing combines cast pre-forms with rotary forging to achieve grain structure alignment comparable to fully forged products at substantially lower unit cost. Mid-luxury OEMs in Germany and Japan are adopting this hybrid process for standard equipment on performance trim levels. The technology is rendering obsolete the traditional cast-forged binary that structured pricing and procurement decisions for three decades.
The EU Green Deal's embodied carbon tracking requirements are reshaping supplier qualification protocols for wheels sold into European vehicle platforms. Wheel producers must now document Scope 3 emissions from bauxite extraction through final machining to maintain OEM supply relationships. Tier-1 suppliers with captive recycling streams and renewable-powered smelting partnerships are securing preferential allocation in platform sourcing decisions.
Fleet buyers and leasing operators are compressing replacement cycles and unbundling wheel-tire packages from traditional service contracts. Digital platforms now aggregate demand from rental car networks and commercial fleets, negotiating direct volume pricing that bypasses regional distributor networks. This channel shift is most visible in the United States, where national fleet management companies consolidate specification decisions across multi-thousand vehicle portfolios.
Alloy Wheels Market Segmentation
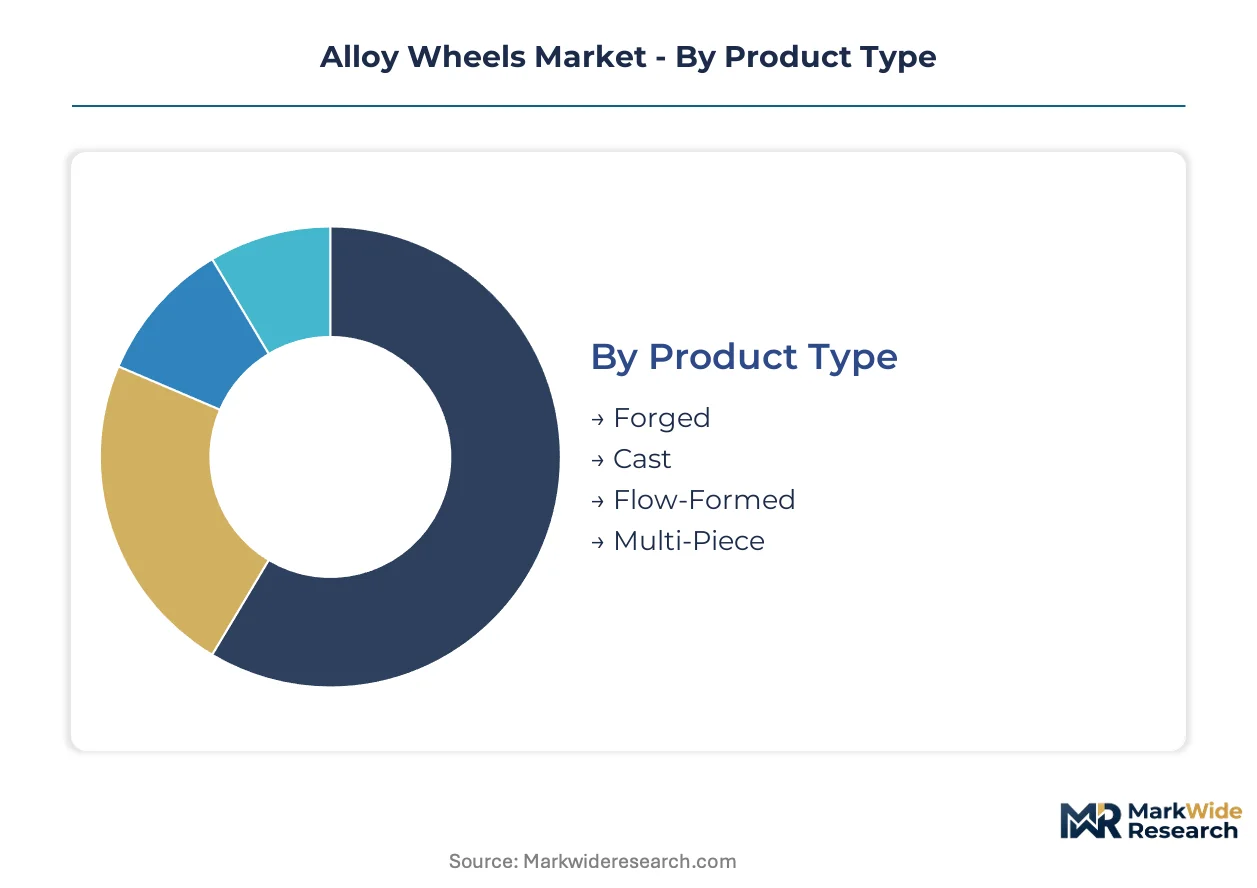
Alloy wheel procurement patterns diverge sharply across product architectures, material specifications, and end-use applications. Each segment carries distinct margin profiles, certification requirements, and aftermarket service intensities that reshape supplier strategies.
Product Type:
After-sales service intensity varies dramatically across manufacturing processes, with forged wheels demanding specialized repair networks and cast wheels supporting commodity replacement channels.
- Forged:High-pressure closed-die forming aligns grain structure for maximum strength-to-weight ratios. Stuttgart automakers specify these for performance lineups where unsprung mass reduction justifies unit costs exceeding cast alternatives by multiples.
- Cast:Gravity and low-pressure die casting dominates passenger vehicle volume tiers. Foundries in Guangdong province supply Western OEMs with standardized 16-18 inch configurations where cost efficiency outweighs marginal weight penalties.
- Flow-Formed:Hybrid rotary forging of cast pre-forms bridges the weight-performance gap at mid-tier price points. Japanese and German OEMs now specify these for standard equipment on battery-electric platforms.
- Multi-Piece:Modular rim-barrel assemblies enable custom offset and width configurations. Motorsport and ultra-luxury applications in the UAE and California sustain low-volume artisan production.
Cast configurations hold the largest share; momentum sits with flow-formed architectures.
Material:
Raw material selection directly determines recyclability credentials under EU Green Deal embodied carbon protocols and NHTSA salt-spray durability thresholds.
- Aluminum:2.6-2.8 g/cm³ specific gravity enables the broadest alloy compatibility. Secondary smelters in Germany and Norway supply low-carbon ingot that satisfies OEM Scope 3 documentation requirements.
- Magnesium:1.74 g/cm³ density offers unmatched mass reduction for racing applications. NHTSA corrosion testing protocols and liability exposure restrict highway-legal fitments despite technical superiority.
- Composite:Carbon fiber reinforced polymer hybrids penetrate Formula 1 and hypercar niches where cost insensitivity permits aerospace-grade manufacturing.
- Others:Titanium and beryllium alloys serve specialized aerospace-ground-vehicle crossover applications with extreme thermal or magnetic property requirements.
Aluminum dominates installed base; composite architectures are climbing the fastest in absolute value terms.
Application:
End-use differentiation drives wheel diameter, load rating, and aesthetic specification with minimal overlap between segments.
- Passenger Vehicles:15-19 inch cast aluminum fitments comprise the replacement cycle volume core. EPA fuel economy mandates accelerate OEM shift from steel to aluminum even on economy sedans.
- SUVs:19-22 inch diameters with reinforced barrel sections accommodate higher curb weights. Flow-formed construction gains share as manufacturers balance visual presence against efficiency targets.
- Commercial Vehicles:Forged aluminum and steel-composite hybrids address fatigue life requirements under sustained heavy loads. Fleet operators in the US Midwest specify these for long-haul trailer applications.
- Racing:FIA and IMSA technical regulations dictate maximum dimensions and minimum weights. Magnesium and carbon fiber configurations dominate where regulations permit.
Passenger vehicles anchor volume; SUVs demonstrate the steepest expansion trajectory as electrification reshapes platform architectures.
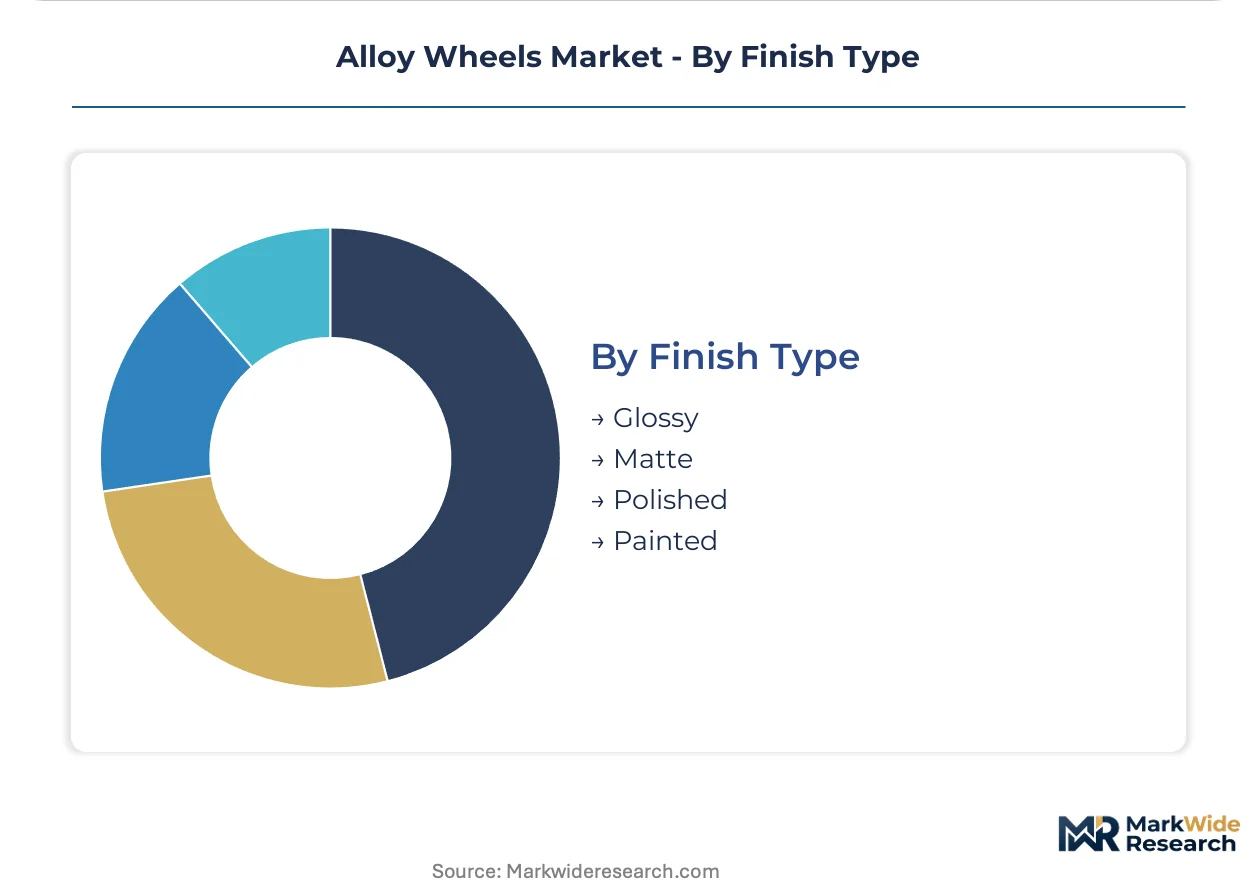
Finish Type:
Surface treatment selection correlates with regional climate exposure, warranty liability, and aftermarket refurbishment economics.
- Glossy:Clearcoat-over-basecoat systems dominate OEM specification for premium brand identity. Southern US and Gulf state markets favor these despite accelerated UV degradation.
- Matte:Satin clearcoats and anodized surfaces reduce visible brake dust accumulation. German and Japanese OEMs specify these for design-forward trim levels.
- Polished:Bare aluminum or mechanical finishing exposes substrate to oxidation. Classic vehicle restoration and show-car applications sustain niche demand.
- Painted:Solid color matching enables wheel-body coordination. Leasing companies favor these for residual value protection across multi-make fleets.
Glossy finishes command the largest share; matte treatments are gaining share fastest among electrified vehicle launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in European alloy wheel distribution, while the Yangtze River Delta's integrated aluminum smelting-to-forging corridor anchors Asia-Pacific supply. These infrastructure assets concentrate procurement decisions and shape regional competitive dynamics.
United States
EPA fuel economy mandates accelerate OEM shifts from steel to aluminum wheels across Detroit's truck and SUV lineups. NHTSA crashworthiness protocols enforce fatigue testing thresholds that favor established domestic suppliers. The Midwest manufacturing belt around Detroit and Cleveland hosts casting operations serving Ford, GM, and Stellantis platform requirements.
Germany
Premium automakers in Stuttgart and Munich specify forged wheels for performance lineups where unsprung mass reduction justifies cost premiums. EU Green Deal embodied carbon tracking reshapes supplier qualification, rewarding recycled content documentation. The Bavarian and Baden-Württemberg industrial clusters concentrate flow-forming capacity for battery-electric vehicle platforms.
China
Zhejiang and Guangdong province die-casting clusters supply Western OEMs with standardized passenger vehicle configurations. MIIT dual carbon goals pressure foundries to document smelting emissions and adopt renewable power. The Pearl River Delta's integrated supply chains compress logistics costs for export-bound wheel shipments.
Japan
Flow-formed wheel adoption accelerates among Tokyo and Nagoya automakers balancing efficiency targets with visual presence requirements. METI industrial standards govern alloy composition and surface treatment durability. The Chubu region around Nagoya anchors motorsport-grade manufacturing that transfers technology to production vehicle programs.
India
PLI scheme production-linked incentives attract wheel suppliers establishing localized forging and machining operations for export and domestic OEM fitment. BIS certification requirements structure quality benchmarks for aluminum alloy specifications. The Tamil Nadu and Gujarat industrial corridors concentrate greenfield capacity serving Maruti Suzuki, Hyundai, and emerging EV platforms.
Alloy Wheels Market Vendor Landscape
On the supply side, the industry is structured around three distinct capability tiers: multinational OEM-integrated suppliers with captive platform relationships, regional specialists commanding aftermarket premium positioning, and scale-driven foundries serving volume replacement cycles. Strategic archetypes include vertically integrated aluminum processors controlling ingot-to-finish workflows, technology licensors monetizing flow-forming patents, and brand houses aggregating distributed manufacturing through trademark licensing. Competitive dynamics center on M&A consolidation of regional aftermarket distributors and strategic partnerships between wheel producers and aluminum smelters securing low-carbon supply.
Among the named participants, Maxion Wheels exemplifies the multinational OEM-integrated archetype through manufacturing scale across multiple continents. ENKEI Corporation occupies a specialist position leveraging motorsport technical credibility. BORBET GmbH anchors European OEM supply relationships through platform-specific engineering partnerships.
| Leading Market Players |
|---|
| Maxion Wheels |
| ENKEI Corporation |
| Ronal Group |
| CITIC Dicastal |
| BORBET GmbH |
| Wheel Pros LLC |
| BBS Kraftfahrzeugtechnik AG |
| Kosei Aluminium Co., Ltd. |
| Superior Industries International |
| Others |
Supply Flow & Price Mechanics
Zhejiang province's die-casting corridor commands outsized influence over global alloy wheel pricing through concentrated gravity-fed foundry capacity serving Western OEMs. The Pearl River Delta's integrated smelting-to-finishing operations compress unit economics for standardized passenger vehicle configurations. This geographic clustering translates directly into tiered procurement leverage for volume buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates forged performance wheels from flow-formed mid-market offerings from cast commodity replacements. Price differentiation hinges on certification grade under NHTSA fatigue protocols and volume scale in platform-specific contracts. Cost compression in the cast tier is intensifying because Chinese foundries compete on spot aluminum ingot pricing. Fleet operators demonstrate highest price sensitivity, while German premium automakers show lowest sensitivity due to unsprung mass reduction mandates.
Supply Chain Analysis
Primary aluminum ingot from Australia, Norway, and Canada feeds bauxite refining and smelting operations before wheel manufacturing. The supply chain draws from secondary scrap streams in Germany and captive recycling flows in Japan for low-carbon qualification. Single-source vulnerability concentrates in Guangdong province die-casting clusters exposed to MIIT emissions enforcement. Distribution runs through OEM direct procurement for new vehicle fitment and specialized tire-and-wheel retailers for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alloy wheel markets increasingly reward service-attach revenue streams, with wheel refurbishment and seasonal storage programs expanding faster than rim hardware sales. Recurring maintenance contracts now anchor profitability for distributors serving fleet and leasing segments.
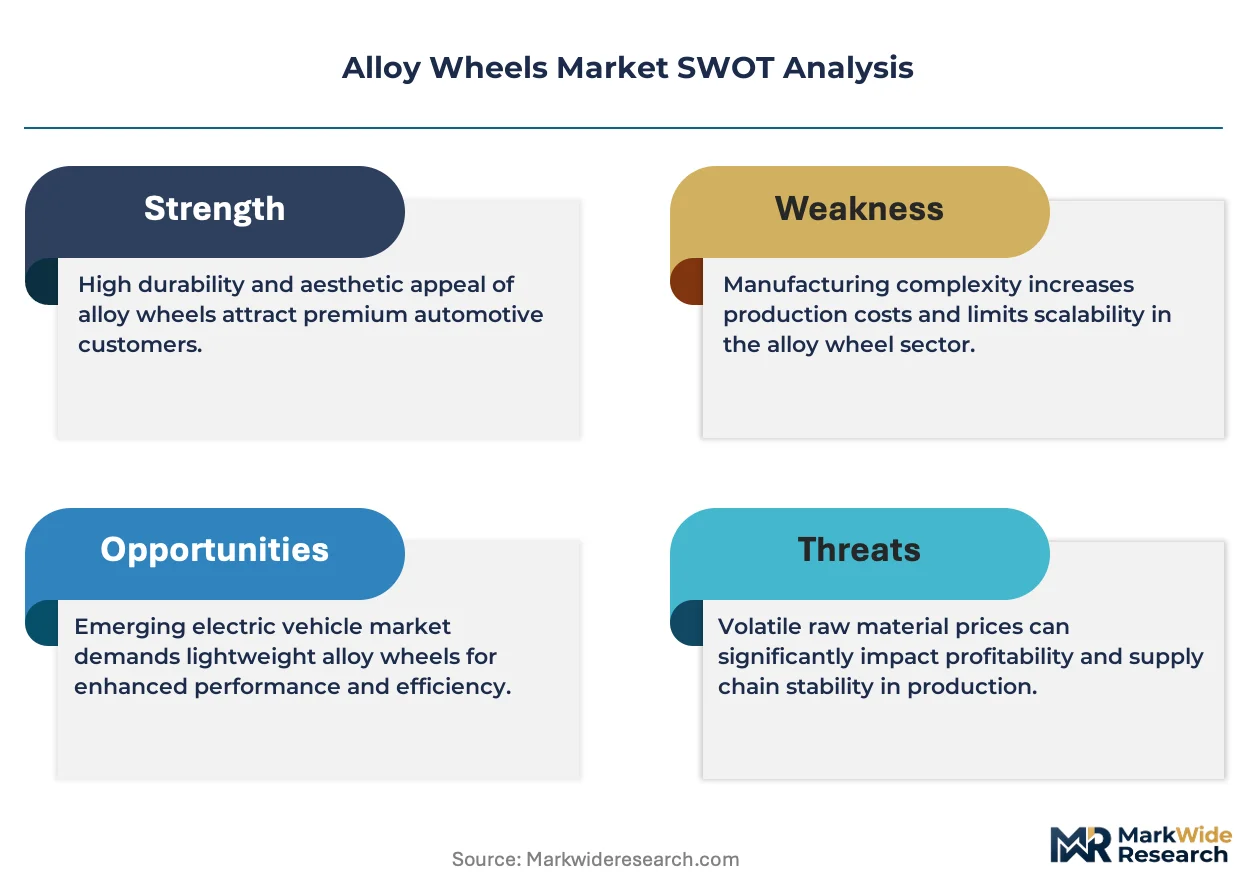
For Market Incumbents: Pre-empt margin erosion from flow-formed technology by securing captive recycling streams and renewable-powered smelting partnerships that satisfy EU Green Deal Scope 3 documentation. Backward integration into secondary aluminum supply hedges LME price volatility. Certification investment in low-carbon production processes defends platform allocation against emerging Asian competitors.
For New Entrants and Emerging Players: India's Tamil Nadu and Gujarat industrial corridors offer underpenetrated white-space for localized forging operations serving Maruti Suzuki and Hyundai EV platforms. Flow-formed wheel supply to mid-luxury battery-electric lineups represents the most penetrable segment. Direct-to-consumer digital platforms bypass established distributor markups for aftermarket entry.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wheel producers with flow-forming patents and EU carbon certification already secured. Long-term viability rests on recycling infrastructure ownership and OEM platform relationships with validation cycle visibility. Monitor EPA fuel economy standard stringency adjustments as the primary inflection indicator for aluminum wheel substitution rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Flow-Forming Technology Licensing | Patent holders monetize rotary forging processes to mid-luxury OEMs in Germany and Japan. |
| Backward Integration into Recycling | Captive secondary aluminum supply secures EU Green Deal qualification and margin protection. |
| Digital Direct-to-Consumer Platform | Bypasses traditional distributor markups in US aftermarket replacement cycles. |
| Localized Forging Operations in India | PLI scheme incentives support export competitiveness and domestic OEM fitment. |
| Low-Carbon Smelting Partnership | Renewable-powered Norwegian and German ingot sources satisfy OEM Scope 3 requirements. |
Methodological Framework
A standing panel of OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distributors, and foundry operations managers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA fuel economy filings, and EU emissions documentation. Bottom-up unit economics and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing framed analytical outputs across the projection horizon, modeling vehicle class, propulsion architecture, manufacturing process type, and regional production cluster dimensions. CAGRs derived from segment-level build-up analysis incorporating content-per-vehicle assumptions and platform mix shifts. Forecast inputs included EPA regulatory trajectory scenarios and battery-electric vehicle penetration curves by automaker.
Practitioners should monitor EPA standard stringency revisions, LME aluminum contract volatility, and EU carbon border adjustment implementation for early signals of forecast deviation. Cross-checking against vehicle production database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Elastic Polyurethane Wheels Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Passenger Tire Market
Tires and Wheels
Automotive Summer Tire Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
United States Tire Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Global Automotive Tire Inflator Market
Tires and Wheels
Agricultural Tires Market