
 Timing Belt Kits Market | 2026-2036
Timing Belt Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Timing Belt Kits Market Analytics
Commercial vehicle application is recalibrating procurement patterns across the Timing Belt Kits Market as fleet operators demand extended service intervals and lower total cost of ownership. Continental AG leverages its integrated rubber compounding and belt manufacturing footprint to control material consistency from compound to finished kit. Gates Corporation anchors its position through deep specialization in fiberglass-reinforced tensioner systems for heavy-duty platforms. SKF Group differentiates by combining bearing technology with belt drive expertise in bundled kit offerings for European OEMs.
A timing belt kit comprises a synchronous drive belt, tensioner, idler pulleys, and associated hardware engineered to maintain precise camshaft-to-crankshaft timing in internal combustion engines; the belt itself typically features a neoprene or hydrogenated nitrile rubber body with fiberglass tensile cords and nylon facing fabric to resist heat, oil, and flex fatigue over prescribed service intervals. Heavy-Duty Kits command durable margin pools because mining and construction equipment operators accept premium pricing for failure-resistant configurations in abrasive operating environments. Aftermarket Retailers represent the volume-dominant channel as vehicle aging parc expansion outpaces new unit production, while OEMs concentrate demand for Premium Kits in turbocharged direct-injection powertrains where tighter tolerances demand matched component sets.
EPA emissions certification and NHTSA corporate average fuel economy enforcement in the United States mandate precise valvetrain control that OEMs achieve through specification of high-grade belt materials and integrated tensioner designs. REACH chemical restrictions in Europe constrain rubber compound formulations, pushing suppliers toward polyurethane and advanced composite alternatives that maintain performance without restricted plasticizers. Stakeholders must monitor regulatory divergence between jurisdictions as material compliance costs reshape competitive cost structures and sourcing geography decisions.
Market Dynamics
Fleet operators across commercial vehicle segments are recalibrating maintenance economics toward extended service intervals, forcing suppliers to engineer belt materials and tensioner systems that sustain precision timing under prolonged duty cycles without catastrophic failure modes.
Growth Catalysts
- EPA emissions certification:The United States mandates precise valvetrain control that OEMs achieve through specification of high-grade belt materials and integrated tensioner designs, sustaining premium kit demand.
- Hydrogenated nitrile rubber (HNBR):Advanced elastomer formulations resist thermal degradation and oil exposure in turbocharged direct-injection powertrains, enabling longer replacement cycles.
- Commercial vehicle fleets:Mining and construction equipment operators accept premium pricing for failure-resistant configurations in abrasive operating environments.
Market Restraints
- REACH chemical restrictions:European rubber compound formulations face constrained plasticizer options, pushing reformulation costs onto suppliers.
- Neoprene supply concentration:Chloroprene rubber feedstock depends on concentrated petrochemical corridors, exposing margin volatility to upstream energy pricing.
- Electric powertrain displacement:Battery-electric vehicle architectures eliminate mechanical timing systems entirely, eroding addressable parc in passenger segments.
Strategic Opportunities
- Polyurethane belt materials:Advanced composite alternatives maintain performance without restricted plasticizers, opening compliance pathways under REACH.
- Aftermarket channel expansion:Vehicle aging parc expansion outpaces new unit production, concentrating volume opportunity in independent repair networks.
- India commercial vehicle growth:Dense logistics corridors and infrastructure investment sustain heavy-duty platform demand with intensive timing system wear profiles.
Industry Challenges
- Compound formulation expertise:REACH-compliant rubber chemistry demands polymer scientists capable of balancing flex fatigue resistance against restricted additive portfolios.
- Matched component certification:Turbocharged direct-injection powertrains require tensioner, idler, and belt combinations validated as integrated sets, extending OEM qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Timing Belt Kits Market |
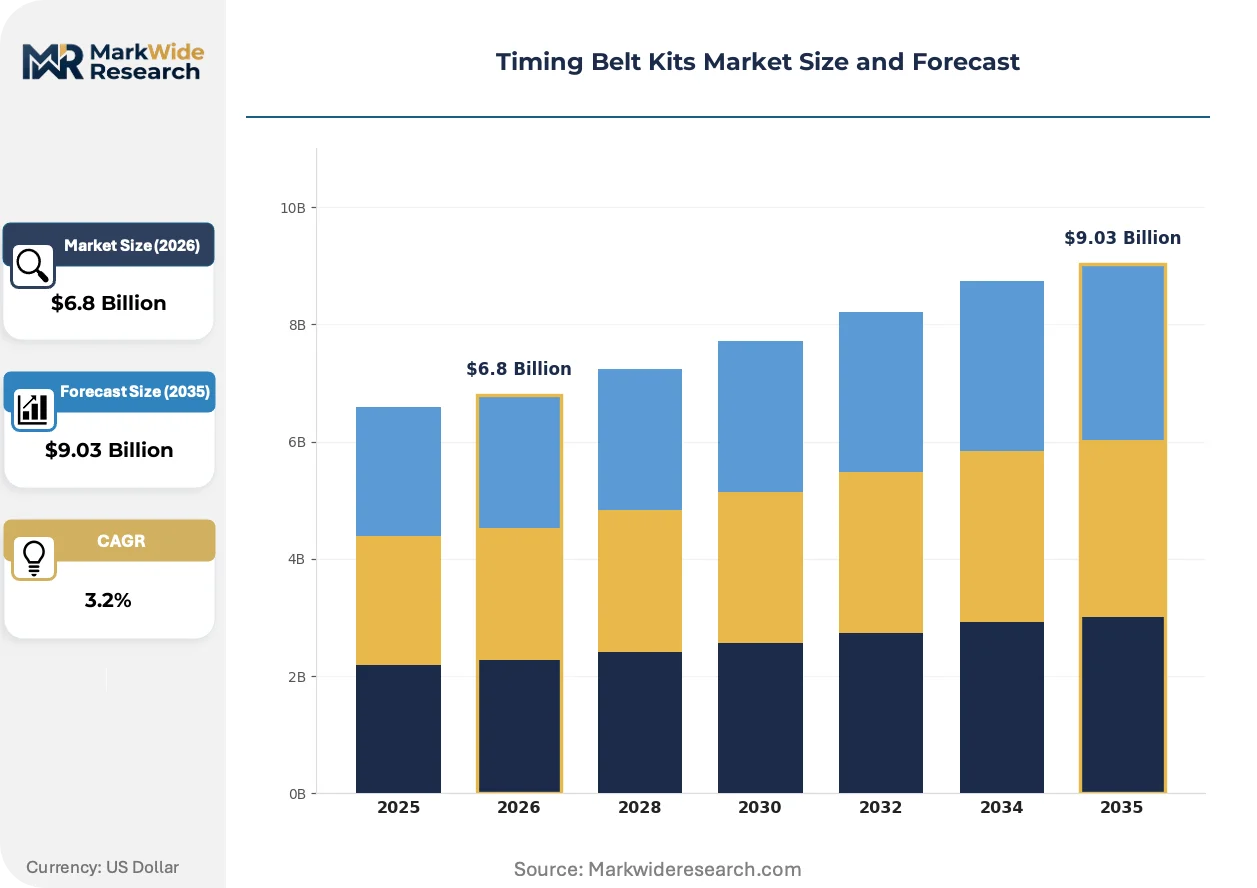
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.03 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Kits, Heavy-Duty Kits, Premium Kits, Racing Kits End User: OEMs, Aftermarket Retailers, Vehicle Assemblers, Repair Shops Material: Rubber, Polyurethane, Fiberglass-Reinforced, Composite Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy Machinery |
| Companies Covered | Continental AG, Gates Corporation, Dayco Corporation, Tsubakimoto Chain Co., SKF Group, Borgwarner Inc., ACDelco Limited, Federal Mogul Motorparts Corporation, J.K. Fenner Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Timing Belt Kits Market Evolving Landscape
Material science advances and regulatory chemistry constraints are restructuring how timing belt kits are specified, manufactured, and distributed across passenger and commercial vehicle segments.
Polyurethane tensile members are converging with fiberglass-reinforced cord architectures to deliver superior heat resistance and dimensional stability under sustained load. Heavy-duty fleet operators in mining and construction applications are adopting these hybrid constructions fastest, accepting 15-20% kit premiums for failure-resistant configurations. The technology is converging with predictive maintenance platforms that monitor belt degradation through vibration signature analysis, compressing replacement decision cycles from calendar-based to condition-based intervals.
REACH chemical restrictions in Europe constrain rubber compound formulations, pushing suppliers toward advanced composite alternatives that maintain performance without restricted plasticizers. Industrial consequence includes accelerated R&D spend on polyurethane and hydrogenated nitrile rubber variants that satisfy ECHA compliance thresholds. Premium kit manufacturers serving German OEMs face the most acute pressure, as dense concentrations of tier-one suppliers demand documentation of full material substance compliance across extended supply chains.
Fleet procurement teams are unbundling after-sales service contracts from original equipment purchases, forcing suppliers to compete on standalone replacement kit value rather than bundled lifetime cost propositions. Independent distributors and e-commerce platforms capture volume from this disintermediation, particularly in North American commercial vehicle segments where fleet operators maintain captive maintenance facilities. The shift is most visible in long-haul trucking corridors across the United States, where operator-owned service bays prioritize rapid parts availability over OEM-authorized channel loyalty.
Timing Belt Kits Market Segmentation
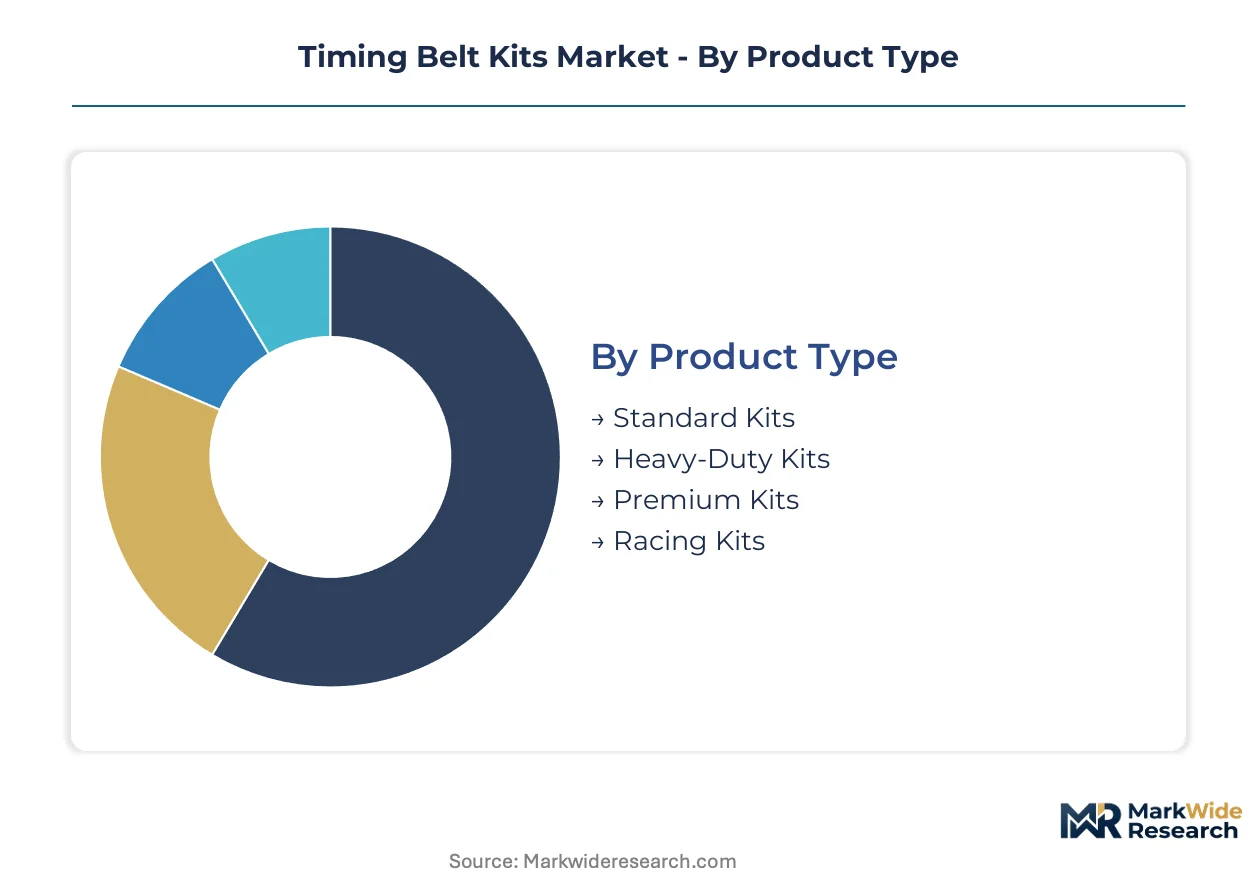
Timing belt kit specification varies sharply across duty cycles and procurement channels. Material chemistry and tensioner integration differentiate performance tiers, while fleet economics and regulatory compliance reshape channel priorities.
Product Type:
Technical specification tiers align with engine architecture complexity and replacement cycle economics.
- Standard Kits:Neoprene-bodied belts with basic tensioner assemblies serve mainstream passenger vehicles with conventional port-injection engines. Demand concentrates in North American aftermarket retail where cost-sensitive vehicle owners prioritize functional replacement over extended service intervals.
- Heavy-Duty Kits:Hydrogenated nitrile rubber formulations with reinforced fiberglass tensile cords withstand thermal loads in turbocharged commercial powertrains. Mining and construction fleets in Germany specify these configurations for abrasive operating environments where failure costs exceed kit premiums.
- Premium Kits:Matched component sets with integrated tensioner bearings and idler pulleys engineered to OEM tolerances.
- Racing Kits:Ultra-lightweight aramid-cord constructions for high-RPM competition engines with accelerated replacement schedules.
Standard Kits lead on scale; Heavy-Duty Kits lead on momentum.
End User:
Procurement authority fragmentation creates divergent value propositions across the supply chain.
- OEMs:Powertrain engineering teams specify integrated kit architectures during vehicle development, locking in multi-year supply agreements with validated component suppliers.
- Aftermarket Retailers:Independent distributors and e-commerce platforms capture volume from vehicle aging parc expansion, particularly in United States long-haul trucking corridors where fleet operators maintain captive maintenance facilities.
- Vehicle Assemblers:Contract manufacturers rely on kit suppliers for just-in-sequence delivery to assembly lines.
- Repair Shops:Service bays prioritize rapid parts availability and technical support over brand loyalty.
Aftermarket Retailers dominate volume capture; Repair Shops are gaining share fastest through fleet disintermediation trends.
Material:
Compound chemistry determines thermal resistance, flex fatigue life, and regulatory compliance pathways.
- Rubber:Chloroprene and hydrogenated nitrile formulations remain cost-competitive for standard replacement cycles, though REACH restrictions in Europe constrain plasticizer options and push reformulation costs onto suppliers.
- Polyurethane:Advanced elastomer alternatives maintain performance without restricted additives, opening compliance pathways under ECHA thresholds while delivering superior heat resistance for turbocharged applications.
- Fiberglass-Reinforced:Tensile cord architectures provide dimensional stability under sustained load.
- Composite:Hybrid constructions combining polyurethane matrices with synthetic fiber reinforcements.
Rubber retains installed base dominance; Polyurethane shows steepest expansion trajectory on regulatory compliance advantages.
Application:
Duty cycle severity and operating environment dictate kit specification intensity.
- Passenger Vehicles:Belt-in-oil systems and dry-running configurations serve conventional and hybrid powertrains, though battery-electric displacement erodes addressable parc in this segment.
- Commercial Vehicles:Fleet operators in India specify heavy-duty configurations for dense logistics corridors where intensive wear profiles demand failure-resistant materials.
- Motorcycles:Compact engine bays require narrow-profile belts with high tooth shear resistance.
- Heavy Machinery:Construction and mining equipment operators accept premium pricing for extended service interval configurations in contaminated environments.
Commercial Vehicles anchor revenue concentration; Heavy Machinery commands the highest kit premiums per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as suppliers relocate compounding operations to jurisdictions with lighter chemical restrictions. REACH compliance costs in Europe push reformulation investment toward facilities in North America and Asia where elastomer chemistry faces fewer additive constraints.
United States
Commercial vehicle fleet operators in Texas and California corridors drive specification of extended-service-interval kits for long-haul trucking platforms. NHTSA fuel economy enforcement mandates precise valvetrain timing that OEMs achieve through high-grade belt materials. Detroit's tier-one supplier cluster concentrates validation engineering for turbocharged direct-injection powertrains.
Germany
Premium automotive OEMs in Stuttgart and Munich sustain above-average kit specification rates for matched component sets. REACH chemical restrictions from ECHA constrain rubber compound formulations and accelerate R&D spend on polyurethane alternatives. The dense concentration of tier-one suppliers in Baden-Württemberg demands full material substance documentation across extended supply chains.
China
Domestic commercial vehicle production in Hubei and Shandong provinces generates intensive timing system wear profiles for logistics corridor operators. MIIT emissions standards for heavy-duty diesel engines tighten valvetrain precision requirements. Yangtze River Delta manufacturing clusters integrate belt fabrication with regional automotive assembly capacity.
India
Infrastructure investment and dense logistics corridors sustain heavy-duty platform demand with accelerated replacement cycles. BIS certification requirements for automotive components shape local sourcing decisions for fleet operators. Tamil Nadu and Maharashtra industrial belts concentrate aftermarket distribution networks for commercial vehicle maintenance.
Japan
Precision engineering culture sustains demand for matched component sets in compact turbocharged powertrains. METI industrial standards enforce quality benchmarks for synchronous drive systems in passenger and commercial applications. Aichi Prefecture's automotive supplier ecosystem anchors regional kit specification for hybrid powertrain architectures.
Timing Belt Kits Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated rubber compounders controlling material consistency while tensioner specialists dominate heavy-duty configurations. The supplier base concentrates around three strategic archetypes: vertically integrated elastomer compounders, bearing-technology bundlers, and fiberglass-reinforcement specialists. Consolidation pressure intensifies as REACH compliance costs favor scaled R&D operations over niche compounders. Geographic expansion and backward integration into chloroprene feedstock represent the dominant competitive vectors.
Within the integrated compounder tier, Continental AG exemplifies the archetype of rubber-to-finished-kit control, while Gates Corporation anchors the heavy-duty tensioner specialization vector. SKF Group occupies a distinct position combining bearing technology with belt drive expertise for European OEM bundling requirements.
| Leading Market Players |
|---|
| Continental AG |
| Gates Corporation |
| Dayco Corporation |
| Tsubakimoto Chain Co. |
| SKF Group |
| Borgwarner Inc. |
| ACDelco Limited |
| Federal Mogul Motorparts Corporation |
| J.K. Fenner Limited |
| Others |
Value Network & Pricing Analysis
Fleet procurement teams demanding extended service intervals are forcing suppliers to absorb reformulation costs for REACH-compliant compounds, compressing margins on standard kits while sustaining premiums on heavy-duty configurations.
Pricing Analysis
Distributor markups on aftermarket kits vary by channel depth, with e-commerce platforms capturing margin compression through direct-to-fleet sales while authorized distributors maintain pricing power via technical support bundling. Price differentiation hinges on certification grade for OEM-matched component sets and volume scale for fleet procurement contracts. Pricing pressure stems from REACH-driven reformulation costs passed through to European suppliers. Cost-sensitive independent repair shops exhibit highest price sensitivity; German OEM procurement teams show lowest sensitivity for validated premium kits.
Supply Chain Analysis
Polymer scientist availability constraints in Baden-Württemberg and Detroit corridors are tightening qualification timelines for compound formulation roles. Supply concentrates in Germany, China, and the United States for belt fabrication and tensioner assembly. Chloroprene rubber feedstock and fiberglass tensile cords anchor material dependencies. Single-source vulnerability in neoprene supply corridors exposes margin volatility to upstream energy pricing. Distribution runs through tier-one supplier clusters to OEM assembly lines, with aftermarket volume shifting toward independent distributors and fleet-captive facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Timing Belt Kits Market functions as a stable compounder anchored by commercial vehicle fleet replacement cycles that outpace passenger vehicle electrification erosion.
For Market Incumbents: Deploy backward integration into chloroprene feedstock to defend margin position against petrochemical price volatility. Consolidate R&D operations to absorb REACH compliance costs that disadvantage smaller compounders. Lock in multi-year supply agreements with German OEMs before qualification timelines extend further.
For New Entrants and Emerging Players: Enter via polyurethane belt manufacturing for European aftermarket channels seeking REACH-compliant alternatives without premium OEM validation burdens. Target India's heavy-duty commercial vehicle corridors where infrastructure investment sustains intensive replacement cycles. Pursue direct e-commerce distribution to fleet operators disintermediating traditional channel structures.
For Investors and Strategic Acquirers: Asymmetric upside sits with scaled compounders possessing integrated rubber-to-finished-kit control and established ECHA documentation systems. Long-term viability favors suppliers with captive HNBR formulation expertise and bearing-bundling capabilities. Monitor battery-electric vehicle penetration rates in commercial vehicle segments as the critical inflection signal for addressable parc erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chloroprene Feedstock | Captive rubber supply insulates Continental AG and Gates Corporation from petrochemical price volatility. |
| Polyurethane Formulation Scale-Up | REACH-compliant elastomer production opens European aftermarket channels for compliant suppliers. |
| Fleet Direct Distribution Partnership | E-commerce platforms capture volume from disintermediated long-haul trucking procurement in Texas corridors. |
| OEM Matched-Component Certification | Validated kit architectures secure multi-year supply agreements with Stuttgart and Munich premium automakers. |
| Predictive Maintenance Platform Integration | Vibration signature analysis compresses replacement cycles from calendar-based to condition-based intervals. |
Research Methodology
Multiple input streams — procurement directors at commercial vehicle fleets, tier-one supplier quality engineers, aftermarket distributor inventory managers, and polymer R&D leads — were reconciled against customs trade data, vehicle production databases, ECHA substance registration filings, and SEC supplier disclosures. Bottom-up kit volume estimates from regional aftermarket channels were cross-validated against top-down OEM procurement projections. Primary fieldwork with maintenance directors at mining and construction operators informed duty cycle severity assumptions.
Historical replacement cycle patterns were cross-referenced against expert panel inputs on electrification displacement timelines across the projection horizon. The analytical framework modeled segmentation across vehicle class, propulsion architecture, kit performance tier, and regional regulatory cluster. CAGRs were derived from trend-line extrapolation of fleet aging parc expansion and material substitution elasticities. Industry-specific forecast inputs included MIIT emissions enforcement trajectories and BIS certification pathway timelines.
Inputs from ECHA substance databases and IHS Markit vehicle registration data were available through the study window; gaps in fleet-level maintenance cost disclosure introduce uncertainty bands around aftermarket volume assumptions. Forecasts reflect documented assumptions on commercial vehicle electrification lag and REACH enforcement consistency. Practitioners should monitor NHTSA fuel economy rulemaking and battery-electric truck adoption curves for early signals of addressable market revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Diesel Engine Market
Powertrain
Asia-Pacific Torque Vectoring Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Natural Gas Engines Market
Powertrain
Tachometer Market
Powertrain
Turbocharger Market
Powertrain
Automotive Fuel Cock Market
Powertrain
Turbine Housing for Automobile Market
Powertrain
Automotive Fuel Injector Market
Powertrain
Power Seat Adjustment Motor Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
Axle Shaft Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Automotive Timing Chain and Belt Market