
 Plastic Formwork Market | 2026-2036
Plastic Formwork Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Formwork Market Analytics
Aftermarket service revenue is reshaping competitive economics in plastic formwork as rental and refurbishment models displace outright purchase. PERI AG leverages its global rental fleet to sustain recurring income streams beyond unit sales. Nova Formworks anchors its position through specialized modular designs for emerging-market labor constraints. Geoplast S.p.A. differentiates via recycled polymer formulations that compete on sustainability credentials in European public tenders.
Plastic formwork denotes engineered polymer systems—typically polypropylene or ABS composites molded into modular panels, column boxes, or slab tables—designed to contain fluid concrete during curing and then strip for repeated use. These systems reduce manual handling weight by up to 70 percent versus timber or steel alternatives, accelerating pour cycles on congested job sites. Modular and reusable form categories command the dominant share of current procurement value, with single-use variants retreating to niche applications where logistics costs prohibit recovery. Infrastructure and residential end users represent the fastest-growing demand pools, driven by bridge deck pours and mid-rise housing repetition.
ISO 9001 quality management and REACH chemical compliance constrain polymer sourcing for European suppliers, while India's BIS certification mandates load-testing protocols for formwork reuse cycles. China's SAMR enforces GB standards on construction plastics that dictate flame-retardant additives and dimensional tolerances. Stakeholders must monitor how evolving extended-producer-responsibility frameworks in the EU and India's PLI scheme for construction materials alter cost structures and sourcing geography.
Market Dynamics
Modular plastic formwork systems are compressing pour cycles and labor hours on congested job sites, forcing a structural shift from timber and steel toward polymer-based reusable systems across residential and infrastructure verticals.
Growth Catalysts
- GB Standards Compliance:China's SAMR-enforced durability specifications for construction plastics are mandating higher reuse cycles, pushing developers toward engineered polypropylene systems that withstand 100+ pours.
- India's PLI Scheme:The Production Linked Incentive scheme for construction materials is subsidizing domestic manufacturing of lightweight formwork, accelerating procurement in commercial building projects.
- Bridge Infrastructure Repetition:Infrastructure contractors are standardizing on slab tables and column boxes for deck pours, where modular polymer systems cut stripping time by half versus conventional alternatives.
Market Restraints
- Polypropylene Price Volatility:Feedstock fluctuations in propylene monomer directly compress margin structures for formwork molders without long-term resin contracts.
- REACH Chemical Compliance:ECHA-mandated additive restrictions on flame retardants and plasticizers constrain formulation flexibility for European suppliers, extending R&D timelines.
- Steel Formwork Substitution:High-rise commercial towers above 30 stories still specify steel for load-bearing wall forms, capping polymer penetration in premium vertical construction.
Strategic Opportunities
- Vietnam Residential Acceleration:Housing developers in Ho Chi Minh City and Hanoi are piloting rental models for modular plastic systems, creating service revenue streams beyond equipment sales.
- EU Extended Producer Responsibility:The EU Green Deal's emerging construction waste frameworks will reward recycled polymer formulations with tender preferences in public infrastructure bids.
- Digital-Physical Convergence:Integration of RFID-tagged formwork panels with BIM workflows enables fleet tracking and predictive maintenance, unlocking subscription-based fleet management contracts.
Industry Challenges
- Skilled Labor Shortage:Site crews trained on timber carpentry lack proficiency in modular panel assembly, forcing manufacturers to embed pictographic instruction systems directly into mold designs.
- BIS Certification Timelines:India's load-testing protocols for reuse-cycle validation extend product launch schedules by 8-14 months, advantaging incumbents with established testing relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Formwork Market |
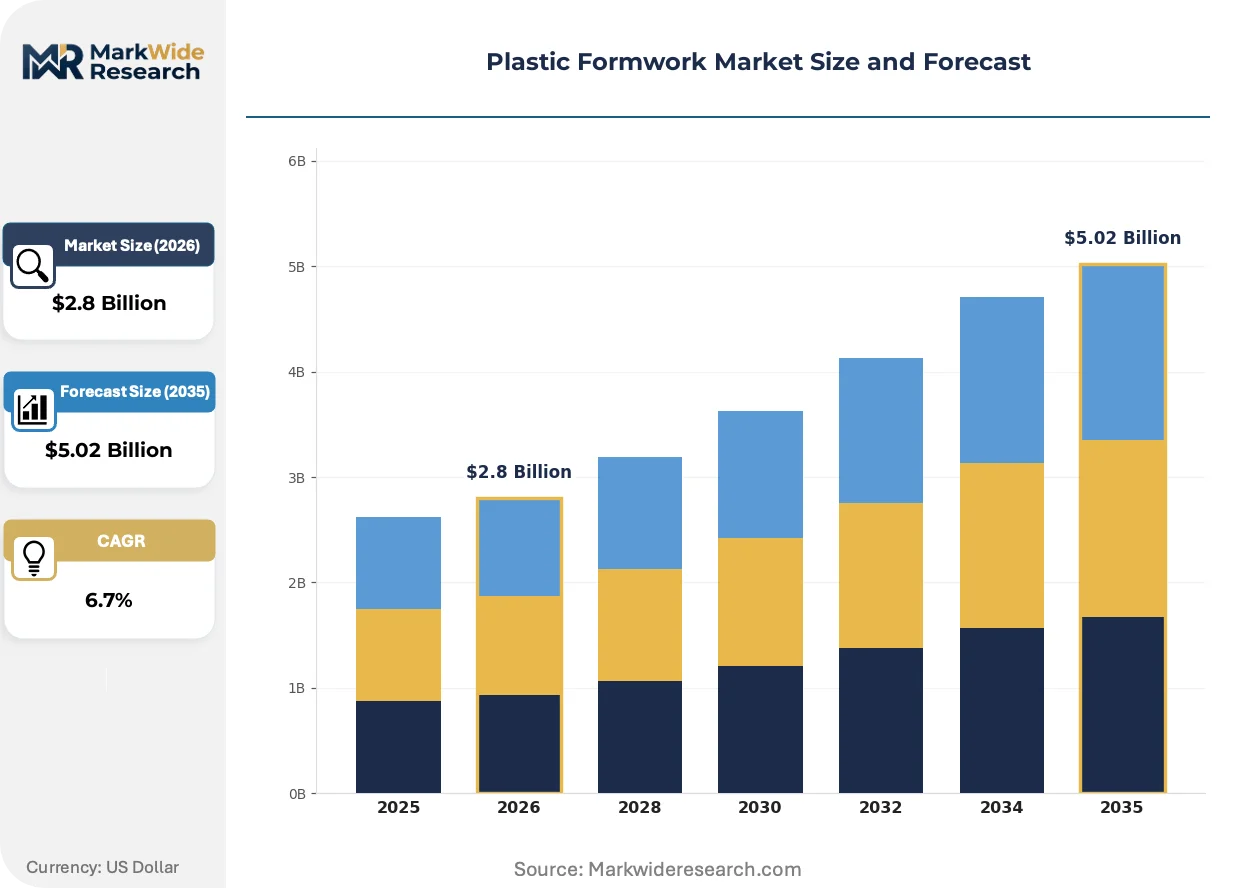
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PAN, Modular, Column, Slab End User: Residential, Commercial, Industrial, Infrastructure Form: Reusable, Single-use, Semi-permanent, Custom Application: Flat Slabs, Walls, Beams, Foundations |
| Companies Covered | PERI AG, Hebei Zolo Construction Material Co., Ltd., Moladi, NOE Formwork, Shandong Green Plastic Co., Ltd., Beizhu Group, Nova Formworks, ULMA Group, Geoplast S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Formwork Market Evolving Landscape
Material science advances and regulatory tightening are converging to redefine competitive advantage around sustainability credentials and digital integration rather than unit economics alone.
Glass-fiber-reinforced polypropylene composites are rendering obsolete conventional ABS-based panels in high-cycle applications. Infrastructure contractors in Germany and the Netherlands are specifying these materials for bridge projects exceeding 200 reuse cycles. The shift is compressing replacement rates and locking suppliers into longer-term fleet service relationships.
REACH chemical compliance is forcing reformulation of flame-retardant additives across European supply chains. ECHA's 2023-2025 restriction roadmap on halogenated compounds is accelerating migration to phosphorus-based alternatives. Formwork molders serving public tenders in France and Italy are absorbing 12-18 month recertification costs to maintain market access.
Rental and refurbishment models are displacing outright purchase across Southeast Asian residential markets. PERI AG's fleet-as-a-service contracts in Indonesia and Malaysia are capturing recurring revenue from mid-rise housing developers. The shift concentrates most visibly in urban clusters where logistics costs for panel recovery fall below 15% of replacement value.
Plastic Formwork Market Segmentation
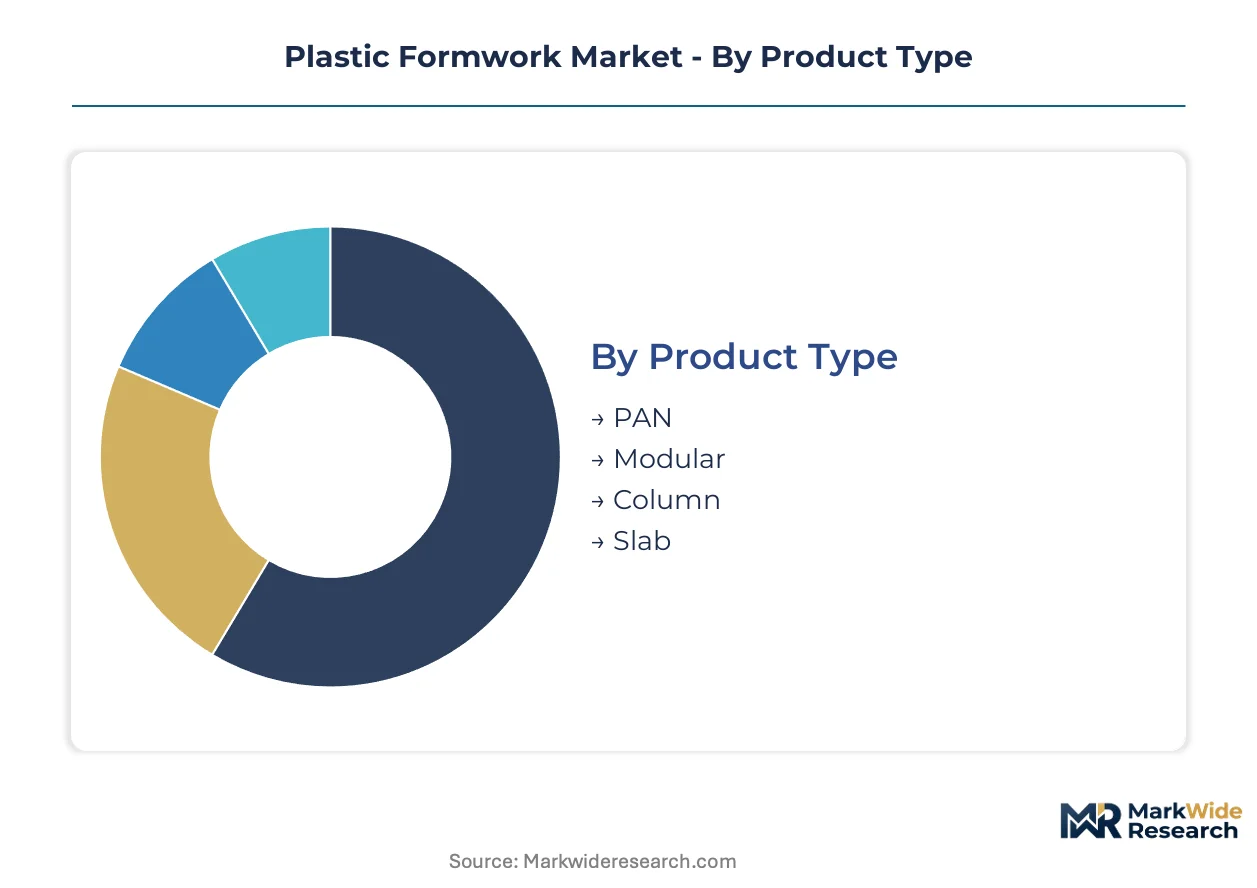
Segmentation in plastic formwork reveals divergent service intensity and reuse economics across product architectures. Rental fleet operators and refurbishment specialists calibrate coverage models to the durability profiles and labor-handling characteristics of each category.
Product Type:
After-sales service intensity varies sharply across product architectures, with modular systems demanding predictive maintenance contracts and PAN systems requiring rapid component replacement networks.
- Modular:Interlocking polypropylene panels configured for rapid assembly and stripping dominate mid-rise residential and commercial projects. Demand concentrates in India's urban housing clusters where labor shortages accelerate procurement of lightweight, pictographic-guided systems. India's PLI scheme subsidizes domestic production, compressing payback periods for developers.
- Column:Engineered boxes for vertical concrete elements withstand 100+ pour cycles in infrastructure applications. Bridge contractors in Germany and the Netherlands specify glass-fiber-reinforced variants for deck pours exceeding 200 reuse cycles, locking suppliers into long-term fleet service relationships.
- Slab:Table systems for horizontal concrete placement reduce stripping time versus conventional alternatives. Demand clusters in Southeast Asian residential towers where rental models displace purchase.
- PAN:Large-format panels for repetitive wall pours serve standardized housing developments. China's GB standards on durability specifications favor engineered PAN systems in state-backed construction.
Modular holds the largest share; momentum sits with Column as infrastructure repetition accelerates.
End User:
Cost tier stratification separates premium specification buyers from price-sensitive volume purchasers across construction verticals.
- Infrastructure:Bridge and highway contractors standardize on reusable polymer systems for repetitive deck pours. China's SAMR-enforced durability specifications mandate higher reuse cycles, pushing procurement toward engineered polypropylene.
- Residential:Mid-rise housing developers in Vietnam and Indonesia pilot rental models for modular systems, creating recurring service revenue streams. Labor constraints in Southeast Asian urban clusters accelerate lightweight formwork adoption.
- Commercial:High-rise towers above 30 stories in India specify steel for load-bearing wall forms, capping polymer penetration in premium vertical construction. Below this threshold, commercial projects drive demand for slab and modular systems.
- Industrial:Manufacturing facility construction favors custom form configurations for non-standard structural elements. Project-specific engineering requirements limit standardization and rental model applicability.
Residential commands the dominant procurement volume; Infrastructure exhibits the steepest expansion trajectory.
Form:
Volume concentration and margin structure diverge between reusable fleet assets and single-use disposable categories.
- Reusable:Engineered polymer systems designed for 100+ pour cycles dominate procurement value. REACH chemical compliance and ECHA-mandated additive restrictions constrain European formulation flexibility, extending R&D timelines for flame-retardant recertification.
- Single-use:Disposable formwork retreats to niche applications where logistics costs prohibit panel recovery. Remote infrastructure sites and conflict-zone construction absorb limited volumes.
- Semi-permanent:Extended-duration forms for complex structural elements bridge reusable and custom categories. Specialized applications in industrial construction require project-specific engineering.
- Custom:Bespoke molded configurations serve non-standard architectural geometries. Low volume and high engineering intensity limit supplier participation to specialized molders.
Reusable captures the majority of value; Custom gains share fastest as architectural complexity increases.
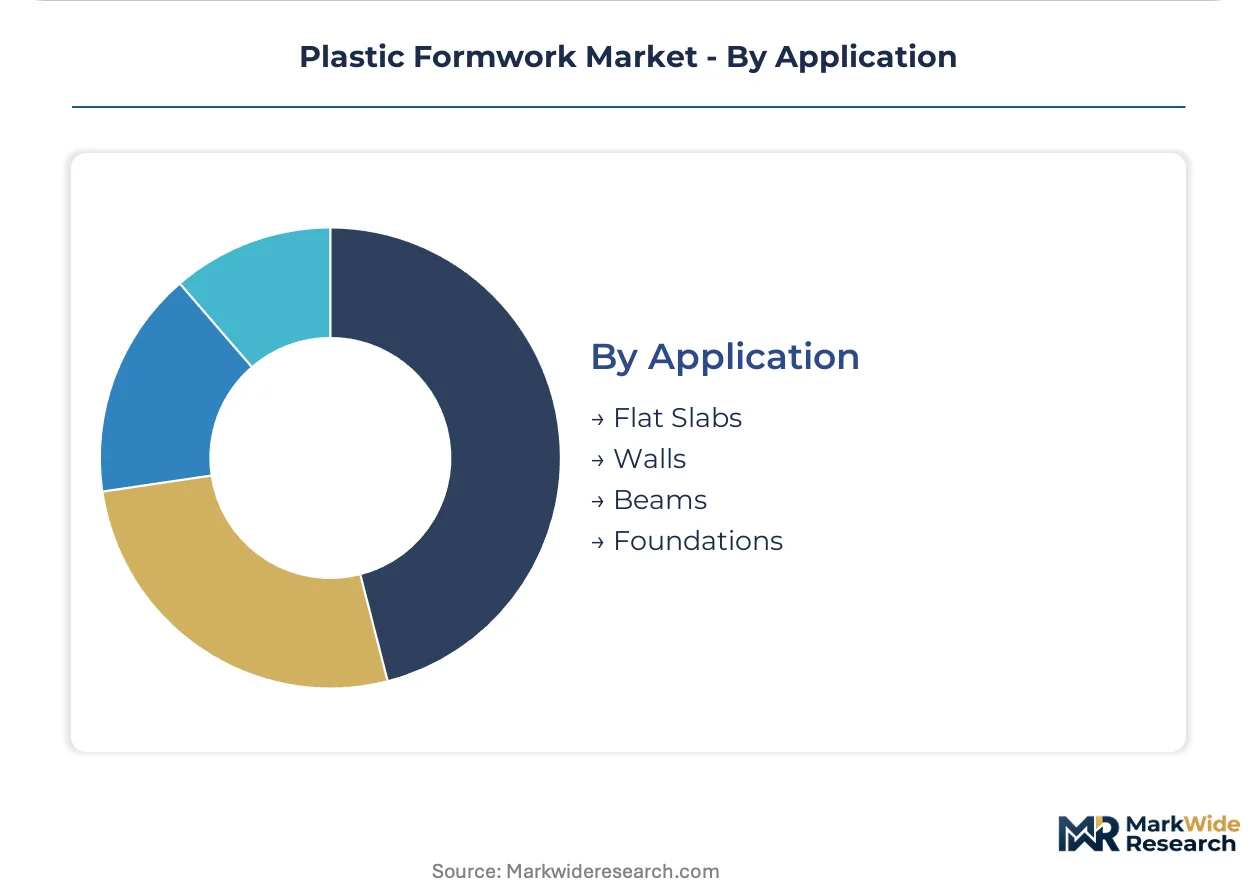
Application:
Customer type differentiation separates infrastructure contractors seeking durability from residential developers prioritizing speed and labor reduction.
- Walls:Vertical concrete containment systems span modular panels and custom configurations. China's dual carbon goals tighten specifications for formwork recyclability, favoring polypropylene over ABS composites.
- Flat Slabs:Horizontal table systems accelerate pour cycles in mid-rise construction. Vietnam's residential acceleration in Ho Chi Minh City and Hanoi drives rental model experimentation.
- Beams:Structural element formwork requires load-bearing capacity for cantilevered and spanning concrete. Infrastructure contractors standardize on glass-fiber-reinforced variants for high-cycle bridge applications.
- Foundations:Below-grade form systems face soil contact and moisture exposure challenges. Limited reuse potential constrains polymer adoption versus steel alternatives.
Walls holds the largest share; Flat Slabs climbs the fastest as residential repetition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. China's state-backed infrastructure contractors prioritize engineered durability for 200-cycle bridge applications, while India's commercial developers optimize for labor reduction in mid-rise towers. Southeast Asian residential markets experiment with rental economics that remain untested elsewhere.
China
Bridge deck pours and high-speed rail viaducts absorb the bulk of engineered polypropylene systems. SAMR-enforced GB standards mandate flame-retardant additives and dimensional tolerances that exclude lower-grade imports. Yangtze River Delta contractors concentrate procurement in Shanghai-Nanjing corridor state projects.
India
Commercial building verticals in Bengaluru and Mumbai drive lightweight formwork procurement for repetitive slab cycles. BIS certification protocols extend product launch timelines, advantaging domestic molders with established testing relationships. The PLI scheme subsidizes local manufacturing capacity expansion.
Germany
Glass-fiber-reinforced composites dominate public infrastructure tenders exceeding 200 reuse cycles. ECHA-mandated REACH compliance on halogenated flame retardants forces 12-18 month reformulation cycles. Rhine-Ruhr bridge contractors specify these materials for Autobahn expansion projects.
Vietnam
Ho Chi Minh City and Hanoi housing developers pilot rental fleet models for modular panel systems. Labor constraints in dense urban clusters accelerate adoption of pictographic-assembly designs. Logistics costs for panel recovery fall below replacement value thresholds in these metro corridors.
United States
Residential contractors in Texas and Florida test reusable polymer systems for slab-on-grade foundations. OSHA workplace safety protocols favor lightweight handling alternatives to steel in repetitive pour environments. Sun Belt population migration sustains housing start volumes that justify fleet investment.
Plastic Formwork Market Competitive Landscape
Capability concentration sits with specialized molders commanding polymer formulation expertise; scale advantage sits with diversified construction equipment suppliers leveraging rental infrastructure. The vendor base stratifies across three tiers: global fleet operators with service-network density, regional specialists in recycled polymer formulations, and domestic fabricators competing on PLI-subsidized cost structures. Dominant competitive moves include backward integration into resin compounding and geographic licensing agreements for mold technology transfer.
Within the global fleet-operator tier, PERI AG anchors recurring-revenue positioning through rental-contract penetration in Southeast Asian residential markets. Among European sustainability-focused specialists, Geoplast S.p.A. occupies a position defined by recycled polymer credentials in public tender environments. Chinese domestic fabricators including Hebei Zolo Construction Material Co., Ltd. exemplify PLI-scheme beneficiaries capturing share in price-sensitive commercial verticals.
| Leading Market Players |
|---|
| PERI AG |
| Hebei Zolo Construction Material Co., Ltd. |
| Moladi |
| NOE Formwork |
| Shandong Green Plastic Co., Ltd. |
| Beizhu Group |
| Nova Formworks |
| ULMA Group |
| Geoplast S.p.A. |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's container rate fluctuations compress margin structures for polypropylene formwork molders, concentrating pricing power among suppliers with captive resin compounding while forcing downstream tiering between certified premium systems and price-sensitive standard grades.
Pricing Analysis
Long-term offtake contracts with propylene suppliers anchor cost predictability for tier-one molders, while spot-market exposure punishes smaller fabricators. Price differentiation separates REACH-compliant European systems from BIS-certified Indian variants, with after-sales service bundling widening spreads. Cost compression in standard-grade modular panels intensifies as China's PLI-subsidized domestic capacity expands. Infrastructure contractors exhibit lowest price sensitivity, absorbing premium for 200-cycle glass-fiber-reinforced systems; residential developers in Southeast Asia resist anything beyond rental-model operating expenditures.
Supply Chain Analysis
Extended payment terms from 90 to 180 days now characterize supplier-finance arrangements for Southeast Asian rental fleet operators, straining working capital for molders without balance-sheet depth. Manufacturing concentrates in China, Germany, and India, with polypropylene resin, glass-fiber reinforcement, and flame-retardant additives as critical inputs. Single-source vulnerability sits with halogenated compound suppliers facing ECHA phase-out timelines. Distribution runs through manufacturer-direct rental contracts in emerging markets and specialized construction equipment distributors in mature economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plastic formwork sits in early-cycle expansion as modular systems displace timber on labor-constrained job sites, with India's PLI scheme and Vietnam's rental pilots accelerating penetration beyond historical infrastructure niches.
For Market Incumbents: Entrench fleet-service relationships through predictive maintenance contracts tied to RFID-tracked panel systems, while backward integration into polypropylene compounding defends margin structures against resin volatility. Steel formwork substitution in high-rise commercial towers above 30 stories threatens polymer penetration ceilings; counter by embedding BIM-integration capabilities that steel cannot replicate. For New Entrants and Emerging Players: Pursue India's BIS-certified commercial building segment where incumbent testing relationships create barriers but PLI subsidies compress capital requirements for domestic manufacturing. Vietnam's rental-model experimentation offers the most penetrable geography; enter through fleet-as-a-service partnerships with Ho Chi Minh City housing developers rather than equipment sales. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified construction equipment parents where formwork represents non-core revenue; specialized polymer formulation expertise commands scarcity premiums. Long-term viability frames around circular-economy credentialing as EU Extended Producer Responsibility frameworks mature. Watch ECHA's halogenated flame-retardant restriction timeline as inflection signal for reformulation-cost winners and losers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates PERI AG and Geoplast S.p.A. from propylene monomer volatility. |
| Rental Fleet Expansion | Recurring revenue contracts in Vietnam and Indonesia displace transactional equipment sales for mid-rise residential developers. |
| REACH Compliance Recertification | Phosphorus-based flame-retardant migration absorbs 12-18 month R&D costs but locks European public tender access. |
| BIM-Integrated Fleet Management | RFID-tagged panels with predictive maintenance unlock subscription contracts beyond hardware margins. |
| PLI-Subsidized Manufacturing Scale-Up | Domestic Indian capacity expansion under production-linked incentives captures commercial building procurement growth. |
Research Methodology
Operator-level perspectives from formwork fleet managers, bridge infrastructure contractors, residential project developers, polymer procurement leads, and BIS certification specialists anchored the qualitative base. Primary interviews triangulated with customs trade data on polypropylene resin flows, construction equipment import records, SEC filings from diversified industrial parents, and SAMR GB standards documentation. Bottom-up demand modeling across product architectures reconciled with top-down construction spending projections.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with CAGRs derived from elasticity-adjusted volume trajectories. Segmentation dimensions spanned product type, end-use vertical, reuse-cycle category, and regional regulatory cluster. Forecast inputs incorporated propylene price volatility bands, PLI subsidy uptake curves, and ECHA restriction implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in construction credit availability, housing start volumes, or infrastructure appropriations would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
Risers Market
Building & Construction Materials
Construction Elastomers Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Glass Curtain Wall Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
India Faucet Market