
 North America Fans and Blowers Market | 2026-2036
North America Fans and Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fans and Blowers Market Analytics
The U.S. Department of Energy's fan efficiency standards is rebalancing the cost-of-entry calculus for new entrants and incumbents alike. Greenheck Fan Corporation leverages vertical integration across its Wisconsin manufacturing base to sustain margin control. Twin City Fan Companies Ltd anchors its position through deep specialization in custom industrial configurations. Gardner Denver Holdings Inc competes by extending its technology leadership into oil-free blower architectures for sensitive process environments.
Fans and blowers are electromechanical devices engineered to move air or gas at specified pressures and flow rates, typically incorporating impellers, housings, and drive motors rated by static pressure, cubic feet per minute, and energy efficiency classifications. Their primary industrial purpose spans ventilation, combustion air supply, material conveying, and thermal management across commercial and process applications. Centrifugal fans occupy the mature core of the installed base where replacement cycles generate predictable revenue pools. Axial fans represent the fastest-growing product category as data center operators specify high-volume, low-pressure designs for rack-level cooling. The HVAC end-user segment concentrates margin capture in the premium tier where variable-speed electric drives command specification preference.
The U.S. Department of Energy, Natural Resources Canada, and OSHA collectively shape product efficiency mandates, safety certification requirements, and workplace exposure limits that dictate design parameters and market access conditions. The DOE's ongoing efficiency rulemakings are forcing manufacturers to redesign motor and impeller packages ahead of compliance deadlines. Natural Resources Canada's EnerGuide labeling program influences procurement specifications for commercial building projects across Canadian provinces. Stakeholders must monitor the trajectory of electrification standards and carbon intensity benchmarks that will determine which technology platforms retain specification authority across North American industrial and commercial buildouts.
Market Dynamics
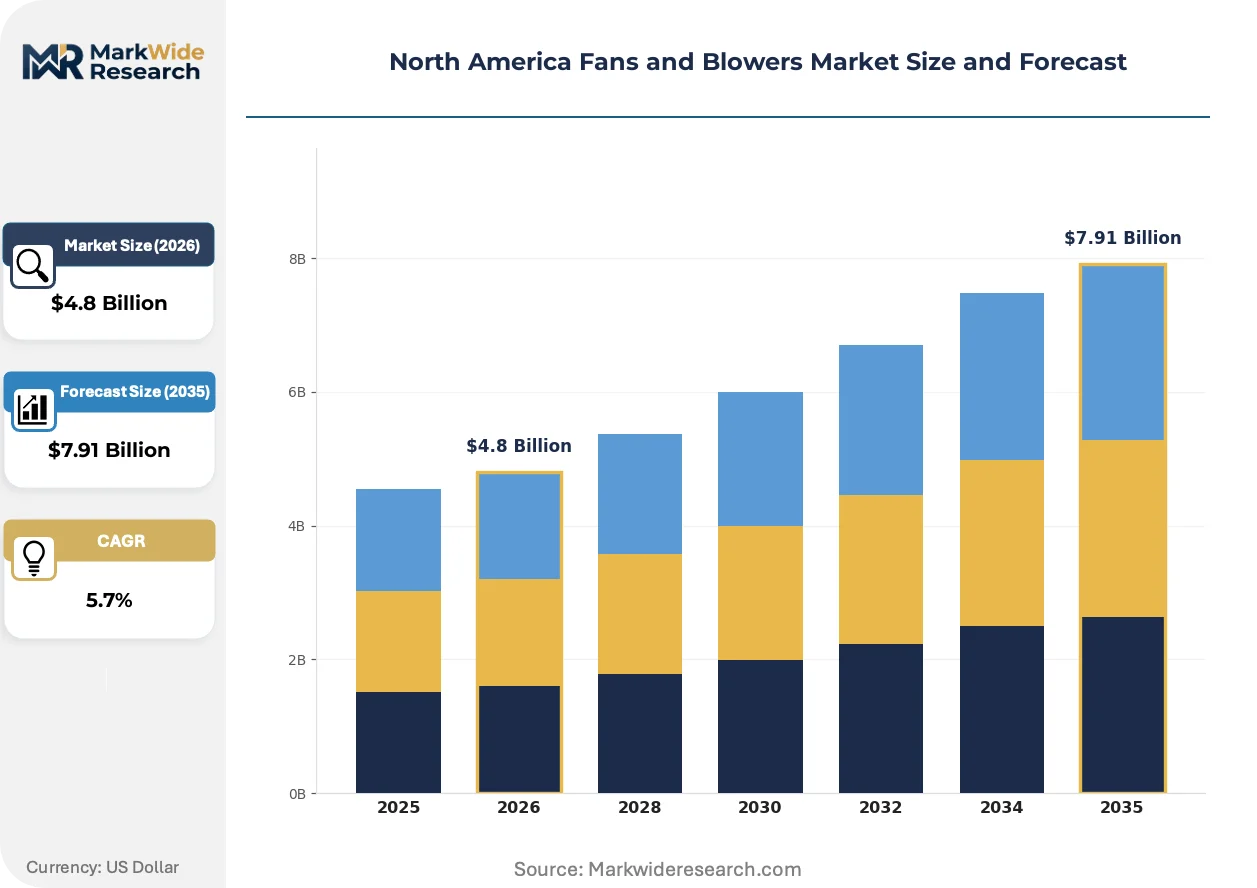
The U.S. Department of Energy's escalating fan efficiency regulations are compressing product development cycles and forcing motor-impeller redesigns across the installed base, while data center cooling demand concentrates specification power in hyperscale operators.
Growth Catalysts
- DOE Efficiency Rulemakings:Tightening motor performance standards are accelerating replacement demand across commercial HVAC and industrial process applications as compliance deadlines approach.
- Hyperscale Data Center Buildouts:Rack-level thermal management requirements across the United States and Canada are pulling high-volume axial fan specifications into premium performance tiers.
- Electrification of Industrial Heat:Process manufacturers in the Great Lakes corridor are retrofitting combustion air systems with electrically driven blowers to meet carbon intensity benchmarks.
Market Restraints
- Rare Earth Magnet Supply Concentration:Permanent magnet motor architectures depend on processed rare earth supply chains concentrated outside North America, exposing cost volatility and availability risk.
- Copper and Steel Input Volatility:Housing and winding material costs fluctuate with commodity markets, compressing margin predictability for custom industrial configurations.
- Technical Limitation of Airfoil Efficiency:Conventional blade geometries face theoretical efficiency ceilings that limit further energy recovery gains without radical design departures.
Strategic Opportunities
- Canadian Commercial Building Retrofit Wave:Natural Resources Canada's EnerGuide labeling program is creating specification pull for premium efficiency units across provincial procurement frameworks.
- Oil-Free Blower Architectures:Convergence of magnetic bearing technology with high-speed permanent magnet motors is opening sensitive process environments previously closed to lubricated designs.
- Digital Twin Integration:Predictive maintenance platforms are enabling aftermarket service revenue streams that extend customer lifetime value beyond hardware margins.
Industry Challenges
- Aerodynamics Simulation Talent Scarcity:Computational fluid dynamics expertise required for next-generation impeller design remains concentrated in aerospace and automotive sectors, creating hiring friction.
- DOE Certification Timeline Compression:Accelerated compliance deadlines are forcing simultaneous engineering validation and production tooling investment, straining mid-tier manufacturer balance sheets.
- Legacy Control System Integration:Variable frequency drive retrofits into existing building automation networks require protocol translation expertise that extends project timelines and erodes contractor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fans and Blowers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fans, Centrifugal Fans, Blowers, Mixed Flow Fans End User: Manufacturing, HVAC, Automotive, Residential Technology: Electric, Hydraulic, Pneumatic, Mechanical Application: Air Circulation, Ventilation, Cooling, Exhaust |
| Companies Covered | Greenheck Fan Corporation, Twin City Fan Companies Ltd, Acme Engineering and Manufacturing Corp, FläktGroup, Gardner Denver Holdings Inc, Airmaster Fan Company Inc, New York Blower Company, Howden Group, Continental Blower LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fans and Blowers Market Evolving Landscape
Active reshaping of the North American fans and blowers landscape centers on three vectors: intelligent control integration, regulatory-driven efficiency escalation, and procurement concentration among specification-consolidating end users.
Magnetic bearing technology is automating the elimination of mechanical contact in high-speed turbo blower applications. Pharmaceutical and food processing operators across the United States are specifying these architectures for contamination-sensitive environments. The technology is automating the displacement of traditional gearbox-driven systems in clean process segments.
The U.S. Department of Energy's ongoing fan efficiency rulemakings are mandating minimum motor performance thresholds that obsolete substantial portions of the installed base. Manufacturers must redesign core platforms ahead of compliance windows or forfeit specification authority in federal and state procurement channels. Centrifugal fan replacement cycles are compressing as facility operators accelerate retirement of non-compliant assets.
Hyperscale data center operators are consolidating specification authority through direct manufacturer relationships that bypass traditional distribution channels. Rack-level cooling procurement now routes through engineering teams at Amazon Web Services, Microsoft Azure, and Google Cloud rather than mechanical contractors. This pattern concentrates volume with suppliers capable of volume-scale customization and compresses margins for intermediaries unable to demonstrate direct OEM relationships.
North America Fans and Blowers Market Segmentation
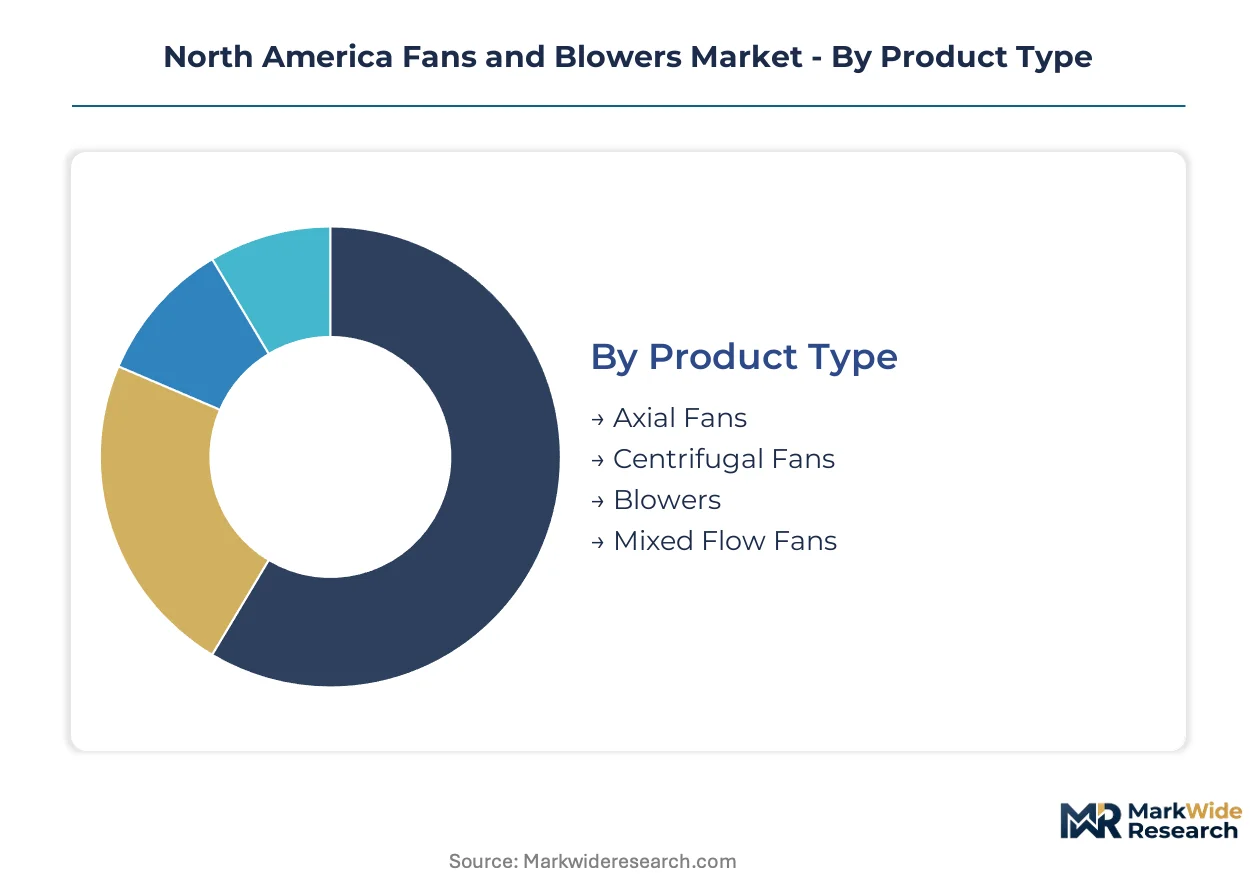
Segmentation in the North America fans and blowers market reveals how specification authority concentrates among end-users with direct engineering capabilities. Procurement patterns diverge sharply between commodity replacement cycles and custom-engineered deployments.
Product Type:
Supply concentration among Great Lakes manufacturers favors centrifugal platforms, while axial designs pull volume toward hyperscale data center corridors.
- Axial Fans:High-volume, low-pressure architectures dominate rack-level thermal management. Hyperscale operators in Northern Virginia and Dallas-Fort Worth specify these units for direct manufacturer relationships that bypass distribution channels.
- Centrifugal Fans:Radial impeller designs handle higher static pressures across industrial process applications. The Great Lakes manufacturing corridor sustains replacement demand from automotive OEMs and metal processors seeking DOE-compliant motor packages.
- Blowers:Positive-displacement and turbo configurations serve pneumatic conveying and combustion air supply.
- Mixed Flow Fans:Hybrid geometries merge axial capacity with centrifugal pressure characteristics for specialized HVAC retrofit applications.
Today's leader: Centrifugal Fans. Tomorrow's challenger: Axial Fans.
End User:
Margin capture stratifies by engineering sophistication, with specification authority migrating from mechanical contractors to in-house engineering teams.
- HVAC:Commercial building automation drives specification for variable-speed electric drives. Natural Resources Canada's EnerGuide labeling program pulls premium efficiency procurement across Ontario and British Columbia provincial frameworks.
- Manufacturing:Process industries in Michigan, Ohio, and Indiana retrofit combustion air systems with electrically driven blowers to meet carbon intensity benchmarks.
- Automotive:Paint booth ventilation and foundry exhaust systems require contamination-resistant architectures.
- Residential:New construction and replacement cycles concentrate in Sun Belt states with cooling-dominated loads.
HVAC commands current margin pools. Manufacturing presents the steepest expansion trajectory as electrification mandates accelerate.
Technology:
Drive system selection determines efficiency ceiling and maintenance burden across the installed base.
- Electric:Permanent magnet synchronous motors with variable frequency drives dominate new specifications. DOE efficiency rulemakings are obsoleting induction motor architectures ahead of compliance deadlines.
- Hydraulic:Fluid power drives persist in explosive atmosphere applications where electrical sparking presents ignition risk.
- Pneumatic:Compressed air motors serve isolated ventilation duties in remote mining and offshore platforms.
- Mechanical:Direct belt and gearbox drives retain niche positions in legacy industrial facilities with minimal automation infrastructure.
Electric platforms anchor specification authority. Hydraulic systems defend position in hazardous environment segments.
Application:
Functional purpose dictates pressure-flow operating points and materials of construction.
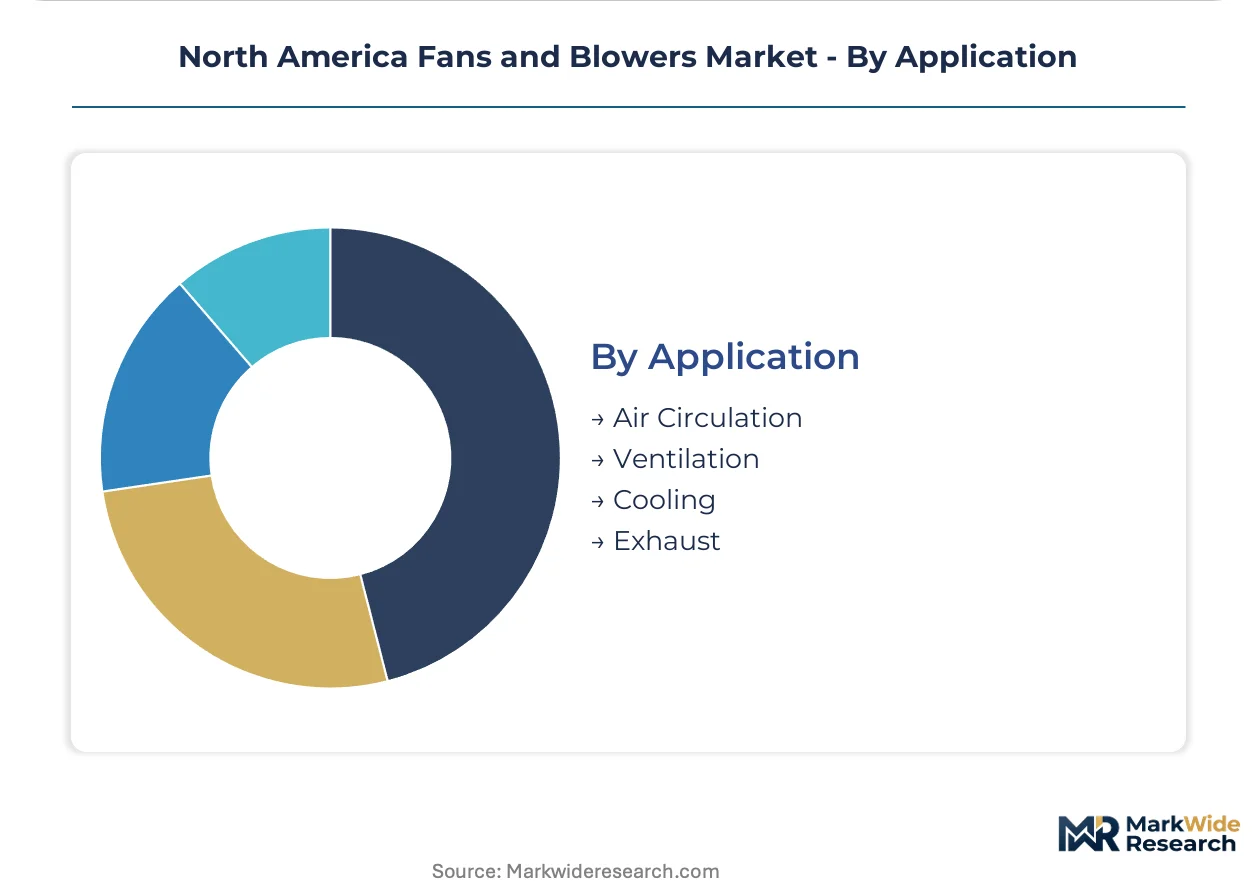
- Cooling:Thermal management applications span data center rack levels to industrial process heat rejection. Hyperscale operators consolidate procurement through engineering teams rather than mechanical contractors.
- Ventilation:Outdoor air supply and indoor air quality management drive commercial building specifications. OSHA workplace exposure limits dictate design parameters for industrial facilities.
- Air Circulation:Space conditioning and thermal uniformity applications serve agricultural and commercial greenhouse operations.
- Exhaust:Fume and particulate removal systems require corrosion-resistant coatings and spark-resistant construction for chemical processing environments.
Cooling captures premium pricing. Ventilation sustains volume through replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent concentrated in the Great Lakes manufacturing belt anchors North American production capacity for industrial-grade air movement equipment.
United States
Hyperscale data center buildouts in Northern Virginia and Dallas-Fort Worth pull high-volume axial fan specifications through direct OEM relationships. The Department of Energy's fan efficiency rulemakings are compressing replacement cycles across commercial HVAC and industrial process applications. Michigan, Ohio, and Indiana automotive clusters sustain demand for contamination-resistant paint booth ventilation systems.
Canada
Natural Resources Canada's EnerGuide labeling program is driving premium efficiency procurement across Ontario and British Columbia provincial building frameworks. The country's national energy regulator coordinates with provincial authorities to harmonize commercial efficiency standards. Toronto and Vancouver metropolitan areas concentrate retrofit demand from institutional and commercial building portfolios.
Mexico
Nearshoring manufacturing investments in Nuevo León and Baja California are expanding industrial ventilation requirements for automotive and electronics assembly operations. The country's federal energy efficiency standards for electric motors are tightening alignment with North American technical regulations. Monterrey anchors demand growth from maquiladora operations seeking DOE-compliant equipment for cross-border supply chains.
North America Fans and Blowers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base clusters around three strategic archetypes: vertically integrated full-line manufacturers, custom engineering specialists, and technology-focused subsystem suppliers. Consolidation pressure intensifies as efficiency regulations raise capital requirements for compliance certification. Dominant competitive moves include backward integration into motor manufacturing and strategic partnerships with hyperscale data center operators.
Among Great Lakes-based fabricators, Greenheck Fan Corporation and Twin City Fan Companies Ltd exemplify the vertically integrated archetype with captive manufacturing control. Gardner Denver Holdings Inc occupies a position representing technology-forward subsystem specialization in oil-free architectures.
| Leading Market Players |
|---|
| Greenheck Fan Corporation |
| Twin City Fan Companies Ltd |
| Acme Engineering and Manufacturing Corp |
| FläktGroup |
| Gardner Denver Holdings Inc |
| Airmaster Fan Company Inc |
| New York Blower Company |
| Howden Group |
| Continental Blower LLC |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators concentrated in Wisconsin and Minnesota anchor production capacity for industrial-grade centrifugal platforms, translating captive manufacturing control into pricing discipline that resists commoditization pressure from Asian imports. Their ownership structure insulates margin targets from quarterly earnings pressure, allowing sustained investment in DOE-compliant motor packages without reactive discounting.
Pricing Analysis
Bundled aftermarket service contracts versus unbundled equipment-only procurement splits buyer segments sharply across the North American installed base. Three-tier pricing structure across premium, standard, and economy levels stratifies by motor efficiency certification and variable-speed drive inclusion, with DOE compliance tiers commanding specification preference. Pricing pressure stems from copper and steel input volatility rather than competitive discounting, compressing margin predictability for custom industrial configurations. Mechanical contractors exhibit highest price sensitivity due to project-based bidding constraints, while hyperscale data center operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Chicago, Toronto, and Dallas operate hub-and-spoke patterns that position finished inventory within 48-hour delivery windows of Great Lakes manufacturing clusters and Southwest data center corridors. Supply concentration rests on China for processed rare earth magnets, Canada for aluminum housings, and domestic U.S. sources for electrical steel laminations. Single-source vulnerability in permanent magnet supply chains exposes cost volatility when export controls disrupt processed material flows. Distribution runs through authorized dealer networks for commercial HVAC replacement cycles, while direct OEM relationships dominate hyperscale data center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through permanent magnet motor cost curves declining against rising efficiency premiums, rewarding early compliance investment with specification lock-in.
For Market Incumbents: Lock in specification authority by accelerating backward integration into motor manufacturing before DOE compliance deadlines compress competitor response windows. Deepen aftermarket service platform penetration through predictive maintenance digital twins that extend customer lifetime value beyond hardware margins. Emerging subsystem specialists from Asia threaten premium positioning through magnetic bearing technology licensing. For New Entrants and Emerging Players: Mid-tier manufacturing facilities in the Great Lakes corridor lacking in-house engineering resources represent an underserved buyer archetype receptive to packaged retrofit solutions combining DOE-compliant drop-in replacements with installation support. White-space concentration sits in oil-free blower architectures for pharmaceutical and food processing operators seeking contamination-resistant specifications. Channel partnership with regional mechanical contractors offers lower customer acquisition cost than direct hyperscale pursuit. For Investors and Strategic Acquirers: Valuations sit cheapest among custom engineering specialists with captive CFD capability but limited scale. Long-term viability hinges on electrification mandate durability across industrial heat applications. Acquisition target archetype: mid-tier manufacturers with DOE certification progress but strained balance sheets from simultaneous engineering validation and production tooling investment. Monitor rare earth magnet export control announcements as inflection indicator for permanent motor architecture cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Captive supply of DOE-compliant permanent magnet motors insulates margin from rare earth price volatility. |
| Digital Twin Platform Development | Predictive maintenance capabilities convert one-time equipment sales into recurring aftermarket revenue streams. |
| Hyperscale Data Center Direct Partnership | Bypassing mechanical contractor channels concentrates volume with suppliers demonstrating rack-level customization capability. |
| Magnetic Bearing Technology Licensing | Oil-free architectures open pharmaceutical and food processing segments previously closed to lubricated designs. |
| Canadian Provincial Procurement Certification | EnerGuide alignment positions premium efficiency units for Ontario and British Columbia retrofit frameworks. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and distribution channel partners with secondary validation through DOE efficiency rulemaking dockets, Natural Resources Canada EnerGuide specifications, SEC 10-K filings of diversified industrial conglomerates, and customs trade data on motor and impeller imports. Triangulation across stakeholder perspectives and documentary sources addresses data gaps inherent in fragmented private-company reporting.
Input-output matrices map product type, end-user segment, drive technology, and application function against regional demand clusters and manufacturing capacity distribution. Segmentation dimensions modeled span centrifugal-axial-blower-mixed flow geometries, HVAC-manufacturing-automotive-residential end uses, electric-hydraulic-pneumatic-mechanical drive systems, and cooling-ventilation-circulation-exhaust applications. CAGRs derive from replacement cycle compression analysis, efficiency regulation compliance windows, and electrification investment trajectories across the projection horizon. Hyperscale data center capex disclosures and Great Lakes automotive production schedules inform volume assumptions.
Underlying measurement precision varies by segment; hyperscale data center cooling specifications carry tighter precision than dispersed residential replacement cycles due to consolidated procurement transparency. Forecasts reflect documented assumptions regarding DOE rulemaking timelines, rare earth supply continuity, and carbon intensity benchmark stringency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Ceramic Roller Bearings Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
Magnetorheological Finishing (MRF) Machine Market
Industrial Equipment
Slewing Bearing Market
Industrial Equipment
Roller Bearings Market
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
ROV Tether Management System Market