
 Compositing Equipment Market | 2026-2036
Compositing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Compositing Equipment Market Outlook
Market Context with Strategic Players
REACH compliance in Europe is repositioning the cost-of-entry calculus for thermal and chemical compositing systems sold into EU markets. Komptech GmbH leverages its German engineering base to dominate mechanical technology segments with heavy-duty grinder platforms. Green Mountain Technologies anchors North American demand through specialized composting and organic waste processing equipment. Kollvik Advanced Composting Solutions differentiates via advanced reactor designs that navigate stringent emissions standards across multiple jurisdictions.
Technical Definition and Structural Segments
Compositing equipment encompasses industrial machinery that blends, grinds, mixes, or thermally processes heterogeneous materials into uniform composite substrates, typically operating at throughput rates from 500 kg/hr to 50 tonnes/hr depending on rotor configuration and chamber geometry. These systems serve construction, automotive, and aerospace sectors by producing fiber-reinforced polymers, recycled aggregate binders, and thermal insulation boards. Mechanical technology leads in installed base across grinder and mixer categories where abrasive wear resistance determines equipment life cycles. Thermal technology represents the fastest-growing segment as aerospace manufacturers adopt out-of-autoclave curing systems for carbon fiber layups. Chemical technology occupies concentrated margin pools in electronics applications requiring sub-micron dispersion control for conductive polymer films.
Regulatory Framework and Forward Outlook
EPA emissions standards in the United States, EU Ecodesign requirements under the European Commission framework, and OSHA workplace exposure limits collectively shape equipment ventilation design, thermal efficiency benchmarks, and operator safety enclosures. The EU F-Gas Regulation specifically restricts fluorinated greenhouse gases used in certain thermal bonding processes, redirecting R&D investment toward infrared and induction heating alternatives. Stakeholders must monitor evolving state-level organic waste mandates in California, New York, and Washington to anticipate demand inflections for construction and contractor-facing composting systems.
Market Dynamics
Real-time rendering pipelines in film and streaming production are compressing post-production timelines from weeks to hours, forcing equipment vendors to integrate GPU-accelerated processing cores directly into compositing hardware.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandates for energy-efficient thermal processing are redirecting capital toward next-generation induction heating systems in German and French manufacturing facilities.
- Carbon fiber layup automation:Aerospace contractors in Washington State and Bavaria are retrofitting facilities with out-of-autoclave curing chambers to bypass autoclave bottlenecks.
- California SB 1383 organic waste mandates:Diversion requirements for food scraps and yard trimmings are accelerating municipal procurement of industrial-scale composting turners and in-vessel systems.
Market Restraints
- Specialized alloy supply concentration:Wear-resistant rotor steels for high-throughput grinders depend on limited German and Austrian metallurgical suppliers, creating input vulnerability.
- REACH chemical authorization delays:Extended substance evaluation timelines for bonding agents and thermal interface materials are freezing product development cycles for 18-24 months.
- Mechanical technology substitution:Thermal and chemical bonding methods are capturing applications previously served by mechanical mixing in electronics packaging and advanced composites.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Production-linked incentives for specialty chemicals and engineered materials are attracting compositing equipment vendors to establish local assembly for carbon fiber prepregs.
- Modular reactor skids:Containerized composting and thermal processing units are opening distributed deployment models for remote mining camps and island municipalities lacking centralized infrastructure.
- Infrared heating convergence with machine vision:Real-time thermal profiling integrated with automated layup heads enables closed-loop quality control in aerospace manufacturing cells.
Industry Challenges
- Cross-disciplinary engineering talent scarcity:Equipment manufacturers struggle to recruit specialists combining thermal engineering, materials science, and software-defined control systems.
- Legacy SCADA integration complexity:Brownfield facilities require costly protocol bridging to connect new compositing equipment with existing plant-wide automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compositing Equipment Market |
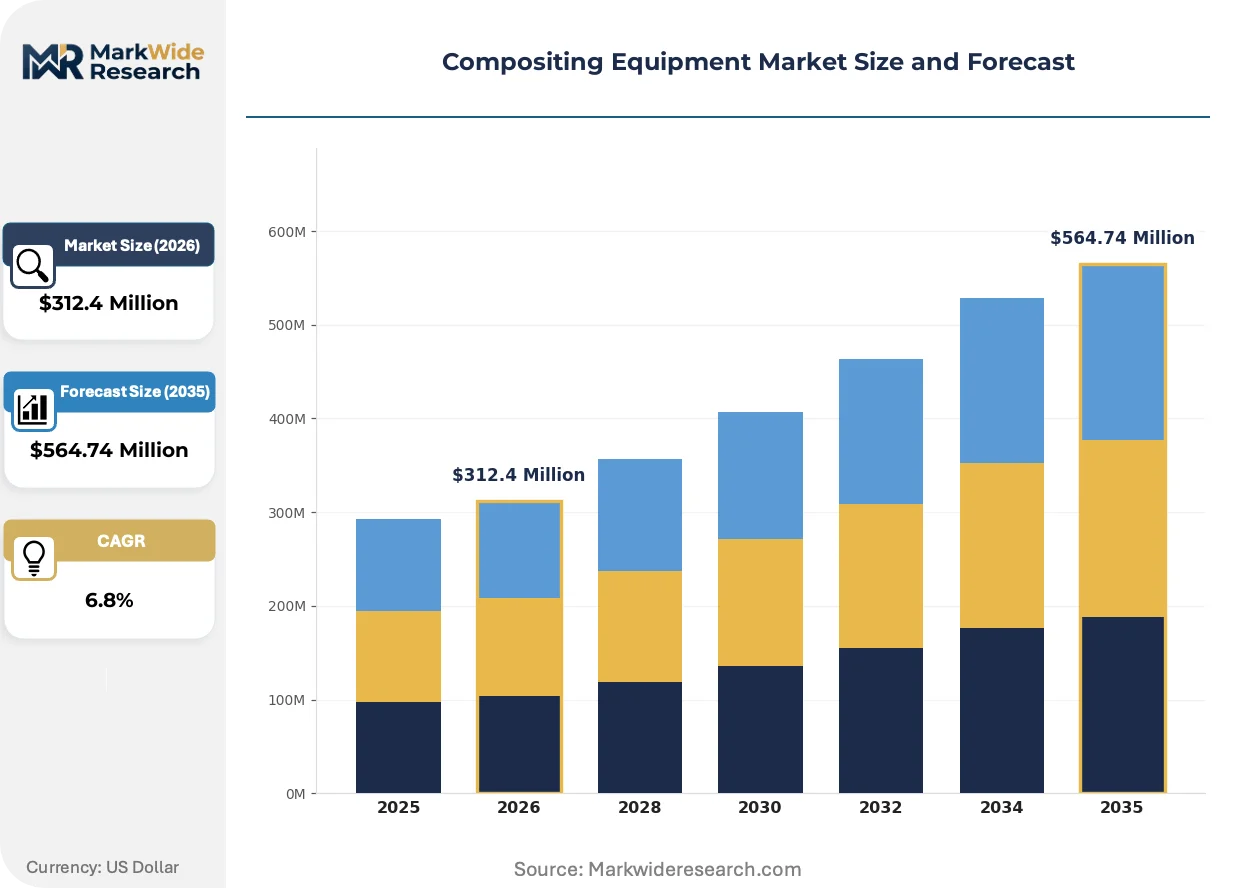
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mixers, Grinders, Blenders, Sifters Technology: Mechanical, Chemical, Thermal, Electrical Application: Construction, Automotive, Aerospace, Electronics End User: Manufacturers, Contractors, OEMs, Researchers |
| Companies Covered | Midwest Biosystems, Green Mountain Technologies, HotRot, Kollvik Advanced Composting Solutions, BDP Industries, Vermeer Corporation, Komptech GmbH, Compost Systems, Ecoverse Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compositing Equipment Market Strategic Shifts
Software-defined thermal processing is dissolving the boundary between hardware and control layers, enabling compositing equipment to reconfigure operating parameters without mechanical retrofit.
Infrared radiation heating systems with programmable wavelength selectivity are overtaking conventional convective ovens in carbon fiber composite manufacturing. Boeing and Airbus tier-one suppliers in Kansas and Hamburg are installing these systems to reduce cure cycle times by forty percent. The technology is compressing capital equipment footprints while eliminating thermal mass lag that constrains batch-to-batch flexibility.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in thermal bonding applications, redirecting equipment design toward induction and microwave alternatives. Manufacturers of electronics substrates and battery enclosures are reformulating process recipes to accommodate fluorinated gas-free curing. German equipment builders are capturing early-mover advantage by certifying systems under the new Ecodesign requirements before 2027 enforcement deadlines.
Equipment-as-a-service contracting is replacing outright purchase for mid-scale composting and waste processing operators. Third-party financiers and OEM captive leasing arms are assuming residual value risk while bundling maintenance and software updates into per-tonne processing fees. This model is penetrating fastest among California municipal waste authorities and British Columbia organic waste processors facing capital budget constraints.
Compositing Equipment Market Segmentation
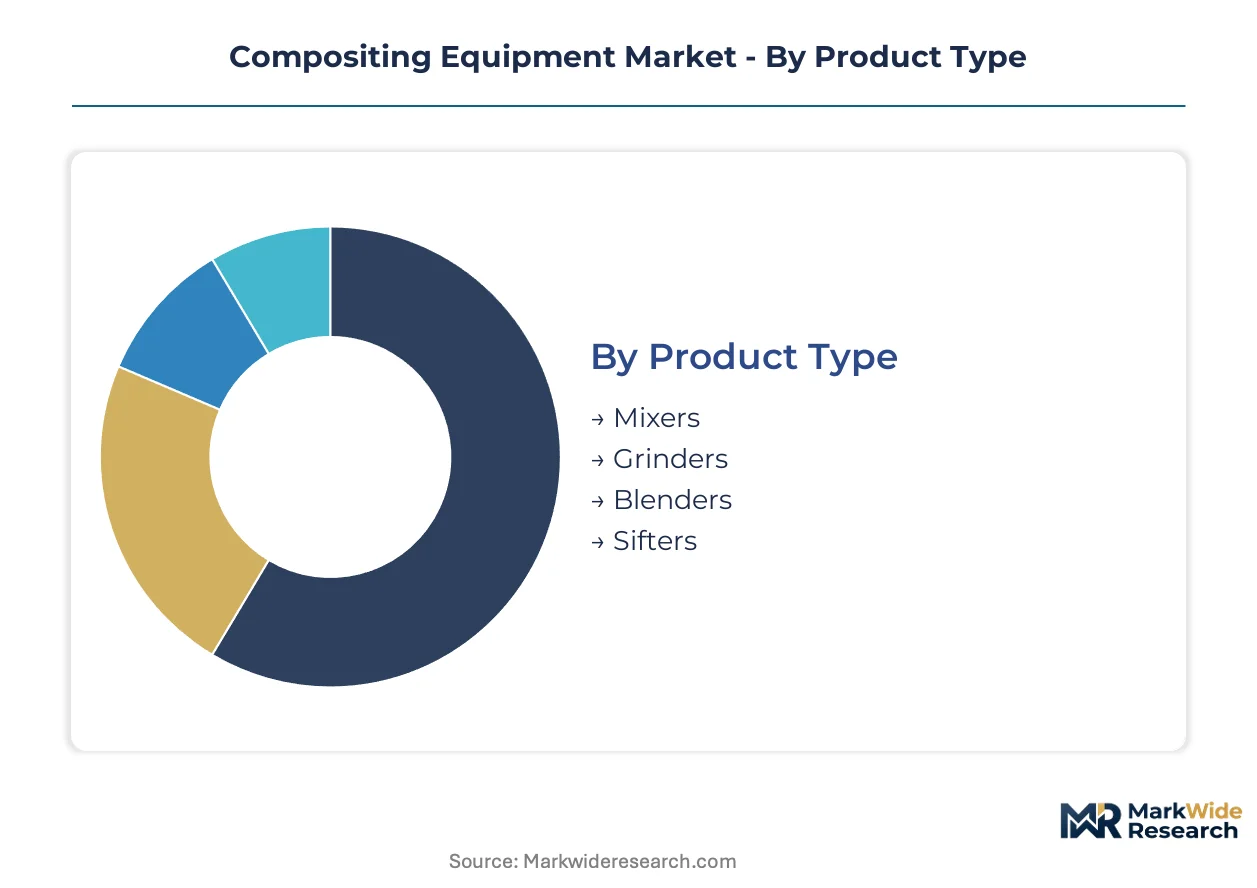
Compositing equipment vendors configure product portfolios around distinct processing intensities and regulatory exposure profiles. Segment boundaries determine pricing architecture, service attach rates, and geographic prioritization for field engineering resources.
Product Type:
Supply concentration in high-wear components favors vendors with captive metallurgy capabilities or long-term offtake agreements with specialized foundries.
- Mixers:Twin-shaft and planetary configurations dominate construction aggregate blending, with rotor speeds adjustable between 20-60 RPM for rheology-sensitive polymer matrices. California concrete precasters and German precast concrete specialists drive replacement demand as abrasion-resistant liner technologies extend service intervals.
- Grinders:Heavy-duty hammer mills and attrition systems process construction demolition waste and organic feedstocks at throughputs exceeding 30 tonnes per hour. Komptech GmbH's German engineering base anchors European supply, while Green Mountain Technologies serves North American composting operators facing California SB 1383 diversion mandates.
- Blenders:Ribbon and paddle designs homogenize powder-liquid suspensions for specialty chemicals. These units concentrate in Indian pharmaceutical manufacturing clusters benefiting from PLI scheme incentives.
- Sifters:Vibratory and trommel configurations classify particle sizes for recycled aggregate streams. Demand clusters around construction waste processing facilities in Bavaria and Ontario.
Grinders absorb the bulk of installed capacity; mixers are expanding most quickly as precast concrete automation accelerates.
Technology:
Cost tier stratification separates capital-intensive thermal systems from mechanically simpler alternatives, with chemical technology occupying narrow premium niches.
- Mechanical:Direct-drive rotor systems with hardened tool steel components handle abrasive construction and waste streams. These platforms dominate installed base across grinder and mixer categories where wear-part replacement economics determine total cost of ownership.
- Thermal:Out-of-autoclave curing chambers and infrared bonding systems serve aerospace carbon fiber layup operations in Washington State and Hamburg. Boeing and Airbus tier-one suppliers adopt these to bypass autoclave bottlenecks and compress cure cycles.
- Chemical:Sub-micron dispersion control for conductive polymer films and battery electrolytes concentrates in electronics substrate manufacturing. REACH authorization delays for bonding agents freeze product development cycles for 18-24 months.
- Electrical:Induction and microwave heating alternatives gain traction as EU F-Gas Regulation phases down hydrofluorocarbon use. German equipment builders certify systems under Ecodesign requirements ahead of enforcement deadlines.
Mechanical technology carries the largest installed base; thermal technology climbs the fastest as aerospace automation spreads.
Application:
Volume concentration in mature construction sectors contrasts with margin-rich aerospace and electronics verticals requiring precision thermal control.
- Construction:Recycled aggregate binders and fiber-reinforced polymer rebar production dominate unit shipments. German industrial manufacturing belts and California infrastructure clusters anchor demand for heavy-duty processing platforms.
- Aerospace:Carbon fiber prepreg manufacturing demands out-of-autoclave curing systems with programmable thermal profiles. Kansas and Hamburg production facilities retrofit existing layup cells to eliminate autoclave queue constraints.
- Automotive:Lightweight composite structural components for electric vehicle battery enclosures drive specification tightening. OEMs in Bavaria and Michigan specify equipment capable of processing thermoplastic composites at automotive cycle times.
- Electronics:Thermal interface materials and conductive polymer films require sub-micron dispersion control. This segment concentrates margin pools where chemical technology commands premium pricing.
Construction claims the majority of unit volume; aerospace generates the steepest expansion trajectory as curing automation proliferates.
End User:
Customer type determines procurement modality, with contractors favoring equipment-as-a-service and OEMs demanding integrated quality assurance systems.
- Manufacturers:Integrated production facilities in automotive and electronics verticals specify equipment with SCADA-compatible control architectures. These buyers prioritize throughput consistency and batch traceability over capital cost minimization.
- Contractors:Construction and waste processing operators face capital budget constraints and volatile project pipelines. Equipment-as-a-service contracting penetrates fastest among California municipal waste authorities and British Columbia organic waste processors.
- OEMs:Tier-one aerospace and automotive suppliers demand closed-loop quality control with machine vision integration. Infrared heating convergence with automated layup heads enables real-time thermal profiling in Kansas and Hamburg manufacturing cells.
- Researchers:National laboratories and university composites centers pilot novel processing parameters. These users drive early adoption of software-defined thermal processing and modular reactor skid configurations.
Manufacturers represent the largest addressable base; contractors are gaining share fastest as service-based procurement models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for compositing equipment clusters in Germany's industrial manufacturing belt and California's entertainment production corridor, with aerospace automation in Washington State and Bavaria accelerating thermal system procurement.
United States
California SB 1383 organic waste mandates drive municipal procurement of industrial-scale composting turners, while EPA emissions standards shape ventilation design for thermal processing equipment. Film studios in Los Angeles deploy real-time compositing pipelines with GPU-accelerated hardware. Aerospace contractors in Washington State retrofit facilities with out-of-autoclave curing chambers to eliminate autoclave bottlenecks.
Germany
EU Ecodesign for Sustainable Products Regulation redirects capital toward induction heating systems in manufacturing facilities across Baden-Württemberg and North Rhine-Westphalia. REACH compliance repositioning raises cost-of-entry for thermal and chemical systems sold into domestic markets. Hamburg hosts tier-one Airbus suppliers adopting infrared bonding systems to compress carbon fiber cure cycles.
India
PLI scheme incentives for specialty chemicals and engineered materials attract equipment vendors to establish local assembly operations for carbon fiber prepregs. CDSCO and BIS certification requirements influence equipment specification for pharmaceutical manufacturing clusters. Maharashtra and Gujarat industrial belts concentrate demand for powder-liquid blending systems in active pharmaceutical ingredient production.
Canada
British Columbia organic waste processors face capital budget constraints that accelerate equipment-as-a-service contracting penetration. Health Canada and PMRA regulations govern thermal processing parameters for agricultural and food-grade applications. Ontario construction waste processing facilities anchor demand for heavy-duty grinder platforms handling recycled aggregate streams.
France
ANSM oversight of pharmaceutical manufacturing equipment combines with EU F-Gas Regulation phase-down to redirect thermal bonding process design. Île-de-France hosts research institutions piloting software-defined thermal processing and modular reactor configurations. Auvergne-Rhône-Alpes automotive suppliers specify thermoplastic composite processing equipment for electric vehicle battery enclosures.
Compositing Equipment Market Competitive Environment
German engineering houses anchor one tier; North American waste processing specialists hold another in a market structured around regional regulatory expertise and application-specific metallurgy capabilities. Three strategic archetypes dominate: European mechanical technology builders with captive wear-component supply, North American composting equipment providers aligned with state-level organic waste mandates, and aerospace-focused thermal system integrators serving autoclave bypass demand. Competitive moves concentrate on geographic expansion into India's PLI-subsidized manufacturing zones and portfolio diversification toward equipment-as-a-service contracting models.
Within the German-engineered tier, Komptech GmbH exemplifies heavy-duty grinder platform specialization, while Green Mountain Technologies occupies a position among North American composting and organic waste processing equipment providers. Kollvik Advanced Composting Solutions represents the advanced reactor design segment navigating multi-jurisdictional emissions standards.
| Leading Market Players |
|---|
| Midwest Biosystems |
| Green Mountain Technologies |
| HotRot |
| Kollvik Advanced Composting Solutions |
| BDP Industries |
| Vermeer Corporation |
| Komptech GmbH |
| Compost Systems |
| Ecoverse Industries |
| Others |
Value Chain & Pricing Dynamics
Municipal waste authorities in California and British Columbia concentrate procurement power through equipment-as-a-service contracting, compressing capital expenditure into per-tonne processing fees that reshape vendor pricing architectures. This buyer consolidation favors vendors bundling maintenance, software updates, and residual value risk into subscription-like structures rather than transactional hardware sales.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations as aerospace contractors in Washington State and Hamburg demand rapid deployment of out-of-autoclave curing chambers to bypass autoclave bottlenecks. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated systems with machine vision from contractor-facing units with basic SCADA compatibility. Cost compression in the standard tier is intensifying because REACH authorization delays for bonding agents freeze product development cycles. Contractors facing capital budget constraints exhibit highest price sensitivity, while tier-one aerospace suppliers prioritize throughput consistency over capital cost minimization.
Supply Chain Analysis
Freight costs for wear-resistant rotor steels from German and Austrian metallurgical suppliers elevate total landed costs for North American grinder manufacturers, creating geographic price dispersion across regional markets. Supply concentrates in Germany for heavy-duty mechanical platforms, the United States for composting and organic waste systems, and India for pharmaceutical blending equipment under PLI scheme incentives. Component dependencies include hardened tool steel rotors, induction heating coils, and emissions control catalysts. Single-source vulnerability in specialized alloy supply creates input risk. Distribution runs through OEM direct sales for integrated manufacturing facilities and third-party financiers for equipment-as-a-service contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign for Sustainable Products Regulation erects a compliance moat that advantages German equipment builders already certifying induction heating systems ahead of enforcement deadlines, raising cost-of-entry for non-compliant competitors.
For Market Incumbents: Lock in captive metallurgy capabilities through long-term offtake agreements with Austrian and German foundries, insulating against specialized alloy supply concentration. Deepen software-defined thermal processing expertise to defend against thermal technology substitution displacing mechanical mixing in electronics packaging. Prioritize certification investment under EU F-Gas Regulation phase-down timelines to maintain market access. For New Entrants and Emerging Players: Modular reactor skids with containerized deployment models offer a technology-first wedge into remote mining camps and island municipalities lacking centralized infrastructure. Target British Columbia and California municipal waste authorities facing capital budget constraints as the most penetrable buyer segment. Pursue equipment-as-a-service go-to-market positioning to bypass upfront capital barriers. For Investors and Strategic Acquirers: The window for entry favors aerospace-focused thermal system integrators with certified out-of-autoclave curing platforms serving Boeing and Airbus tier-one suppliers. Long-term viability hinges on exposure to carbon fiber automation trends and regulatory tailwinds from EU Ecodesign mandates. Monitor India's PLI scheme incentive disbursement velocity as an inflection indicator for specialty chemicals and engineered materials demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wear-Component Supply | Captive metallurgy capabilities from Austrian and German foundries reduce input vulnerability for grinder manufacturers. |
| EU Ecodesign Certification Program | German equipment builders capture early-mover advantage ahead of F-Gas Regulation enforcement deadlines. |
| Equipment-as-a-Service Launch | California municipal waste authorities adopt per-tonne contracting to bypass capital budget constraints. |
| Infrared Heating Platform Integration | Boeing and Airbus tier-one suppliers in Kansas and Hamburg compress cure cycles by forty percent. |
| Joint Venture for Indian PLI Access | Local assembly operations in Maharashtra and Gujarat serve carbon fiber prepreg demand under specialty chemicals incentives. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and municipal waste authority equipment managers. EPA emissions standards documentation, EU Ecodesign regulatory texts, and California SB 1383 implementation reports provided policy-side validation. Bottom-up equipment shipment tallies and top-down end-use demand estimates underwent cross-referencing to ensure consistency.
Data-stream reconciliation across product type, technology, application, and end-user dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectories weighted by installed base evolution and replacement cycle timing. Aerospace automation penetration rates, organic waste diversion mandate compliance deadlines, and REACH authorization pipeline status served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments, abrupt commodity price shocks in specialty steel alloys, and geopolitical disruptions to EU-German manufacturing supply chains. Forecasts reflect documented assumptions about technology substitution rates and compliance timeline adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Industrial Refrigeration Systems Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
Industrial Marking Equipment Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Global Dosing Systems Market
Industrial Equipment
Global Industrial Weighing Machines Market
Industrial Equipment
Global Linear Bearings Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Laser Ablation Systems Market
Industrial Equipment
Liquid Cold Plates Market
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Micro Motor Market
Industrial Equipment
Europe Fusion Splicer Market