
 Screw Air End Market | 2026-2036
Screw Air End Market Size, Share, and Industry Trends Forecast 2026-2036
Screw Air End Market Analytics
OEM-direct supply channels for compressor packages is reconfiguring as Asian machinery builders build in-house screw air end capabilities. Atlas Copco leverages its aftermarket service density to defend installed-base revenue streams. Ingersoll Rand anchors North American demand through vertical integration into oil-free compressor systems. Kaeser Kompressoren differentiates via energy-efficient variable speed drive configurations that target EU industrial efficiency mandates.
A screw air end is the precision-machined rotating assembly within a rotary screw compressor, consisting of interlocking male and female rotors typically manufactured from high-grade cast iron or forged steel with tolerances below 5 microns, converting mechanical power into compressed air for continuous-duty industrial processes. Screw compressors dominate volume shipments due to their reliability in 24/7 manufacturing environments, while oil-free technology commands premium positioning where food safety and pharmaceutical purity standards apply. Variable speed drive adoption is accelerating as end users prioritize energy recovery over fixed-speed baseload operation.
ISO 8573-1 air purity classes and EU Ecodesign regulations constrain product entry by mandating minimum efficiency indexes and oil carryover limits. The US Department of Energy compressor efficiency standards and China's GB 19153 energy labeling together shape global product development roadmaps. Stakeholders must monitor how regional carbon border adjustments redefine total cost of ownership calculations for imported compressor packages.
Market Dynamics
The screw air end market is experiencing structural reconfiguration as captive production capabilities among Asian machinery builders erode traditional OEM-direct supply channels, compressing margins for independent component suppliers while reshaping aftermarket service economics.
Growth Catalysts
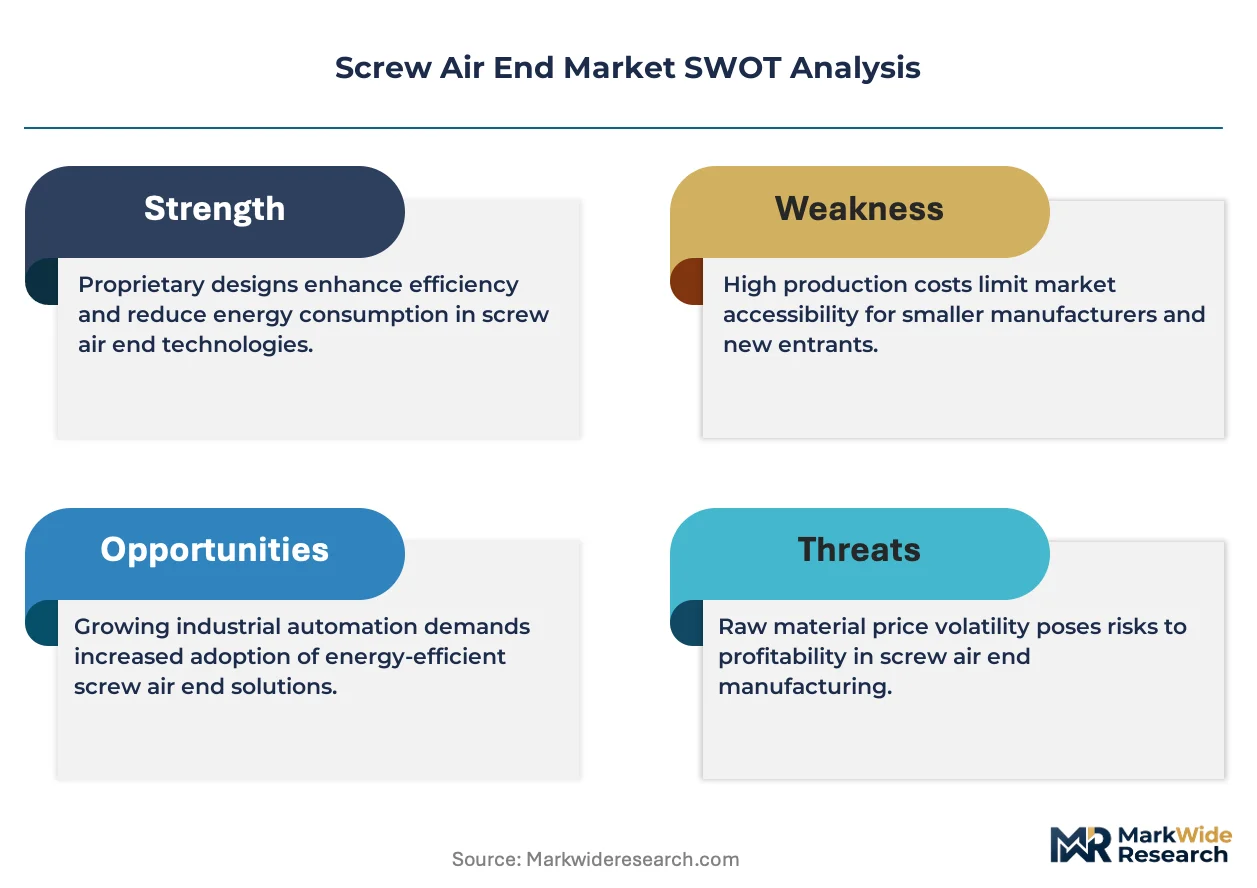
- ISO 8573-1 Purity Mandates:Stricter oil-free compressed air standards in food processing and pharmaceutical manufacturing are forcing end users toward advanced screw air end designs with enhanced sealing and coating technologies.
- Southeast Asian Automation Infrastructure:Manufacturing plants across Vietnam, Thailand, and Indonesia are expanding compressed air networks to support precision automation lines, creating sustained demand for high-duty-cycle rotary screw systems.
- EU Ecodesign Efficiency Directives:Minimum efficiency index requirements are accelerating replacement cycles for legacy fixed-speed compressors with variable speed drive configurations that recover energy during partial-load operation.
Market Restraints
- High-Grade Alloy Input Volatility:Forged steel and specialized cast iron alloys with sub-5-micron machining tolerances face price instability from concentrated metallurgical supply chains.
- Precision Manufacturing Concentration:Grinding and profile machining capabilities for interlocking rotors remain concentrated among German and Japanese machine tool suppliers, creating single-source dependencies.
- Centrifugal Compressor Substitution:Oil-free centrifugal systems are capturing demand in large-scale continuous-flow applications above 500 kW, compressing addressable market for screw-based solutions in heavy process industries.
Strategic Opportunities
- India Industrial Acceleration:PLI scheme incentives for domestic manufacturing and BIS energy labeling implementation are creating first-mover advantages for localized screw air end assembly operations.
- Hydrogen Compression Integration:Convergence of screw compression technology with electrolyzer systems and fuel cell infrastructure is opening specialized high-pressure, contamination-sensitive applications.
- Digital Retrofit Channel:IoT-enabled condition monitoring and predictive maintenance services represent unbundled revenue streams separate from hardware sales, targeting installed bases with aftermarket telemetry upgrades.
Industry Challenges
- Precision Machining Talent Scarcity:Profile grinding specialists and rotor dynamics engineers with experience in sub-micron tolerance manufacturing are in critically short supply across all major production regions.
- Multi-Certification Timeline Compression:Simultaneous compliance with China's GB 19153 energy labeling, EU CE machinery directives, and US OSHA pressure vessel codes extends product validation cycles by 18-24 months.
- Legacy Control System Integration:Modern variable speed drives must interface with decades-old plant SCADA architectures, creating commissioning complexity and field service escalation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screw Air End Market |
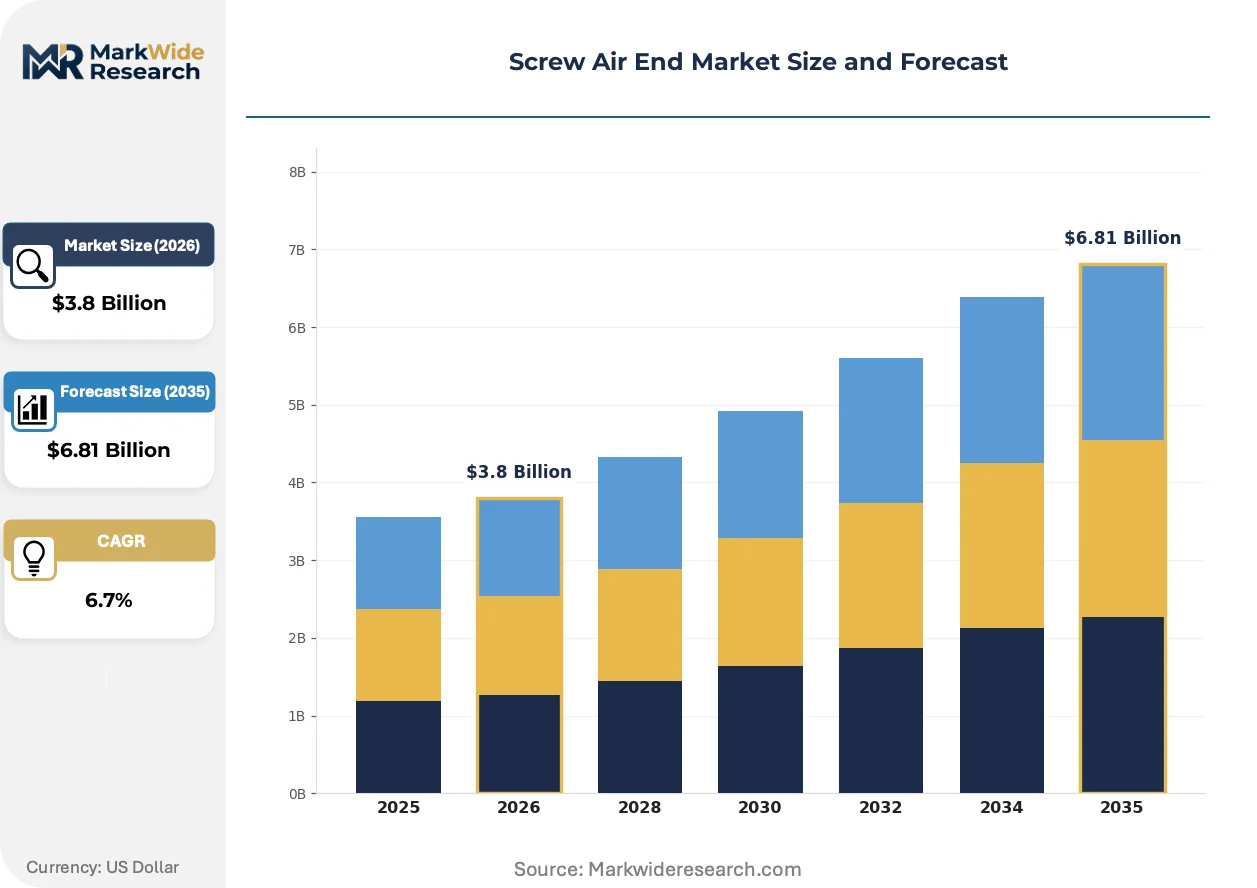
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Compressors, Piston Compressors, Centrifugal Compressors, Rotary Vane Compressors Application: Manufacturing, Oil & Gas, Automotive, Construction End User: Industrial, Commercial, Residential, Agricultural Technology: Oil-injected, Oil-free, Variable Speed Drive, Low Pressure |
| Companies Covered | Atlas Copco, Ingersoll Rand, Hitachi, Kaeser Kompressoren, IHI Rotating Machinery Engineering, ELGi, Kobelco Construction Machinery, ANEST IWATA Corporation, Fusheng, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screw Air End Market Evolving Landscape
Permanent magnet motor integration and advanced rotor coating chemistries are actively displacing conventional induction motor and uncoated steel designs, compressing the total cost of ownership calculus for end users while elevating performance benchmarks across industrial compressed air systems.
Magnetic bearing technology eliminates mechanical contact in high-speed rotation, enabling oil-free operation without traditional gearbox or lubrication systems. Pharmaceutical manufacturers and semiconductor fabs are adopting these configurations for ISO Class 0 air purity requirements. Fixed-speed cast iron architectures with splash lubrication are rendering obsolete in applications where contamination risk carries regulatory or product liability exposure.
The US Department of Energy compressor efficiency standards and China's GB 19153 energy labeling together mandate minimum specific power consumption thresholds that disqualify legacy fixed-speed designs from new installation eligibility. Equipment purchasers in both jurisdictions now face regulatory pressure to specify variable speed or permanent magnet configurations. Multinational industrial gas suppliers are harmonizing procurement specifications across their US and Chinese facilities to simplify compliance.
Compressed air as-a-service contracting is displacing traditional capital purchase models in energy-intensive manufacturing verticals. End users in automotive stamping and textile processing are transferring operational risk to compressor OEMs through performance-based agreements indexed to delivered air volume and quality. Germany and Japan exhibit the deepest penetration of this model, with chemical processors leading adoption due to their continuous-duty operational profiles and internal carbon accounting requirements.
Screw Air End Market Segmentation
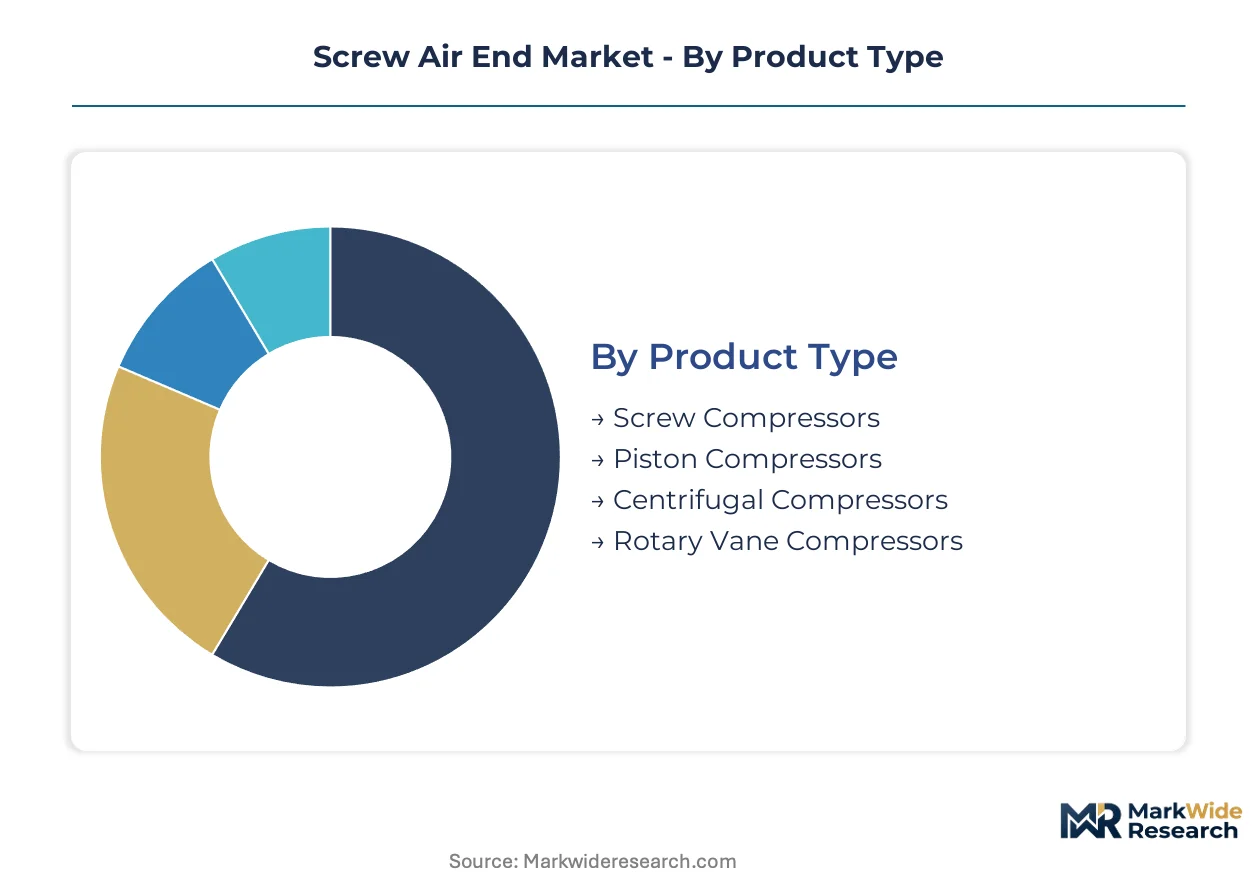
Screw air end configurations vary dramatically in replacement frequency, with oil-free precision assemblies cycling every 8-12 years while commodity oil-injected units turn over faster in high-duty environments. Understanding these velocity differentials helps suppliers calibrate inventory and service attach rates across the installed base.
Product Type:
Cycle times diverge sharply: piston and rotary vane units require most frequent rebuilds due to wear-prone sealing elements, while centrifugal and screw architectures sustain longer intervals between major overhauls.
- Screw Compressors:Interlocking helical rotors machined to sub-5-micron tolerances deliver continuous-duty compressed air with minimal pulsation. Manufacturing plants in Vietnam and Thailand specify these for 24/7 automation lines where unscheduled downtime carries six-figure hourly costs.
- Piston Compressors:Reciprocating crankshaft-driven pistons with ring-sealed cylinders generate intermittent high-pressure output suited to intermittent duty cycles. Automotive repair shops and small machine shops across India favor these for capital-constrained deployments despite higher maintenance burdens.
- Centrifugal Compressors:Dynamic compression via high-speed impellers serves continuous-flow applications above 500 kW in petrochemical and steel processing.
- Rotary Vane Compressors:Eccentric rotor with sliding vanes provides compact oil-flooded compression for mobile and portable equipment.
Screw compressors dominate installed base. Centrifugal compressors are where expansion concentrates in heavy process industries.
Application:
Cost-tier stratification separates precision-critical pharmaceutical and semiconductor applications from price-sensitive construction and general manufacturing deployments.
- Manufacturing:Precision automation lines demand ISO 8573-1 Class 0 or Class 1 compressed air with oil carryover below 0.01 mg/m³. Food processors in Germany and pharmaceutical manufacturers in Switzerland specify oil-free screw air ends to eliminate contamination risk in direct product contact applications.
- Oil & Gas:Upstream production and downstream refining require explosion-proof configurations rated for hazardous area classifications. Offshore platforms in the North Sea and Gulf of Mexico specify corrosion-resistant coatings and redundant sealing systems for salt-laden environments.
- Automotive:Stamping and paint operations consume high-volume compressed air with strict moisture control for surface finish quality.
- Construction:Portable diesel-driven units prioritize durability over efficiency in temporary and mobile deployments.
Manufacturing dominates installed base. Oil & Gas is where expansion concentrates amid upstream infrastructure renewal.
End User:
Customer-type segmentation reveals divergent procurement sophistication, with industrial buyers negotiating performance-based contracts while residential and agricultural segments remain transaction-oriented.
- Industrial:Continuous-process manufacturers with internal carbon accounting and energy management systems specify variable speed drives and permanent magnet motors to minimize specific power consumption. Chemical processors in Germany and Japan lead adoption of compressed-air-as-a-service contracting models.
- Commercial:Facility operators with intermittent demand patterns prioritize first-cost economics over lifecycle efficiency.
- Residential:Small-scale applications including home workshops and hobbyist equipment represent minimal screw air end penetration.
- Agricultural:Irrigation and grain handling systems utilize basic fixed-speed configurations with limited maintenance infrastructure.
Industrial dominates installed base. Commercial is where expansion concentrates as facility management outsourcing accelerates.
Technology:
Margin structure varies by technical complexity, with oil-free and magnetic bearing configurations commanding substantial premiums over commodity oil-injected architectures.
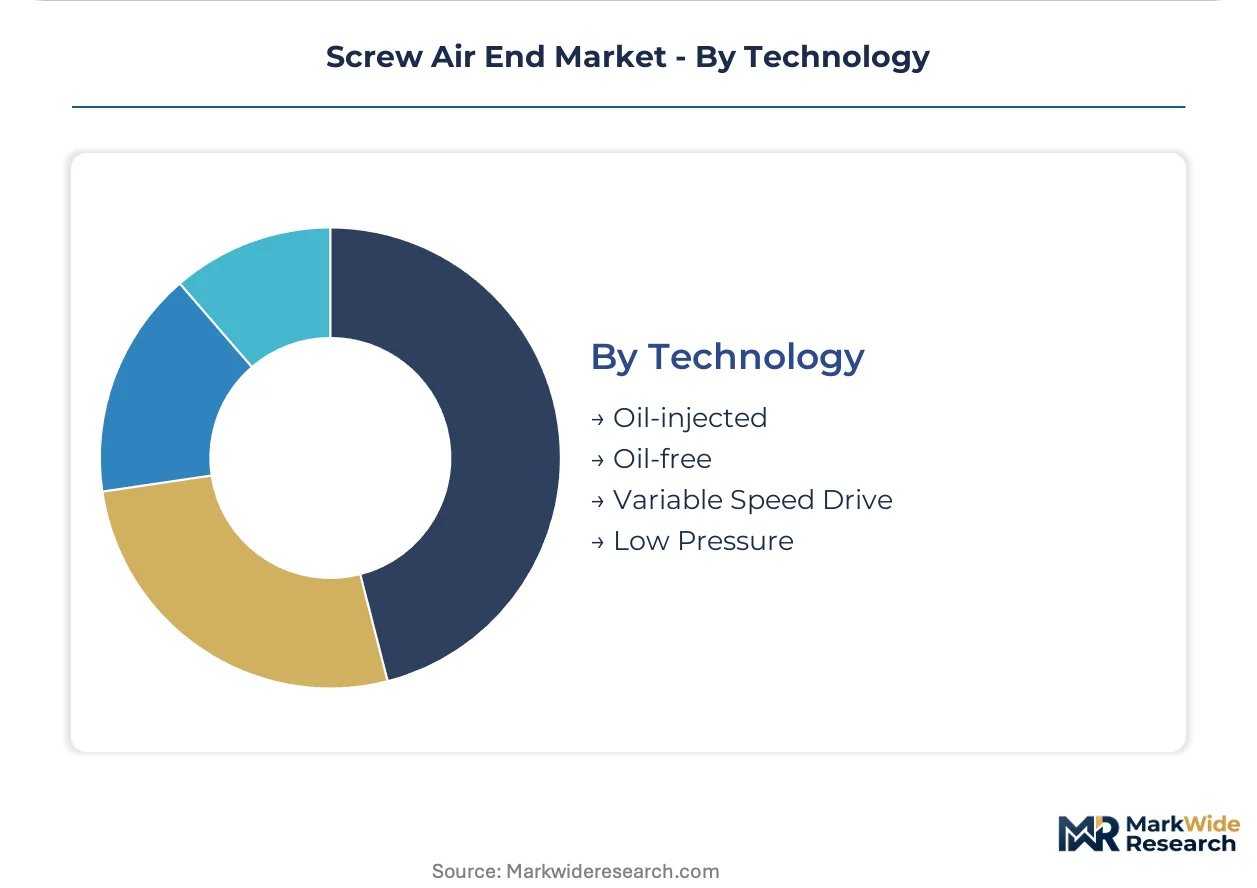
- Oil-free:Dry-running rotors with precision timing gears and advanced coating chemistries eliminate lubricant contact with compressed air. Semiconductor fabs in Taiwan and pharmaceutical manufacturers in Ireland mandate these configurations for ISO Class 0 purity with zero risk of hydrocarbon contamination.
- Variable Speed Drive:Permanent magnet motors with integrated frequency inverters modulate rotor speed to match fluctuating demand, recovering energy during partial-load operation. EU Ecodesign Directive compliance now effectively mandates these configurations for new installations above 7.5 kW.
- Oil-injected:Flooded compression with rotor coolant and sealing oil remains cost-optimized for general industrial applications without strict purity requirements.
- Low Pressure:Specialized blower-derived architectures serve pneumatic conveying and wastewater aeration below 2 bar discharge pressure.
Oil-injected dominates installed base. Variable Speed Drive is where expansion concentrates as efficiency regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany and Switzerland where precision machining heritage commands margin premiums, while Chinese manufacturers compress component pricing through scale-driven captive production networks.
China
Domestic machinery builders in Shanghai and Suzhou are scaling in-house screw air end production to supply captive compressor packages. MIIT's GB 19153 energy labeling mandates minimum efficiency thresholds that disqualify legacy fixed-speed imports. The Yangtze River Delta manufacturing corridor hosts expanding automation infrastructure serving precision electronics assembly lines.
Germany
EU Ecodesign Directive compliance requirements are accelerating replacement cycles for industrial compressed air systems across Baden-Württemberg and Bavaria. The country's Federal Ministry for Economic Affairs enforces strict machinery safety standards through CE marking protocols. Stuttgart's automotive stamping clusters specify oil-free screw configurations for paint shop operations demanding ISO 8573-1 Class 0 purity.
United States
OSHA pressure vessel codes and Department of Energy compressor efficiency standards shape procurement specifications for continuous-process manufacturers. The Gulf Coast petrochemical corridor maintains demand for explosion-proof configurations rated for hazardous area classifications. Houston-based upstream operators specify corrosion-resistant coatings for offshore platform deployments.
India
PLI scheme incentives for domestic manufacturing are attracting localized screw air end assembly operations to Maharashtra and Gujarat. BIS energy labeling implementation creates first-mover advantages for compliant suppliers in Pune's automotive component belt. Tamil Nadu's textile processing clusters are adopting compressed-air-as-a-service contracting models to transfer operational risk.
Japan
METI efficiency mandates and JIS standards certification requirements constrain product entry for non-domestic suppliers. The Chubu region around Nagoya hosts precision machining capabilities for sub-5-micron tolerance rotor grinding. Yokohama's pharmaceutical manufacturers mandate oil-free magnetic bearing configurations for ISO Class 0 air purity in sterile processing environments.
Screw Air End Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a structure where captive production capabilities among Asian machinery builders erode traditional OEM-direct supply channels. The vendor base organizes around three archetypes: European precision engineering houses with aftermarket service density, Asian scale manufacturers with backward integration into rotor machining, and North American system integrators with vertical control over oil-free compressor architectures. Competitive moves concentrate on strategic partnerships for technology licensing and geographic expansion through localized assembly operations.
Among European precision engineering houses, Atlas Copco and Kaeser Kompressoren occupy positions where aftermarket service networks defend installed-base revenue streams. Ingersoll Rand anchors the North American system integrator tier. Japanese specialists including Hitachi and IHI Rotating Machinery Engineering exemplify the precision machining archetype with concentrated capabilities in sub-micron tolerance manufacturing.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Hitachi |
| Kaeser Kompressoren |
| IHI Rotating Machinery Engineering |
| ELGi |
| Kobelco Construction Machinery |
| ANEST IWATA Corporation |
| Fusheng |
| Others |
Value Network & Pricing Analysis
Tariff exposure on German and Japanese precision grinding equipment determines both the premium spread for sub-5-micron tolerance rotors and the geographic shape of supply chain investments. Buyers facing 18-24 month multi-certification timelines absorb cost premiums for pre-certified assemblies, while Asian machinery builders compress component pricing through captive rotor machining networks.
Pricing Analysis
Configured-to-order pricing for ISO 8573-1 Class 0 oil-free screw air ends commands substantial premiums over standard oil-injected configurations. Three-tier pricing structure across premium, standard, and economy levels separates magnetic bearing pharmaceutical-grade systems from variable speed drive industrial units and fixed-speed cast iron commodity designs. Cost compression in the standard tier intensifies because Chinese domestic machinery builders scale in-house production. Commercial facility operators exhibit highest price sensitivity, while semiconductor fabs and pharmaceutical manufacturers prioritize purity certification over acquisition cost.
Supply Chain Analysis
Contract manufacturing capacity for precision rotor grinding concentrates among German machine tool builders and Japanese specialists in the Chubu region. Forged steel and specialized cast iron alloys draw from concentrated metallurgical supply chains in Germany, Japan, and China. Single-source vulnerability persists for sub-micron tolerance profile machining equipment, where replacement lead times extend operational risk. Distribution runs through OEM-direct channels for compressor packages and independent component suppliers serving aftermarket rebuild operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Screw air end procurement is shifting toward compressed-air-as-a-service platforms, creating ecosystem lock-in effects where telemetry integration and predictive maintenance contracts determine supplier switching costs. Interoperability between modern variable speed drives and legacy plant SCADA architectures is reshaping competitive positioning.
For Market Incumbents: Entrench aftermarket service density through IoT-enabled condition monitoring deployments that capture installed-base telemetry revenue separate from hardware cycles. Deepen backward integration into permanent magnet motor production to defend margin position against Asian scale manufacturers. Centrifugal compressor substitution above 500 kW represents the priority threat requiring oil-free screw technology differentiation in heavy process applications.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where facility management outsourcing accelerates and local service infrastructure remains underdeveloped. India's PLI scheme incentives for domestic manufacturing create favorable tariff and certification positioning for localized assembly operations. Target compressed-air-as-a-service contracting models to transfer operational risk and capture recurring revenue streams.
For Investors and Strategic Acquirers: EU Ecodesign Directive efficiency mandates and China's GB 19153 energy labeling implementation reshape the acquisition landscape toward variable speed drive and permanent magnet motor capabilities. Long-term viability centers on suppliers with digital retrofit channel infrastructure and hydrogen compression integration roadmaps. Precision machining talent scarcity signals acquisition value for specialist rotor grinding operations with sub-micron tolerance expertise. Watch for carbon border adjustment mechanisms as the inflection indicator for total cost of ownership recalculation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rotor Machining | Captive sub-5-micron grinding capability eliminates German and Japanese machine tool dependencies. |
| Digital Retrofit Channel Development | IoT telemetry upgrades unlock unbundled revenue from installed bases with decades-old equipment. |
| Hydrogen Compression Technology Licensing | Electrolyzer and fuel cell integration opens specialized high-pressure contamination-sensitive applications. |
| Localized Assembly Operations | India PLI scheme and BIS compliance create first-mover positioning in automotive and textile clusters. |
| Permanent Magnet Motor Manufacturing Scale-Up | EU Ecodesign and China GB 19153 mandates accelerate displacement of induction motor architectures. |
Research Methodology
The analysis maps oil-free, oil-injected, variable speed drive, and low-pressure screw air end configurations, each validated through maintenance directors at continuous-process manufacturers, OEM procurement teams at compressor packagers, aftermarket service heads, and plant engineers in precision automation facilities. Primary interview insights triangulate against customs and trade data for forged steel and cast iron alloy flows, SEC filings from listed compressor OEMs, MIIT energy efficiency disclosures, and EU Ecodesign Directive compliance databases. Bottom-up unit economics and top-down sector sizing cross-validate volume and value estimates.
Forecast assumptions hold fixed the current regulatory trajectory for ISO 8573-1 purity classes, EU Ecodesign efficiency indexes, and China GB 19153 labeling thresholds, while varying penetration rates for compressed-air-as-a-service contracting and hydrogen compression integration. Segmentation dimensions span product type, application vertical, end-user sophistication tier, and technology architecture across the projection horizon. CAGRs derive from replacement cycle analysis calibrated to duty-cycle intensity and regional energy efficiency mandate compliance timelines. Specific power consumption benchmarks and oil carryover limit enforcement patterns inform trajectory sensitivity.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, alloy commodity pricing, or carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions about certification timeline compression and precision machining talent availability. Quarterly review of EU Ecodesign enforcement patterns, China MIIT efficiency standard revisions, and Southeast Asian automation infrastructure investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Electric Actuator Market
Industrial Equipment
Battery Power Tools Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
Global Special Purpose Machines Market
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Electrode Slag Remelting (ESR) Furnace Market
Industrial Equipment
Global Dosing Systems Market