
 Plasma Feeder Market | 2026-2036
Plasma Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Feeder Market Analytics
Asset-light leasing models for high-frequency plasma equipment are rewriting competitive entry barriers in the feeder supply chain. Darling Ingredients Inc. leverages its vertically integrated protein processing footprint to secure raw material streams for plasma-derived feed formulations. Daka Denmark A/S anchors Nordic supply reliability through controlled cold-chain logistics. APC Inc. specializes in customized feeder configurations for additive manufacturing lines.
A plasma feeder is a precision material delivery system that injects powdered or wire-form feedstock into a generated plasma stream, typically operating at temperatures between 8,000°C and 15,000°C to achieve complete melting and controlled deposition. The device regulates feed rate, carrier gas flow, and injection angle to ensure uniform coating thickness or build geometry in thermal spray and directed energy deposition processes. Automated feeders command premium positioning due to their closed-loop control systems that synchronize with robotic motion platforms. Hybrid plasma technology is gaining fastest traction as manufacturers combine arc stability with induction preheating to reduce energy consumption and improve deposition efficiency. Single-slot feeders remain the volume workhorse in legacy surface treatment installations.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that limit hexavalent chromium exposure in thermal spray operations, directly shaping plasma feeder specification requirements for enclosed capture systems. OSHA mandates permit-required confined space protocols that influence automated feeder adoption to minimize human exposure in coating booths. The EU F-Gas Regulation progressively restricts hydrofluorocarbon use in plasma generation gases, compelling equipment redesign toward inert gas alternatives. Stakeholders must weigh capital allocation between induction heating retrofits and full hybrid plasma system replacements as regulatory thresholds tighten across multiple jurisdictions.
Market Dynamics
Hybrid plasma technology is compressing equipment replacement cycles as manufacturers retrofit arc-based systems with induction preheating modules to meet tightening fluorinated gas controls. The EU F-Gas Regulation and parallel EPA enforcement on hexavalent chromium exposure are forcing simultaneous compliance investments across thermal spray operations.
Growth Catalysts
- Aerospace coating demand:Turbine blade thermal barrier specifications are expanding plasma spray capacity at precision engineering clusters in Germany and the United States.
- EU F-Gas Regulation:Progressive hydrofluorocarbon phase-down mandates are accelerating equipment turnover toward inert gas-compatible feeder architectures.
- Additive manufacturing integration:Directed energy deposition lines are specifying closed-loop plasma feeders synchronized with robotic motion platforms.
Market Restraints
- Tungsten electrode supply concentration:Sourcing bottlenecks from primary extraction regions constrain non-consumable plasma torch availability.
- Induction retrofit capex burden:Full hybrid system replacements demand capital allocation that mid-tier coating shops cannot absorb without financing structures.
- OSHA confined space protocols:Permit-required entry procedures extend coating booth downtime, compressing throughput at legacy installations.
Strategic Opportunities
- India precision engineering corridor:Emerging aerospace component manufacturing near Bengaluru creates first-mover positioning for automated feeder deployment.
- Asset-light leasing models:High-frequency equipment rental programs lower entry barriers for job shops serving intermittent thermal spray demand.
- CE marking convergence:Unified European conformity assessment streamlines cross-border equipment certification for multi-site operators.
Industry Challenges
- Plasma physics specialist scarcity:Talent pipelines for arc stability optimization and carrier gas flow calibration lag equipment sophistication.
- Legacy analog controller integration:Retrofitting closed-loop digital feeders into existing surface treatment lines demands custom mechanical interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Feeder Market |
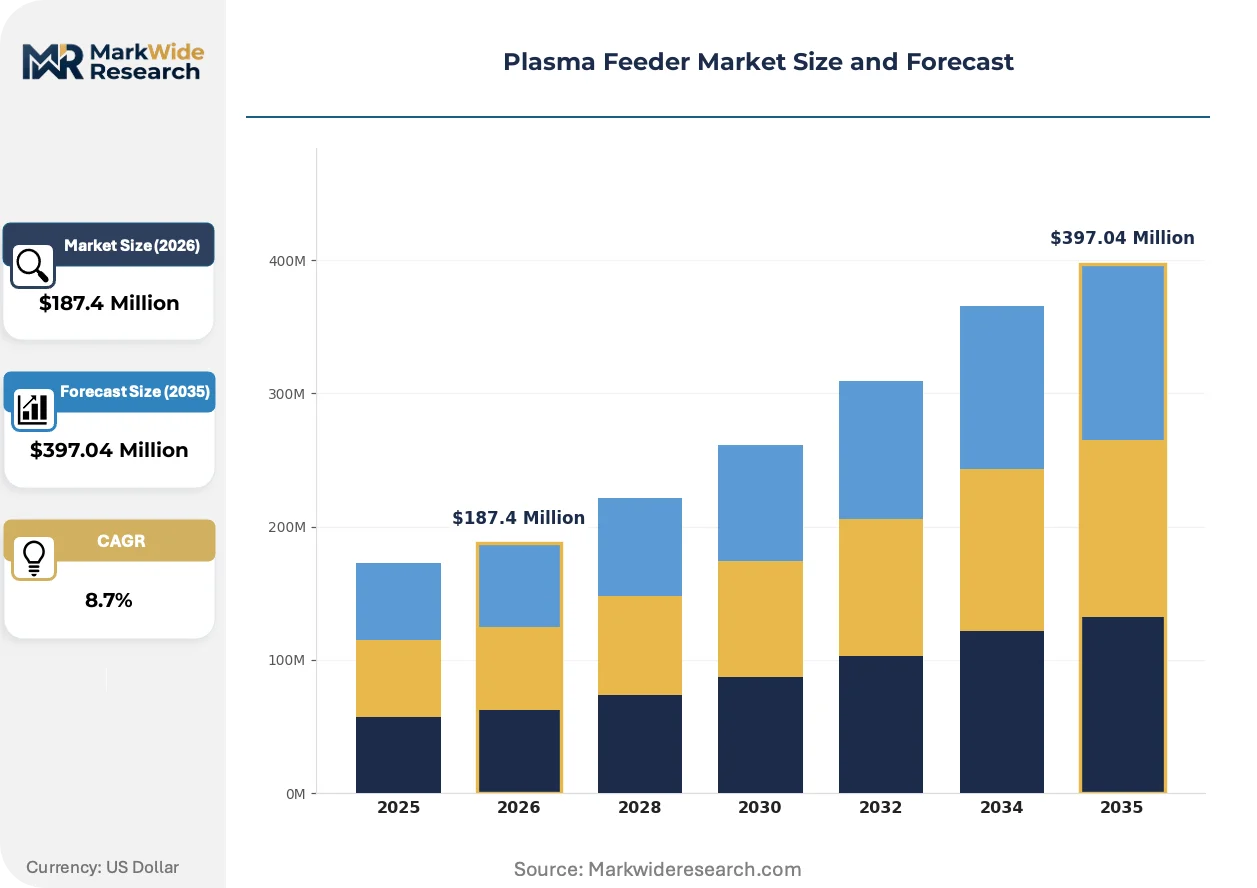
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
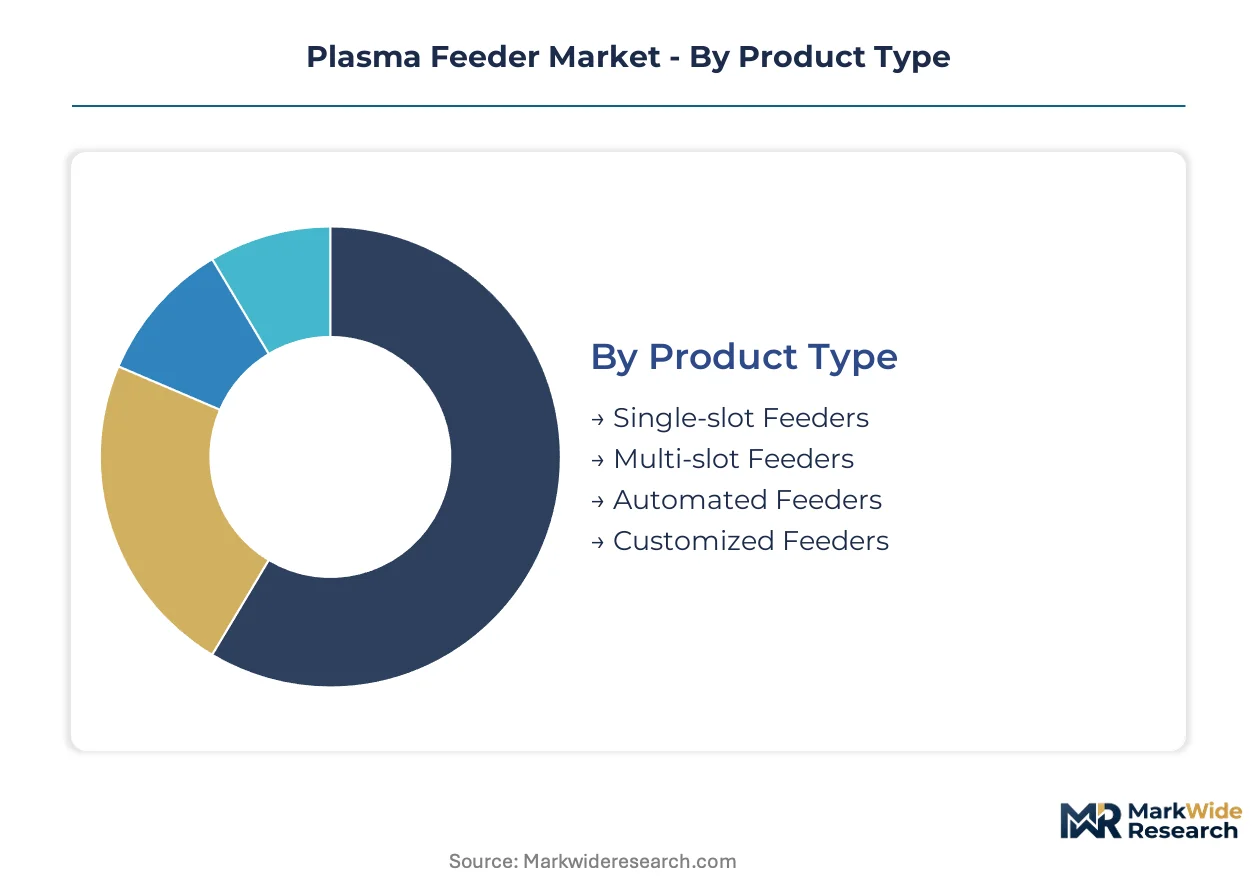
| Segmentation | Product Type: Single-slot Feeders, Multi-slot Feeders, Automated Feeders, Customized Feeders Technology: Induction Heating, Arc Plasma, High-frequency Plasma, Hybrid Plasma Application: Industrial Coatings, Additive Manufacturing, Surface Treatment, Plasma Etching End User: Aerospace, Electronics, Automotive, Energy |
| Companies Covered | Darling Ingredients Inc., Daka Denmark A/S, Lauridsen Group Inc., Sera Scandia A/S, Veos Group, SARIA Group, APC Inc., Rocky Mountain Biologicals, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Feeder Market Evolving Landscape
Plasma feeder architecture is bifurcating between premium automated systems with real-time deposition control and cost-optimized single-slot units for commodity coating work. This divergence is compressing mid-tier positioning and reshaping vendor R&D allocation.
Sensor-integrated feedstock monitoring is digitizing quality assurance workflows in thermal spray operations. Aerospace prime contractors in Germany and the United States are mandating these systems for turbine blade coating traceability. The technology is digitizing documentation burdens that previously required manual batch sampling and offline metallurgical analysis.
EPA National Emission Standards for Hazardous Air Pollutants are forcing enclosed capture system retrofits across US thermal spray facilities. The regulation is elevating capital requirements for open-booth operations and pushing demand toward fully automated plasma cells with integrated fume extraction. Coating job shops in Ohio and Texas are consolidating to spread compliance costs across higher throughput volumes.
Service-unbundling is fragmenting traditional equipment-plus-maintenance contracts into separate hardware, calibration, and consumable subscriptions. Tier-one automotive suppliers in Stuttgart and Munich are piloting outcome-based feeder availability agreements. This shift is most visible in German precision engineering clusters where coating quality liability rests with feeder performance guarantees rather than operator certification.
Plasma Feeder Market Segmentation
Plasma feeder segmentation reveals how equipment specification diverges between precision aerospace mandates and commodity surface treatment economics. Technology and application boundaries are blurring as hybrid architectures penetrate legacy coating installations.
Product Type:
Cost tier stratification separates premium automated systems from volume single-slot units serving intermittent job shop demand.
- Single-slot Feeders:These units deliver powdered or wire feedstock through a single injection channel with manual rate adjustment. Demand concentrates in Ohio and Texas coating job shops where intermittent thermal spray volumes cannot justify automation capex. OSHA confined space protocols are accelerating replacement timelines as shops consolidate to spread compliance burdens.
- Automated Feeders:Closed-loop systems synchronize feed rate, carrier gas flow, and injection angle with robotic motion platforms in real time. Aerospace prime contractors in Germany and the United States mandate these configurations for turbine blade thermal barrier traceability. The EU F-Gas Regulation is pushing equipment turnover toward inert gas-compatible architectures.
- Multi-slot Feeders:Parallel injection channels enable rapid material switching in complex coating sequences.
- Customized Feeders:Application-specific configurations address unique substrate geometries or deposition parameters.
Single-slot feeders hold installed capacity. Automated feeders are rotating up the share rankings.
Technology:
Application requirements for deposition efficiency and emission compliance are reshaping technology adoption curves.
- Hybrid Plasma:Combines arc stability with induction preheating to reduce energy consumption and fluorinated gas dependency. German precision engineering clusters around Stuttgart and Munich anchor fastest equipment replacement cycles as the EU F-Gas Regulation tightens hydrofluorocarbon phase-down mandates. Mid-tier coating shops face capex barriers without asset-light leasing structures.
- Arc Plasma:Traditional non-consumable torch technology operating at 8,000°C to 15,000°C with tungsten electrode constraints. Sourcing bottlenecks from primary extraction regions limit availability for legacy surface treatment lines in United States industrial corridors.
- Induction Heating:Preheating modules retrofit onto existing arc systems to improve deposition efficiency.
- High-frequency Plasma:Specialized configurations for precision electronics and semiconductor etching applications.
Arc plasma retains legacy installed base. Hybrid plasma is climbing the fastest expansion trajectory.
Application:
Volume concentration in mature coating segments contrasts with emerging additive manufacturing integration.
- Industrial Coatings:Thermal spray deposition for wear resistance and corrosion protection across heavy machinery and infrastructure. Demand clusters in German automotive supplier networks and United States rust-belt manufacturing corridors. EPA National Emission Standards for Hazardous Air Pollutants are forcing enclosed capture system retrofits.
- Additive Manufacturing:Directed energy deposition lines specify closed-loop feeders synchronized with robotic build platforms. Aerospace component manufacturing near Bengaluru creates first-mover positioning for automated deployment in emerging precision engineering corridors.
- Surface Treatment:Legacy preparation and finishing processes in job shop environments.
- Plasma Etching:Electronics fabrication applications requiring precise material removal control.
Industrial coatings dominates current throughput. Additive manufacturing is gaining share fastest.
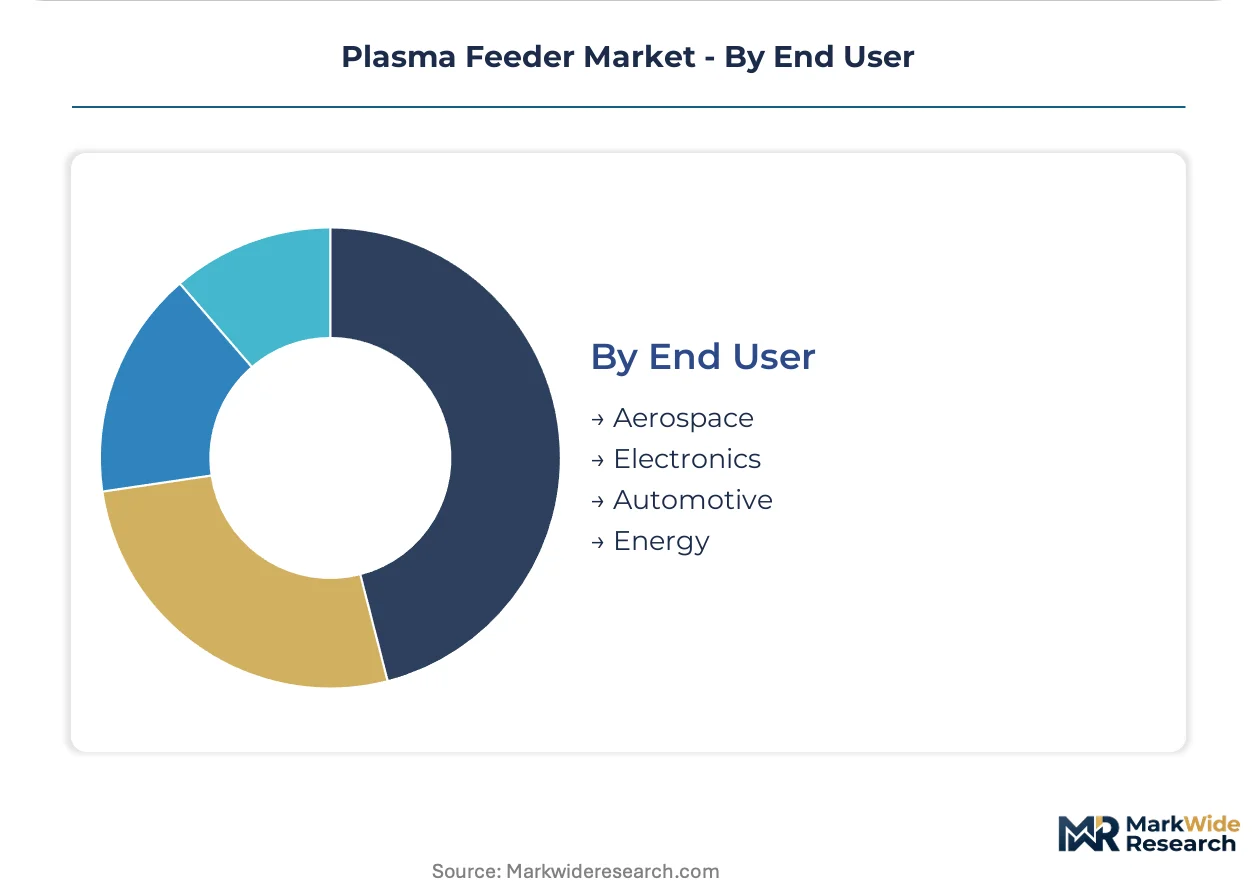
End User:
Customer type differentiation reflects certification burden and quality liability concentration.
- Aerospace:Turbine blade thermal barrier specifications demand closed-loop control and full deposition traceability. German and United States prime contractors mandate sensor-integrated feedstock monitoring systems. Tier-one suppliers in Stuttgart and Munich pilot outcome-based feeder availability agreements.
- Automotive:Precision coating requirements for powertrain components and exterior trim. German engineering clusters anchor supply chain reliability through controlled logistics and performance guarantee structures.
- Electronics:Semiconductor and display manufacturing requiring high-frequency plasma precision.
- Energy:Turbine and infrastructure applications with extended service life requirements.
Aerospace commands premium positioning. Automotive is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters extract premium pricing for automated plasma feeder configurations, while Ohio and Texas job shops compete on cost-optimized single-slot unit economics. This asymmetry concentrates R&D investment in Stuttgart and Munich corridors. Regulatory divergence between EPA enforcement and EU F-Gas phase-down timelines fragments equipment specification standards.
United States
Aerospace prime contractors in the Pacific Northwest and Southeast drive closed-loop feeder specifications for turbine blade thermal barriers. EPA National Emission Standards for Hazardous Air Pollutants mandate enclosed capture systems that accelerate automated cell adoption. Coating job shops in Ohio and Texas consolidate operations to spread hexavalent chromium compliance costs across higher throughput volumes.
Germany
Tier-one automotive suppliers in Stuttgart and Munich pilot outcome-based feeder availability agreements that shift quality liability to equipment performance. EU F-Gas Regulation hydrofluorocarbon phase-down mandates compress replacement cycles toward hybrid plasma architectures. Precision engineering clusters anchor supply chain reliability through controlled logistics and CE marking convergence.
India
Aerospace component manufacturing near Bengaluru creates first-mover positioning for automated feeder deployment in emerging precision engineering corridors. BIS certification requirements and PLI scheme incentives align domestic production capacity with import substitution goals. Karnataka's electronics and defense manufacturing hubs attract technology licensing partnerships from European system integrators.
China
MIIT industrial upgrading directives prioritize deposition efficiency improvements in thermal spray operations serving heavy machinery and infrastructure segments. Dual carbon goals pressure coating facilities toward energy-efficient hybrid plasma retrofits. Yangtze River Delta manufacturing bases concentrate demand for high-frequency plasma configurations in semiconductor fabrication.
Japan
METI technology roadmaps emphasize sensor-integrated feedstock monitoring for deposition traceability in precision electronics applications. JIS standards harmonization with ISO frameworks streamlines equipment certification for multi-site operators. Kansai and Chubu industrial corridors specialize in tungsten electrode supply chain security for non-consumable torch availability.
Plasma Feeder Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the plasma feeder supply chain. The vendor base stratifies between premium automated system providers and volume single-slot fabricators, with mid-tier positioning compressing as architecture bifurcation accelerates. Three archetypes dominate: vertically integrated protein processors securing raw material streams, precision engineering specialists customizing feeder configurations for additive manufacturing lines, and Nordic logistics operators anchoring cold-chain supply reliability. Competitive moves concentrate on asset-light leasing program expansion and hybrid technology licensing partnerships.
Among North American ingredient processors, Darling Ingredients Inc. exemplifies backward integration into captive raw material supply for plasma-derived feed formulations. Daka Denmark A/S occupies a position within the Nordic cold-chain reliability tier, while APC Inc. represents the additive manufacturing specialization archetype through customized feeder configuration capabilities.
| Leading Market Players |
|---|
| Darling Ingredients Inc. |
| Daka Denmark A/S |
| Lauridsen Group Inc. |
| Sera Scandia A/S |
| Veos Group |
| SARIA Group |
| APC Inc. |
| Rocky Mountain Biologicals |
| Alltech |
| Others |
Value Network & Pricing Analysis
Tungsten electrode mining concentration in China and Russia funnels margin capture toward plasma torch fabricators with captive supply agreements, while downstream coating job shops absorb residual price volatility through equipment leasing structures.
Pricing Analysis
Configured-to-order automated feeders command spreads over standard single-slot units that widen with certification tier and robotic integration depth. Three-tier pricing structure across premium, standard, and economy levels segments by closed-loop control sophistication and traceability documentation. Cost compression in mid-tier equipment is intensifying because hybrid plasma retrofits force simultaneous capex outlays. Job shops in Ohio and Texas exhibit highest price sensitivity, while aerospace prime contractors in Germany accept premium positioning for deposition guarantee structures.
Supply Chain Analysis
Extended payment terms from German precision engineering clusters anchor supplier-financing arrangements that stabilize tungsten electrode procurement through Kansai and Chubu corridor distributors. Manufacturing draws from China, Germany, and Japan for non-consumable torch assemblies, induction preheating modules, and sensor-integrated feedstock monitors. Single-source vulnerability concentrates in tungsten extraction regions subject to export licensing shifts. Distribution runs through system integrators bundling calibration and consumable subscriptions for multi-site operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating as aerospace prime contractors in Germany and the United States mandate unified feeder specifications across tier-one supplier networks, compressing vendor negotiation leverage.
For Market Incumbents: Build switching-cost moats through outcome-based availability agreements that embed calibration and consumable subscriptions. Expand captive tungsten electrode sourcing through JIS-certified Japanese distributors to offset extraction-region volatility. Invest in hybrid plasma R&D partnerships with Stuttgart automotive suppliers facing EU F-Gas compliance deadlines. Channel control through certified service networks defends against asset-light leasing entrants.
For New Entrants and Emerging Players: Pursue additive manufacturing integration white space in Bengaluru precision engineering corridors where automated feeder penetration remains below aerospace-tier levels. Target single-slot feeder replacement cycles in Ohio and Texas job shops consolidating for EPA hexavalent chromium compliance. Go-to-market through equipment-as-a-service models lowers capex barriers for intermittent thermal spray demand.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coating job shop consolidators in US rust-belt manufacturing corridors seeking platform add-ons. Long-term viability hinges on hybrid technology licensing portfolios and regulatory compliance service capabilities. Watch EU F-Gas phase-down enforcement velocity as inflection indicator for equipment replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Technology Licensing | EU F-Gas Regulation compliance transfers margin to inert gas-compatible system providers. |
| Asset-Light Leasing Expansion | Ohio and Texas job shops adopt rental structures to spread intermittent demand costs. |
| Backward Integration into Tungsten Supply | Kansai corridor electrode security reduces exposure to China-Russia extraction concentration. |
| Sensor-Integrated Feedstock Monitoring | Aerospace prime contractors in Germany mandate traceability systems for turbine blade coating. |
| Additive Manufacturing Partnership | Bengaluru precision engineering hubs create first-mover positioning for directed energy deposition lines. |
Research Methodology
A spread of perspectives from plasma system engineers, coating shop operations managers, aerospace procurement leads, and thermal spray equipment distributors converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings of industrial equipment manufacturers, EPA enforcement databases, EU F-Gas Regulation implementation reports, and customs trade data. Bottom-up equipment shipment analysis and top-down thermal spray market sizing triangulated volume estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, technology architecture, application vertical, and end-user industry concentration. CAGRs derived from replacement cycle analysis and regulatory compliance timeline acceleration. Industry-specific inputs incorporated EU hydrofluorocarbon phase-down schedules and OSHA confined space protocol adoption curves.
Macroeconomic conditions sit as an overlay; deviation in aerospace capital expenditure cycles or tungsten commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Hot Runner Temperature Controller Market
Industrial Equipment
Resistance Spot Welding Machines Market
Industrial Equipment
ROV Tether Management System Market
Industrial Equipment
Global Temperature Control Units (TCU) Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
CNC Tool Storage System Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Global Refrigeration Compressor Market
Industrial Equipment
Industrial Marking Equipment Market
Industrial Equipment
Vertical Centrifugal Separator Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Floor Scales Market
Industrial Equipment
Thermal Cleaning System Market