
 Global Vacuum Furnaces Market | 2026-2036
Global Vacuum Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vacuum Furnaces Market Analysis
China is rewriting vacuum furnace deployment patterns as domestic aerospace and semiconductor fabs commission localized heat treatment lines. Ipsen leverages its European engineering heritage to sustain premium positioning in aerospace-grade vacuum systems across France and Germany. SIMUWU Vacuum Furnace anchors cost-competitive batch furnace production for China's expanding automotive tooling sector. Seco/Warwick differentiates through modular furnace architectures that reduce installation lead times for precision manufacturers.
Vacuum furnaces are sealed thermal processing systems operating below atmospheric pressure, typically achieving temperatures from 500°C to 2,400°C with oxygen levels controlled to parts-per-million ranges, enabling oxide-free heat treatment of reactive metals and superalloys. Their primary purpose centers on eliminating surface contamination during critical processes such as brazing, sintering, and solution annealing for aerospace turbine components and medical implants. Batch furnace configurations occupy the largest installed base due to flexibility across low-volume, high-mix production environments, though continuous furnace architectures are gaining traction in automotive powertrain manufacturing where throughput standardization dominates. Ultra high vacuum technology commands the highest margin pool, serving semiconductor wafer processing and precision optics where residual gas specifications approach 10⁻⁹ mbar.
EPA emissions enforcement in the United States and REACH chemical restrictions administered by ECHA in Europe are eliminating open-atmosphere alternatives for heat treatment of nickel-based superalloys and titanium alloys, directly expanding vacuum furnace qualification requirements. China's SAMR enforces GB standards for industrial furnace energy efficiency that favor cold-wall vacuum designs with improved insulation packages over conventional hot-wall constructions. Japan's METI promotes vacuum processing adoption through industrial decarbonization roadmaps targeting heat treatment sector emissions reductions. Stakeholders must monitor evolving alloy specifications from aerospace OEMs and semiconductor foundries, as material chemistry shifts will dictate the next generation of vacuum pressure and temperature capability requirements.
Market Dynamics
EPA emissions enforcement and ECHA REACH substance restrictions are structurally eliminating open-atmosphere heat treatment alternatives, forcing qualification of vacuum systems across aerospace and automotive supply chains.
Growth Catalysts
- Semiconductor wafer processing:Ultra high vacuum technology serves precision optics and semiconductor fabrication where residual gas specifications approach 10⁻⁹ mbar, creating captive infrastructure demand in China.
- REACH chemical restrictions:ECHA-administered substance limitations are expanding vacuum furnace qualification requirements for nickel-based superalloy processing across European aerospace suppliers.
- Japan's METI decarbonization roadmap:Industrial emissions reduction targets are accelerating vacuum processing adoption in heat treatment sectors.
Market Restraints
- Graphite heating element supply concentration:High-purity graphite sourcing concentrates among limited suppliers, creating input cost volatility for hot-zone construction.
- Ultra high vacuum technical complexity:Achieving and maintaining 10⁻⁹ mbar residual gas specifications requires specialized pumping trains and chamber materials that extend delivery timelines.
- GB standards energy efficiency mandates:China's SAMR-enforced industrial furnace standards favor cold-wall designs, rendering legacy hot-wall installations non-compliant for expansion projects.
Strategic Opportunities
- India automotive tooling sector:Underpenetrated vacuum heat treatment capacity presents white space as domestic component manufacturers qualify for export supply chains.
- Medical implant additive manufacturing:Emerging titanium alloy sintering applications require vacuum furnace integration with powder bed fusion systems.
- EU Green Deal industrial transition:Carbon border adjustment mechanisms and emissions trading scheme expansions are creating regulatory tailwinds for zero-emission vacuum processing.
Industry Challenges
- Vacuum metrology technician scarcity:Specialized skills for leak detection, mass spectrometry, and pressure calibration are concentrated among aging workforce cohorts in Germany and Japan.
- AS9100D and NADCAP certification timelines:Aerospace quality system accreditation for vacuum heat treatment requires 18-24 month qualification periods that delay revenue recognition.
- Legacy SCADA integration complexity:Brownfield furnace installations must interface with proprietary control architectures from 1990s-era equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vacuum Furnaces Market |
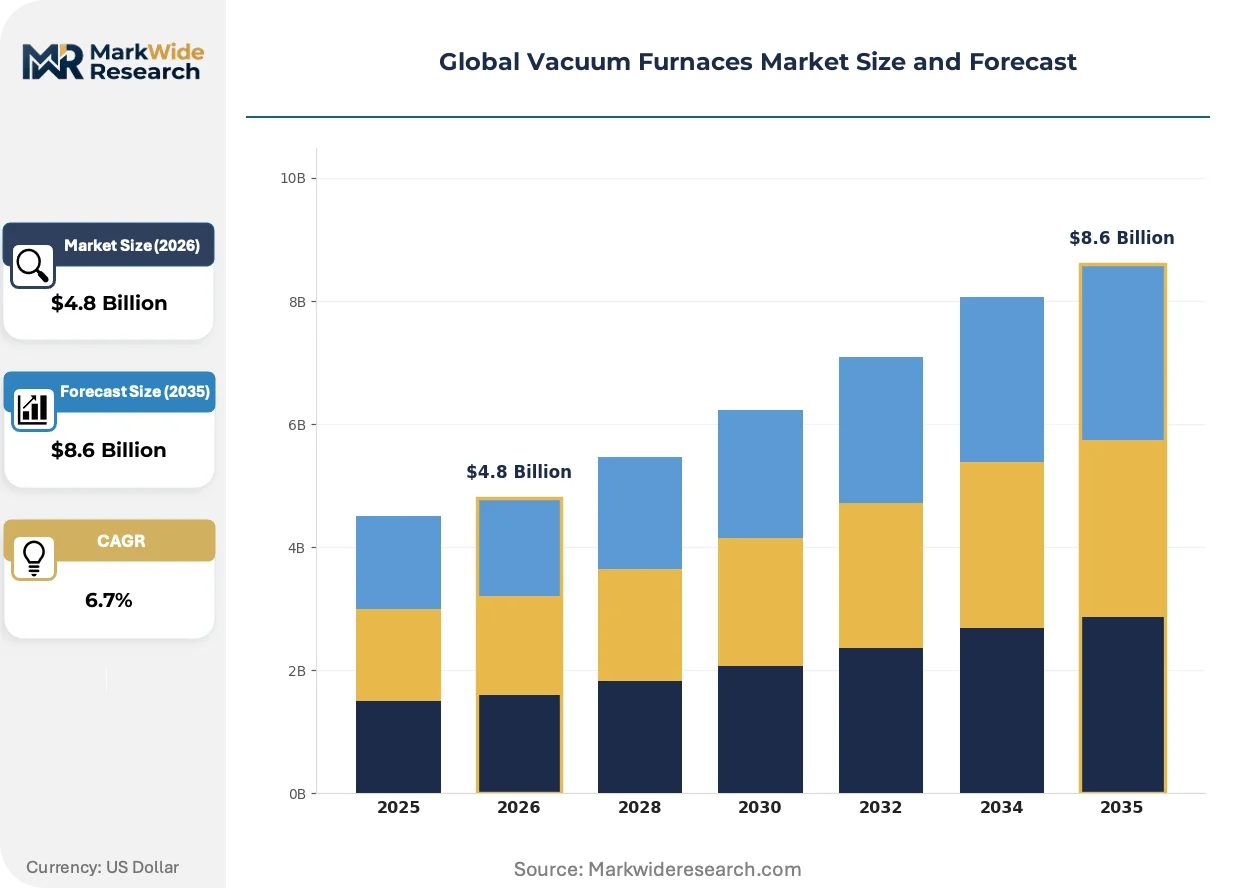
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Furnaces, Continuous Furnaces, High-Temperature Furnaces, Specialty Furnaces End User: Aerospace, Automotive, Healthcare, Electronics Technology: High Vacuum, Ultra High Vacuum, Cold Wall, Hot Wall Application: Material Processing, Heat Treatment, Sintering, Coating |
| Companies Covered | Solar Manufacturing, SIMUWU Vacuum Furnace, Ipsen, Tenova, ECM Technologies, Seco/Warwick, Centorr Vacuum Industries, IHI, ALD Vacuum Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vacuum Furnaces Market Emerging Trajectories
Digital twin architectures and predictive maintenance algorithms are compressing unplanned downtime in high-value vacuum processing operations. Three distinct developments are reshaping competitive capability requirements.
Digital twin simulation software is virtualizing thermal process development, enabling aerospace manufacturers to validate brazing cycles and quench profiles without physical prototyping. Turbine blade producers in France and Germany are adopting these tools aggressively. The technology is virtualizing traditional equipment commissioning timelines from months to weeks.
EPA emissions standards enforcement in the United States is eliminating atmospheric furnace alternatives for titanium alloy heat treatment. Automotive suppliers serving electric vehicle powertrain manufacturing must now qualify vacuum systems for rotor and stator component processing. The Midwest manufacturing belt is experiencing the most acute compliance-driven equipment replacement activity.
Captive heat treatment infrastructure is displacing merchant service providers as semiconductor foundries and aerospace OEMs internalize critical processes. China's domestic fabs and turbine blade manufacturers are building localized vacuum furnace lines rather than outsourcing. This insourcing pattern is most visible in Shanghai and Xi'an industrial clusters.
Global Vacuum Furnaces Market Segmentation
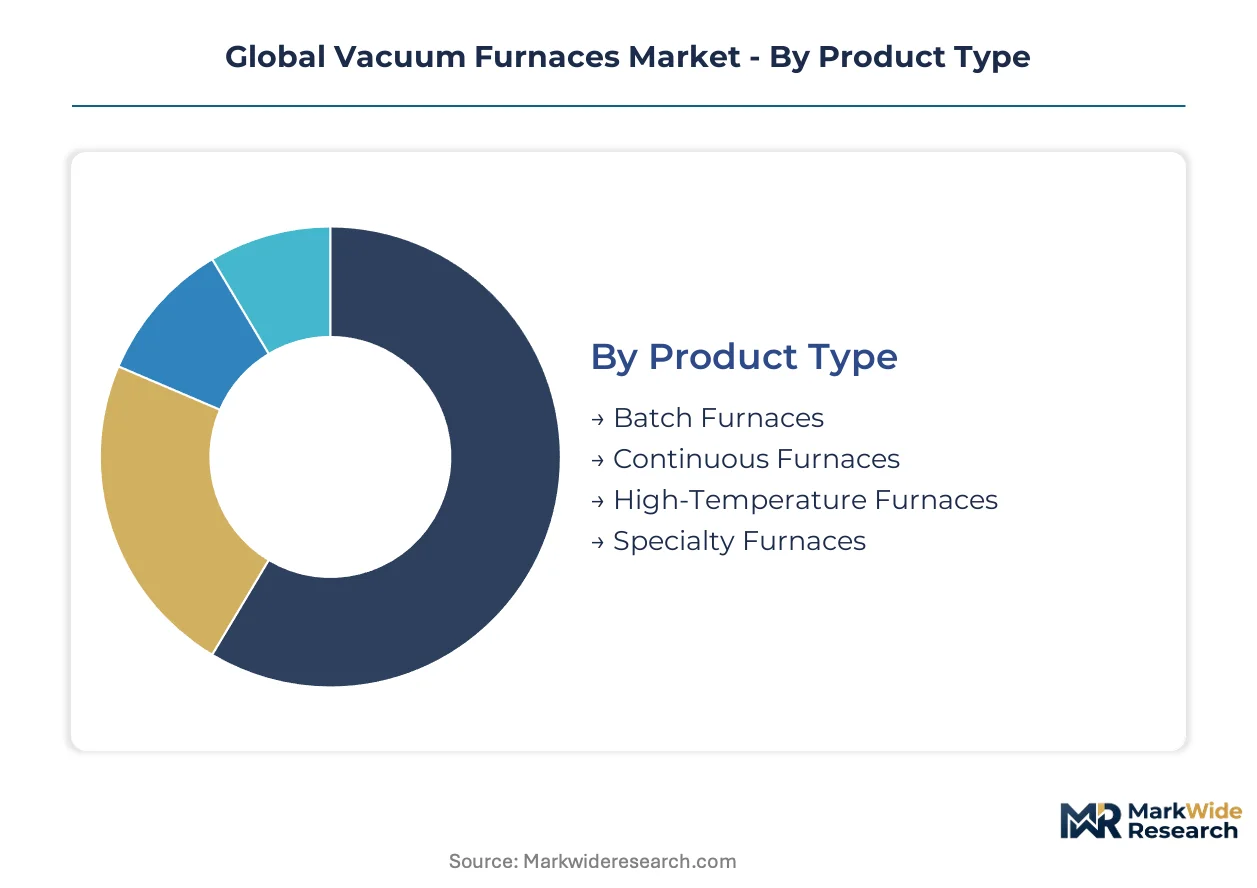
Segmentation in vacuum furnaces reveals divergent equipment lifecycles and capital intensity patterns. Batch configurations cycle every 8-15 years while continuous lines demand 20-25 year replacement horizons. Technology tiers separate semiconductor-grade ultra high vacuum systems from general industrial heat treatment equipment with order-of-magnitude pricing spreads.
Product Type:
Cycle times vary dramatically across furnace architectures. Batch systems turn over fastest due to flexibility demands from contract heat treaters. Continuous lines amortize over decades in automotive powertrain plants.
- Batch Furnaces:Sealed chamber designs process discrete loads under vacuum with programmable thermal cycles. Aerospace component manufacturers in Germany and Japan favor these for low-volume turbine blade production where alloy changeovers occur weekly.
- Continuous Furnaces:Conveyor-fed architectures move workpieces through sequential heating and cooling zones without breaking vacuum. Automotive transmission gear producers in the US Midwest deploy these for 24/7 standardized throughput where SKU variety remains limited.
- High-Temperature Furnaces:Systems exceeding 2,000°C for refractory metal and ceramic matrix composite processing.
- Specialty Furnaces:Custom-engineered configurations for nuclear fuel cladding and precision optical component manufacturing.
Batch Furnaces dominate installed base. Continuous Furnaces are where expansion concentrates.
End User:
Capital allocation patterns separate regulated aerospace qualification requirements from price-sensitive automotive procurement. Healthcare and electronics segments sit at opposite ends of the specification-maturity spectrum.
- Aerospace:NADCAP-accredited vacuum heat treatment for nickel-based superalloy turbine disks and titanium structural components. OEMs in France and Germany mandate captive furnace ownership for critical flight hardware.
- Automotive:Vacuum processing for electric motor laminations and transmission components as EPA emissions rules eliminate atmospheric alternatives. Tier-1 suppliers in Michigan and Stuttgart face compressed qualification timelines.
- Healthcare:Titanium implant sintering and cobalt-chrome alloy solution annealing for orthopedic manufacturers.
- Electronics:Semiconductor wafer annealing and magnetic thin-film deposition requiring 10⁻⁹ mbar base pressures.
Aerospace commands premium pricing. Electronics is expanding most quickly.
Technology:
Engineering complexity and pumping infrastructure requirements create distinct margin tiers. Cold-wall designs now displace legacy hot-wall constructions under Chinese energy efficiency mandates.
- High Vacuum:Achieving 10⁻³ to 10⁻⁷ mbar through mechanical and diffusion pumping for general heat treatment. Automotive suppliers across the US and Germany standardize on these for cost-controlled brazing operations.
- Ultra High Vacuum:10⁻⁹ mbar residual gas specifications via turbomolecular and cryogenic pumping trains. Chinese semiconductor fabs in Shanghai and Xi'an build captive infrastructure for 300mm wafer processing.
- Cold Wall:Water-cooled double-wall construction with internal insulation packages meeting China's SAMR GB standards.
- Hot Wall:Resistance-heated retort designs with higher thermal mass and legacy installed base.
High Vacuum holds largest installed base. Ultra High Vacuum is where expansion concentrates.
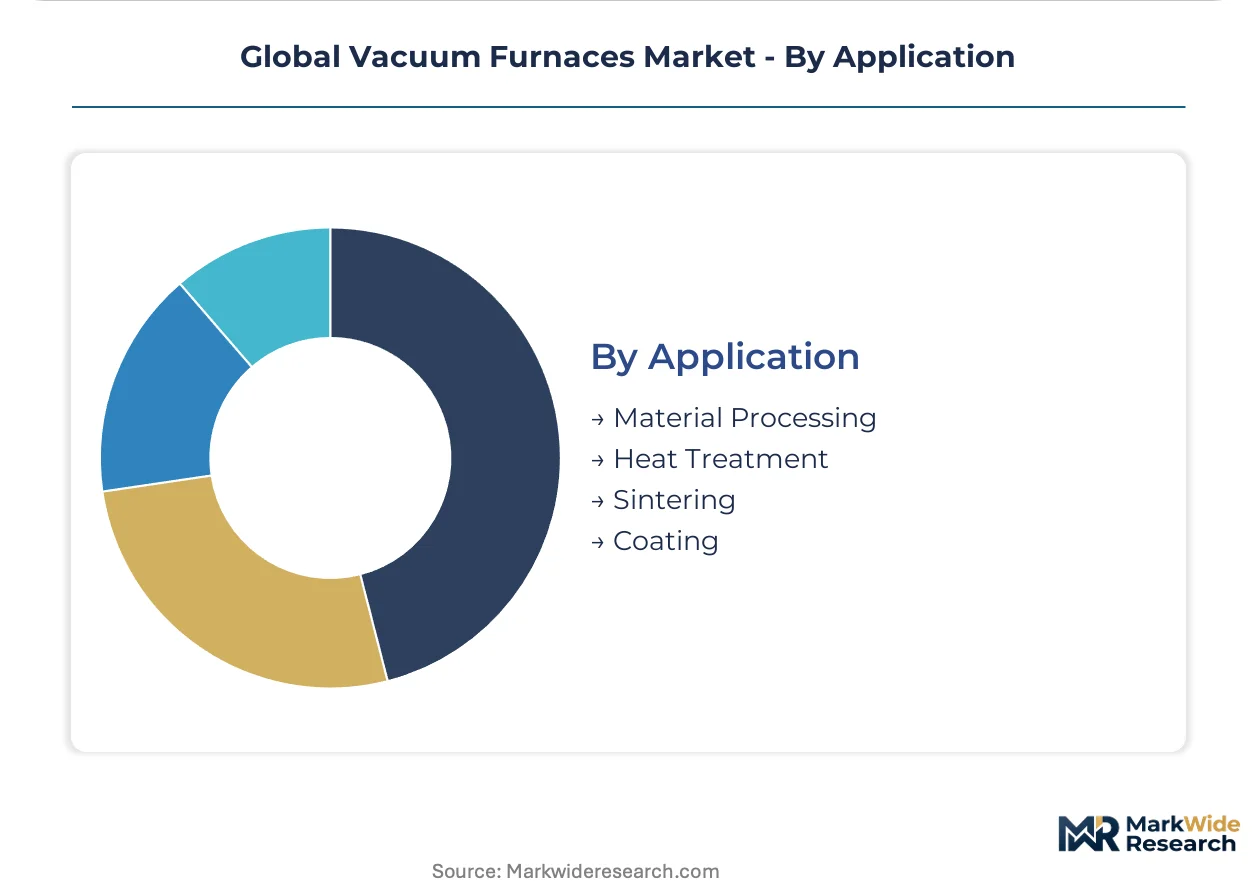
Application:
Process temperature and atmosphere requirements separate commodity heat treatment from precision sintering and coating applications. Material specification evolution drives equipment capability upgrades.
- Heat Treatment:Solution annealing, aging, and stress relieving of reactive alloys under protective vacuum. Aerospace suppliers in Japan qualify these processes for single-crystal turbine blade microstructure control.
- Sintering:Powder metallurgy consolidation for additive manufacturing feedstocks and cemented carbide tooling. Medical implant manufacturers integrate these with electron beam powder bed fusion systems.
- Material Processing:General vacuum melting and degassing operations for specialty alloy production.
- Coating:Physical vapor deposition and chemical vapor deposition substrate preparation.
Heat Treatment dominates installed base. Sintering is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's heavy-lift cargo terminals enable German furnace fabricators to ship complete vacuum chamber assemblies to aerospace clusters worldwide. This infrastructure underwrites Europe's dominance in high-specification thermal processing equipment exports.
United States
EPA emissions enforcement is eliminating atmospheric heat treatment alternatives for titanium alloy processing across Michigan and Ohio automotive corridors. Tier-1 suppliers serving electric vehicle powertrain manufacturing must now qualify vacuum systems for rotor laminations. The Midwest manufacturing belt experiences acute compliance-driven equipment replacement activity.
Germany
Aerospace OEMs in Bavaria and Baden-Württemberg mandate captive furnace ownership for critical flight hardware qualification. ECHA REACH substance restrictions expand vacuum furnace requirements for nickel-based superalloy processing across European supply chains. Stuttgart industrial parks host concentrated turbine blade production lines commissioning localized heat treatment infrastructure.
China
Domestic semiconductor fabrication and aerospace supply chains build captive heat treatment infrastructure rather than outsourcing. SAMR-enforced GB standards for industrial furnace energy efficiency favor cold-wall vacuum designs over legacy hot-wall constructions. Shanghai and Xi'an industrial clusters commission localized vacuum furnace lines for 300mm wafer processing and turbine blade production.
Japan
METI industrial decarbonization roadmaps target heat treatment sector emissions reductions through vacuum processing adoption. Aerospace manufacturers expand vacuum heat treatment capacity for single-crystal turbine blade microstructure control. Nagoya and Tokyo industrial corridors concentrate precision heat treatment operations serving domestic turbine engine programs.
India
Underpenetrated vacuum heat treatment capacity presents expansion opportunity as domestic component manufacturers qualify for export supply chains. Automotive tooling sector growth drives demand for cost-competitive batch furnace configurations. Maharashtra and Gujarat industrial zones attract furnace deployment for captive heat treatment infrastructure serving precision component manufacturing.
Global Vacuum Furnaces Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in hot-zone materials and pumping infrastructure. The vendor base stratifies between premium European engineering houses and cost-optimized Asian fabricators. Three archetypes dominate: aerospace-grade system integrators with NADCAP accreditation depth; semiconductor-focused ultra high vacuum specialists; and automotive-sector batch furnace producers competing on delivery timelines. Consolidation concentrates among European incumbents through technology licensing arrangements, while Asian players expand via capacity additions in captive production clusters.
Among European engineering houses, Ipsen and ECM Technologies occupy positions exemplifying premium-tier aerospace qualification capabilities. SIMUWU Vacuum Furnace anchors cost-competitive production archetypes serving China's expanding automotive tooling sector. Seco/Warwick represents modular architecture specialists compressing installation lead times for precision manufacturers. These three patterns—European premium engineering, Chinese scale fabrication, and modular system design—structure competitive positioning across application segments.
| Leading Market Players |
|---|
| Solar Manufacturing |
| SIMUWU Vacuum Furnace |
| Ipsen |
| Tenova |
| ECM Technologies |
| Seco/Warwick |
| Centorr Vacuum Industries |
| IHI |
| ALD Vacuum Technologies |
| Others |
Supply Flow & Price Mechanics
High-purity graphite heating element sourcing concentrates in China and Japan, anchoring margin pools in hot-zone construction and vacuum chamber fabrication tiers where specialized metallurgy commands premium positioning.
Pricing Analysis
EPA emissions enforcement dictates the pricing tier structure across North American vacuum furnace procurement. Three-tier pricing structure across aerospace-certified, industrial-standard, and economy-level configurations separates NADCAP-accredited systems from general heat treatment equipment. Cost compression in economy-tier batch furnaces is intensifying because Chinese fabricators are expanding capacity for automotive tooling applications. Tier-1 automotive suppliers in Michigan exhibit highest price sensitivity due to compressed EV qualification timelines, while semiconductor foundries in Shanghai demonstrate lowest sensitivity given captive infrastructure mandates.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for vacuum furnace fabricators sourcing hot-zone insulation packages. Component manufacturing concentrates in Germany, Japan, and China, with precision pumping trains drawing from specialized suppliers in France and the United States. Raw material dependencies center on high-purity graphite, molybdenum alloys, and ceramic fiber insulation. Distribution runs through regional heavy-lift logistics hubs serving aerospace clusters in Bavaria, Nagoya, and the American Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from predictive maintenance contracts and hot-zone refurbishment programs is expanding faster than hardware sales, creating recurring-income opportunities for furnace system integrators.
For Market Incumbents: Pre-empt modular architecture commoditization by deepening captive control over graphite heating element supply chains and accelerating digital twin software bundling with new furnace deployments. Aerospace-grade system integrators face emerging pressure from Chinese cost-optimized fabricators qualifying for European automotive tooling contracts. Certification investment in semiconductor-grade ultra high vacuum capabilities represents the critical defensive lever. For New Entrants and Emerging Players: Build out vacuum heat treatment capacity in Maharashtra and Gujarat industrial corridors where domestic Indian component manufacturers are qualifying for export supply chains. Medical implant additive manufacturing integration presents the most penetrable white-space target, with titanium alloy sintering applications requiring vacuum furnace pairing with electron beam powder bed fusion systems. Go-to-market execution should emphasize cost-competitive batch furnace configurations with compressed delivery timelines. For Investors and Strategic Acquirers: Capital is best deployed toward modular architecture specialists with demonstrated capability to compress installation lead times for precision manufacturers. Long-term viability across the analysis window hinges on software-attach rates and aftermarket service penetration rather than pure hardware shipment volumes. The signal to monitor is semiconductor foundry captive infrastructure buildout rates in Shanghai and Xi'an clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Virtualizes thermal process development for turbine blade producers in France and Germany. |
| Backward Integration into Graphite Supply | Secures hot-zone material sourcing against input cost volatility from concentrated suppliers. |
| Cold-Wall Design Transition | Aligns furnace portfolios with SAMR-enforced GB energy efficiency standards in China. |
| Semiconductor Captive Infrastructure Partnership | Captures 300mm wafer processing demand from fabs building localized heat treatment lines. |
| Predictive Maintenance Platform Launch | Compresses unplanned downtime through algorithmic monitoring of vacuum integrity and heating element degradation. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vacuum furnace procurement managers at aerospace OEMs, heat treatment service directors, plant engineers at automotive Tier-1 suppliers, and aftermarket service heads at system integrators. Secondary validation drew from EPA emissions enforcement records, ECHA REACH substance restriction updates, SAMR GB standard publications, METI industrial decarbonization roadmaps, and customs data on vacuum furnace trade flows. Bottom-up equipment shipment tallies and top-down capital expenditure estimates were triangulated to anchor market sizing.
Calibration against historical capacity additions and replacement cycle patterns informed projection modeling across the analysis window. Segmentation dimensions included furnace architecture, vacuum technology tier, end-use industry, and regional regulatory cluster. CAGRs were derived from equipment lifecycle analysis and capital intensity benchmarking. Industry-specific forecast inputs encompassed semiconductor fab construction pipelines and aerospace OEM captive infrastructure buildout announcements.
Sensitivities concentrate around graphite supply disruption, REACH substance restriction expansion, and semiconductor capital expenditure cyclicality. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Anti-Vibration Mounts Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Slewing Bearing Market
Industrial Equipment
Laser Processing Market
Industrial Equipment
Europe Industrial Centrifuge Market
Industrial Equipment
CNC Tool Storage System Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
North America Fans and Blowers Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
Sorter Machines Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Servo Drive Market