
 Canada Mobile Payments Market | 2026-2036
Canada Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Mobile Payments Market Outlook
Revenue-based financing and merchant cash advance models is reconfiguring competitive entry barriers for payment platforms serving Canadian small businesses. Royal Bank of Canada leverages its deposit base to anchor integrated merchant services within retail banking workflows. Moneris specializes in point-of-sale hardware-software bundles that dominate Canadian in-person transaction processing. Square competes through flat-rate pricing transparency that appeals to independent contractors and micro-merchants.
Mobile payments encompass fund transfers executed through portable connected devices using near-field communication, tokenized credentials, and encrypted authentication protocols to complete commercial transactions without physical card presentation. The primary purpose centers on reducing friction in consumer-to-business and peer-to-peer value exchange while capturing transaction data for merchant analytics. Digital wallet penetration among Gen Z and millennial demographics leads adoption curves, while peer-to-peer transaction types exhibit the fastest growth trajectory as social payment norms displace traditional cash exchange. In-store mobile payment volume remains the largest value pool, though online transaction margins attract platform investment due to lower terminal infrastructure requirements.
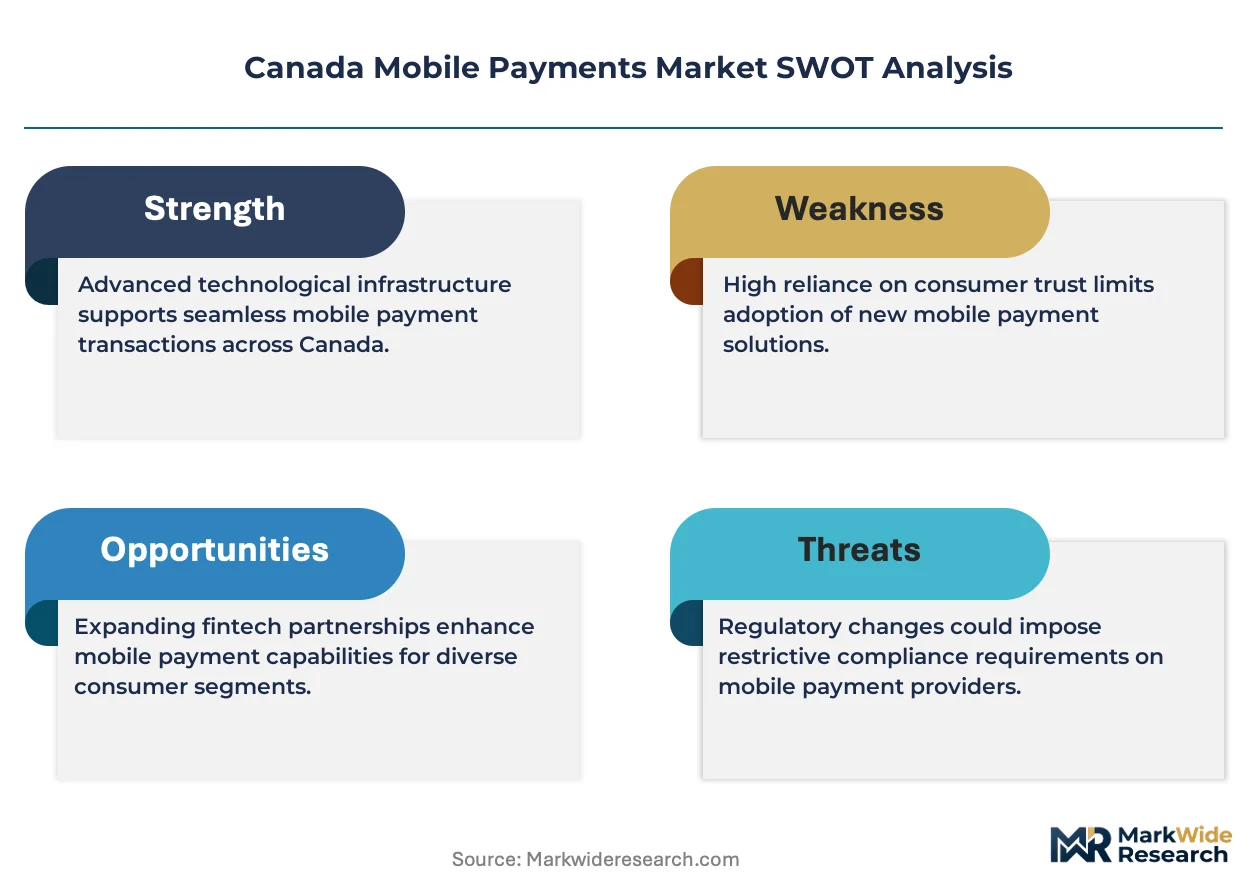
The Retail Payments Activities Act administered by the Bank of Canada imposes operational risk and safeguarding standards on payment service providers, directly elevating compliance costs for new market entrants. FINTRAC anti-money laundering protocols and PCI-DSS certification requirements further shape product architecture and vendor qualification criteria across the ecosystem. Stakeholders must monitor open banking implementation timelines and interoperability mandates that will determine whether incumbent banks or independent fintechs capture the next wave of payment innovation.
Market Dynamics
The Retail Payments Activities Act and Finance Canada's open banking framework are forcing payment service providers to rearchitect compliance infrastructure while competing for merchant relationships.
Growth Catalysts
- Contactless POS Infrastructure:Small businesses across Ontario's retail corridors are deploying near-field communication terminals. Transaction volume accelerates as merchant digitization outpaces legacy cash handling.
- Retail Payments Activities Act:The Bank of Canada's operational risk standards create regulatory clarity. Licensed payment service providers gain trust advantages in merchant acquisition.
- Gen Z Digital Wallet Adoption:Younger demographics in the Greater Toronto Area lead peer-to-peer transaction growth. Social payment norms displace traditional cash exchange in urban centers.
Market Restraints
- PCI-DSS Certification Burden:Payment Card Industry data security standards impose multi-quarter compliance timelines. Small fintech entrants face capital constraints in meeting infrastructure requirements.
- Interchange Fee Compression:Card network pricing pressure squeezes processor margins. Revenue-based financing models struggle to sustain unit economics at scale.
- Banking Incumbent Deposit Advantage:Royal Bank of Canada and Toronto-Dominion Bank leverage core deposit relationships. Integrated merchant services bundle payment acceptance with treasury management.
Strategic Opportunities
- Quebec and Prairie Province Expansion:Fintech density concentrates in Ontario while merchant digitization lags in Montreal and Calgary corridors. First-mover platforms capture underpenetrated independent retail segments.
- Open Banking API Convergence:Account-to-account payment rails and tokenized credential systems merge. Real-time fund settlement bypasses traditional card network infrastructure.
- Independent Contractor Micro-Merchant Segment:Gig economy workers and sole proprietors lack tailored payment solutions. Flat-rate pricing transparency attracts this underserved category.
Industry Challenges
- Cybersecurity Talent Scarcity:Encryption protocol specialists and fraud detection engineers command premium compensation. Payment platforms compete with broader fintech sector for limited domestic expertise.
- Legacy Core Banking Integration:Merchant cash advance underwriting requires real-time data feeds from incumbent deposit systems. API fragmentation across Canadian financial institutions complicates product deployment.
- FINTRAC Compliance Timeline:Anti-money laundering protocol updates demand continuous monitoring system upgrades. Reporting infrastructure investments divert engineering resources from feature development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Mobile Payments Market |
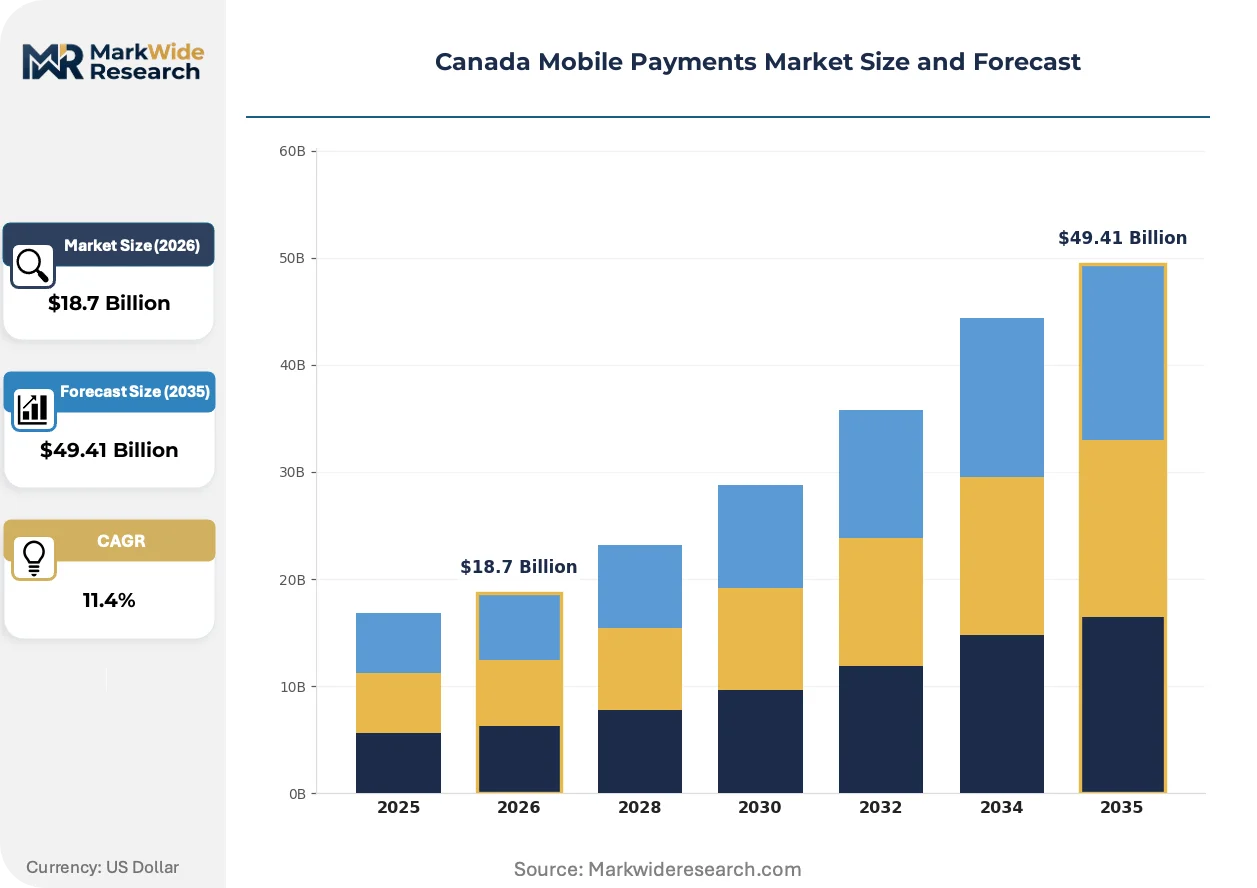
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Digital Wallet, Bank Transfer Transaction Type: In-Store, Online, Peer-to-Peer, Bill Payments Device Type: Smartphone, Tablet, Wearable, POS Terminal User Demographic: Millennials, Gen Z, Professionals, Small Businesses |
| Companies Covered | Samsung Electronics Co., Ltd., Royal Bank of Canada, Apple Inc., Stripe Inc., Moneris, PayPal Holdings Inc., Canadian Imperial Bank of Commerce, Square, Google LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Mobile Payments Market Strategic Shifts
Tokenized credential architectures and biometric authentication protocols are compressing transaction friction while regulatory mandates force interoperability investments across the Canadian payment stack.
SoftPOS technology transforms standard smartphones into payment acceptance terminals without dedicated hardware. Micro-merchants and independent contractors in Vancouver and Toronto corridors adopt these solutions fastest. Traditional point-of-sale terminal procurement is rendering obsolete as software-only deployment slashes merchant onboarding costs.
The Retail Payments Activities Act administered by the Bank of Canada imposes safeguarding and operational risk standards on payment service providers. Compliance infrastructure investments now consume significant product development budgets. New market entrants face extended qualification timelines before processing live transaction volume.
Social payment norms among Gen Z and millennial demographics prioritize peer-to-peer transfer convenience over traditional banking interfaces. Messaging-embedded payment flows and split-bill functionality displace standalone banking applications. This behavioral shift concentrates in Ontario's urban centers where fintech density supports feature innovation.
Canada Mobile Payments Market Segmentation
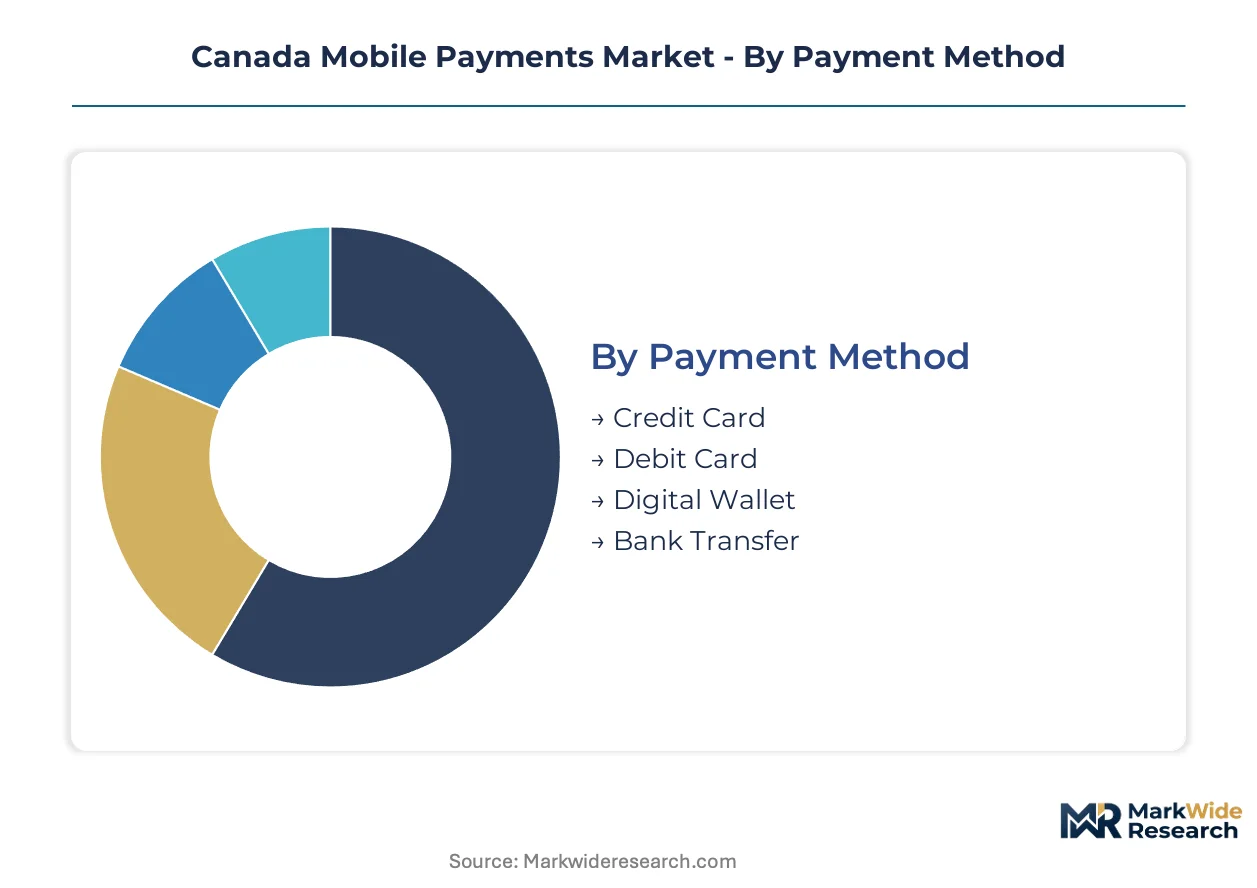
Segmentation reveals distinct infrastructure requirements across Canadian payment corridors. Merchant acquisition strategies diverge sharply between in-person terminal deployment and digital-first onboarding workflows. Compliance obligations under the Retail Payments Activities Act apply unevenly across transaction types, reshaping platform economics.
Payment Method:
After-sales service intensity concentrates in tokenized credential management and dispute resolution workflows, where platform liability exposure varies by payment rail architecture.
- Digital Wallet:Tokenized credential systems encrypt payment data within device-secured enclaves. Demand concentrates among Gen Z consumers in Toronto and Vancouver urban corridors where peer-to-peer social payment norms displace cash handling. Token provisioning complexity elevates customer support touchpoints.
- Credit Card:Revolving credit lines integrate with mobile interfaces through bank-issued digital credentials. Small businesses in Ontario's retail corridors prioritize chargeback protection and transaction dispute resolution services. Interchange fee structures compress processor margins at scale.
- Debit Card:Direct account deduction protocols require real-time balance verification across Canadian banking networks.
- Bank Transfer:Account-to-account rails bypass card network infrastructure entirely.
Digital wallets hold the largest share; momentum sits with bank transfer solutions.
Transaction Type:
Cost tier differentiation separates high-frequency low-margin in-store processing from premium-margin online transaction orchestration.
- In-Store:Near-field communication terminals execute contactless tap-to-pay protocols at physical merchant locations. Ontario's Greater Toronto Area retail corridors drive volume concentration as small business digitization accelerates. Terminal hardware procurement and firmware maintenance constitute ongoing cost burdens.
- Peer-to-Peer:Social payment flows enable fund exchange between individuals without merchant intermediary. Urban millennial and Gen Z demographics in Montreal and Calgary displace traditional cash exchange through messaging-embedded transfer interfaces. Split-bill functionality drives engagement frequency.
- Online:E-commerce checkout integration demands PCI-DSS certified hosting infrastructure.
- Bill Payments:Recurring utility and subscription settlement requires mandate management systems.
In-store transactions hold the largest share; peer-to-peer solutions are gaining share fastest.
Device Type:
Application-specific hardware requirements fragment procurement patterns across merchant segments.
- Smartphone:SoftPOS software transforms standard mobile devices into payment acceptance terminals without dedicated hardware. Independent contractors and gig economy workers in Vancouver adopt these solutions for zero upfront procurement cost. Operating system fragmentation across iOS and Android complicates certification timelines.
- POS Terminal:Dedicated near-field communication hardware dominates Canadian retail establishment checkout counters. Established merchants in Toronto and Ottawa corridors prioritize integrated receipt printing and inventory synchronization. Hardware depreciation cycles extend replacement timelines.
- Tablet:Larger screen real estate supports line-item visibility and signature capture workflows.
- Wearable:Tokenized credential storage in smartwatches and fitness bands enables contactless tap functionality.
POS terminals hold the largest share; smartphones are climbing the fastest.
User Demographic:
Customer type determines feature prioritization and pricing sensitivity across platform interfaces.
- Gen Z:Native digital wallet adoption prioritizes social payment integration and split-bill functionality over traditional banking feature depth. Concentration in Ontario urban centers drives peer-to-peer transaction volume growth. Messaging-embedded payment flows displace standalone application usage.
- Small Businesses:Merchant acquisition focuses on integrated payment acceptance with treasury management and cash advance underwriting. Royal Bank of Canada and Toronto-Dominion Bank leverage deposit relationships to bundle services. Revenue-based financing models reconfigure competitive entry barriers.
- Millennials:Dual preference for convenience and security drives omnichannel payment behavior.
- Professionals:Expense management integration and receipt categorization prioritize business-use feature sets.
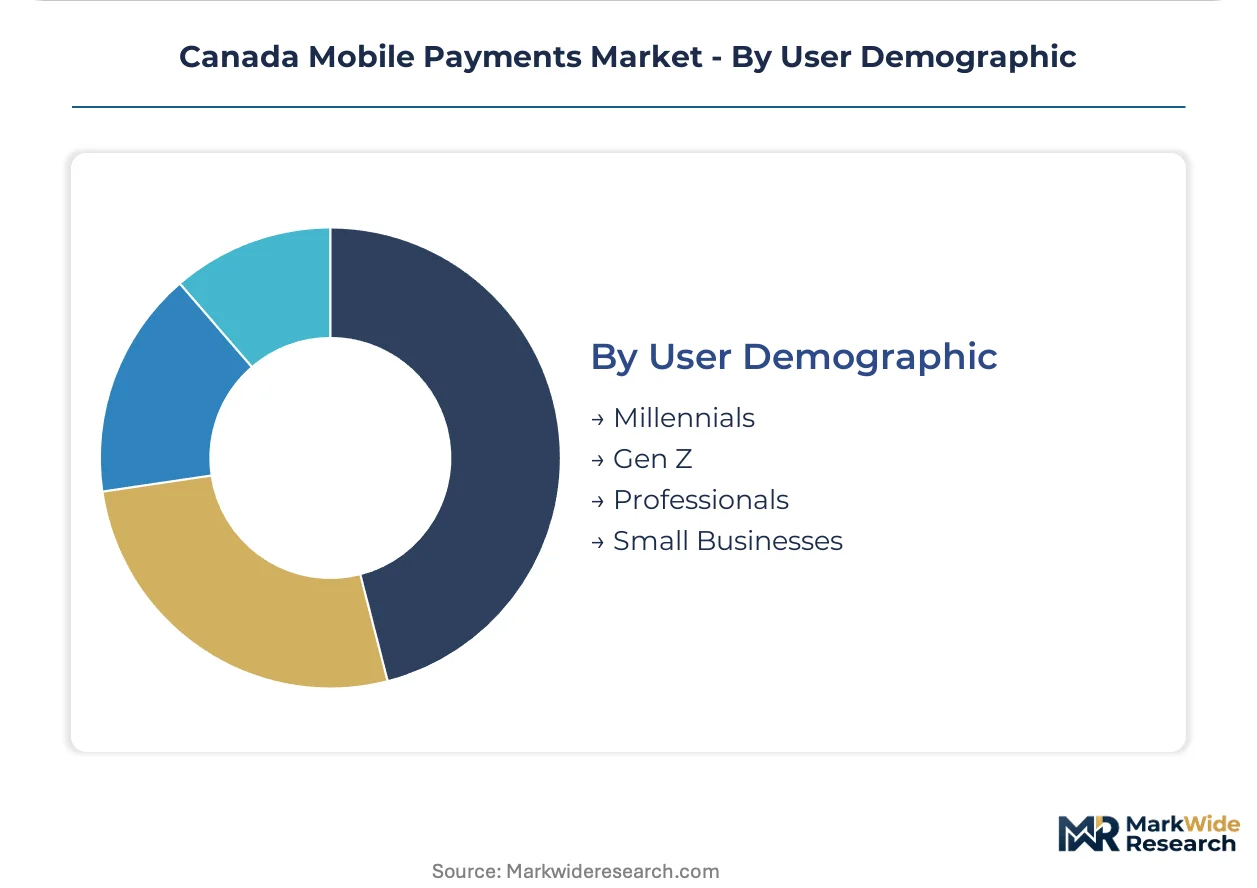
Small businesses hold the largest share; Gen Z shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's mobile payments ecosystem operates as a self-contained market with limited cross-border transaction flow, concentrating investment and regulatory development within domestic corridors rather than export-oriented infrastructure.
Ontario
The Greater Toronto Area generates the highest transaction density as merchant digitization accelerates through contactless point-of-sale deployment. Finance Canada's open banking framework implementation creates regulatory clarity for fintech operators seeking payment service provider licensing. Toronto's fintech corridor concentrates engineering talent and venture capital, driving platform innovation in tokenized credential systems.
Quebec
Montreal's merchant base exhibits slower digitization rates compared to Ontario, creating first-mover opportunities for payment platforms targeting independent retail segments. The Autorité des marchés financiers coordinates with federal regulators on payment supervision standards. Montreal's emerging fintech cluster focuses on bilingual service delivery and cross-cultural payment interface design.
British Columbia
Vancouver's gig economy workforce adopts SoftPOS solutions fastest, transforming smartphones into payment terminals without hardware procurement. The British Columbia Securities Administration monitors payment platform compliance with provincial consumer protection statutes. Vancouver's technology sector attracts mobile payment engineering talent from Asia-Pacific markets.
Alberta
Calgary's energy sector professionals drive demand for expense management integration within mobile payment applications. The Alberta Securities Commission enforces alignment with federal Retail Payments Activities Act standards. Calgary's independent retail corridors lag Toronto in contactless terminal penetration, presenting merchant acquisition opportunities.
Prairie Provinces
Saskatchewan and Manitoba agricultural communities show emerging demand for mobile payment solutions at farmers' markets and seasonal retail operations. Provincial financial regulators defer to Bank of Canada oversight for payment service provider licensing. Winnipeg and Regina serve as distribution nodes for payment terminal hardware servicing rural merchant networks.
Canada Mobile Payments Market Competitive Environment
On the supply side, the industry is tiered between deposit-anchored banking incumbents, specialized point-of-sale hardware-software bundlers, and flat-rate pricing challengers targeting micro-merchants. Strategic archetypes include integrated financial services conglomerates, merchant acquirer specialists, and platform-agnostic software providers. Dominant competitive moves encompass strategic partnerships with core banking systems and geographic expansion into underpenetrated provincial corridors.
Within the banking-anchored tier, Royal Bank of Canada and Canadian Imperial Bank of Commerce exemplify deposit-based merchant service integration, bundling payment acceptance with treasury management and cash advance underwriting. Among technology platform specialists, Samsung Electronics Co., Ltd. and Apple Inc. occupy positions in device-secured token provisioning, while Stripe Inc. and Square represent the flat-rate pricing transparency archetype that attracts independent contractors and sole proprietors underserved by traditional merchant acquiring structures.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Royal Bank of Canada |
| Apple Inc. |
| Stripe Inc. |
| Moneris |
| PayPal Holdings Inc. |
| Canadian Imperial Bank of Commerce |
| Square |
| Google LLC |
| Others |
Value Chain & Pricing Dynamics
PCI-DSS certification chokepoints determine both merchant acquisition cost spreads and vendor qualification timelines across the Canadian payment stack. Small fintech entrants face capital constraints that compress their pricing flexibility while extending supply chain onboarding cycles.
Pricing Analysis
Small business merchants anchor flat-rate pricing structures that dominate micro-merchant acquisition in Toronto and Vancouver corridors. Pricing stratifies across integrated banking bundles, hardware-software terminal packages, and pure-software SoftPOS deployments based on deposit relationship depth and after-sales service intensity. Cost compression in pure-software tiers intensifies because interchange fee pressure squeezes processor margins. Independent contractors exhibit highest price sensitivity; Royal Bank of Canada deposit holders show lowest sensitivity due to bundled treasury management value.
Supply Chain Analysis
Tariff exposure between China and Canada dominates near-field communication terminal procurement risk for hardware-dependent acquirers. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, while encryption chip assembly feeds from Malaysia and Vietnam. Supply chain vulnerability rests on single-source dependencies for PCI-DSS certified secure element modules. Distribution runs through Toronto-based wholesale distributors serving merchant networks across Ontario and Quebec.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Merchant cash advance underwriting and tokenized credential management represent service-attach layers expanding faster than point-of-sale hardware deployment. Recurring revenue from transaction analytics and fraud monitoring is displacing upfront terminal sales as the primary value capture mechanism.
For Market Incumbents: Build regulatory compliance moats through Retail Payments Activities Act licensing investments that extend qualification timelines for emerging competitors. Deepen backward integration into core banking API infrastructure to secure real-time data feeds for cash advance underwriting. Anchor deposit relationships with integrated treasury management bundles that raise switching costs for small business merchants.
For New Entrants and Emerging Players: Pursue Quebec and Prairie Province corridors where merchant digitization lags Toronto penetration rates. Target independent contractor segments in Vancouver and Calgary with zero-upfront SoftPOS solutions that bypass hardware procurement barriers. Lead with transparent flat-rate pricing that exposes incumbent bundle complexity.
For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors licensed payment service providers with existing Bank of Canada oversight. Long-term viability hinges on open banking API convergence readiness and real-time settlement infrastructure ownership. Watch FINTRAC compliance system upgrade announcements as inflection indicators for engineering resource allocation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Open Banking API Integration | Real-time account-to-account rails bypass card network infrastructure entirely. |
| SoftPOS Platform Launch | Software-only deployment slashes merchant onboarding costs in Vancouver corridors. |
| Quebec Market Expansion | Montreal's slower digitization creates first-mover acquisition opportunities. |
| Biometric Authentication Investment | Fingerprint and facial recognition protocols compress transaction friction. |
| Merchant Cash Advance Scaling | Revenue-based financing reconfigures competitive entry barriers. |
Study Parameters
Desk research of regulatory filings, payment processor financial disclosures, and Bank of Canada supervision reports preceded structured interviews with payment platform CTOs, merchant acquisition heads, and compliance officers at licensed service providers. Primary fieldwork with small business owners in Toronto, Montreal, and Vancouver corridors validated transaction volume assumptions. Secondary sources included Retail Payments Activities Act consultation documents, FINTRAC guidance updates, and open banking framework implementation timelines. Bottom-up merchant adoption modeling triangulated against top-down payment flow estimates from banking system data.
Assumption sets held regulatory implementation timelines and interchange fee structures fixed while varying fintech density projections and merchant digitization rates across provincial corridors. Segmentation modeling spanned payment method, transaction type, device architecture, and user demographic dimensions across the analysis window. CAGRs derived from S-curve adoption patterns fitted to contactless terminal deployment data and digital wallet penetration surveys. Industry-specific inputs incorporated PCI-DSS certification backlog estimates and cybersecurity talent pipeline constraints.
Macroeconomic conditions sit as an overlay; deviation in small business formation rates and consumer spending velocity would shift the trajectory. Forecasts reflect assumptions about open banking API standardization and Retail Payments Activities Act enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Cross-Border Payment Platform Market
Payments
GCC Payment Gateway Market
Payments
Accelerator Card Market
Payments
Epayment System Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
Australia Buy Now Pay Later Services Market
Payments
United Kingdom Mobile Payments Market
Payments
Global Wearable Payment Device Market
Payments
Europe Payment Gateways Market
Payments
United States Mobile Payment Market
Payments
Spain Mobile Payment Market
Payments
Norway POS Terminals Market
Payments
Medical Payment Fraud Detection Market
Payments
Canada Buy Now Pay Later Market
Payments
Third Party Payment Market
Payments
South Korea Mobile Payment Market