
 Poland Payments Market | 2026-2036
Poland Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Payments Market Analytics
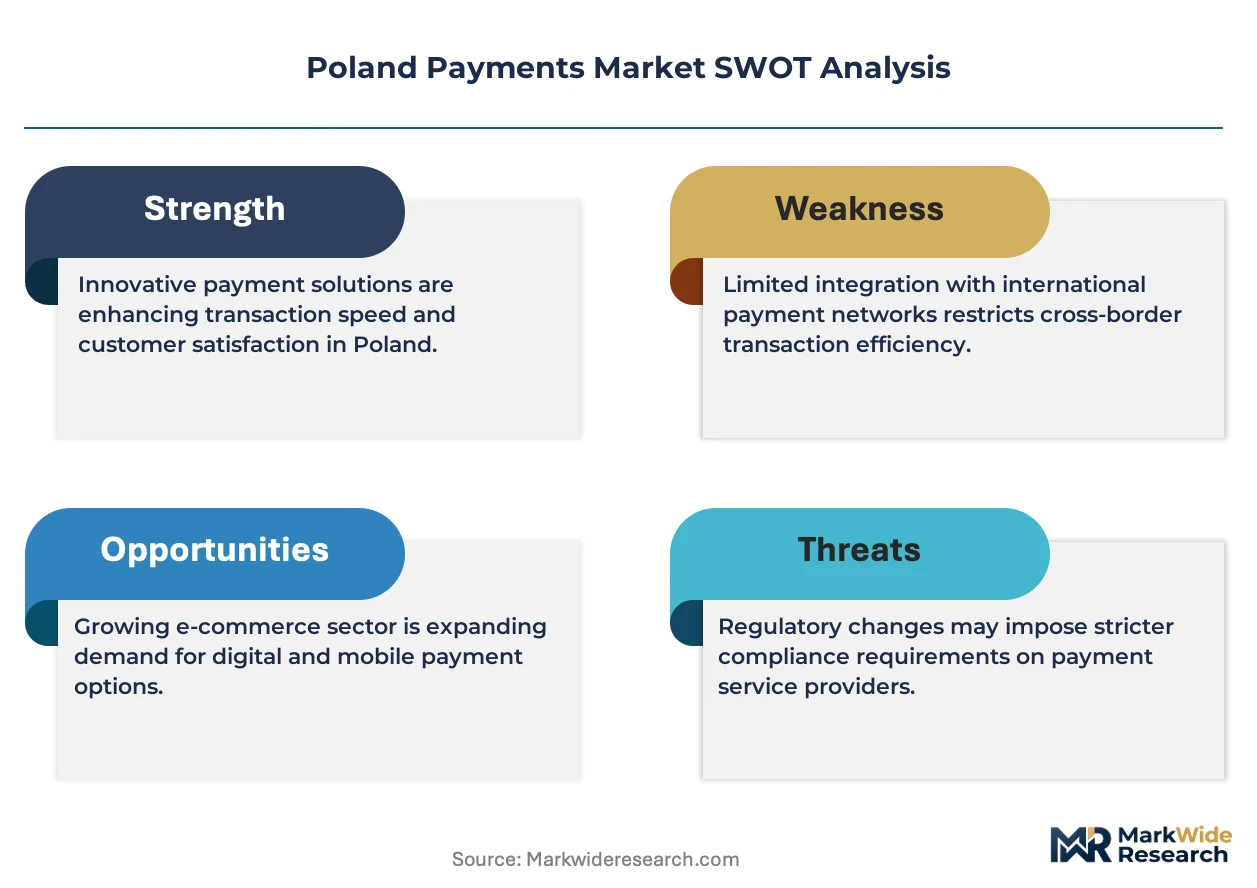
Real-time settlement capability is rotating from a premium feature to a baseline expectation across Polish retail banking. PKO Bank Polski leverages its branch density to anchor merchant acquiring relationships in tier-two cities. BLIK specializes in domestic instant payment rails that bypass international card networks for peer-to-peer and e-commerce transactions. PayU competes aggressively on cross-border checkout optimization for Polish merchants selling into European Union markets.
Poland Payments denotes electronic value transfer systems encompassing card networks, mobile wallets, bank transfers, and instant payment rails operating within Polish zloty and euro-denominated corridors, with settlement latency measured in seconds under modern infrastructure. These systems facilitate commercial exchange, treasury operations, and consumer financial access across physical and digital commerce environments. Mobile payment and bank transfer segments are capturing incremental volume as Polish consumers reduce cash dependency, while credit card issuance retains margin concentration among established banking groups. The merchant end-user category absorbs disproportionate investment in point-of-sale terminal modernization, particularly for small enterprises seeking to meet evolving consumer payment preferences.
The National Bank of Poland enforces payment system stability and oversight of instant settlement infrastructure, while the Polish Financial Supervision Authority governs electronic money institution licensing and anti-money laundering protocols for fintech entrants. EU PSD2 strong customer authentication requirements and forthcoming open banking standards compel incumbent banks to expose application programming interfaces, reshaping competitive access for non-bank payment providers. Stakeholders must monitor regulatory calibration between innovation facilitation and systemic risk containment as instant payment volumes accelerate.
Market Dynamics
The National Bank of Poland's PSD2 strong customer authentication mandate is compressing settlement latency expectations and forcing merchant acquirers to upgrade terminal infrastructure at unprecedented speed. This regulatory pressure is redistributing competitive advantage toward banks with dense branch networks and fintechs with API-native architectures.
Growth Catalysts
- PSD2 Compliance Deadlines:The National Bank of Poland's authentication requirements are accelerating contactless terminal deployment among small merchants who previously relied on cash.
- BLIK Network Expansion:Domestic instant payment rails are capturing e-commerce volume that previously routed through international card networks, reducing merchant discount rates.
- Warsaw-Kraków Digital Density:Mobile wallet penetration in these metropolitan clusters is creating demonstration effects that pull adoption into tier-two cities.
Market Restraints
- Terminal Hardware Costs:Small enterprises face concentrated capital requirements for NFC-enabled point-of-sale upgrades, compressing margins in fragmented retail.
- Core Banking System Rigidity:Legacy mainframe architectures at established Polish banks constrain real-time API response speeds required for instant payment rails.
- Złoty-Euro Corridor Dependency:Cross-border settlement remains tethered to correspondent banking relationships that introduce friction for Polish merchants selling abroad.
Strategic Opportunities
- Łódź-Wrocław Corridors:These tier-two urban agglomerations show sub-30% contactless penetration, creating whitespace for acquirers with branch-light distribution models.
- Open Banking API Monetization:The Polish Financial Supervision Authority's forthcoming standards will enable account-to-account payment initiation services that bypass card networks entirely.
- Biometric Authentication Convergence:Facial recognition integrated with BLIK codes is eliminating friction in high-value peer-to-peer transfers previously constrained by PIN entry.
Industry Challenges
- SCA Implementation Complexity:Merchants are struggling to integrate multiple authentication flows without cart abandonment spikes during checkout.
- Interoperable Standard Delays:Divergent technical specifications between domestic instant payment schemes and European SEPA Instant Credit Transfer are fragmenting developer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Payments Market |
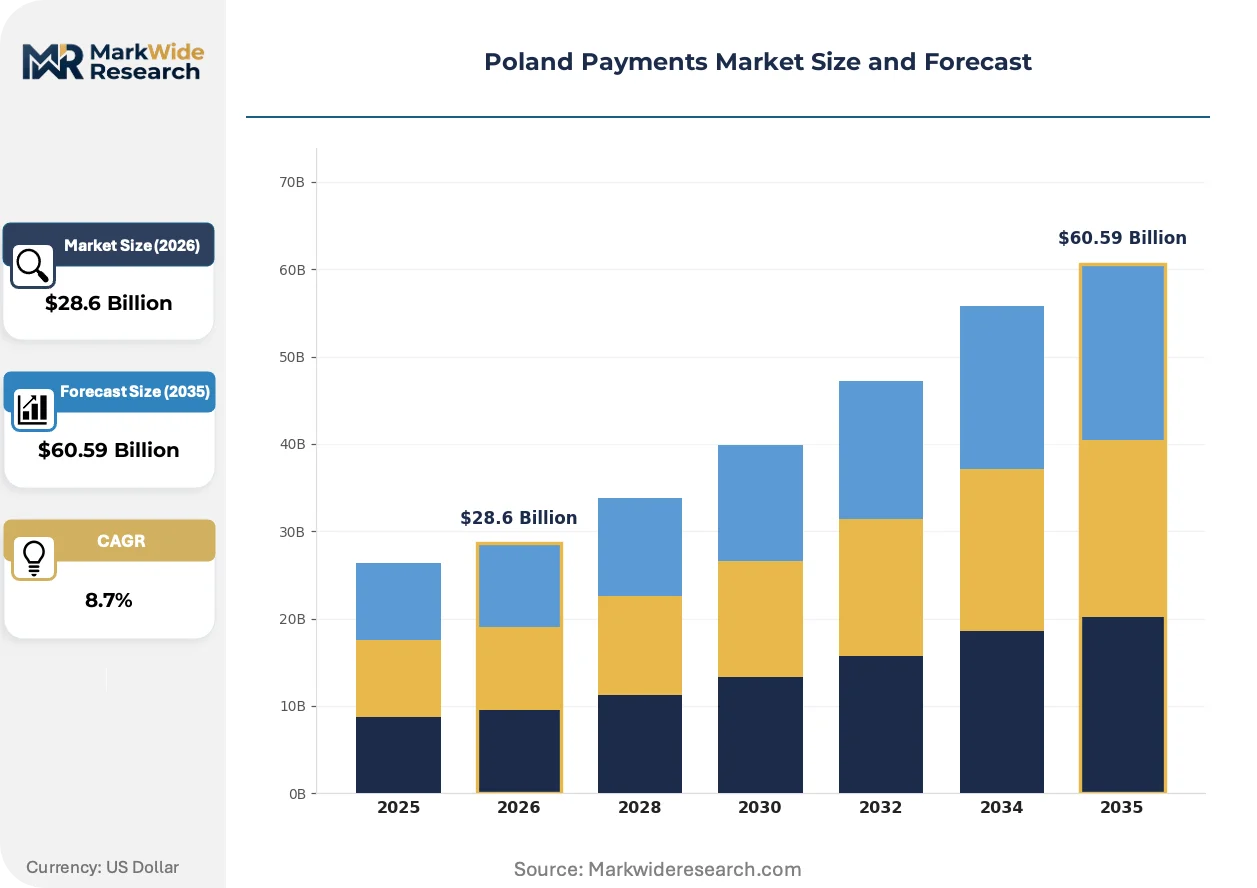
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Payment, Bank Transfer End User: Consumers, Merchants, Corporations, Financial Institutions Transaction Size: Low-Value, Medium-Value, High-Value, Microtransactions Service Type: Online Payment, In-Store Payment, Bill Payment, Remittances |
| Companies Covered | PayU, Apple Inc. (Apple Pay), PKO Bank Polski, Visa Inc., Mastercard, Bank Pekao, PayPal Holdings Inc., BLIK (Polski Standard Płatności), Santander Bank Polska, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Payments Market Evolving Landscape
Polish payment infrastructure is undergoing architectural disaggregation as proprietary banking stacks give way to API-orchestrated ecosystems. Three concurrent developments are compressing incumbent advantage while expanding fintech addressable market.
Tokenized card credentials are decomposing the traditional merchant acquiring value chain. Large retail chains in Warsaw are adopting network tokenization to reduce PCI-DSS compliance scope. This technology is compressing fraud liability pools and shifting risk allocation toward issuers with superior authentication data.
Poland's implementation of EU PSD2 strong customer authentication is mandating step-up authentication for e-commerce transactions above defined thresholds. The Polish Financial Supervision Authority's technical standards are forcing merchant platforms to redesign checkout flows. Small e-commerce operators are responding by outsourcing authentication to specialized third-party providers.
Consumer preference is rotating toward invisible payment experiences that eliminate explicit checkout steps. Subscription merchants and mobility-as-a-service providers are capturing this demand through stored credential frameworks. This behavioral shift is most visible among Warsaw's urban professional demographic, where transit and food delivery apps have normalized background charging.
Poland Payments Market Segmentation
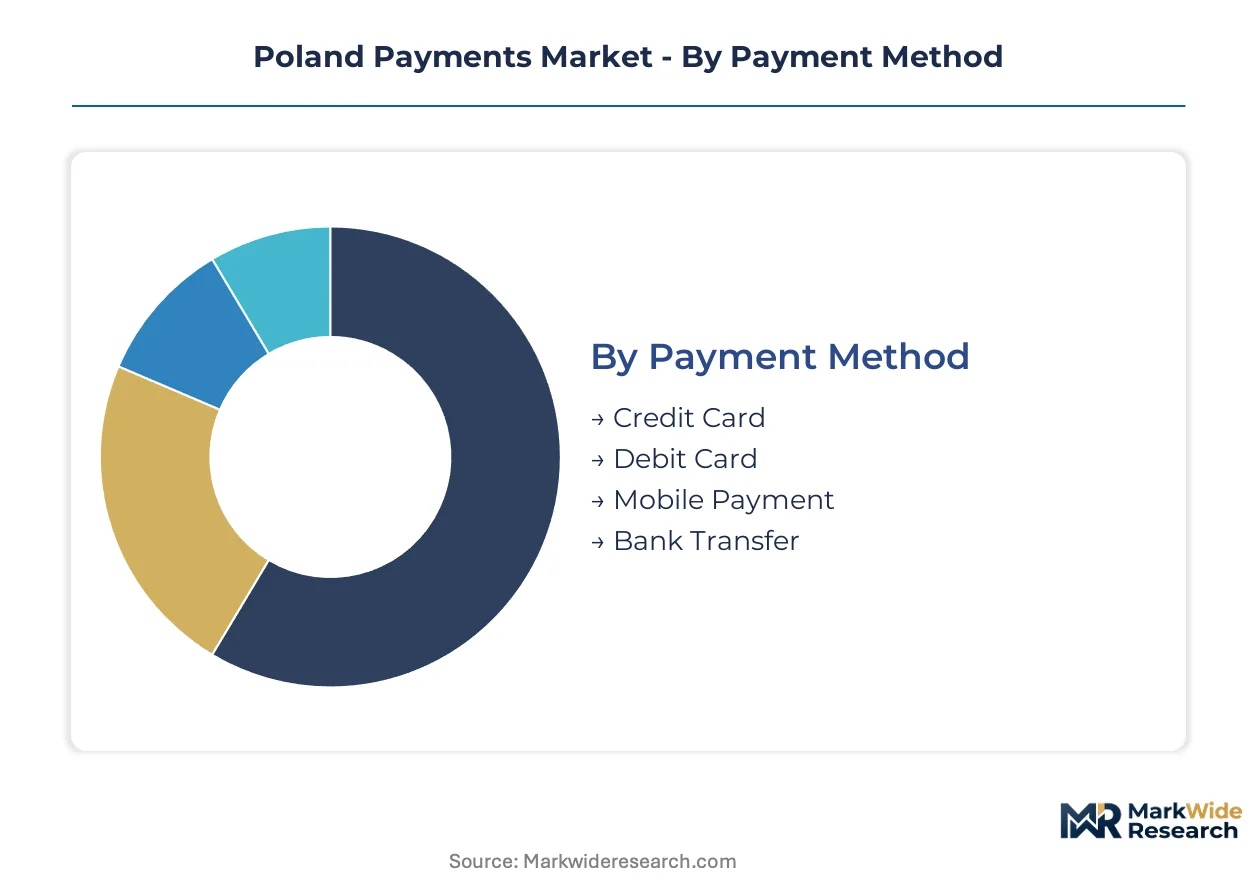
Payment method diversity in Poland reflects divergent regulatory treatment across instruments, with PSD2 authentication mandates reshaping relative economics for merchants and issuers. Segment boundaries are blurring as BLIK-enabled bank transfers compete for e-commerce volume previously dominated by card networks.
Payment Method:
The National Bank of Poland applies tiered authentication requirements that advantage certain instruments in high-velocity commerce environments.
- Credit Card:Revolving credit lines with interchange fee structures concentrated among established banking groups. Warsaw-based premium retailers absorb elevated merchant discount rates to capture affluent consumer segments seeking reward programs and chargeback protection.
- Mobile Payment:Smartphone-originated transactions leveraging NFC proximity or QR code scanning, predominantly BLIK-enabled or digital wallet-based. Kraków's urban professional demographic drives concentration here, with transit and food delivery apps normalizing background charging behaviors that bypass explicit checkout steps.
- Debit Card:Direct-linked demand deposit instruments with lower interchange burden. Tier-two city merchants favor these for cost-sensitive payment acceptance where credit penetration remains shallow.
- Bank Transfer:Account-to-account rails including instant settlement schemes that bypass card networks entirely. The Polish Financial Supervision Authority's forthcoming open banking standards will expand payment initiation services through exposed APIs.
Credit cards handle the majority of throughput; mobile payment is climbing the fastest on share as authentication friction diminishes.
End User:
Stakeholder investment priorities diverge sharply between consumer-facing convenience optimization and merchant-side infrastructure modernization.
- Merchants:Commercial entities accepting electronic value transfer, from micro-enterprises to retail chains. Small enterprises in Łódź and Wrocław corridors face concentrated capital requirements for NFC-enabled terminal upgrades mandated by regulatory deadlines.
- Consumers:Individual payment initiators whose authentication burden has intensified under PSD2 strong customer authentication requirements. Warsaw and Kraków clusters demonstrate adoption behaviors that pull tier-two city migration through demonstration effects.
- Corporations:Treasury operations and B2B payment orchestration requiring multi-bank connectivity and real-time cash visibility. These entities prioritize API-native architectures over legacy batch processing.
- Financial Institutions:Banks and licensed electronic money institutions governing settlement infrastructure and compliance frameworks. PKO Bank Polski leverages branch density to anchor acquiring relationships outside metropolitan cores.
Merchants absorb disproportionate infrastructure investment; consumers are gaining share fastest as authentication experiences streamline.
Transaction Size:
Settlement latency requirements and authentication thresholds segment the market by value band, with regulatory thresholds creating natural breakpoints.
- Low-Value:Transactions beneath PSD2 strong customer authentication thresholds, enabling frictionless contactless tap-and-go. These dominate Warsaw transit and convenience retail environments where speed outweighs explicit authorization.
- Microtransactions:Sub-złoty digital content and mobility-as-a-service increments processed through stored credential frameworks. Subscription merchants capture this demand through background charging mechanisms.
- Medium-Value:Routine commerce requiring step-up authentication under Polish Financial Supervision Authority technical standards. E-commerce platforms here struggle with cart abandonment during multi-factor flows.
- High-Value:Large-ticket purchases and peer-to-peer transfers where biometric convergence is eliminating PIN entry friction. Facial recognition integration with BLIK codes is reshaping this segment.
Low-value transactions carry the volume base; microtransactions are expanding most quickly as invisible payment experiences normalize.
Service Type:
Channel differentiation reflects infrastructure maturity gaps between digital-native and physical-retail environments.
- Online Payment:E-commerce checkout flows including card-not-present, bank transfer, and digital wallet options. Cross-border optimization dominates competitive positioning for Polish merchants selling into European Union markets.
- In-Store Payment:Physical point-of-sale acceptance through contactless terminals or QR codes. Terminal hardware costs compress margins for fragmented retail operators.
- Bill Payment:Recurring utility and service obligations increasingly automated through direct debit or instant payment initiation.
- Remittances:Cross-border value transfer remaining tethered to correspondent banking relationships that introduce friction for złoty-euro corridor settlement.
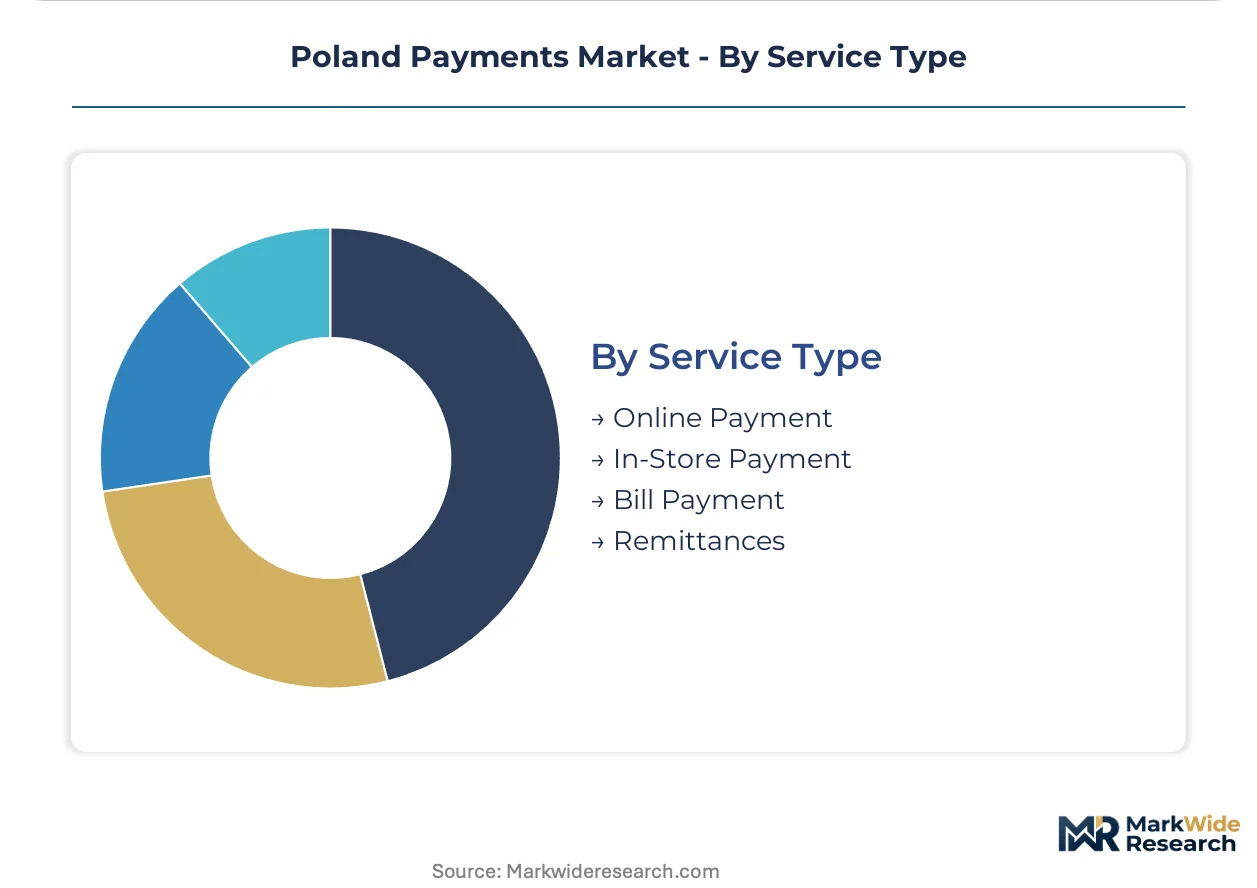
Online payment commands the revenue concentration; in-store payment is gaining share fastest as terminal deployment accelerates under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's payments sector operates as a net importer of cross-border settlement infrastructure, with domestic instant rails capturing volume previously routed through international networks. The National Bank of Poland's regulatory framework shapes corridor economics across the country's urban hierarchy.
Masovia
Warsaw's financial district concentrates merchant acquiring headquarters and fintech development labs. The Polish Financial Supervision Authority's licensing protocols govern electronic money institution authorizations processed through this corridor. Transit and food delivery apps in the capital normalize background charging behaviors that diffuse to smaller cities.
Lesser Poland
Kraków's urban professional demographic drives mobile wallet penetration rates exceeding national averages. The National Bank of Poland's PSD2 strong customer authentication deadlines compress terminal deployment timelines for merchants here. Software engineering clusters in the city feed API-native payment architecture development.
Łódź Voivodeship
Sub-30% contactless penetration creates whitespace for branch-light acquirers targeting cost-sensitive retail. The Polish Financial Supervision Authority's forthcoming open banking standards will enable account-to-account payment initiation services. Terminal hardware investments concentrate in commercial corridors linking the city to Warsaw.
Lower Silesia
Wrocław's manufacturing base generates B2B treasury operations demanding real-time cash visibility. The National Bank of Poland's oversight of instant settlement infrastructure governs corporate payment orchestration. Industrial parks surrounding the city anchor merchant relationships for tier-two acquiring strategies.
Pomerania
Gdańsk's port logistics create cross-border settlement friction for exporters operating in złoty-euro corridors. The Polish Financial Supervision Authority's anti-money laundering protocols shape correspondent banking relationships. Maritime commerce clusters drive demand for multi-currency payment acceptance.
Poland Payments Market Competitive Landscape
Listed leaders compete with private specialists across infrastructure ownership and merchant relationship models. PKO Bank Polski leverages branch density to anchor acquiring outside metropolitan cores, while BLIK operates as a domestic instant rail bypassing international networks. Three archetypes dominate: universal banks with legacy terminal estates, fintechs with API-native architectures, and card networks defending cross-border optimization. Consolidation pressures intensify as regulatory deadlines force terminal upgrades, while partnerships between banks and technology providers reshape distribution economics.
Among universal banking groups, PKO Bank Polski and Bank Pekao occupy positions defined by branch network scale and core banking system heritage. PayU exemplifies the cross-border optimization archetype, competing for Polish merchants selling into European Union markets. BLIK represents the domestic rail specialization, capturing e-commerce volume through instant payment codes that displace card network routing. Santander Bank Polska sits within the foreign-owned subsidiary tier, importing parent-group technology while adapting to Polish regulatory calibration.
| Leading Market Players |
|---|
| PayU |
| Apple Inc. (Apple Pay) |
| PKO Bank Polski |
| Visa Inc. |
| Mastercard |
| Bank Pekao |
| PayPal Holdings Inc. |
| BLIK (Polski Standard Płatności) |
| Santander Bank Polska |
| Others |
Value Network & Pricing Analysis
Take-or-pay terminal leasing contracts lock small Polish merchants into multi-year hardware commitments that flatten cost volatility while constraining supplier switching. These arrangements tether merchant acquirers to terminal manufacturers and bind pricing predictability to regulatory compliance timelines enforced by the Polish Financial Supervision Authority.
Pricing Analysis
Industrial OEM buyers anchor merchant discount rate negotiations through volume concentration and multi-year acquiring contracts. Three-tier pricing structure across premium integrated POS, standard standalone terminals, and economy mobile-only readers stratifies the hardware market. Pricing pressure stems from PSD2-mandated NFC upgrade cycles compressing replacement timelines. Micro-enterprises in Łódź corridors exhibit acute price sensitivity, while Warsaw retail chains absorb premium tiers for omnichannel integration.
Supply Chain Analysis
Semiconductor fabrication chokepoints in Taiwan and South Korea constrain NFC chip availability for Polish terminal deployments. Supply draws from Chinese assembly plants, German logistics hubs, and domestic Polish distribution centers. Single-source vulnerability concentrates in secure element manufacturing. Distribution feeds from Warsaw-based wholesaler networks into tier-two city installer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's payments sector sits at a platform-economics inflection where BLIK's domestic rail interoperability with EU instant payment schemes will reshape network effects and merchant switching costs.
For Market Incumbents: Fortify core banking API response speeds to defend against fintech disintermediation of instant payment initiation. PKO Bank Polski and Bank Pekao should deepen branch-based acquiring relationships in Łódź-Wrocław corridors before branch-light entrants capture whitespace. Certification investment in biometric authentication standards will anchor high-value transaction retention. For New Entrants and Emerging Players: Anchor in account-to-account payment initiation services enabled by forthcoming Polish Financial Supervision Authority open banking standards. The Łódź Voivodeship corridor offers sub-30% contactless penetration with concentrated small-merchant hardware demand. A direct-to-merchant terminal financing model bypasses incumbent acquirer relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among API-native payment orchestration platforms serving cross-border Polish e-commerce. Five-to-ten year viability favors specialists with SEPA Instant Credit Transfer interoperability rather than domestic-only rails. The signal to watch is merchant abandonment rate divergence between BLIK-enabled and card-network checkout flows.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Integration | Facial recognition convergence with BLIK codes eliminates PIN friction in high-value peer-to-peer transfers. |
| Open Banking API Development | Payment initiation services bypass card networks entirely under Polish Financial Supervision Authority standards. |
| Tier-Two City Terminal Deployment | Branch-light distribution models capture Łódź-Wrocław whitespace before incumbent network extension. |
| Cross-Border Checkout Optimization | SEPA Instant interoperability reduces złoty-euro corridor friction for Polish EU-market merchants. |
| Merchant Acquiring Consolidation | Regulatory terminal upgrade deadlines force sub-scale acquirers toward partnership or exit. |
Research Methodology
The analysis maps payment method segments, end-user categories, and transaction value bands, each validated through merchant acquiring executives, terminal hardware procurement leads, and Polish Financial Supervision Authority compliance officers. Primary interview data triangulates against National Bank of Poland payment system reports, EU PSD2 implementation filings, and BLIK network operator disclosures. Bottom-up terminal deployment estimates and top-down payment volume projections cross-validate segment sizing.
Consistency checks against SEPA Instant Credit Transfer adoption benchmarks and Polish e-commerce growth indices validated volume and value outputs across the projection horizon. The analytical framework models payment method substitution dynamics, authentication friction effects, and merchant infrastructure investment cycles. CAGRs derive from terminal replacement curves, regulatory deadline impacts, and behavioral adoption parameters specific to Polish digital wallet penetration patterns.
Material uncertainties — regulatory calibration shifts, instant payment interoperability delays, and macroeconomic merchant investment constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions about PSD2 compliance timelines and open banking standard implementation. Revision becomes warranted when BLIK-EU rail interoperability implementation crosses technical or political thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Dual Interface Payment Card Market
Payments
Mobile Payment Data Protection Market
Payments
Instant Payments Market
Payments
Accelerator Card Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
United Kingdom Payment Gateway Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Saudi Arabia Mobile Payments Market
Payments
UK Prepaid Cards Market
Payments
Europe Payments Market
Payments
Digital Payment in Healthcare Market
Payments
Singapore Remittance Market
Payments
Master Recharge API Market
Payments
B2C Payment Market
Payments
Malta POS Terminal Market
Payments
Global Mobile Payment Technology Market