
 Global Payment Monitoring Market | 2026-2036
Global Payment Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Payment Monitoring Market Foresight
PCI DSS Level 1 certification is rotating as the primary gating credential for enterprise payment monitoring vendors. FIS leverages its core banking integration depth to sustain platform stickiness across tier-one financial institutions. NICE Actimize anchors its position through specialized behavioral analytics for anti-money laundering workflows. Oracle Corporation competes by extending database-layer transaction processing into native monitoring modules.
Payment monitoring encompasses real-time surveillance of fund movement across digital channels, employing rule engines, machine learning classifiers, and network graph analytics to flag anomalies, assess risk exposure, and enforce regulatory compliance. The architecture processes sub-200 millisecond latency thresholds for high-velocity clearing environments while maintaining immutable audit trails for forensic investigation. Cloud-based deployment models are capturing the fastest expansion as banks shed capital-intensive on-premises infrastructure. Fraud detection solutions command the deepest margin pools due to tiered pricing tied to transaction volume bands and regulatory penalty exposure. Behavioral analytics represents the emerging growth vector as institutions shift from static rules to dynamic entity profiling.
FFIEC guidance in the United States, PSD2 in Europe, and RBI's digital payment security framework in India collectively mandate layered authentication logging and suspicious activity reporting. These frameworks shape procurement specifications by embedding compliance thresholds directly into vendor RFP requirements. Stakeholders must weigh cloud migration timelines against data residency constraints as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Real-time payment rails are compressing transaction processing windows from minutes to milliseconds, forcing surveillance infrastructure to migrate from batch-based screening to stream-processing architectures that evaluate risk before settlement finality.
Growth Catalysts
- India's UPI expansion:Transaction volumes exceeding 10 billion monthly payments are mandating sub-100 millisecond fraud detection at the network layer, pulling banks toward cloud-native monitoring stacks.
- PSD2 Strong Customer Authentication:European open banking mandates require continuous authentication logging across third-party payment initiation, embedding compliance monitoring into every API call.
- Behavioral biometrics adoption:Device fingerprinting and keystroke dynamics are layering identity verification atop transaction surveillance, creating incremental software attach rates for monitoring vendors.
Market Restraints
- Data residency fragmentation:Singapore's Personal Data Protection Act, India's data localization directives, and EU GDPR Article 44 restrictions are forcing vendors to maintain jurisdiction-specific infrastructure instances, inflating operational complexity.
- Legacy core system entrenchment:Tier-one banks in the United States and Japan maintain decades-old mainframe architectures that resist real-time API integration, extending deployment timelines.
- Specialized talent scarcity:Machine learning engineers with financial crime domain expertise command premium compensation, constraining vendor scaling velocity.
Strategic Opportunities
- Embedded finance penetration:Non-bank platforms in Brazil and Nigeria deploying payment services are procuring white-label monitoring modules rather than building compliance infrastructure in-house.
- Cross-border instant payment convergence:The ISO 20022 messaging standard harmonization across FedNow, TARGET Instant Payment Settlement, and Singapore's FAST is enabling unified surveillance dashboards.
- Regulatory sandbox participation:The Monetary Authority of Singapore's sandbox framework permits live testing of AI-driven anomaly detection without full licensing, accelerating product validation cycles.
Industry Challenges
- PCI DSS Level 1 certification timelines:The 6-12 month audit cycle for the highest compliance tier delays vendor market entry and freezes procurement decisions at risk-averse institutions.
- False positive calibration:Rule engine tuning that minimizes customer friction while satisfying suspicious activity reporting thresholds requires continuous model retraining, consuming data science bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Payment Monitoring Market |
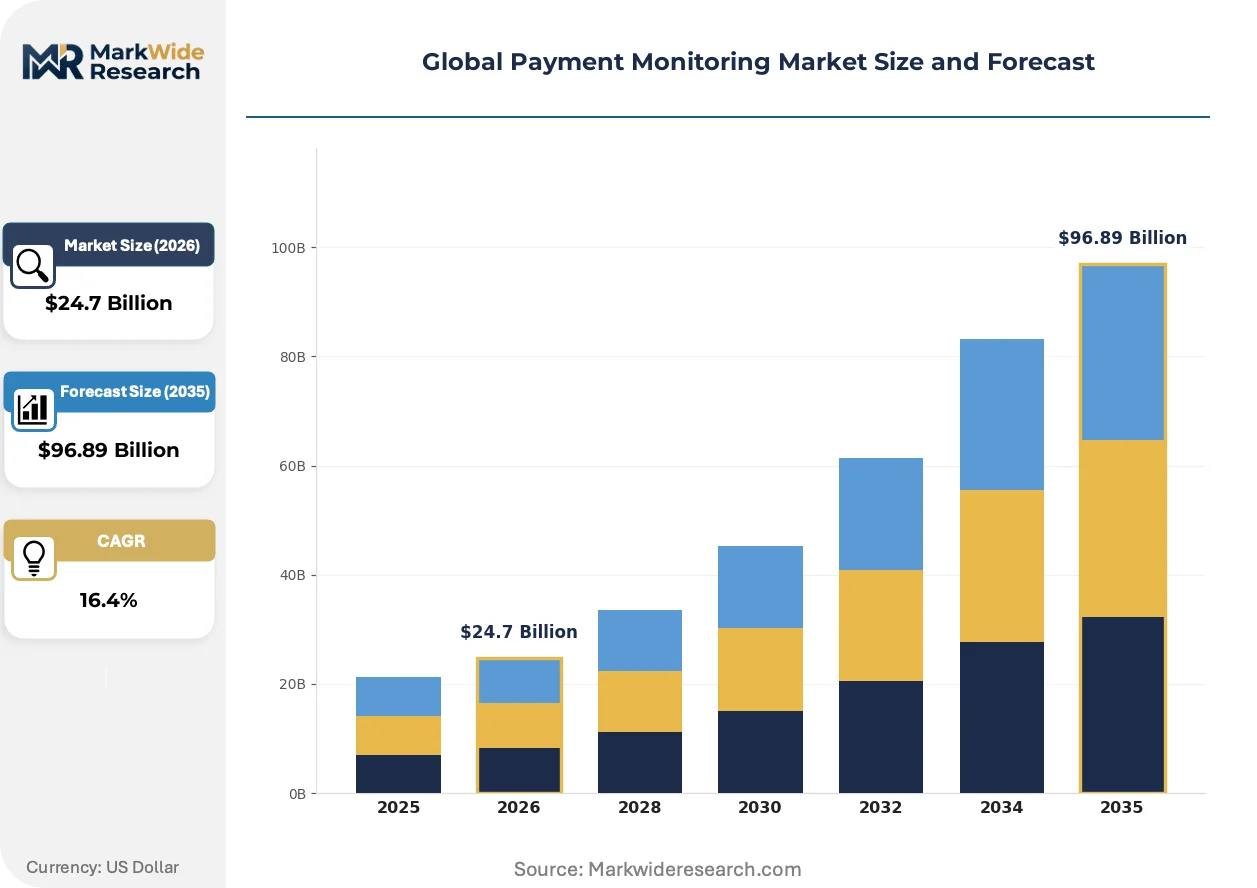
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $96.89 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Fraud Detection, Transaction Analytics, Risk Management, Compliance Monitoring, Anomaly Detection, Behavioral Analytics Deployment Model: Cloud-Based, On-Premises, Hybrid, Software-as-a-Service, Managed Services End User Industry: BFSI Institutions, E-Commerce Brands, Telecommunication Providers, Government Agencies, Travel Enterprises, Education Sector Transaction Channel: Mobile Payments, Point-of-Sale, Online Banking, Card Networks, Automated Clearing House, Wire Transfers |
| Companies Covered | FICO, FIS, Fiserv, Oracle Corporation, SAS Institute, Experian Information Solutions, NICE Actimize, ACI Worldwide, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Payment Monitoring Market Shifts & Advancements
Payment monitoring architecture is bifurcating between centralized cloud-native platforms and edge-deployed inference engines, with the balance shifting based on data sovereignty requirements and latency tolerances.
Graph neural networks for entity resolution are fragmenting traditional rules-based transaction monitoring. These models map hidden relationships across corporate hierarchies and beneficial ownership structures. Tier-two banks in Germany and Australia are piloting deployments to identify shell company networks. The technology is fragmenting vendor competitive positioning by rewarding specialized data science capabilities over incumbent installed base.
FFIEC guidance on authentication in an increasingly digital environment is mandating stepped-up verification for high-risk transactions. US community banks must document risk-based decision logic for examination scrutiny. The guidance is compressing procurement cycles for behavioral analytics modules that demonstrate audit trail completeness.
Buyers are unbundling monitoring software from core banking contracts. Institutions in the Netherlands and South Korea are issuing standalone RFPs for fraud detection rather than accepting bundled modules from legacy providers. This pattern is most pronounced among digital-native challenger banks with in-house core development capabilities.
Global Payment Monitoring Market Segmentation
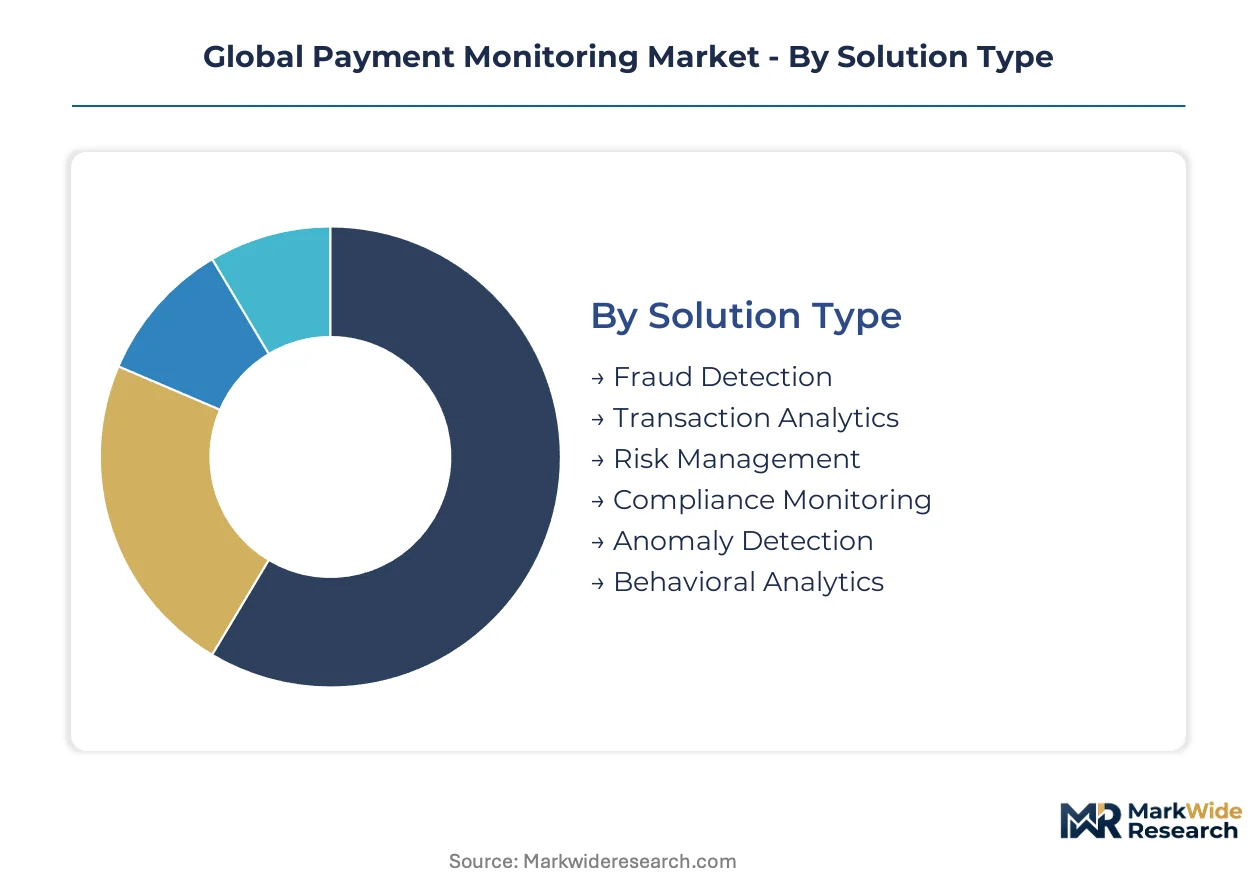
Payment monitoring procurement diverges sharply across solution architectures and deployment economics. Banks prioritize fraud detection modules with volume-scaled pricing, while fintech platforms favor cloud-native behavioral analytics with API-first integration.
Solution Type:
Fraud detection commands the deepest margin pools due to tiered pricing tied to transaction volume bands and regulatory penalty exposure.
- Fraud Detection:Rule engines and machine learning classifiers evaluate transaction velocity, geolocation mismatches, and device fingerprints in sub-200 millisecond windows. Tier-one banks in Singapore and India's UPI ecosystem are consolidating procurement around platforms with PCI DSS Level 1 certification to satisfy network operator mandates.
- Behavioral Analytics:Dynamic entity profiling replaces static rules through keystroke dynamics, mouse movement patterns, and session behavioral baselines. European open banking providers under PSD2 Strong Customer Authentication requirements are embedding these modules into every third-party payment initiation API call.
- Transaction Analytics:Real-time stream processing of fund movement data for liquidity optimization and settlement risk assessment.
- Risk Management:Portfolio-level exposure quantification across counterparty and geographic concentrations.
- Compliance Monitoring:Automated suspicious activity report generation aligned with FFIEC guidance and RBI digital payment security frameworks.
- Anomaly Detection:Unsupervised learning models flag deviation from historical transaction patterns without predefined rule sets.
The dominant share belongs to Fraud Detection, while Behavioral Analytics is closing the gap fastest.
Deployment Model:
Cloud-based architectures are capturing procurement preference as banks shed capital-intensive data center commitments.
- Cloud-Based:Elastic compute scaling supports transaction volume spikes exceeding 10 billion monthly payments on India's UPI rails without infrastructure overprovisioning. Singapore's fintech corridor and Brazil's embedded finance platforms are mandating multi-availability-zone deployments.
- Software-as-a-Service:Subscription pricing eliminates upfront license fees, enabling tier-two banks and non-bank payment platforms to access enterprise-grade surveillance capabilities. Nigeria's digital payment startups and Netherlands challenger banks are procuring white-label modules rather than building compliance infrastructure in-house.
- On-Premises:Air-gapped installations persist where data localization directives or sovereign cloud requirements prohibit cross-border data transit.
- Hybrid:Sensitive entity resolution processing remains on-premises while non-PII analytics shifts to cloud inference engines.
- Managed Services:Vendor-operated monitoring infrastructure with embedded compliance expertise for institutions lacking in-house data science teams.
Cloud-Based deployments hold the largest installed base, though Software-as-a-Service is expanding most quickly among digital-native entrants.
End User Industry:
BFSI institutions concentrate procurement value through multi-year enterprise contracts with integrated core banking dependencies.
- BFSI Institutions:Universal banks, payment processors, and card networks require sub-100 millisecond fraud detection at clearing layer with immutable audit trails for forensic investigation. Japan's megabanks and Germany's tier-one institutions maintain decades-old mainframe architectures that resist real-time API integration.
- E-Commerce Brands:Merchant-facing transaction screening with chargeback liability shifting creates demand for checkout-embedded risk scoring. South Korean marketplace platforms and Southeast Asian super-apps are unbundling monitoring software from legacy payment gateway contracts.
- Telecommunication Providers:Mobile money wallets in Sub-Saharan Africa and South Asia require lightweight surveillance modules for agent-network cash-in/cash-out monitoring.
- Government Agencies:Treasury payment systems and social benefit distribution platforms mandate enhanced due diligence on beneficiary identity verification.
- Travel Enterprises:Cross-border booking platforms face elevated scrutiny for card-not-present fraud and dynamic currency conversion manipulation.
- Education Sector:University payment portals and international student fee processing require PCI DSS compliance with limited IT security staffing.
BFSI Institutions anchor procurement volume, while E-Commerce Brands are gaining share fastest through embedded finance expansion.
Transaction Channel:
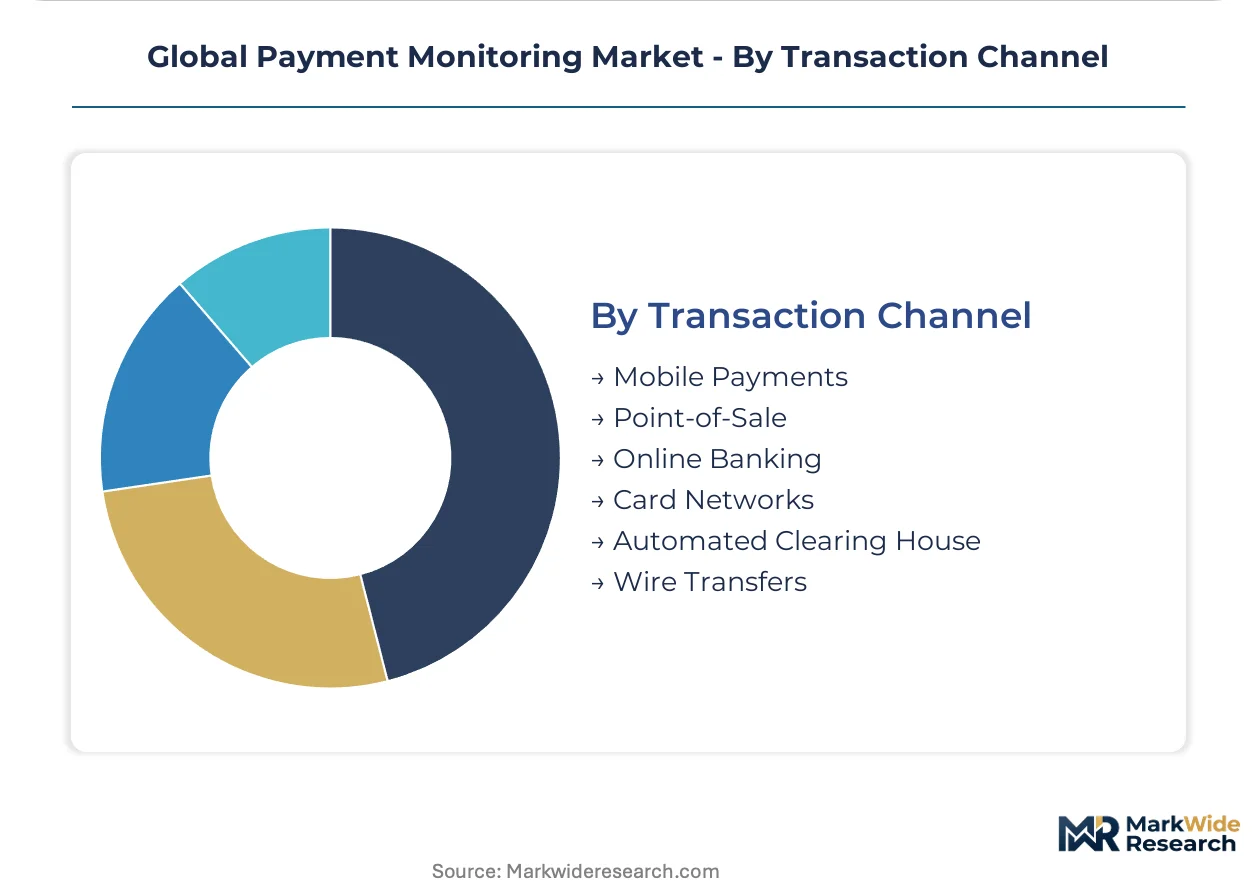
Mobile payment rails are compressing processing windows and forcing surveillance infrastructure toward stream-processing architectures.
- Mobile Payments:App-based fund transfers, QR code settlements, and wallet-to-wallet transactions generate the highest velocity data streams requiring edge-deployed inference engines. India's UPI network processes volumes mandating network-layer fraud detection before settlement finality.
- Point-of-Sale:Card-present transactions with EMV chip authentication and contactless tap-to-pay interfaces. Australia's major retailers and Germany's merchant acquiring networks are piloting graph neural networks for entity resolution at terminal level.
- Online Banking:Web-based fund transfers and bill payment interfaces with stepped-up authentication for high-risk transactions under FFIEC guidance.
- Card Networks:Interchange clearing and authorization messaging with real-time decline decisions on suspected fraud.
- Automated Clearing House:Batch-processed direct debits and credits with next-day settlement windows enabling post-hoc anomaly review.
- Wire Transfers:High-value correspondent banking payments with SWIFT gpi tracking and sanctions screening requirements.
Mobile Payments represents the largest addressable channel, while Point-of-Sale is climbing the fastest through contactless adoption curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI's digital payment security framework and Singapore's fintech sandbox policies are accelerating procurement of real-time surveillance infrastructure across Asia-Pacific financial centers. European PSD2 mandates and US FFIEC guidance are forcing parallel modernization cycles in Western markets.
United States
FFIEC authentication guidance mandates stepped-up verification logging for high-risk transactions, compressing procurement cycles for behavioral analytics modules. Community banks face examination scrutiny requiring documented risk-based decision logic. New York's financial district and Chicago's clearinghouse corridor anchor enterprise contract concentration for tier-one institutions.
Singapore
The Monetary Authority of Singapore's sandbox framework permits live testing of AI-driven anomaly detection without full licensing, accelerating product validation cycles for monitoring vendors. Personal Data Protection Act requirements enforce jurisdiction-specific infrastructure instances. The fintech corridor along Marina Bay drives cloud-native procurement preference among digital-native challengers.
India
UPI transaction volumes exceeding 10 billion monthly payments mandate sub-100 millisecond fraud detection at the network layer, pulling banks toward elastic cloud architectures. RBI data localization directives prohibit cross-border data transit for payment surveillance. Mumbai's banking headquarters and Bengaluru's technology cluster concentrate vendor deployment activity.
Germany
PSD2 Strong Customer Authentication embeds compliance monitoring into every third-party payment initiation API call across open banking providers. Tier-one institutions maintain decades-old mainframe architectures resisting real-time integration, extending deployment timelines. Frankfurt's financial center and Berlin's fintech ecosystem split procurement between legacy modernization and greenfield cloud deployments.
Brazil
Embedded finance penetration drives non-bank platforms to procure white-label monitoring modules rather than build compliance infrastructure in-house. Central bank instant payment infrastructure expansion creates demand for real-time surveillance at acquiring networks. São Paulo's financial district anchors procurement concentration for merchant-facing transaction screening.
Global Payment Monitoring Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with core banking integration depth alongside specialized fraud detection pure-plays. Market structure exhibits tiered consolidation with three to five dominant platforms capturing enterprise procurement at tier-one institutions while mid-tier vendors compete for regional bank and fintech contracts. Strategic archetypes include database-layer infrastructure extenders, behavioral analytics specialists, and payment network-integrated platforms. Competitive dynamics center on PCI DSS Level 1 certification attainment and cloud-native architecture migration to capture UPI-scale volume processing contracts.
Within the core banking-integrated tier, FIS leverages platform stickiness across tier-one financial institutions through deep legacy system integration. NICE Actimize anchors specialized positioning through behavioral analytics workflows for anti-money laundering applications. Oracle Corporation occupies the database-layer extender archetype by processing transaction data through native monitoring modules. These three exemplify divergent competitive vectors: integration depth versus analytical specialization versus infrastructure consolidation.
| Leading Market Players |
|---|
| FICO |
| FIS |
| Fiserv |
| Oracle Corporation |
| SAS Institute |
| Experian Information Solutions |
| NICE Actimize |
| ACI Worldwide |
| BAE Systems |
| Others |
Supply & Pricing Matrix
Cloud-native infrastructure substitution for on-premises data centers simultaneously redraws supply geography toward Singapore's fintech corridor and India's UPI ecosystem while compressing pricing economics through elastic compute scaling. This displacement forces vendors to recalibrate margin structures across deployment models as banks shed capital-intensive infrastructure commitments.
Pricing Analysis
Cost-plus contracts indexed to transaction volume bands dominate enterprise procurement, with tier-one banks negotiating rates tied to monthly payment throughput thresholds. Three-tier pricing structure across PCI DSS Level 1 certified platforms, standard compliance tiers, and economy SaaS modules separates premium fraud detection capabilities from basic rule-engine deployments. Pricing pressure stems from India's UPI network mandating sub-100 millisecond detection at network-layer economics. Digital-native challenger banks exhibit highest price sensitivity, while Japan's megabanks accept premium positioning for mainframe integration depth.
Supply Chain Analysis
Inbound logistics costs through Singapore's port infrastructure and container availability on Asia-Pacific trade lanes concentrate component sourcing for edge-deployed inference engines. Hardware assembly draws from Taiwan's semiconductor foundries, South Korea's memory fabrication, and China's server manufacturing. Supply chain risk centers on single-source vulnerability for specialized machine learning accelerators. Distribution runs through vendor-operated cloud availability zones with jurisdiction-specific instances mandated by India's data localization directives and EU GDPR Article 44 restrictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
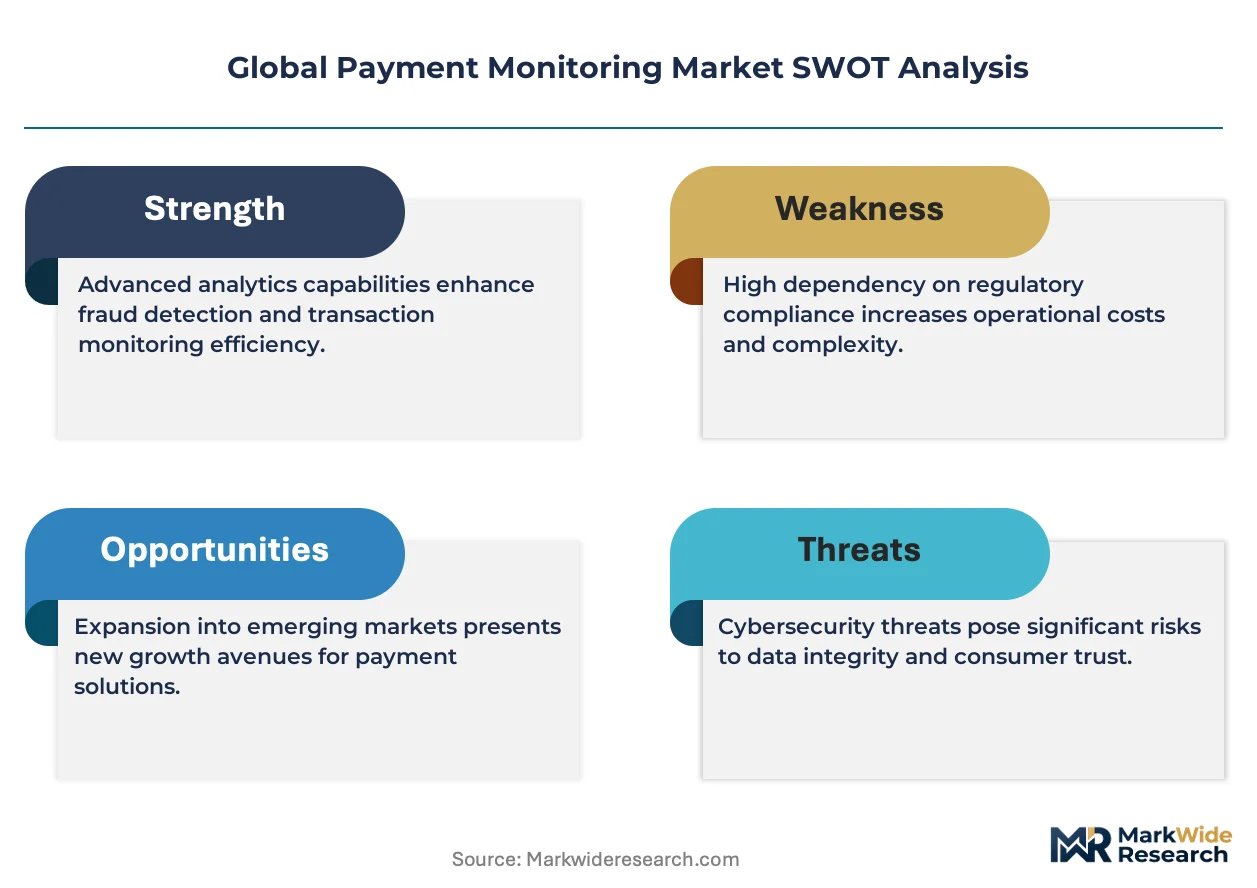
The acute shortage of machine learning engineers with financial crime domain expertise constrains vendor scaling velocity and concentrates premium talent compensation in Singapore and Bengaluru. This capability gap shapes competitive outcomes more than capital access.
For Market Incumbents: Shield installed base stickiness through deeper core banking integration investments that resist unbundling trends in the Netherlands and South Korea. Prioritize PCI DSS Level 1 certification maintenance as challenger banks issue standalone fraud detection RFPs. Vertical integration into behavioral analytics R&D offsets pure-play specialist encroachment. For New Entrants and Emerging Players: Service-layer gaps in white-label compliance modules for Brazil's embedded finance platforms and Nigeria's digital payment startups represent immediate addressable space. Target tier-two banks in Germany and Australia piloting graph neural network deployments for shell company detection. API-first integration positioning bypasses legacy mainframe entrenchment barriers. For Investors and Strategic Acquirers: PSD2 Strong Customer Authentication implementation reshapes the acquisition landscape toward behavioral analytics specialists with proven European open banking integration. Long-term viability hinges on cloud-native architecture migration capability. Target vendors with demonstrated AI sandbox participation in Singapore's regulatory framework. Watch for ISO 20022 messaging standard harmonization across FedNow and TARGET Instant Payment Settlement as consolidation trigger.| Strategic Initiative | Industry Significance |
|---|---|
| PCI DSS Level 1 Certification Investment | Unlocks tier-one bank procurement in Singapore's fintech corridor and India's UPI ecosystem. |
| Cloud-Native Architecture Migration | Captures elastic scaling contracts for 10 billion monthly payment volumes on real-time rails. |
| Behavioral Analytics R&D Expansion | Addresses PSD2 Strong Customer Authentication mandates across European open banking APIs. |
| Regulatory Sandbox Participation | Accelerates AI-driven anomaly detection validation through Singapore's MAS framework. |
| API-First Integration Development | Penetrates unbundled procurement patterns among Netherlands and South Korea challenger banks. |
Research Methodology
A spread of perspectives from fraud detection software architects, regulatory compliance officers at tier-one banks, cloud infrastructure procurement leads, and behavioral analytics data scientists converged on the working assumptions. Primary fieldwork combined with secondary validation drew from FFIEC examination guidance documents, RBI digital payment security framework circulars, PSD2 regulatory technical standards, and vendor SEC disclosures. Bottom-up transaction volume modeling and top-down market sizing triangulation anchored quantitative outputs.
Segmentation dimensions modeled encompass solution type, deployment architecture, end-user industry, and transaction channel complexity across the projection horizon. CAGRs derived from elasticity analysis of procurement cycles against regulatory mandate timelines. Forecast inputs incorporated UPI volume trajectories, PCI DSS certification pipeline data, and cloud migration velocity indicators from Singapore's fintech corridor.
Material uncertainties — regulatory fragmentation intensifying data residency requirements, legacy core system modernization delays, and machine learning talent scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance threshold embedding in vendor RFP specifications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Contactless Payment Terminals Market
Payments
Epayment System Market
Payments
Electronic Bill Presentment and Payment (EBPP) Market
Payments
LAMEA Payment Gateway Market
Payments
Netherlands Mobile Payments Market
Payments
In-Vehicle Payment System Market
Payments
Europe Payment Gateways Market
Payments
GCC Mobile Payment Market
Payments
Europe Fuel Cards Market
Payments
Bulgaria POS Terminals Market
Payments
POS Terminals Market
Payments
Third Party Payment Market
Payments
Global Payments Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Vietnam Mobile Payments Market
Payments
Asia-Pacific Accounts Payable Automation Market