
 Thailand Mobile Payments Market | 2026-2036
Thailand Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Mobile Payments Market Analytics
The Bank of Thailand's Payment Systems Roadmap is shifting merchant onboarding requirements toward real-time settlement protocols. True Money Co., Ltd. leverages its telco heritage to dominate rural agent networks. Kasikornbank PCL anchors corporate treasury digitization through API-linked cash management. ShopeePay (Thailand) Co., Ltd. competes on checkout integration with eCommerce marketplaces.
Thailand Mobile Payments encompass fund transfers executed through portable devices using encrypted tokenization, near-field communication, or quick-response matrix barcodes. These systems route transactions through centralized switching infrastructure maintained under central bank supervision, with primary purpose of reducing cash handling costs for micro-merchants and accelerating settlement velocity for supply chain participants. Digital wallet penetration leads consumer-facing adoption while QR code payments capture the fastest growth in street-level commerce. NFC technology occupies premium retail environments where transaction speed determines queue throughput. Mobile banking sustains the largest value pool through salary disbursement and utility settlement volumes.
The Bank of Thailand governs licensing under the Payment Systems Act while the Anti-Money Laundering Office enforces customer due diligence thresholds for wallet balances. The Electronic Transactions Act establishes enforceability standards for tokenized payment instruments, narrowing market access to certified providers. Stakeholders must monitor central bank digital currency pilot outcomes and their interoperability mandates for private wallet operators.
Market Dynamics
The Bank of Thailand's PromptPay infrastructure is compressing settlement timelines for micro-merchants while forcing wallet operators to adopt real-time clearing protocols. This central bank-mandated switching layer is reshaping platform economics across urban and rural agent networks.
Growth Catalysts
- PromptPay Mandate:The Bank of Thailand's real-time retail payment infrastructure eliminates interbank friction for peer-to-peer transfers. Wallet operators must integrate with this centralized switching layer.
- QR Code Standardization:Thailand's Common QR specifications unify merchant acceptance across competing wallets. Street vendors in Bangkok and Chiang Mai now display single codes readable by all major platforms.
- E-KYC Framework:Electronic Know-Your-Customer protocols from the Anti-Money Laundering Office accelerate digital onboarding. Rural populations in Isan regions gain wallet access without branch visits.
Market Restraints
- Agent Network Concentration:Rural cash-in/cash-out points cluster around telco-affiliated agent chains. Independent merchants face exclusion from high-traffic locations.
- Interoperability Costs:The Payment Systems Act imposes certification and compliance burdens on non-bank wallet providers. Smaller fintech entrants struggle with recurring audit expenses.
- Cash Persistence:Informal sector preference for physical currency limits transaction velocity in agricultural supply chains. Rice wholesalers and produce distributors maintain paper-based settlement.
Strategic Opportunities
- Cross-Border Remittance Rails:Thailand's bilateral agreements with Cambodia, Laos, Myanmar, and Vietnam enable wallet-to-wallet corridors. Migrant worker corridors from Myanmar represent underpenetrated corridors.
- Central Bank Digital Currency Pilots:The Bank of Thailand's retail CBDC experiments may mandate private wallet interoperability. Early integration positions operators for future settlement layer access.
- Embedded Finance Convergence:Transportation and delivery apps integrate payment acceptance into driver onboarding. Grab and Line Man drivers become de facto merchant acquirers.
Industry Challenges
- Legacy Core Banking Integration:Regional banks maintain decades-old mainframe architectures. API connectivity for real-time wallet funding requires expensive middleware development.
- Fraud Detection Talent Scarcity:Machine learning engineers with transaction monitoring expertise command premium compensation. Local universities produce insufficient quantitative risk specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Mobile Payments Market |
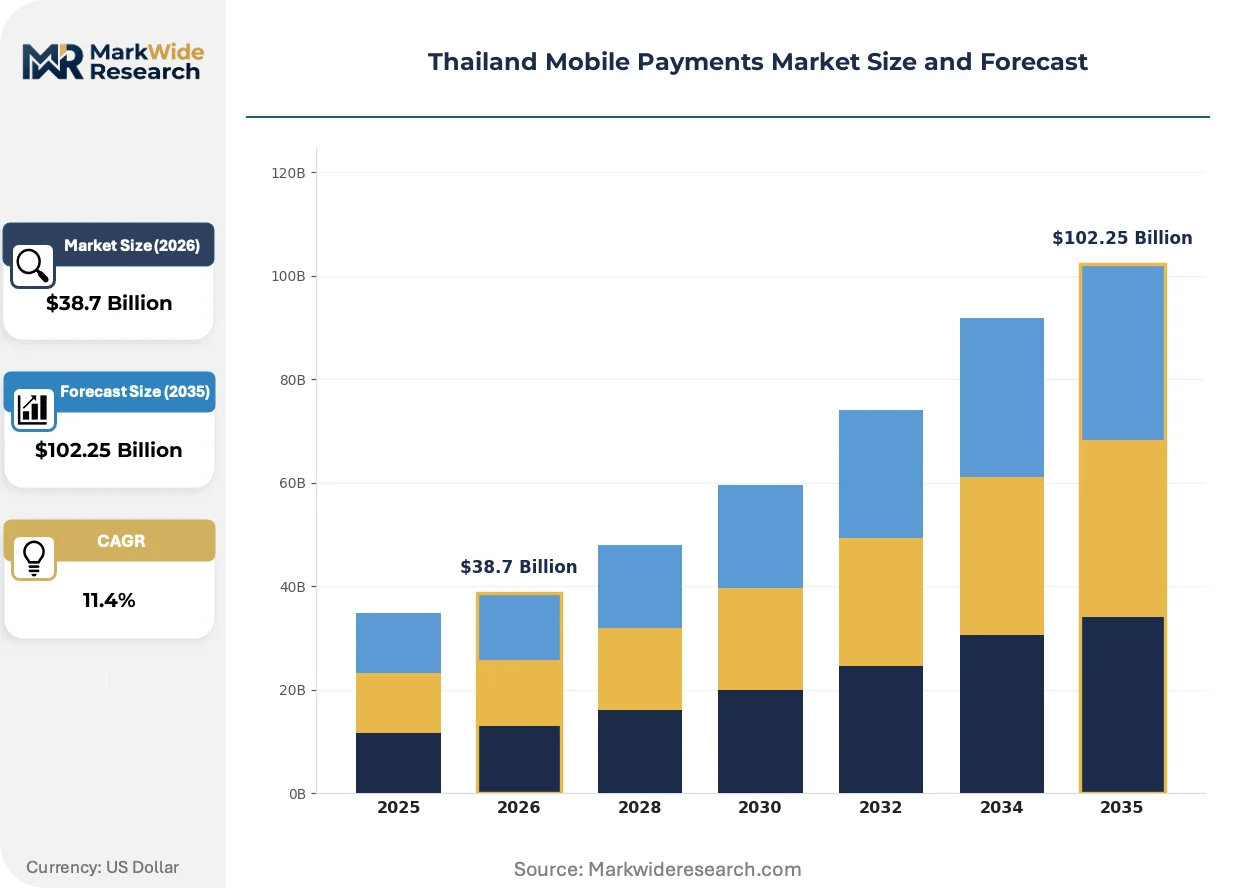
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Cards, Digital Wallets, Mobile Banking, QR Code Payments End User: Retail Consumers, Small Businesses, Enterprises, eCommerce Platforms Service Type: Peer-to-Peer Transfers, Bill Payments, In-Store Purchases, International Remittances Technology: NFC, SMS Payments, Blockchain, Mobile Apps |
| Companies Covered | Advanced Info Service Public Company Limited, ShopeePay (Thailand) Co., Ltd., True Money Co., Ltd., Mobiamo Inc, AirPay (Thailand) Company Limited, Rabbit LINE Pay Co., Ltd., Kasikornbank PCL, LINE Corporation, Grab Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Mobile Payments Market Evolving Landscape
Thailand's mobile payment infrastructure is bifurcating between instant retail QR transactions and embedded B2B settlement workflows. Platform operators are racing to capture merchant data streams beyond pure payment processing.
Biometric authentication is overtaking PIN-based verification for high-value wallet transactions. Facial recognition systems from Chinese hardware vendors are penetrating convenience store chains. 7-Eleven Thailand and FamilyMart are retrofitting point-of-sale terminals with 3D camera modules. The technology is compressing checkout times while raising compliance thresholds under Anti-Money Laundering Office guidelines.
The Electronic Transactions Act amendments are tightening enforceability standards for tokenized payment instruments. Smart contract-based escrow services for e-commerce marketplaces face new notarization requirements. ShopeePay and Lazada Wallet must maintain segregated reserve accounts for merchant settlement guarantees. The regulatory friction is accelerating consolidation among certified payment service providers.
Merchant acquisition is fragmenting away from dedicated sales forces toward platform-native onboarding. Social commerce sellers in Thailand's Facebook and TikTok live-streaming channels now activate payment acceptance through self-service dashboards. The shift is most visible in Bangkok's fashion and cosmetics verticals where influencer-led storefronts bypass traditional bank relationships entirely.
Thailand Mobile Payments Market Segmentation
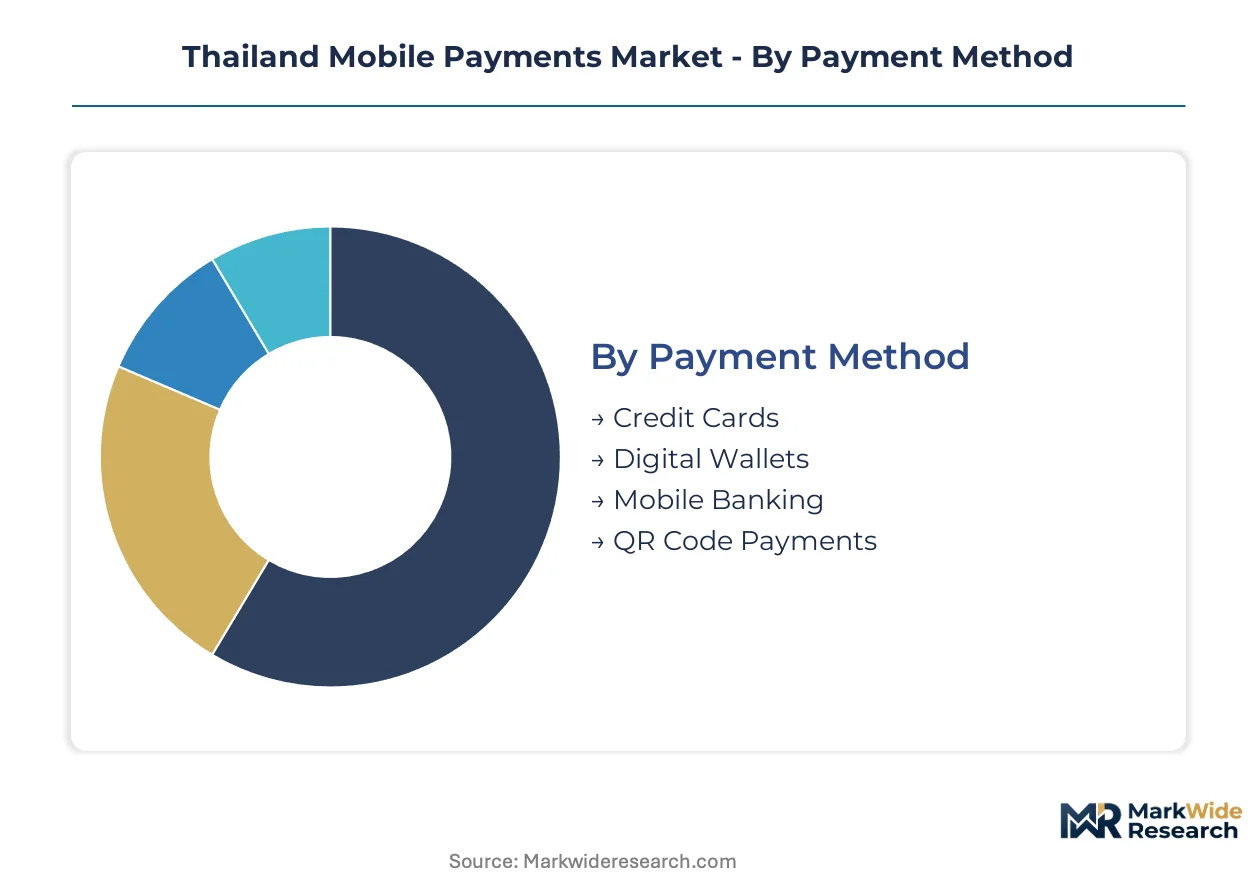
Segmentation in Thailand's mobile payments landscape reveals how infrastructure choices, user sophistication, and transaction purpose reshape platform requirements. Payment method selection determines settlement velocity and merchant onboarding complexity. Technology adoption splits between premium retail speed optimization and mass-market accessibility.
Payment Method:
Cost tier separates casual users from high-velocity commercial operators.
- Digital Wallets:These platforms store tokenized value in cloud-hosted accounts, enabling instant peer-to-peer transfers through PromptPay rails. Bangkok street vendors and Chiang Mai convenience stores drive wallet demand for sub-500 baht transactions. The Bank of Thailand's e-KYC standards compress onboarding friction for unbanked populations in Isan provinces.
- QR Code Payments:Static and dynamic quick-response matrices route transactions through centralized switching infrastructure. Single-code merchant displays now dominate Thailand's cash-heavy informal sector. Common QR standardization eliminates wallet-specific exclusivity, forcing platforms to compete on cashback rather than acceptance coverage.
- Mobile Banking:Bank-owned applications integrate fund transfers with credit facilities and investment products. Salary disbursement and utility settlement sustain the largest transaction value pools. Legacy core banking integration limits real-time functionality at regional institutions.
- Credit Cards:Card-not-present and tokenized mobile credentials target cross-border e-commerce and hospitality verticals. Higher interchange fees restrict penetration among price-sensitive micro-merchants. Airline and hotel bookings concentrate demand in Bangkok and Phuket tourism corridors.
Volume sits with Mobile Banking; growth tilts toward QR Code Payments.
End User:
Application maturity divides established digital adopters from first-time financial service users.
- Retail Consumers:Individual users execute peer-to-peer transfers, bill settlements, and retail purchases through smartphone applications. Bangkok and Chiang Mai urbanites lead adoption curves. The Anti-Money Laundering Office's tiered KYC thresholds segment wallet functionality by verification depth.
- Small Businesses:Micro-merchants and sole proprietors accept payments without traditional merchant accounts. Northeastern rice wholesalers and produce distributors in Isan lag behind urban adoption curves. Cash persistence in agricultural supply chains constrains transaction velocity.
- Enterprises:Corporate treasuries demand API-linked cash management and bulk disbursement capabilities. Kasikornbank and Siam Commercial Bank anchor this segment through integrated receivables platforms. Real-time liquidity visibility drives platform selection over consumer-facing features.
- eCommerce Platforms:Marketplace operators embed checkout functionality and escrow services for third-party sellers. ShopeePay and Lazada Wallet compete on seller onboarding speed and settlement guarantees. Smart contract-based escrow faces tightened notarization requirements under Electronic Transactions Act amendments.
Enterprise transactions generate highest per-user revenue; Retail Consumers deliver steepest expansion trajectory.
Service Type:
Customer type determines margin structure and regulatory exposure.
- In-Store Purchases:Physical retail transactions leverage NFC tap-to-pay or QR code scanning at point-of-sale. 7-Eleven Thailand and FamilyMart retrofit terminals with biometric authentication modules. Facial recognition compresses checkout times while raising compliance thresholds.
- Peer-to-Peer Transfers:Individual fund routing through PromptPay infrastructure eliminates interbank friction. The Bank of Thailand's centralized switching layer mandates real-time clearing protocols. Migrant worker corridors from Myanmar represent underpenetrated demand pockets.
- Bill Payments:Recurring utility, telecom, and insurance settlements sustain predictable transaction volumes. Mobile banking applications dominate through pre-registered beneficiary lists. Salary-linked autopay functionality reduces churn for incumbent platforms.
- International Remittances:Cross-border corridors to Cambodia, Laos, Myanmar, and Vietnam leverage bilateral central bank agreements. Wallet-to-wallet rails bypass traditional correspondent banking networks. Compliance with source-of-funds documentation constrains corridor expansion.
Bill Payments anchor transaction frequency; International Remittances offer highest fee-based margin expansion.
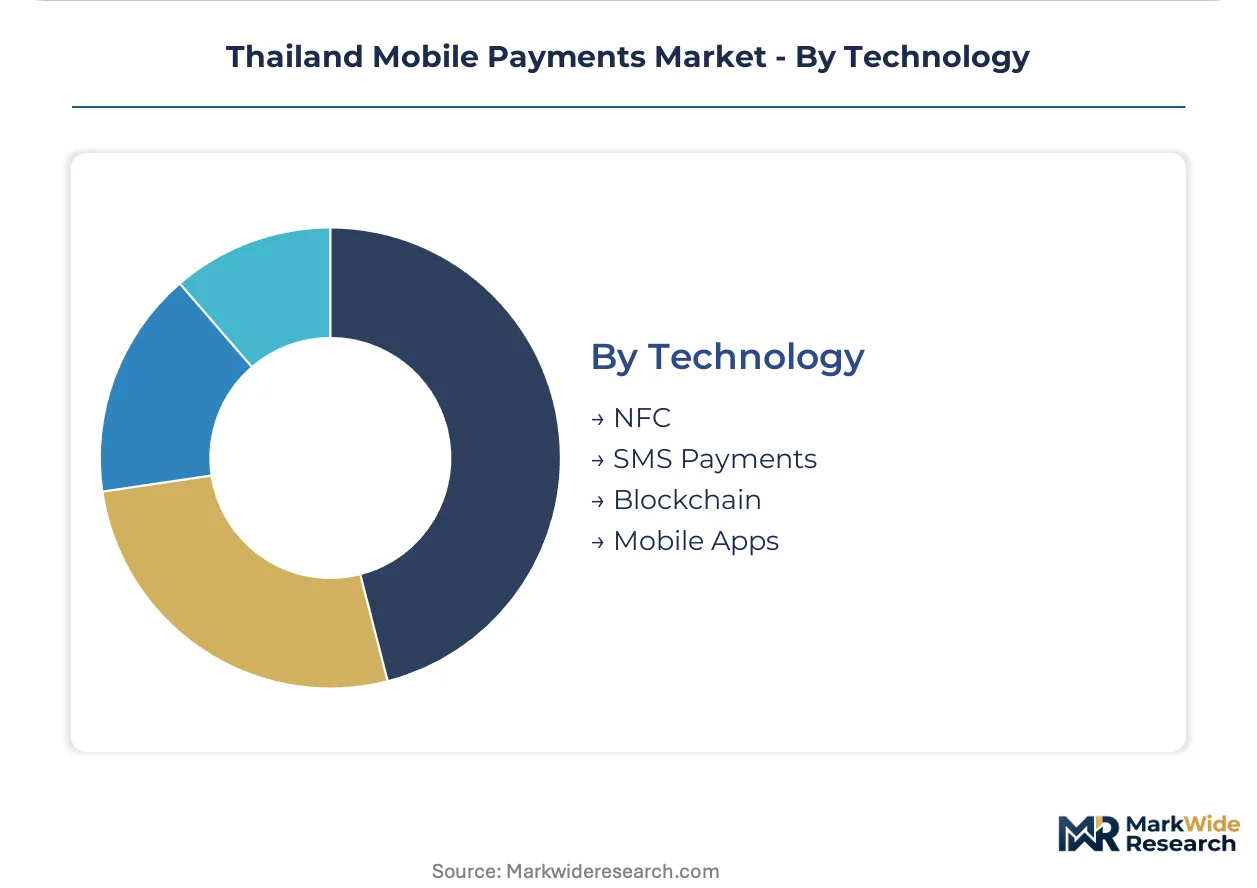
Technology:
Supply concentration clusters around platform-native development versus licensed foreign infrastructure.
- Mobile Apps:Native and web-based applications dominate Thailand's smartphone-saturated market. Self-service dashboards enable social commerce sellers to activate payment acceptance without bank relationships. TikTok and Facebook live-streaming channels drive merchant acquisition fragmentation.
- NFC:Near-field communication enables sub-second transaction completion for queue-sensitive environments. Premium retail locations in Bangkok's central business district prioritize speed over cost. Chinese hardware vendors supply 3D camera modules for biometric-enabled tap-to-pay.
- SMS Payments:Text-message-based routing serves feature phone users and network-constrained environments. Telco-affiliated agent networks in rural provinces maintain SMS fallback capability. Smartphone penetration erosion limits long-term relevance.
- Blockchain:Distributed ledger experiments support pilot central bank digital currency interoperability. The Bank of Thailand's retail CBDC trials may mandate private wallet integration. Smart contract escrow faces Electronic Transactions Act enforceability constraints.
Mobile Apps capture absolute transaction volume; NFC installations gain share fastest in premium retail retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's mobile payment infrastructure generates transaction volumes that exceed domestic production capacity for fintech development tools. Bangkok-based platforms consume technical talent and regulatory frameworks produced in Singapore and Hong Kong while deploying services across provincial markets.
Bangkok Metropolitan Region
Street vendors and convenience store chains in Bangkok drive QR code transaction density through PromptPay rails. The Bank of Thailand's e-KYC standards accelerate digital onboarding for unbanked migrants from neighboring provinces. Siam Square and Chatuchak market clusters host the highest concentration of multi-wallet merchant acceptance.
Chiang Mai and Northern Provinces
Tourism-dependent merchants in Chiang Mai prioritize checkout speed for international visitors through NFC-enabled terminals. The Tourism Authority of Thailand's digital payment promotion schemes subsidize terminal deployment for heritage site operators. Nimmanhaemin Road retail corridors retrofit point-of-sale systems with biometric authentication modules.
Isan Region
Rice wholesalers and produce distributors in Khon Kaen and Udon Thani maintain cash-heavy settlement patterns despite wallet penetration among urban consumers. The Bank of Thailand's financial inclusion mandates target agricultural supply chain digitization through agent network expansion. Telco-affiliated cash-in/cash-out points cluster around highway commercial zones.
Eastern Economic Corridor
Manufacturing payroll disbursement in Chonburi and Rayong industrial estates sustains mobile banking transaction volumes. The Eastern Economic Corridor Office coordinates with commercial banks on API-linked corporate treasury solutions. Amata and Hemaraj industrial zones anchor B2B payment digitization for supplier networks.
Southern Border Provinces
Cross-border trade corridors to Malaysia concentrate remittance demand in Hat Yai and Songkhla commercial districts. The Anti-Money Laundering Office enforces enhanced due diligence for wallet balances near international boundaries. Sadao customs zone merchants pilot dual-currency QR acceptance for Malaysian tourist traffic.
Thailand Mobile Payments Market Competitive Landscape
The competitive structure tilts toward telco-affiliated wallet operators with pre-existing agent network density. Platform economics favor players controlling rural cash-in/cash-out infrastructure over pure technology developers. Three archetypes dominate: telecommunications-derived wallets with physical agent presence, bank-owned applications with treasury integration capabilities, and marketplace-embedded checkout systems. Consolidation pressure concentrates on certification costs under the Payment Systems Act and interoperability mandates from PromptPay integration.
Among Thailand-based operators, True Money Co., Ltd. and Kasikornbank PCL occupy distinct positioning archetypes, while ShopeePay (Thailand) Co., Ltd. represents the marketplace-embedded model. True Money exemplifies the telco heritage advantage in rural agent network control. Kasikornbank anchors the corporate treasury digitization segment through API-linked infrastructure. ShopeePay occupies a position within e-commerce checkout integration, competing on seller onboarding velocity.
| Leading Market Players |
|---|
| Advanced Info Service Public Company Limited |
| ShopeePay (Thailand) Co., Ltd. |
| True Money Co., Ltd. |
| Mobiamo Inc |
| AirPay (Thailand) Company Limited |
| Rabbit LINE Pay Co., Ltd. |
| Kasikornbank PCL |
| LINE Corporation |
| Grab Holdings Limited |
| Others |
Value Network & Pricing Analysis
The Bank of Thailand's PromptPay interoperability mandate gates both qualified supply and premium-tier pricing access for wallet operators seeking real-time settlement certification. Compliance costs concentrate pricing power among incumbent platforms with pre-certified infrastructure, while non-compliant entrants face exclusion from high-velocity transaction rails.
Pricing Analysis
Transaction throughput volume anchors value-based pricing for merchant acquirers serving Bangkok's convenience store chains. Three-tier pricing structure across premium API-linked, standard dashboard, and economy agent-assisted tiers separates Kasikornbank's corporate treasury clients from True Money's rural cash-in networks. Pricing pressure stems from ShopeePay's zero-fee checkout subsidies for marketplace sellers. Small businesses in Isan provinces exhibit highest price sensitivity; enterprise treasuries anchored by Siam Commercial Bank show lowest.
Supply Chain Analysis
Machine learning engineering talent scarcity in Bangkok and Singapore concentrates platform development costs for fraud detection modules. Chinese hardware vendors supply NFC terminal components; Taiwanese semiconductor fabs produce secure element chips; Indian IT services firms deliver middleware integration. Cloud hosting dependencies on hyperscaler infrastructure create single-source vulnerability for wallet operators. Distribution runs through telco-affiliated agent networks in rural provinces and direct API salesforces for corporate segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's mobile payments landscape functions as a vertical-integration race where control over rural cash-in/cash-out infrastructure determines platform viability. Players are pursuing backward integration into agent network ownership to defend merchant acquisition economics.
For Market Incumbents: Acquire rural agent chain assets to lock out telco-affiliated competitors from Isan highway commercial zones. Consolidate position by embedding biometric authentication modules into 7-Eleven and FamilyMart terminal retrofits before regulatory mandates tighten. The Anti-Money Laundering Office's escalating KYC thresholds threaten unintegrated platforms with compliance cost spirals. For New Entrants and Emerging Players: Facial recognition-enabled tap-to-pay offers a technology-first wedge against PIN-saturated incumbent wallets. Target Myanmar migrant worker corridors in Samut Sakhon and Ranong provinces where remittance demand outstrips supply from licensed operators. Partner with transportation platforms like Line Man to embed payment acceptance into driver onboarding workflows. For Investors and Strategic Acquirers: The Bank of Thailand's retail CBDC pilot announcement is the leading indicator that interoperability mandates will reshape private wallet economics. Platforms with pre-integrated switching infrastructure represent the most defensible acquisition archetype over the coming decade. Monitor central bank digital currency technical specifications for forced API disclosure requirements that would erode proprietary settlement advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Agent Network Acquisition | True Money's rural cash-in point density locks out competitors from Isan agricultural supply chains. |
| Biometric Terminal Retrofit | 7-Eleven Thailand's facial recognition deployment compresses checkout times while raising AML compliance barriers. |
| CBDC Interoperability Integration | Early PromptPay switching layer compliance positions operators for future central bank settlement access. |
| Cross-Border Corridor Licensing | Bilateral agreements with Myanmar and Cambodia enable wallet-to-wallet remittance bypassing correspondent banking. |
| Embedded Finance Partnership | Grab driver onboarding converts transportation platforms into de facto merchant acquirer networks. |
Research Methodology
Independent corroboration across wallet platform executives, commercial bank treasury leads, and Anti-Money Laundering Office policy specialists underwrites the qualitative findings in this study. Primary interviews with PromptPay infrastructure engineers, rural agent network operators, and e-commerce marketplace payment heads combined with secondary validation from Bank of Thailand regulatory circulars, Payment Systems Act compliance filings, and Eastern Economic Corridor industrial zone development reports. Bottom-up transaction volume estimates triangulate against top-down GDP electronic payment penetration benchmarks.
Rate-of-change decomposition separates volume growth from value-per-transaction evolution across the projection horizon. The analytical framework models payment method, end user archetype, service type, and technology platform dimensions. CAGRs derive from segment-specific adoption curves calibrated against PromptPay infrastructure rollout timelines and e-KYC onboarding velocity. Forecast inputs include merchant terminal deployment rates in Bangkok convenience chains and migrant worker remittance corridor activation under bilateral central bank agreements.
Several conditions sit outside the modeled scope, including central bank digital currency issuance decisions, geopolitical disruption to Myanmar border trade, and abrupt Anti-Money Laundering Office KYC threshold revisions. Forecasts reflect assumptions about continued PromptPay interoperability enforcement and stable agent network economics in rural provinces. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Saudi Arabia Mobile Payments Market
Payments
United Kingdom Real Time Payments Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
Latin America Retail Cash Management Market
Payments
Electronic Cash Register Market
Payments
Subscription Billing Management Market
Payments
Japan Credit Cards Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Global Telecom Billing Market
Payments
Spain Payments Market
Payments
Face-Swiping Payment Market
Payments
Freight Audit and Payment Service Market
Payments
North America POS Terminal Market
Payments
Payment Analytics Software Market
Payments
Middle East Gift Card and Incentive Card Market