
 Germany Mobile Payments Market | 2026-2036
Germany Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Mobile Payments Market Foresight
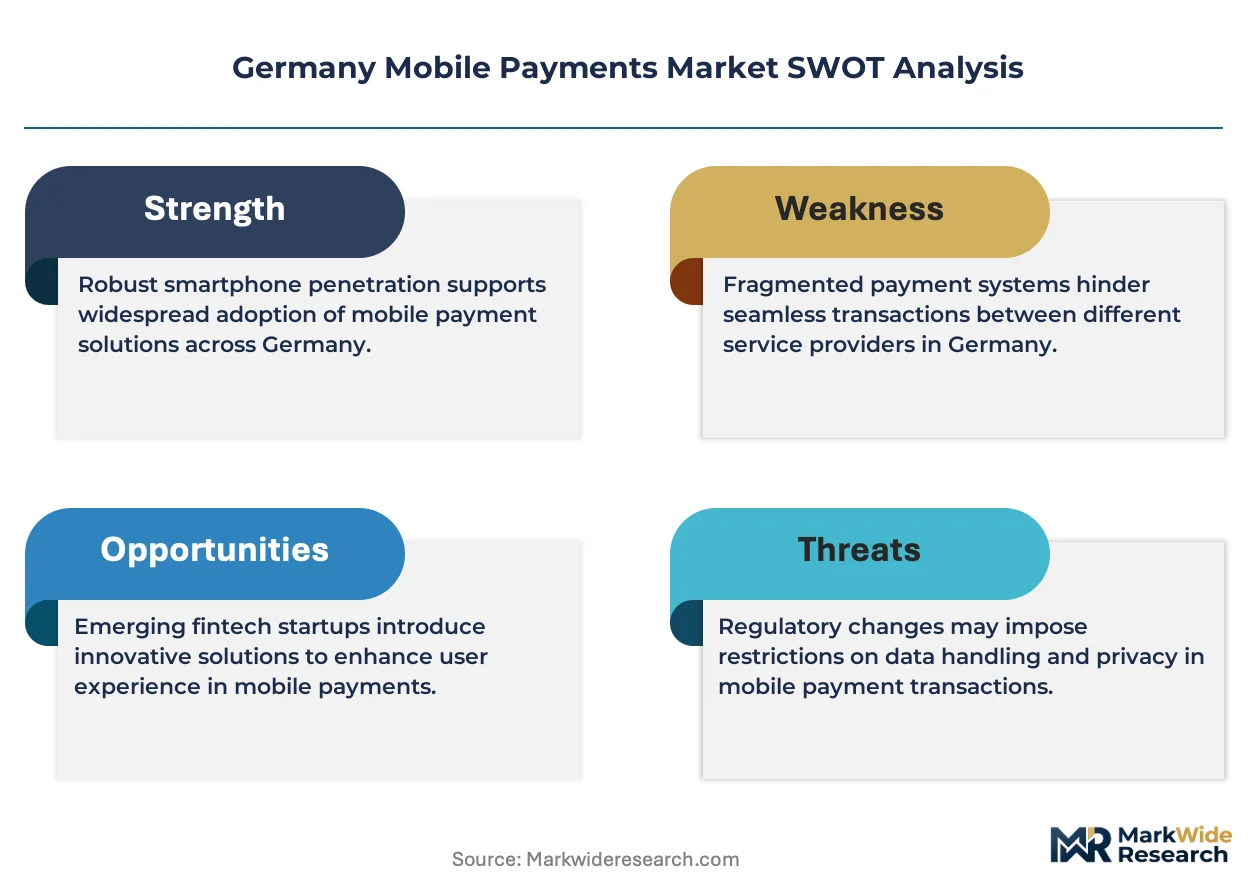
PSD2 is consolidating the cost-of-entry calculus for new payment service providers entering Germany. Apple Pay leverages its tokenization architecture to sustain premium positioning among iOS users in urban centers. PayPal Holdings, Inc. anchors merchant acceptance through its established German banking license and extensive retailer network. N26 GmbH competes via its native mobile-first banking infrastructure that integrates payments with core deposit accounts.
Germany mobile payments encompass digital fund transfers executed through smartphones, tablets, and wearable devices using near field communication chips, QR code scanners, or encrypted mobile banking protocols. These systems route transactions through tokenized credentials rather than raw card data, enabling real-time settlement between consumers, merchants, and financial intermediaries. Near field communication dominates point-of-sale touchpoints due to sub-second latency and established terminal infrastructure across German retail. Mobile wallets capture expanding share as consumers consolidate loyalty programs, transit passes, and payment instruments within single applications. Biometric authentication represents the fastest-growing technology segment as fingerprint and facial recognition replace PIN entry for high-value transactions.
BaFin supervises payment institution licensing and enforces anti-money laundering protocols that elevate compliance costs for non-bank entrants. The Bundesbank operates the real-time payment rail that underpins instant settlement capabilities now mandatory for major German banks. KBA guidelines for in-vehicle payment systems are extending regulatory scope into automotive-integrated commerce. Stakeholders must monitor how the European Commission's Digital Euro initiative reshapes the competitive boundary between private wallets and central bank liabilities.
Market Dynamics
The Bundesbank's instant payment infrastructure mandate is compressing settlement timelines across German retail banking, forcing incumbents and fintech entrants to rebuild core processing architectures around real-time rails rather than batch-based legacy systems.
Growth Catalysts
- PSD2 Open Banking Framework:Mandatory access to payment account data and initiation services is dismantling incumbent data monopolies, enabling third-party providers to embed payments into non-financial applications.
- Near Field Communication Terminal Rollout:German retailers are replacing magnetic stripe readers with contactless-capable POS hardware, expanding the physical addressable market for smartphone-based transactions.
- Berlin Fintech Cluster Density:Concentrated venture capital and engineering talent in the capital is accelerating wallet innovation and merchant acquisition velocity relative to dispersed European markets.
Market Restraints
- BaFin Licensing Burden:Payment institution authorization requires minimum capital reserves and operational continuity plans that strain early-stage providers with limited balance sheet depth.
- Cash Preference Inertia:Germany's historical attachment to physical currency, particularly among older demographics and rural merchant networks, creates friction against digital wallet conversion.
- Interoperability Fragmentation:Proprietary tokenization schemes from device manufacturers prevent seamless cross-wallet transactions, fragmenting user experience and merchant acceptance decisions.
Strategic Opportunities
- In-Vehicle Commerce Integration:KBA guidelines for automotive-integrated payment systems are opening toll, fuel, and parking transactions to wallet providers as connected car penetration expands.
- Biometric Authentication Convergence:Fingerprint and facial recognition technologies are merging with PSD2 strong customer authentication requirements, enabling high-value transactions without hardware tokens.
- Hamburg Merchant Banking Corridor:The city's concentration of trade finance and shipping logistics firms presents specialized B2B payment automation opportunities absent from consumer-centric markets.
Industry Challenges
- Legacy Core Banking Integration:Established German banks operate on decades-old mainframe architectures that resist real-time API connectivity, forcing expensive middleware development for instant payment compliance.
- Anti-Money Laundering Compliance Talent Scarcity:BaFin's transaction monitoring requirements demand specialized compliance engineering expertise that commands premium compensation in a constrained labor market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Mobile Payments Market |
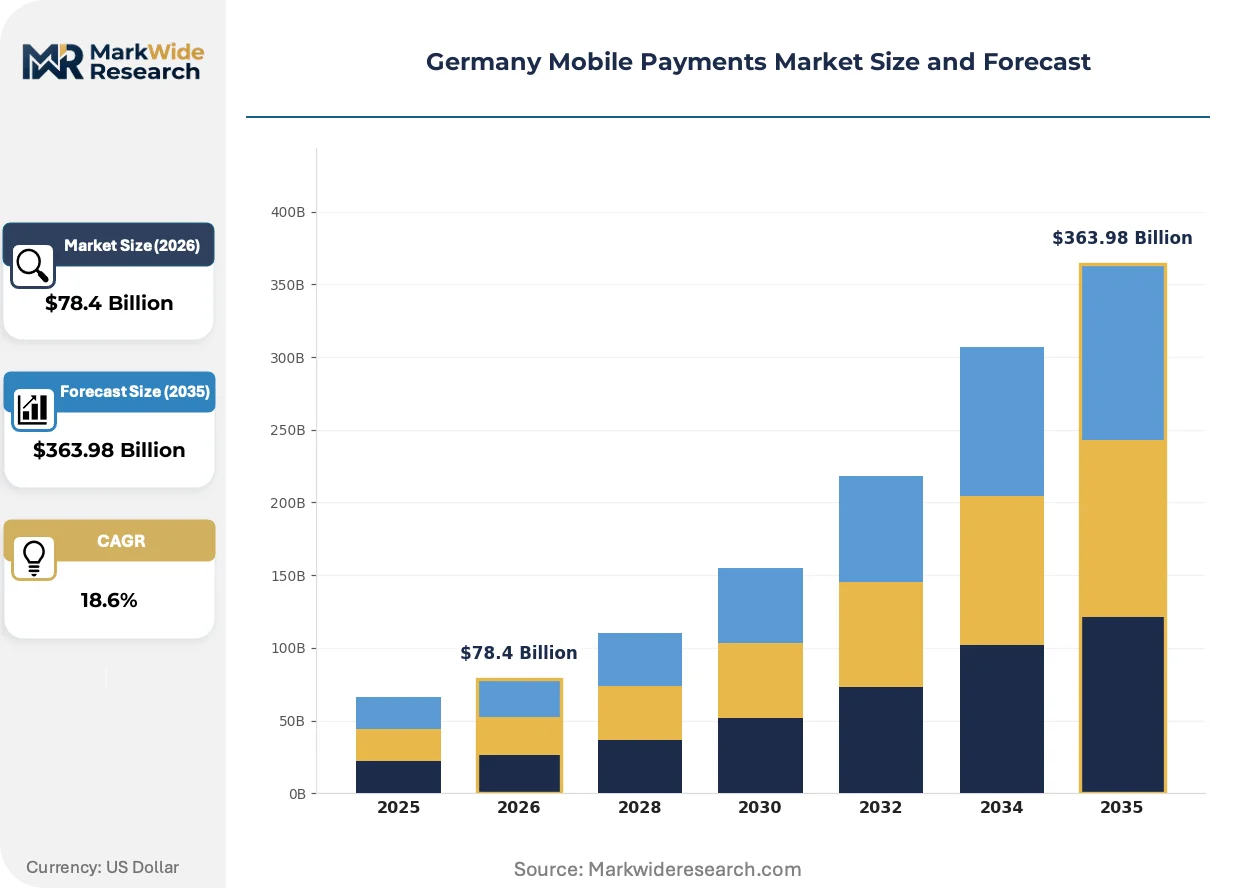
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $363.98 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Near Field Communication, QR Code, SMS Payments, Direct Carrier Billing, Mobile Wallets, Mobile Banking Apps End User: Retailers, E-commerce Platforms, Public Transport Operators, Hospitality Providers, Event Organizers, Educational Institutions Technology: Tokenization, Biometric Authentication, Cloud-Based Solutions, Blockchain, Two-Factor Authentication, Point of Sale Integration Distribution Channel: App Stores, Financial Institutions, Telecom Operators, Third-Party Providers, Retail Outlets, Online Marketplaces |
| Companies Covered | Google Pay, Apple Pay, PayPal Holdings, Inc., Visa Inc., Mastercard Inc., Samsung Electronics Co. Ltd, N26 GmbH, Revolut Ltd, Klarna Bank AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Mobile Payments Market Shifts & Advancements
Tokenized credential architectures are displacing raw card data transmission across German payment rails, compressing fraud exposure while enabling device-agnostic wallet proliferation.
Host Card Emulation technology is consolidating smartphone-based payment authority by eliminating the need for carrier-controlled secure elements. German Android device manufacturers are embedding HCE protocols into native wallet applications, accelerating merchant adoption beyond Apple Pay's iOS confines. This architecture is consolidating processing cost structures by routing transactions through cloud-based token vaults rather than hardware-dependent security modules.
The European Commission's Digital Euro initiative is mandating central bank liability accessibility through private wallet interfaces, reshaping competitive boundaries between commercial deposit products and sovereign currency instruments. German banks must now architect technical bridges to Bundesbank settlement rails while defending their deposit base against direct CBDC holding. Retail payment providers in Berlin and Hamburg are piloting programmable payment features that comply with draft ECB technical specifications.
Merchant acquisition patterns are fragmenting as independent software vendors embed payment acceptance into vertical-specific business management tools. German hospitality and healthcare sectors are adopting all-in-one platforms that combine scheduling, inventory, and settlement, displacing standalone POS relationships. This consolidation is most visible in Bavaria's mid-sized city networks where merchant banking relationships previously dominated local commerce.
Germany Mobile Payments Market Segmentation
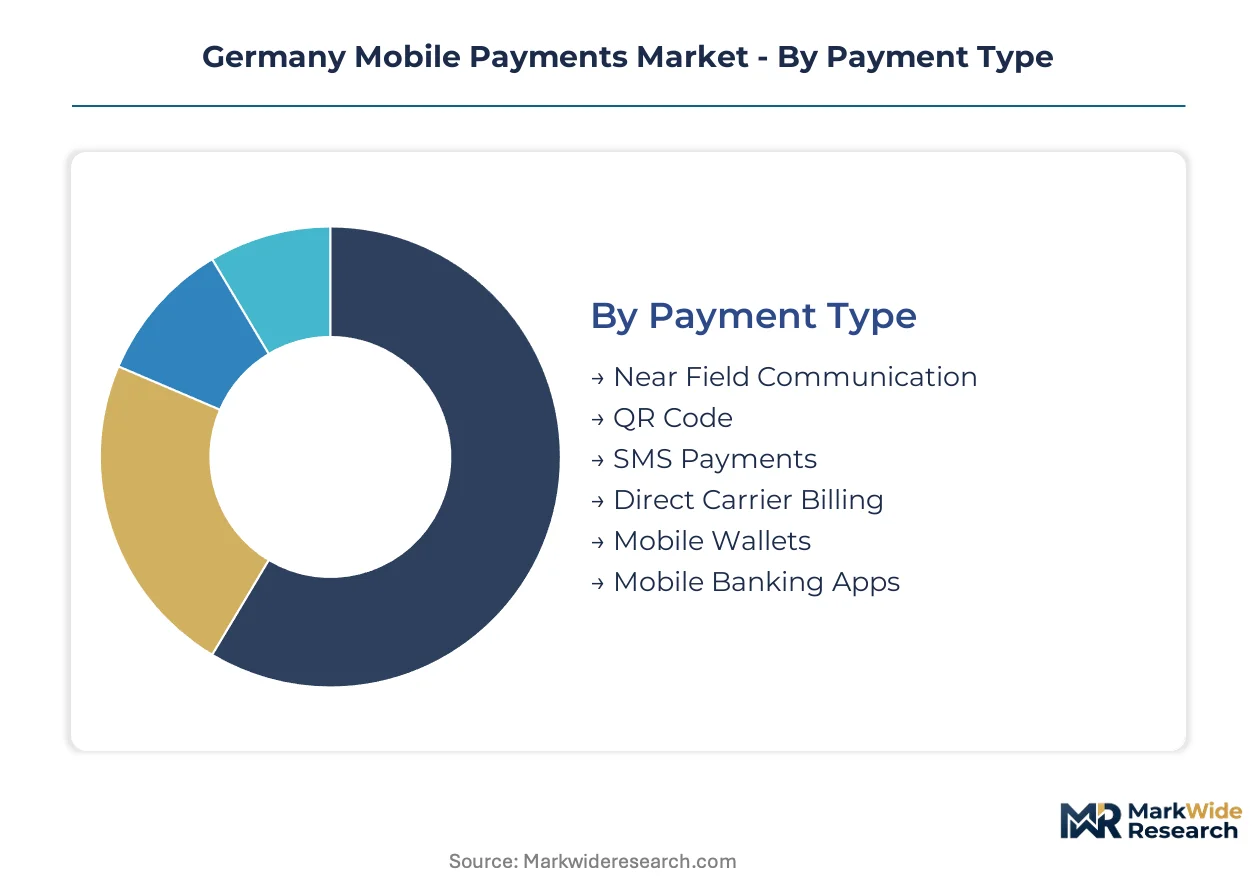
German mobile payment architectures fragment across technical protocols, institutional end-users, and distribution pathways. Each segmentation axis reveals distinct margin structures and deployment maturity curves that shape provider strategy.
Payment Type:
Volume concentration favors proximity-based protocols, while premium positioning clusters around integrated wallet ecosystems.
- Near Field Communication:Sub-second latency protocols dominate German retail POS infrastructure. Demand concentrates in Hamburg's merchant banking corridor where contactless terminal density supports high-frequency small-value transactions.
- Mobile Wallets:Consolidated loyalty, transit, and payment instruments within single applications command premium user acquisition costs. Berlin's fintech cluster drives wallet innovation velocity through concentrated venture deployment.
- QR Code:Optical scanning protocols enable low-cost merchant acceptance without hardware investment.
- SMS Payments:Text-based transaction initiation serves legacy device penetration and accessibility requirements.
- Direct Carrier Billing:Telecom-integrated settlement routes purchases through mobile subscription accounts.
- Mobile Banking Apps:Institution-branded payment interfaces leverage existing deposit relationships for transaction origination.
Mature deployment sits with Near Field Communication. Newer deployment is concentrated in Mobile Wallets.
End User:
Application context determines authentication complexity and settlement timeline requirements across German commercial sectors.
- Retailers:Physical merchants demand sub-second authorization with integrated loyalty program recognition. Bavaria's mid-sized city networks exhibit accelerating standalone POS displacement by all-in-one management platforms.
- E-commerce Platforms:Remote checkout requires strong customer authentication compliance with minimized friction. Hamburg's logistics concentration drives B2B payment automation integration with inventory systems.
- Public Transport Operators:High-volume, low-value corridors necessitate offline-capable credential validation.
- Hospitality Providers:Tip-adjustment and split-bill functionality shape terminal selection criteria.
- Event Organizers:Temporary infrastructure demands rapid merchant onboarding with minimal hardware deployment.
- Educational Institutions:Campus-wide credential systems integrate meal plans, facility access, and incidental purchases.
Established integration characterizes Retailers. Experimental deployment clusters with Event Organizers.
Technology:
Security architecture investments separate compliance-minimum providers from premium-positioned infrastructure builders.
- Biometric Authentication:Fingerprint and facial recognition protocols satisfy PSD2 strong customer authentication without hardware tokens. German automotive-integrated commerce under KBA guidelines is accelerating in-vehicle biometric deployment for fuel and toll transactions.
- Tokenization:Cloud-based credential vaulting displaces raw card data transmission across payment rails. BaFin's transaction monitoring requirements elevate token vault security investment for payment institution licensing.
- Cloud-Based Solutions:Distributed processing architectures enable real-time scaling without on-premise infrastructure.
- Blockchain:Distributed ledger settlement remains experimental for cross-border remittance corridors.
- Two-Factor Authentication:Multi-credential verification satisfies regulatory minimums for high-value transfers.
- Point of Sale Integration:Terminal-software coupling determines merchant acquisition stickiness.
Regulatory-mandated deployment centers on Tokenization. Steepest expansion trajectory belongs to Biometric Authentication.
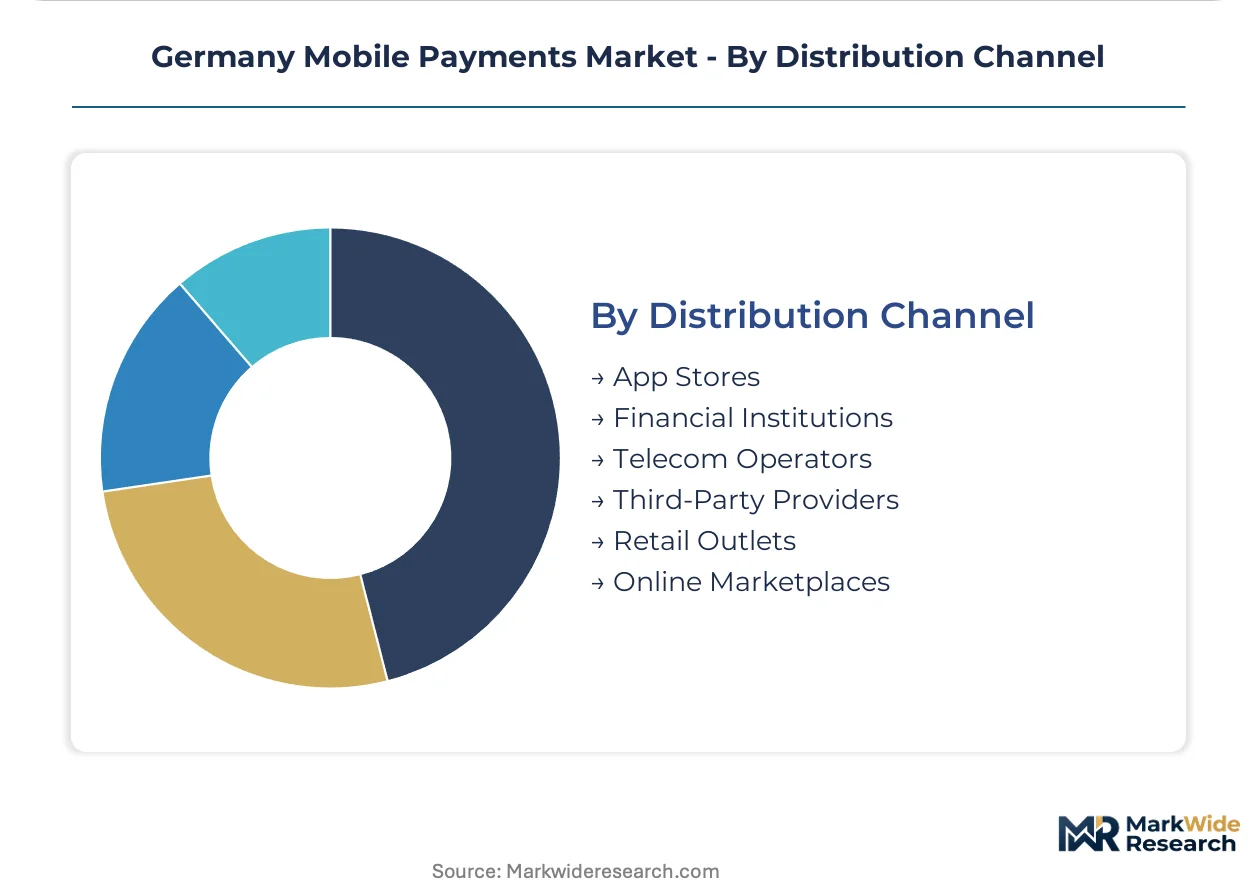
Distribution Channel:
Channel economics vary dramatically between platform-controlled discovery and institution-captive distribution.
- Financial Institutions:Banking license holders leverage existing customer relationships and trust frameworks for wallet adoption. The Bundesbank's instant payment infrastructure mandate forces core system reconstruction that favors established deposit-taking channels.
- App Stores:Platform gatekeepers extract significant revenue share but provide discovery scale for consumer-facing applications. Berlin's density of venture-backed fintechs depends on iOS and Android storefront optimization for user acquisition.
- Telecom Operators:Carrier billing relationships exploit existing subscription management infrastructure.
- Third-Party Providers:Independent PSPs compete on merchant service pricing and vertical specialization.
- Retail Outlets:Physical distribution of prepaid instruments and credential provisioning serves underbanked segments.
- Online Marketplaces:Embedded checkout experiences reduce friction for marketplace-native commerce.
Dominant volume flows through Financial Institutions. Emerging channel investment targets App Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin's fintech tax incentives and Hamburg's merchant banking corridor concentrate Germany's mobile payment infrastructure development. The Bundesbank's instant payment mandate reshapes settlement architecture nationwide. Regional specialization clusters emerge around distinct regulatory and commercial ecosystems.
Bavaria
Automotive-integrated commerce under KBA guidelines drives in-vehicle payment pilots for fuel and toll transactions. Bavaria's manufacturing base supplies connected car platforms that embed wallet functionality. Munich anchors this ecosystem with concentrated automotive R&D and Tier-1 supplier headquarters.
North Rhine-Westphalia
Industrial B2B payment automation concentrates in Düsseldorf's corporate banking cluster. The region's chemical and machinery exporters demand real-time cross-border settlement rails. Cologne's insurance technology sector experiments with embedded premium collection via mobile wallets.
Baden-Württemberg
Precision engineering and automotive supply chains generate specialized procurement payment requirements. Stuttgart's manufacturing Mittelstand adopts mobile-first invoice settlement to compress working capital cycles. The state's technical universities feed payment engineering talent into local fintech incubators.
Berlin-Brandenburg
Venture capital density supports wallet innovation velocity unmatched elsewhere in Germany. PSD2 compliance engineering concentrates in the capital's regulatory technology cluster. Potsdam's media technology sector pilots content micropayment systems integrated with streaming platforms.
Hamburg
Trade finance and shipping logistics create specialized B2B payment automation demand. The port city's merchant banking heritage supports complex multi-currency settlement infrastructure. Fintechs cluster around the Speicherstadt district, leveraging Hamburg's historic commercial banking relationships.
Germany Mobile Payments Market Competitive Landscape
US-based technology platforms anchor one competitive tier; European neobanks and payment networks hold specialized positions. Market structure tilts toward platform consolidation where device-integrated wallets capture urban consumer segments. Three archetypes dominate: hardware-coupled wallets, banking-license holders, and merchant-acquisition specialists. Incumbents defend through PSD2 compliance integration; challengers attack via vertical-specific checkout experiences.
Within the banking-license tier, N26 GmbH exemplifies mobile-first deposit integration with payment origination. PayPal Holdings, Inc. occupies the merchant network anchoring position through its established German banking license. Apple Pay represents the hardware-coupled archetype, leveraging tokenization architecture for premium urban positioning.
| Leading Market Players |
|---|
| Google Pay |
| Apple Pay |
| PayPal Holdings, Inc. |
| Visa Inc. |
| Mastercard Inc. |
| Samsung Electronics Co. Ltd |
| N26 GmbH |
| Revolut Ltd |
| Klarna Bank AB |
| Others |
Supply & Pricing Matrix
Compliance engineering talent scarcity in Berlin's fintech cluster compresses wage differentials between premium tokenization architects and standard API developers, widening pricing-tier spreads across PSD2-certified and uncertified service tiers.
Pricing Analysis
Short lead-time deployment of biometric authentication modules commands premium positioning against spot-market software development kits. Three-tier pricing structure across premium, standard, and economy levels segments by PSD2 strong customer authentication compliance depth and token vault security certification. Cost compression in the economy tier intensifies because offshore development houses replicate basic HCE protocols without BaFin licensing overhead. E-commerce platforms exhibit highest price sensitivity due to thin merchant margins, while automotive OEMs under KBA guidelines absorb premium pricing for in-vehicle payment integration.
Supply Chain Analysis
Workforce availability for tokenization engineering concentrates in Germany, Estonia, and Poland, where PSD2 implementation experience has accumulated since the directive's enforcement. Semiconductor fabrication for NFC controllers draws from Taiwan, South Korea, and Germany, while cloud infrastructure rests on hyperscaler data centers in Ireland, the Netherlands, and Germany. Single-source vulnerability sits with Taiwan's concentrated secure element manufacturing. Distribution runs through financial institution channels with embedded banking relationships, supplemented by app store discovery for consumer-facing wallet applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. BaFin's payment institution licensing requirements create a barrier-to-entry moat that rewards early movers who absorbed capital reserve and operational continuity burdens.
For Market Incumbents: To counter Host Card Emulation commoditization by Android device manufacturers, deepen proprietary token vault security investments and secure exclusive merchant acquisition partnerships in Hamburg's trade finance corridor. Prioritize biometric authentication convergence with automotive-integrated commerce under KBA guidelines to capture toll and fuel transaction flows before platform competitors establish terminal relationships.
For New Entrants and Emerging Players: White-label wallet infrastructure for Bavaria's mid-sized city merchant networks offers the most penetrable entry point, as all-in-one hospitality and healthcare platforms displace standalone POS relationships. Target event organizers with rapid merchant onboarding capabilities that require minimal hardware deployment. A vertical-specific go-to-market angle through shipping logistics payment automation in Hamburg's Speicherstadt fintech cluster bypasses saturated consumer wallet competition.
For Investors and Strategic Acquirers: The window for entry favors payment institutions with existing BaFin licenses and proven Bundesbank instant payment rail integration. Long-term viability hinges on defending deposit base relationships against European Commission Digital Euro disintermediation. Watch the ECB's programmable payment feature specifications as the inflection indicator for CBDC-enabled wallet architecture investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Integration | PSD2 strong customer authentication compliance without hardware tokens satisfies regulatory minimums for high-value transactions. |
| Automotive Commerce Partnership | KBA guidelines for in-vehicle payment systems embed wallet functionality into connected car platforms from Munich's Tier-1 suppliers. |
| Merchant Acquisition Platform Consolidation | All-in-one hospitality and healthcare management tools in Bavaria displace standalone POS terminal relationships. |
| Instant Payment Rail Compliance | Bundesbank infrastructure mandate forces core system reconstruction that favors established deposit-taking channels. |
| Token Vault Security Certification | BaFin transaction monitoring requirements elevate investment barriers for payment institution licensing applicants. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Germany mobile payments analysis. Primary interviews with payment institution compliance officers, fintech CTOs, merchant acquisition heads, and Bundesbank settlement infrastructure managers combined with BaFin licensing databases, ECB payment statistics, and venture capital deployment records. Bottom-up wallet provider revenue aggregation and top-down German retail transaction volume estimates underwent triangulation validation.
Data-stream reconciliation across payment type, end user, technology, and distribution channel segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from installed NFC terminal growth curves, PSD2 API call volume trajectories, and biometric authentication adoption rates across automotive and retail applications. Bundesbank instant payment mandate compliance timelines and European Commission Digital Euro pilot program specifications fed industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory acceleration of CBDC deployment or prolonged BaFin licensing backlogs. Assumptions reflect current PSD2 enforcement intensity and merchant terminal replacement cycles. ECB technical specification releases, KBA automotive guideline amendments, and venture capital availability for Berlin fintech scaling warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
United States Electronic Toll Collection Market
Payments
Latin America Subscription and Billing Management Market
Payments
Africa Mobile Money Market
Payments
Accelerator Card Market
Payments
GCC Mobile Payment Market
Payments
China POS Terminals Market
Payments
Latin America Retail Cash Management Market
Payments
Spain Payment Gateway Market
Payments
Direct Carrier Billing Market
Payments
Sweden Mobile Payments Market
Payments
Netherlands Mobile Payments Market
Payments
United States Payments Market
Payments
Voice-Based Payments Market
Payments
South Korea Digital Payments Market
Payments
Canada Real Time Payments Market
Payments
Canada POS Terminal Market