
 Acrylic Pad Market | 2026-2036
Acrylic Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Pad Market Outlook
Subscription-based replenishment programs for art supply retailers is rebalancing how acrylic pads move through distribution channels. CANSON leverages its European mill network to sustain premium-grade output for professional artists. Strathmore anchors North American supply through specialized paper finishing capabilities. Dick Blick Art Materials competes by controlling direct-to-consumer channels with curated private-label assortments.
An acrylic pad consists of heavyweight paper sheets, typically gsm-rated between 190 and 400, surface-treated to resist warping under acrylic paint loads and bound for portability in studio or field settings. Non-adhesive pads command structural priority in art and craft applications where reworkability matters, while self-adhesive variants lead in office supplies and packaging segments where quick-mount functionality drives replacement cycles. Industrial pads occupy narrower volume pools but carry higher per-unit margins due to custom sizing and substrate specifications.
EPA guidelines on volatile organic compound emissions shape adhesive formulation choices for manufacturers serving US distribution channels, while REACH registration requirements in Europe restrict specific acrylic monomer content in self-adhesive product lines. ISO 9706 permanence standards for paper longevity increasingly filter procurement specifications at educational institutions and museum-adjacent retailers. Stakeholders must weigh regulatory compliance investments against segment-specific margin profiles when allocating R&D budgets across adhesive and non-adhesive product architectures.
Market Dynamics
REACH compliance in Europe is compressing formulation flexibility for self-adhesive acrylic pads while simultaneously elevating premium non-adhesive alternatives in educational procurement cycles.
Growth Catalysts
- Educational procurement mandates:ISO 9706 permanence standards are filtering into institutional purchasing specifications across museum-adjacent retailers and university art departments, favoring heavyweight gsm-rated substrates.
- REACH registration requirements:ECHA restrictions on specific acrylic monomer content are accelerating R&D investment in bio-based adhesive alternatives for European distribution channels.
- Central European paper clusters:Germany's specialized mill networks sustain captive supply advantages for premium-grade output serving professional artist segments.
Market Restraints
- Cellulose pulp volatility:Input cost swings for cotton rag and alpha-cellulose feedstocks compress margin predictability for heavyweight paper substrates.
- Adhesive formulation complexity:EPA volatile organic compound emission guidelines constrain solvent-based acrylic options for US-bound production lines.
- Synthetic canvas substitution:Polyester and linen painting surfaces displace paper pads in high-value professional studio applications.
Strategic Opportunities
- Subscription replenishment channels:Direct-to-consumer art supply platforms are capturing repeat purchase cycles previously held by brick-and-mortar retailers.
- Dual carbon alignment:China's MEE emission trading schemes create premium positioning for water-based adhesive formulations in export-oriented manufacturing.
- Field portability convergence:Travel-format pad specifications merging watercolor and acrylic compatibility open hybrid application white space.
Industry Challenges
- Surface chemistry specialization:Sizing formulation expertise for acrylic paint load resistance remains concentrated among legacy European paper finishers.
- Batch consistency at scale:Maintaining uniform surface treatment across 400 gsm+ sheets challenges automated coating line investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Pad Market |
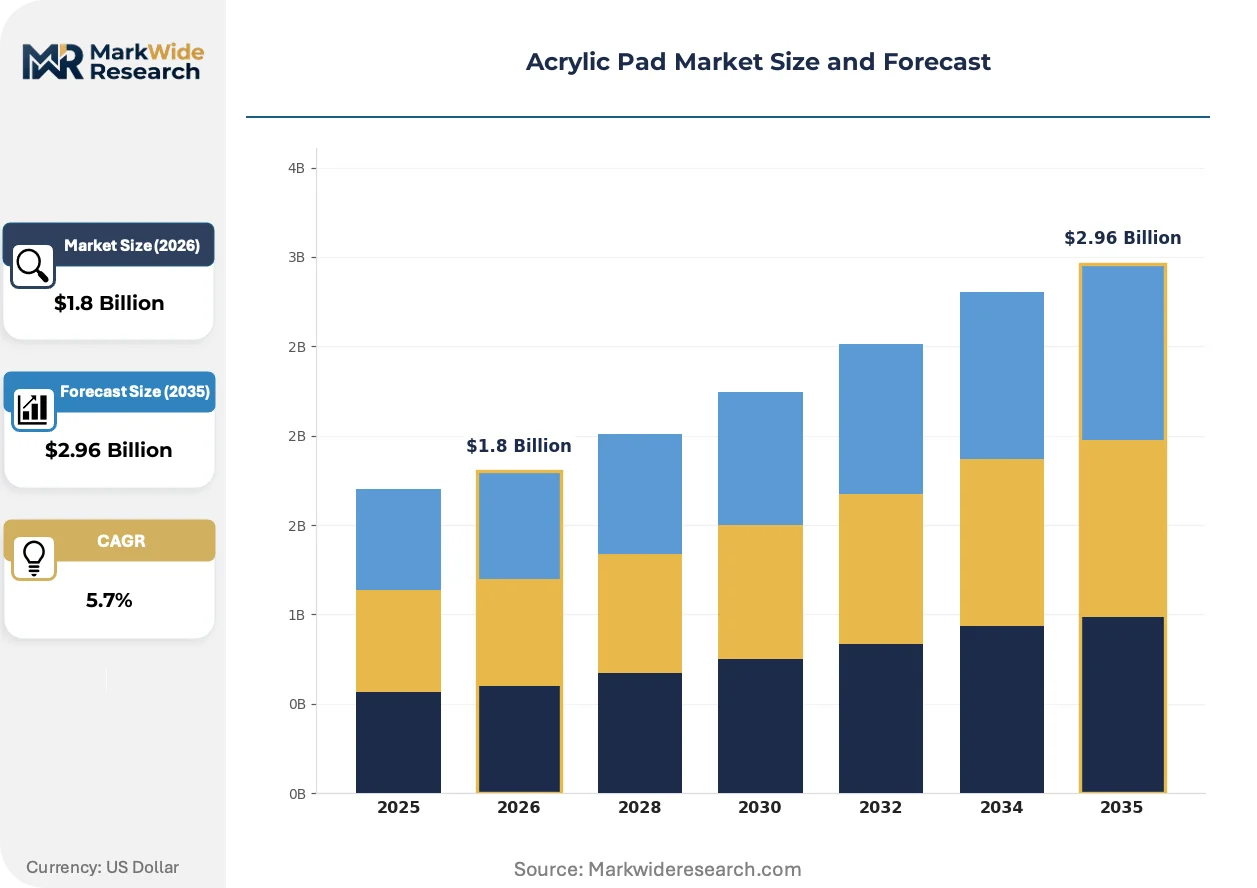
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive Pads, Non-Adhesive Pads, Decorative Pads, Industrial Pads Application: Office Supplies, Art and Craft, Medical Use, Packaging End User: Corporate Offices, Educational Institutions, Healthcare Facilities, Retail Stores Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | CANSON, Arteza, Strathmore, US Art Supply, Dick Blick Art Materials, JACKSON'S ART SUPPLIES, Creative Hands Art Materials, Arkema Group, Kuraray Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Pad Market Strategic Shifts
Surface treatment chemistry and distribution channel architecture are undergoing parallel transformation as regulatory pressure and buyer behavior shift in tandem.
Water-based acrylic sizing technology is consolidating position as the dominant surface treatment for heavyweight art pads. Professional artists and art educators are adopting these formulations at accelerating rates due to reduced yellowing risk. This consolidation is compressing demand for traditional animal-glue sizing in premium pad segments.
REACH authorization procedures for acrylic monomers are tightening chemical content thresholds for self-adhesive pad lines bound for European distribution. Manufacturers serving German and Benelux channels are reformulating toward UV-cured acrylic alternatives. Art supply importers are absorbing extended certification timelines into product launch schedules.
Curated private-label assortments are displacing open-stock purchasing in North American art supply retail. Dick Blick Art Materials and regional distributors are building captive pad specifications that bypass traditional brand intermediaries. This channel compression is most visible in online art supply platforms serving hobbyist and student segments.
Acrylic Pad Market Segmentation
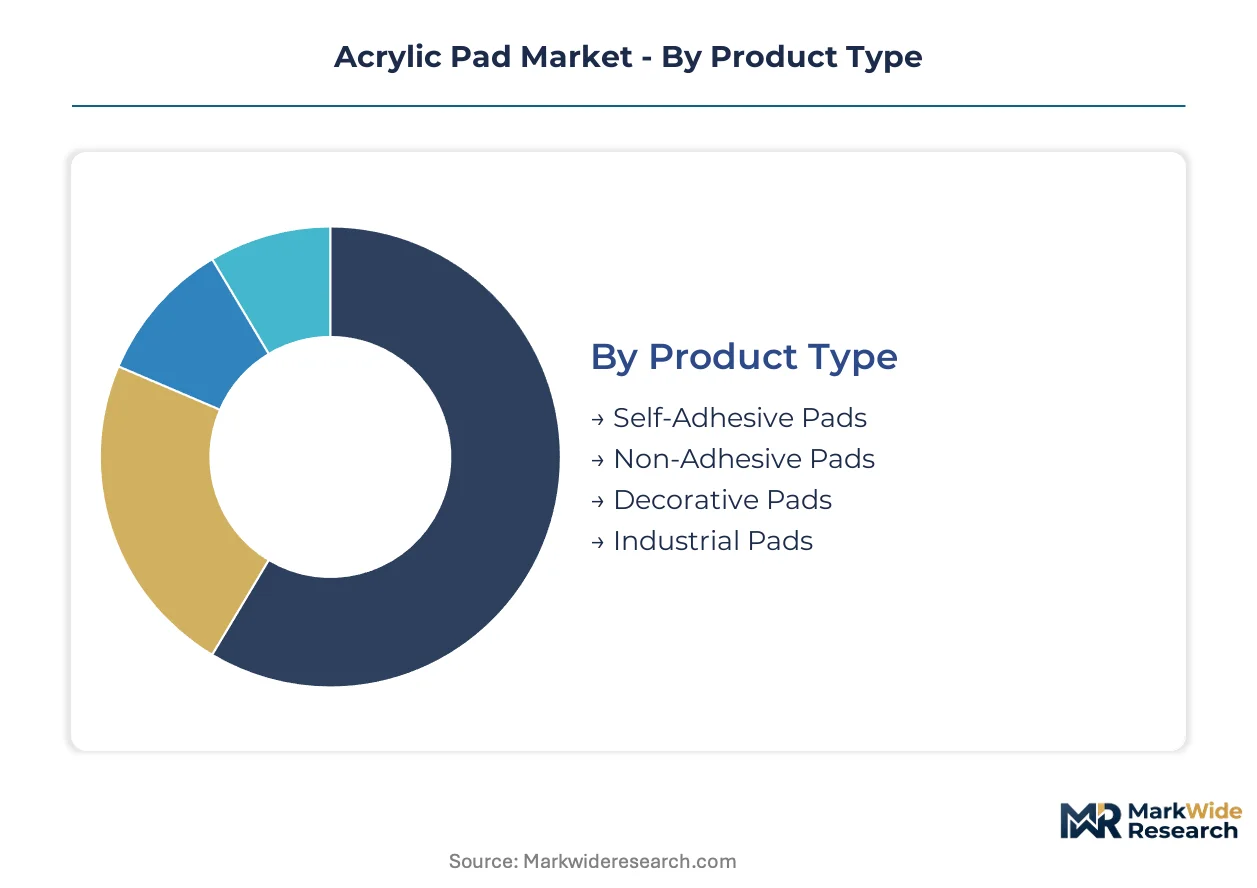
Acrylic pad manufacturers face divergent capital requirements across product architectures. Surface treatment chemistry, adhesive formulation compliance, and substrate finishing capabilities each demand specialized equipment investments that reshape competitive entry barriers.
Product Type:
Capital intensity varies sharply across adhesive and non-adhesive architectures, with coating line automation and regulatory certification driving upfront investment thresholds.
- Self-Adhesive Pads:UV-cured or solvent-based acrylic adhesive layers applied to heavyweight substrates. REACH registration requirements for acrylic monomer content are compressing formulation flexibility in European distribution channels while elevating R&D spend on bio-based alternatives.
- Non-Adhesive Pads:Water-based acrylic sizing treatments on cotton rag or alpha-cellulose substrates rated 190-400 gsm. Educational procurement in Germany and surrounding Central European markets favors these formulations for ISO 9706 permanence compliance and reworkability.
- Decorative Pads:Surface-printed or textured finishes for consumer gifting segments.
- Industrial Pads:Custom substrate specifications for manufacturing process applications.
Most installed capacity flows through Non-Adhesive Pads. Expansion is steepest in Self-Adhesive Pads as UV-cured formulations gain regulatory clearance.
Application:
Application segments separate by margin structure, with professional art use commanding premium pricing against commoditized office supply volumes.
- Art and Craft:Heavyweight pads with specialized sizing for acrylic paint load resistance. Museum-adjacent retailers and university art departments in Germany concentrate demand for premium-grade output from specialized mill networks.
- Office Supplies:Standard-weight pads for general documentation and presentation mounting. Corporate procurement favors cost-optimized specifications with minimal surface treatment.
- Medical Use:Sterile-grade pads for wound dressing and device fixation.
- Packaging:Quick-mount functionality drives replacement cycles in logistics and fulfillment operations.
Art and Craft captures the highest per-unit margins. Packaging shows the steepest volume expansion trajectory as e-commerce fulfillment scales.
End User:
End user concentration determines channel strategy, with institutional buyers demanding certified permanence against consumer price sensitivity.
- Educational Institutions:University art departments and K-12 programs specifying ISO 9706-compliant substrates. Procurement mandates in German-speaking markets filter through specialized paper manufacturing clusters.
- Corporate Offices:Standardized supply contracts with minimal customization requirements.
- Healthcare Facilities:Regulatory-compliant pads for clinical environments.
- Retail Stores:Open-stock and private-label assortment strategies for hobbyist segments.
Educational Institutions anchor premium positioning. Retail Stores are climbing fastest as curated private-label programs displace traditional brand intermediaries.
Distribution Channel:
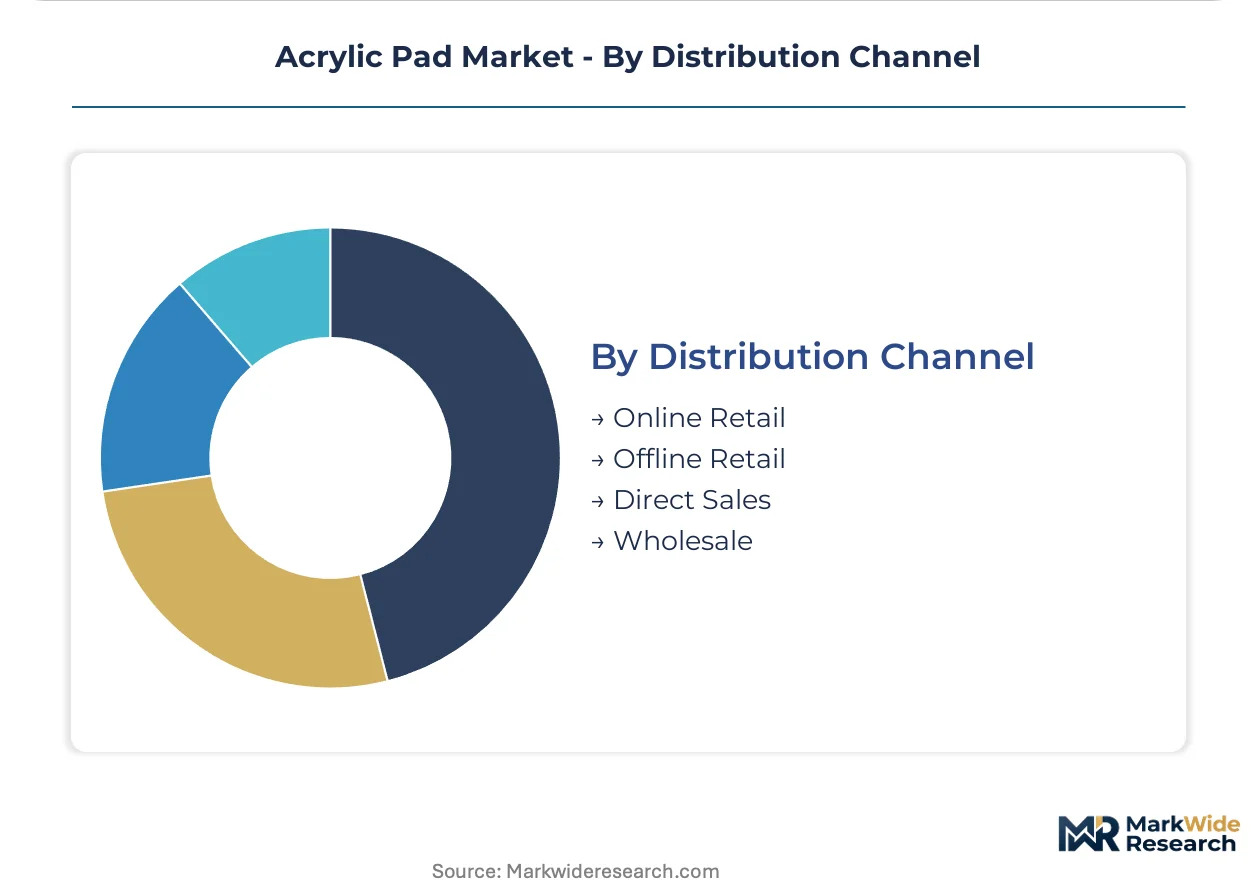
Channel architecture is bifurcating between direct-to-consumer platforms and legacy wholesale networks.
- Online Retail:Subscription-based replenishment programs capturing repeat purchase cycles. Dick Blick Art Materials and regional platforms build captive specifications bypassing traditional brand distribution.
- Direct Sales:Manufacturer relationships with institutional buyers and professional artist collectives.
- Offline Retail:Brick-and-mortart art supply stores with open-stock purchasing.
- Wholesale:Bulk distribution to educational suppliers and corporate stationery vendors.
Wholesale retains the largest volume footprint. Online Retail is gaining share fastest as subscription models lock in recurring revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between REACH-compliant European production and EPA-governed US manufacturing is shifting investment toward jurisdictions with lower compliance costs. Manufacturers are relocating coating operations to exploit these arbitrage gaps while maintaining premium-grade output for institutional buyers.
Germany
University art departments in Berlin and Munich drive ISO 9706-compliant procurement for heavyweight pads. ECHA registration requirements under REACH restrict acrylic monomer content in self-adhesive formulations. Specialized paper finishing clusters in Bavaria sustain captive supply advantages for professional artist segments.
United States
EPA volatile organic compound guidelines constrain solvent-based adhesive production for domestic distribution. Museum-adjacent retailers in New York and Los Angeles specify premium non-adhesive pads for conservation-grade applications. Strathmore anchors North American supply through specialized paper finishing capabilities in the Midwest.
China
MEE emission trading schemes create premium positioning for water-based adhesive formulations in export-oriented manufacturing. Yangtze River Delta paper mills scale production of 190-400 gsm substrates for art supply OEMs. Domestic demand concentrates in Shanghai and Beijing studio collectives.
United Kingdom
Post-Brexit regulatory alignment with REACH maintains chemical content standards for European-bound exports. London art schools and national museum networks specify archival-grade pad specifications. Regional distributors consolidate procurement through curated private-label programs.
France
CANSON leverages its historic Annonay mill network to sustain premium-grade output for professional segments. ANSM oversight of art material safety influences formulation choices for student-grade products. Île-de-France educational institutions anchor institutional procurement volumes.
Acrylic Pad Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium art supply channels favoring established mill brands while private-label programs capture volume in hobbyist and student tiers. The vendor base organizes around three archetypes: heritage European paper finishers with captive mill networks, North American distributors controlling direct-to-consumer channels, and Asian OEMs serving cost-optimized specifications. Consolidation pressure concentrates in the mid-tier, where scale advantages in coating line automation separate viable competitors from marginal players. Dominant competitive moves include backward integration into substrate manufacturing and subscription-based replenishment partnerships with online retail platforms.
Among heritage European specialists, CANSON and Strathmore exemplify the mill-integrated archetype, leveraging century-old finishing expertise and proprietary sizing formulations. Dick Blick Art Materials occupies a distinct position as a North American distributor, controlling curated private-label specifications that bypass traditional brand intermediaries. These three entities represent the structural poles around which competitive positioning organizes: manufacturing depth versus channel control versus hybrid integration.
| Leading Market Players |
|---|
| CANSON |
| Arteza |
| Strathmore |
| US Art Supply |
| Dick Blick Art Materials |
| JACKSON'S ART SUPPLIES |
| Creative Hands Art Materials |
| Arkema Group |
| Kuraray Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
REACH registration requirements under ECHA jurisdiction gate qualified supply for European-bound acrylic pads while simultaneously filtering premium-tier pricing access to manufacturers with compliant formulation capabilities. Buyers in German educational procurement channels now face bifurcated sourcing where certified water-based sizing commands structural premiums against reformulating competitors.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-weight substrates while premium-grade output from Bavarian mill networks maintains separation through ISO 9706 certification tiers. Three-tier pricing structure across premium, standard, and economy levels reflects substrate gsm rating, surface treatment chemistry, and archival compliance documentation. Cost compression in student-grade segments is intensifying because Yangtze mills scale 190-250 gsm output for art supply OEMs. Corporate office buyers exhibit highest price sensitivity; museum-adjacent retailers show least.
Supply Chain Analysis
Specialized paper finishing expertise concentrates in Germany's Bavarian clusters and France's Annonay mill network, constraining rapid capacity scaling for premium-grade acrylic sizing. Raw material dependencies center on cotton rag pulp from North American suppliers, alpha-cellulose feedstocks from Nordic producers, and water-based acrylic resin formulations from Benelux chemical specialists. Single-source vulnerability runs through legacy European surface treatment chemistry know-how. Distribution runs through curated private-label programs at online art supply platforms and wholesale networks serving educational institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acrylic pad market functions as a regulatory compounder where REACH authorization milestones for acrylic monomers continuously elevate compliance investment thresholds, consolidating demand around certified manufacturers with captive mill networks.
For Market Incumbents: Cement supply security through backward integration into alpha-cellulose substrate manufacturing in Central European clusters. Deepen formulation moats by accelerating UV-cured adhesive R&D ahead of ECHA restriction timelines. Synthetic canvas substitution in professional studio applications threatens paper pad volumes; counter via archival-grade certification bundling with educational procurement contracts. For New Entrants and Emerging Players: Launch via subscription-based replenishment partnerships with direct-to-consumer art supply platforms. Target travel-format hybrid pads merging watercolor and acrylic compatibility as the most penetrable white space. White-label manufacturing for curated private-label programs offers lowest barrier entry against heritage brand incumbency. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier European paper finishers with dormant mill assets because REACH compliance costs are driving distressed divestitures from family-owned operations. Five-to-ten year viability hinges on water-based adhesive patent estates and educational procurement relationships. Watch ECHA authorization timelines for specific acrylic monomers as inflection signal for competitive repositioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Manufacturing | Captive cotton rag supply from Bavarian mills insulates CANSON and Strathmore from pulp volatility. |
| UV-Cured Adhesive R&D Investment | ECHA-compliant formulations unlock continued European distribution for self-adhesive product lines. |
| Subscription Replenishment Partnerships | Dick Blick Art Materials locks recurring revenue through curated private-label pad specifications. |
| ISO 9706 Certification Acceleration | Museum-adjacent retailers in Berlin and Los Angeles filter procurement toward permanence-compliant substrates. |
| Hybrid Travel-Format Product Development | Field portability convergence opens white space between watercolor and acrylic application segments. |
Study Parameters
Direct dialogue with paper mill operations directors, art supply procurement managers at educational institutions, coating line automation engineers, and ECHA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from REACH registration databases, customs trade records for cotton rag pulp, SEC filings of art supply distributors, and ISO certification registries. Bottom-up substrate demand modeling triangulated against top-down educational spending projections.
Segment-level outputs across adhesive and non-adhesive architectures, art versus office application splits, and institutional versus retail end-user channels were generated over the projection horizon. CAGRs were derived from weighted average of historical pricing trajectories and forward capacity announcements. Industry-specific inputs included gsm rating migration patterns and REACH authorization timeline probabilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cellulose pulp price spikes or accelerated ECHA restriction schedules. Material deviation in ECHA monomer authorization timelines or Yangtze River Delta emission enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Filler Masterbatch Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Dammar Gum Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Global Quaternary Ammonium Compounds Market
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
Potassium Hydrogen Sulphite Market