
 Global Thin and Thick Film Resistors Market | 2026-2036
Global Thin and Thick Film Resistors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thin and Thick Film Resistors Market Outlook
Buyer concentration around automotive tier-one electronics suppliers is hardening as EV platforms consolidate resistor procurement across fewer qualified vendors. Vishay Intertechnology leverages its precision thin film portfolio to anchor high-reliability contracts with powertrain module makers. Yageo Corporation sustains manufacturing scale across thick film chip resistors, competing aggressively on cost in consumer electronics supply chains. KOA Corporation specializes in automotive-grade metal glaze products, differentiating through AEC-Q200 qualification breadth.
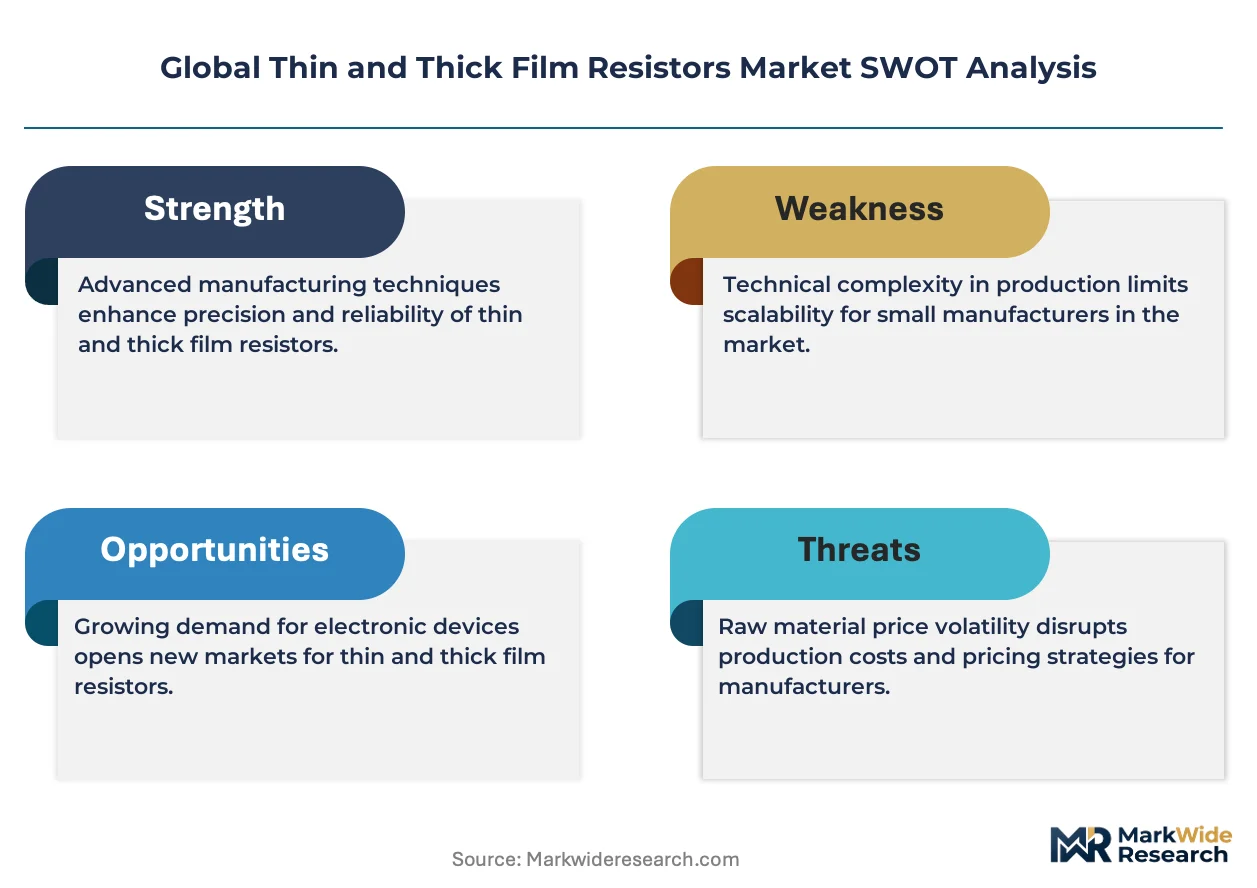
Thin and thick film resistors are passive electronic components manufactured by depositing resistive material—typically nichrome, tantalum nitride, or ruthenium oxide—onto ceramic substrates through sputtering or screen-printing processes, with tolerances ranging from ±0.01% to ±5% depending on the deposition method and laser trimming precision. Their primary purpose is to regulate current flow, divide voltages, and provide termination in circuits spanning consumer devices to industrial control systems. Thick film chip resistors occupy the highest volume tier due to cost efficiency in high-density surface mount assemblies, while thin film precision resistors capture disproportionate margin pools in medical devices and test instrumentation where temperature coefficient stability below 25 ppm/°C commands premium positioning. Surface mount technology leads across all application categories, though through-hole formats retain structural demand in high-power industrial and automotive environments where mechanical robustness outweighs miniaturization priorities.
RoHS and REACH frameworks in Europe restrict hazardous substances in resistor terminations and substrate coatings, compelling reformulation of traditional lead-bearing glass frits. The EPA and FCC in the United States impose complementary constraints on electronic waste streams and electromagnetic compatibility that shape end-product design requirements upstream. ISO standards for automotive quality management extend these compliance burdens into supplier qualification protocols. Stakeholders must monitor evolving material substitution timelines and dual-source qualification status as regulatory thresholds tighten across multiple jurisdictions.
Market Dynamics
Automotive electrification is consolidating resistor procurement around powertrain module suppliers capable of meeting AEC-Q200 qualification and dual-source requirements simultaneously.
Growth Catalysts
- EV Powertrain Standardization:Battery management systems and inverter controls require precision thin film resistors with temperature coefficients below 25 ppm/°C. Tier-one automotive electronics suppliers are qualifying fewer vendors per platform.
- REACH Material Substitution:European ECHA mandates are accelerating reformulation of lead-bearing glass frits in thick film terminations. Resistor manufacturers with compliant material pipelines capture qualified supplier status.
- Semiconductor Packaging Expansion:China's domestic advanced packaging facilities are scaling consumption of 0402 and 0201 chip resistors for flip-chip and wafer-level packaging applications.
Market Restraints
- Ruthenium Oxide Supply Concentration:Thick film resistor paste production concentrates among Japanese and European specialty chemical suppliers, exposing manufacturers to input cost volatility and allocation risk.
- Thin Film Deposition Equipment Lead Times:Sputtering system availability from dominant equipment vendors extends qualification timelines for new precision resistor production lines.
- Alternative Component Integration:Integrated passive devices and active load management circuits are substituting discrete resistors in space-constrained consumer electronics designs.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and component manufacturing are attracting resistor producers to establish localized thick film packaging operations.
- Medical Device Precision Requirements:Diagnostic imaging and patient monitoring equipment demand ultra-stable thin film networks with 0.01% tolerance and tracked thermal drift characteristics.
- Copper Termination Migration:RoHS-compliant copper-based termination technologies are converging with improved solderability coatings to displace traditional tin-lead finishes in high-reliability segments.
Industry Challenges
- Laser Trimming Specialist Scarcity:Precision thin film resistor production requires operators with expertise in sub-micron kerf control and real-time resistance mapping, creating talent acquisition bottlenecks.
- Dual Qualification Burden:Automotive customers demand parallel AEC-Q200 and IATF 16949 certification timelines, compressing product development cycles and straining validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thin and Thick Film Resistors Market |
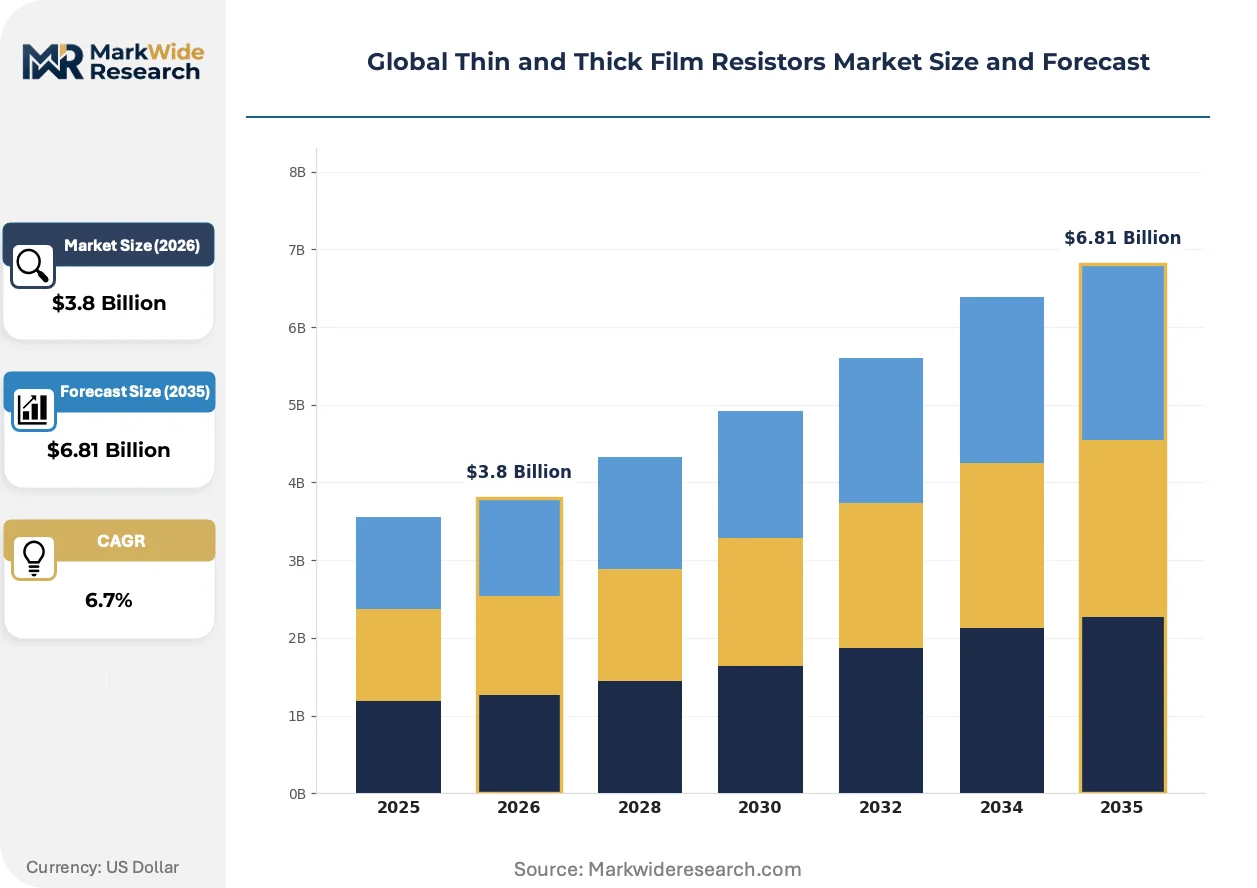
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Film, Thick Film, Chip Resistors, Wirewound Resistors Application: Consumer Electronics, Automotive Electronics, Telecommunications, Medical Devices End User: Manufacturers, Repair Services, Distributors, Research Institutions Technology: Surface Mount, Through-Hole, Precision Resistors, High-Power Resistors |
| Companies Covered | Rohm Co., Bourns, Vishay Intertechnology, TT Electronics, TE Connectivity, Yageo Corporation, Panasonic Corporation, Walsin Technology, KOA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thin and Thick Film Resistors Market Strategic Shifts
Material science advances and deposition process refinements are redefining performance thresholds across both commodity thick film and precision thin film resistor categories.
Tantalum nitride thin film technology is absorbing demand from nichrome-based alternatives in high-temperature automotive sensing applications. Powertrain module makers in Germany and Japan are qualifying TaN resistors for exhaust gas and battery thermal monitoring circuits. The technology is absorbing margin pressure from commodity thick film competition by anchoring premium positioning in safety-critical measurement loops.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing reformulation of cleaning chemistries used in thick film resistor laser trimming and substrate preparation. Manufacturers serving European automotive and industrial customers are qualifying aqueous and plasma-based alternatives to traditional solvent processes. Medical device producers in Switzerland and Germany face the steepest compliance timelines due to stringent surface cleanliness requirements.
Consolidated procurement contracts are compressing distributor margins and accelerating direct manufacturer-to-OEM relationships in high-volume automotive and consumer electronics segments. Authorized distributors in Southeast Asia are losing share to regional trading companies offering consolidated component kits for contract electronics manufacturers. The shift is most visible in China's Pearl River Delta assembly clusters, where resistor procurement is bundling with capacitor and inductor sourcing under single vendor-managed inventory agreements.
Global Thin and Thick Film Resistors Market Segmentation
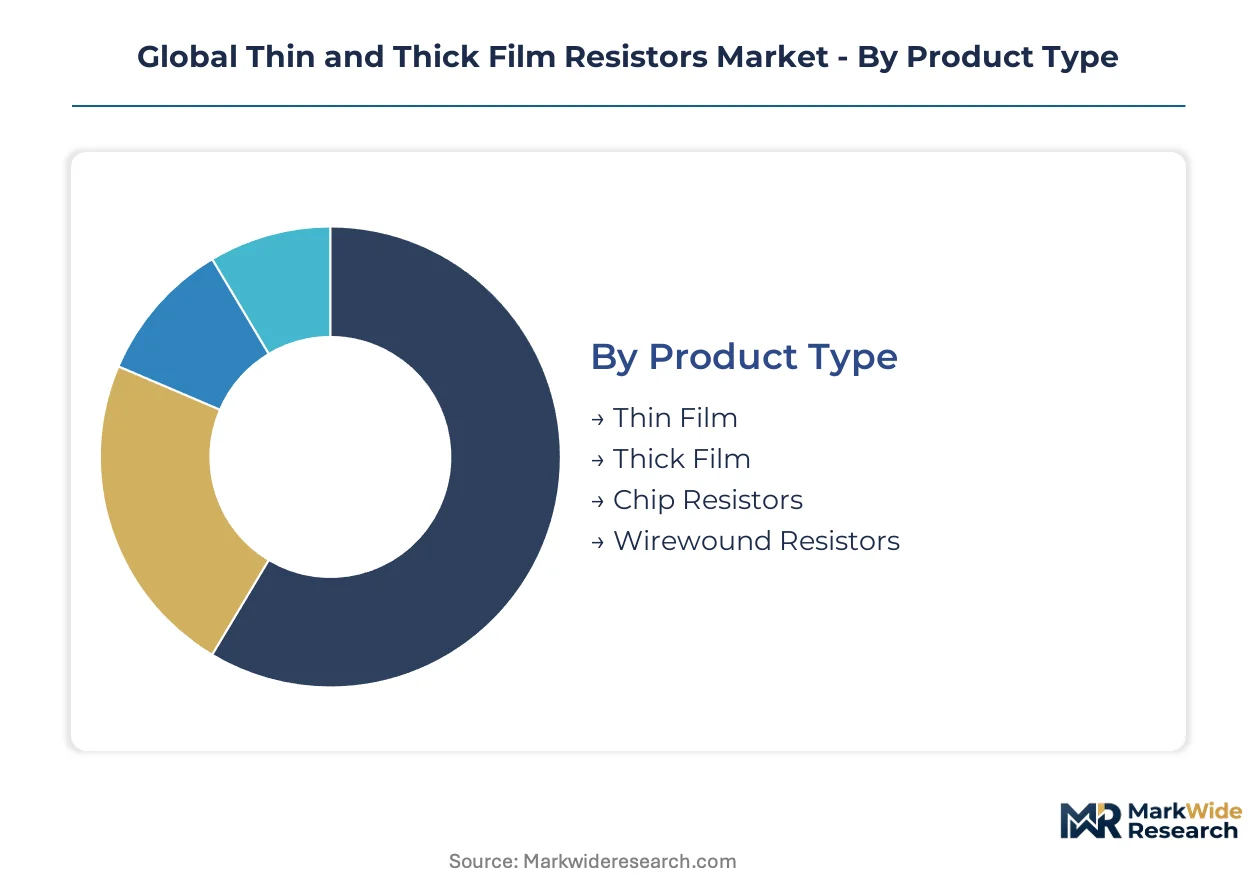
Segmentation in the resistor market tracks how deposition precision, mounting formats, and end-use reliability requirements split procurement patterns across automotive, medical, and consumer supply chains. Understanding these divides exposes where margin pools concentrate versus where volume commoditization accelerates.
Product Type:
Buyers differentiate primarily by tolerance thresholds and thermal stability needs, with precision applications commanding premiums while commodity segments compete on scale.
- Thin Film:Sputtered nichrome or tantalum nitride layers on ceramic substrates achieve tolerances down to ±0.01% with temperature coefficients below 25 ppm/°C. German powertrain module makers and Japanese battery management system suppliers are consolidating procurement around qualified thin film vendors for EV sensing circuits.
- Thick Film:Screen-printed ruthenium oxide pastes on alumina substrates deliver cost-efficient ±1% to ±5% tolerances for high-density surface mount assemblies. Chinese consumer electronics contract manufacturers in Shenzhen and Dongguan dominate consumption, driving aggressive price negotiation on 0402 and 0603 chip formats.
- Chip Resistors:Rectangular ceramic-bodied components with termination electrodes at both ends, dominating automated pick-and-place assembly lines across all volume tiers.
- Wirewound Resistors:Resistive wire coils around ceramic or fiberglass cores handling surge currents and high-power dissipation in industrial motor drives and grid infrastructure.
Thick film leads volumes today; thin film is gaining share fastest in automotive electrification.
Application:
End-use reliability certification requirements fragment procurement, with AEC-Q200 automotive qualification creating vendor lock-in distinct from consumer electronics cost optimization.
- Consumer Electronics:Smartphones, laptops, and wearables demand 0201 and 0402 chip resistors in billion-unit annual volumes. Assembly lines in China's Pearl River Delta bundle resistor procurement with capacitor and inductor sourcing under vendor-managed inventory agreements.
- Automotive Electronics:Battery management systems, inverter controls, and advanced driver-assistance systems require AEC-Q200 qualified resistors with documented failure rate data. Tier-one electronics suppliers in Germany and Japan are reducing qualified vendor lists per EV platform.
- Telecommunications:Base station power amplifiers and optical networking equipment balance precision with thermal cycling endurance in outdoor deployments.
- Medical Devices:Diagnostic imaging and patient monitoring equipment demand ultra-stable thin film networks with tracked thermal drift characteristics and ISO 13485 quality system documentation.
Consumer electronics captures the largest volume position; automotive electronics shows the steepest expansion trajectory.
End User:
Procurement authority concentration varies sharply, with manufacturers driving specification standards while distributors lose ground to direct OEM relationships.
- Manufacturers:Original equipment manufacturers in automotive, medical, and industrial segments set resistor specifications and qualify suppliers directly. Consolidated procurement contracts are compressing distributor margins and accelerating manufacturer-to-OEM relationships.
- Repair Services:Aftermarket maintenance operations for industrial automation and automotive electronics require compatible replacement resistors with documented parametric equivalence.
- Distributors:Authorized distributors in Southeast Asia are losing share to regional trading companies offering consolidated component kits for contract electronics manufacturers.
- Research Institutions:Universities and national laboratories prototype custom resistor networks for experimental instrumentation and aerospace applications.
Manufacturers dominate procurement value; distributors are ceding share fastest to direct channels.
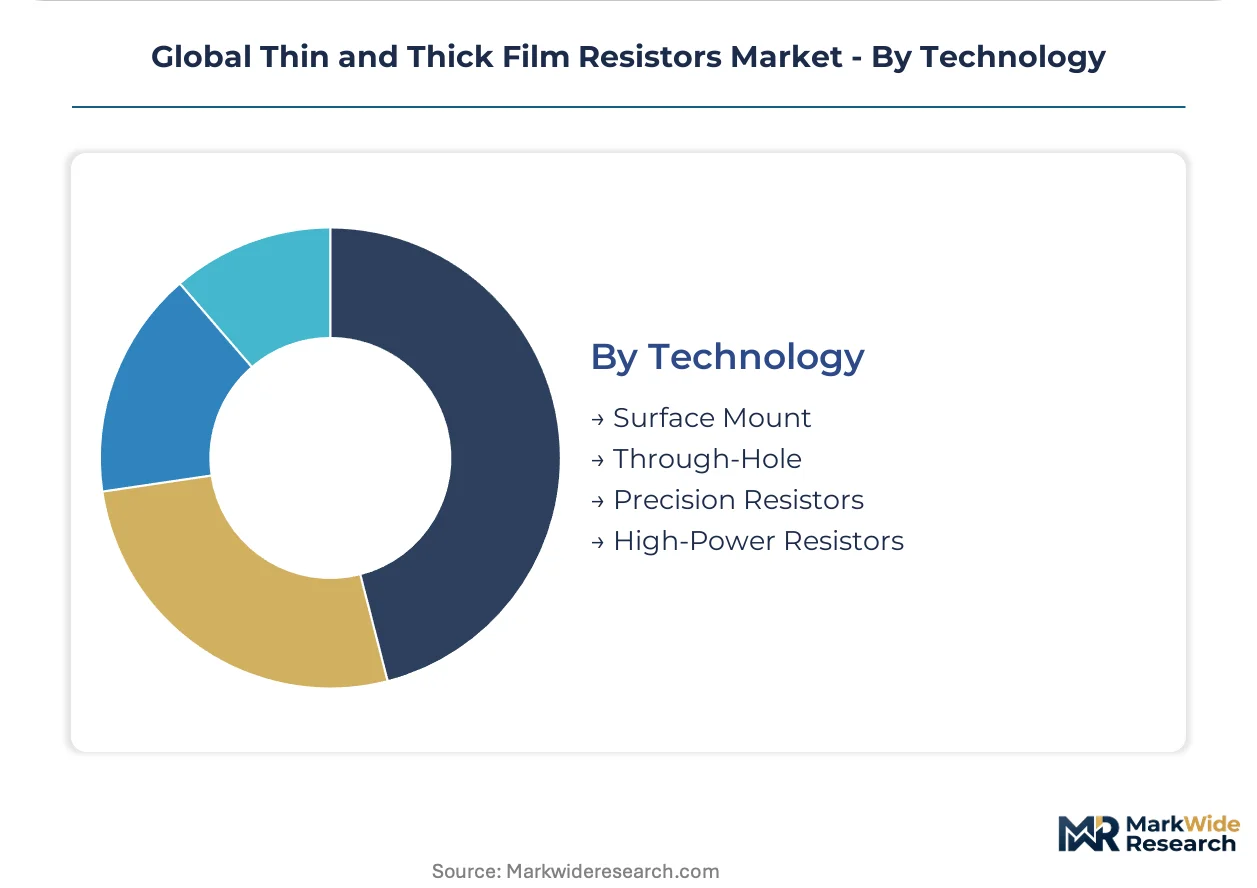
Technology:
Mounting format selection reflects the tension between miniaturization imperatives and mechanical robustness requirements in high-vibration environments.
- Surface Mount:Leadless chip resistors attach directly to PCB pads, enabling automated assembly and highest component density. The format leads across consumer electronics, telecommunications, and automotive interior electronics where vibration exposure is limited.
- Through-Hole:Axial and radial leaded resistors insert through PCB holes and solder on opposite sides, retaining structural demand in high-power industrial and under-hood automotive environments where mechanical robustness outweighs miniaturization priorities.
- Precision Resistors:Laser-trimmed thin film or foil technologies achieving ±0.01% tolerance and sub-5 ppm/°C temperature coefficients for test instrumentation and medical measurement.
- High-Power Resistors:Aluminum-housed wirewound or thick film designs dissipating 5W to 1000W in motor drives, power supplies, and braking resistor applications.
Surface mount leads volumes today; precision resistors are climbing the fastest in medical and automotive sensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in precision electronics manufacturing anchor geographic demand concentration. Sputtering equipment operators and laser trimming specialists concentrate in established semiconductor clusters, creating self-reinforcing supply ecosystems.
China
Domestic semiconductor packaging expansion drives resistor consumption at advanced packaging facilities in Jiangsu and Guangdong. MIIT's dual carbon goals accelerate energy efficiency mandates for electronics manufacturing equipment. The Yangtze River Delta cluster around Shanghai anchors thick film chip resistor production for consumer electronics contract manufacturers.
Germany
Powertrain module makers in Stuttgart and Munich qualify precision thin film resistors for battery management systems in EV platforms. KBA enforces AEC-Q200 documentation requirements through type approval processes for automotive electronics. Bavaria's automotive electronics corridor concentrates tier-one supplier engineering centers demanding sub-25 ppm/°C temperature coefficient stability.
United States
Medical device manufacturers in Minnesota and Massachusetts source ultra-stable thin film networks for diagnostic imaging equipment. FDA quality system regulations under 21 CFR Part 820 extend into resistor supplier qualification protocols. The Pacific Northwest hosts test instrumentation OEMs specifying 0.01% tolerance resistors for metrology applications.
Japan
Automotive-grade metal glaze resistor specialists serve hybrid and EV powertrain programs through Nagoya and Tokyo engineering centers. METI's industrial competitiveness policies support domestic precision component manufacturing capabilities. Kyushu's semiconductor materials cluster supplies ruthenium oxide pastes to thick film resistor producers.
India
Electronics manufacturing incentives under the PLI scheme attract thick film packaging operations to Gujarat and Tamil Nadu. BIS certification requirements for electronic components create compliance entry barriers for imported resistors. The Delhi-NCR corridor hosts emerging contract manufacturers bundling resistor procurement with passive component sourcing.
Global Thin and Thick Film Resistors Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across resistor market tiers. The vendor base spans Japanese precision component houses, Taiwanese scale operators, and European automotive-qualified suppliers. Three archetypes dominate: integrated passive component conglomerates, automotive-focused qualification specialists, and cost-driven volume manufacturers. M&A activity concentrates on acquiring AEC-Q200 qualified production lines, while capacity expansion targets 0201 and 0402 chip formats for advanced packaging demand.
Among the named participants, Vishay Intertechnology anchors high-reliability positioning through precision thin film portfolios, Yageo Corporation exemplifies scale-driven thick film manufacturing, and KOA Corporation occupies the automotive-grade specialization tier. These three represent distinct competitive vectors—precision qualification, manufacturing scale, and application-specific certification—rather than overlapping market positions. Each sits within a different procurement channel: powertrain module direct supply, consumer electronics distributor networks, and tier-one automotive electronics qualification lists respectively.
| Leading Market Players |
|---|
| Rohm Co. |
| Bourns |
| Vishay Intertechnology |
| TT Electronics |
| TE Connectivity |
| Yageo Corporation |
| Panasonic Corporation |
| Walsin Technology |
| KOA Corporation |
| Others |
Value Chain & Pricing Dynamics
Tier-one automotive electronics suppliers are consolidating qualified vendor lists per EV platform, anchoring contract-based long-term offtake agreements that compress spot-market pricing power for commodity thick film resistors. This buyer concentration forces pricing stratification across AEC-Q200 certified precision tiers, standard industrial grades, and economy consumer electronics segments.
Pricing Analysis
Component bundling with capacitors and inductors under vendor-managed inventory agreements separates negotiated contract pricing from spot-market spot buying. Price differentiation rests on AEC-Q200 certification grade and volume scale, with automotive-grade thin film resistors commanding premiums against consumer electronics commodity tiers. Cost compression in thick film chip formats intensifies because Chinese contract manufacturers leverage consolidated procurement volumes. Consumer electronics OEMs in Shenzhen and Dongguan exhibit the highest price sensitivity, while German powertrain module makers prioritize thermal stability specifications over unit cost.
Supply Chain Analysis
AEC-Q200 and IATF 16949 qualification gating restricts supply base breadth, concentrating certified production among Japanese, German, and Taiwanese precision component houses. Raw material dependencies center on ruthenium oxide pastes from Kyushu-based specialty chemical suppliers, nichrome sputtering targets, and alumina ceramic substrates. Single-source vulnerability in laser trimming equipment from dominant vendors creates qualification timeline risk for new precision resistor lines. Distribution runs through authorized distributors losing share to direct manufacturer-to-OEM relationships in high-volume automotive and consumer electronics segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where REACH material substitution timelines and RoHS termination reformulation mandates are accelerating demand for compliant resistor portfolios. European ECHA enforcement actions against lead-bearing glass frits create structural vendor replacement windows.
For Market Incumbents: Hedge against ruthenium oxide supply concentration by qualifying alternative paste formulations and securing dual-source agreements with Japanese specialty chemical suppliers. Anchor position through backward integration into sputtering target production or captive ceramic substrate manufacturing to defend margin pressure from commodity thick film competition. For New Entrants and Emerging Players: REACH in Europe opens a window for copper-based termination technologies displacing traditional tin-lead finishes in high-reliability segments. Target India's PLI scheme electronics manufacturing clusters where localized thick film packaging operations face limited qualified domestic competition. Pursue hospital system partnerships for ISO 13485-certified thin film networks in diagnostic imaging equipment. For Investors and Strategic Acquirers: Automotive electronics conglomerates are the most active acquirer in this space, seeking AEC-Q200 qualified production lines to consolidate powertrain module supply relationships. Long-term viability hinges on exposure to EV platform standardization cycles rather than consumer electronics commodity exposure. Monitor IATF 16949 certification backlog as an inflection indicator for supply-constrained precision resistor tiers.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Certification Investment | Qualifies suppliers for German and Japanese EV powertrain module procurement lists. |
| Copper Termination Migration | Aligns resistor portfolios with RoHS and REACH compliance requirements in European markets. |
| India PLI Localization | Captures thick film packaging demand from Gujarat and Tamil Nadu contract manufacturers. |
| Precision Thin Film Capacity Expansion | Serves Minnesota and Massachusetts medical device manufacturers requiring 0.01% tolerance networks. |
| Ruthenium Oxide Paste Dual Sourcing | Mitigates allocation risk from Kyushu-based specialty chemical supply concentration. |
Study Parameters
Bottom-up automotive electronics and medical device modeling reconciled against top-down resistor production and import tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement managers, precision component R&D directors, hospital biomedical engineers, and semiconductor packaging operations heads combined with secondary validation from ECHA substance restriction databases, MIIT equipment efficiency filings, KBA type approval documentation, and customs trade flow records. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map deposition equipment capacity, paste formulation supply, and end-use qualification requirements against projected EV platform ramp schedules and medical device OEM procurement cycles. Segmentation dimensions span product type, application vertical, mounting technology, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation moderated by qualification timeline constraints and material substitution elasticity assumptions. Ruthenium oxide price volatility and laser trimming equipment lead times feed directly into capacity expansion scenario modeling.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden REACH enforcement acceleration or automotive platform consolidation cancellations. Forecasts reflect documented assumptions regarding AEC-Q200 adoption curves and copper termination technology maturation. A model refresh is warranted upon material change in ECHA substance restriction timelines or IATF 16949 certification processing rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Passive Tunable Integrated Circuits Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Chip Capacitor Market
Passive And Interconnecting Electronic Components
Ultra-Thin Electronic PI Film Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Thick Film Resistor Market
Passive And Interconnecting Electronic Components
Global Precision Resistor Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Global EMI Shielding Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market