
 Paper Gummed Tape Market | 2026-2036
Paper Gummed Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Gummed Tape Market Analytics
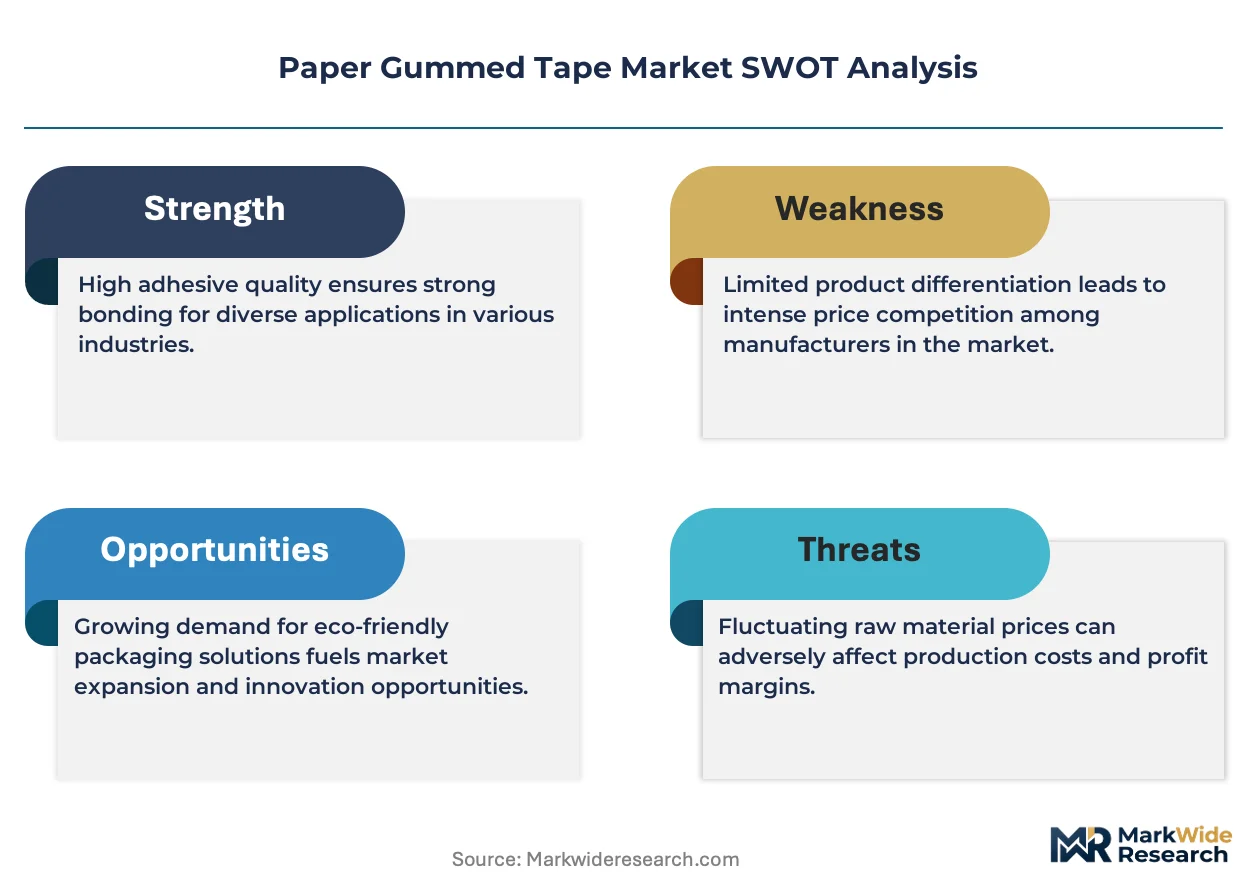
Asset-light leasing models for coating and slitting equipment are reconfiguring competitive entry barriers for mid-tier producers. 3M leverages its materials science depth to sustain premium positioning in reinforced tape grades. Intertape Polymer Group anchors North American supply through integrated kraft paper sourcing. Tesa SE differentiates via adhesive formulations optimized for high-speed automated case sealers.
Paper gummed tape comprises a kraft paper backing coated with a starch-based adhesive that requires moisture activation to form a permanent bond with corrugated fiberboard, typically delivering tamper-evident sealing at tensile strengths exceeding 60 lbs per inch. Its primary commercial purpose centers on secure carton closure in distribution environments where recyclability and package integrity carry equal weight. Water-activated tape dominates volume flows across e-commerce fulfillment networks, while reinforced grades command margin pools in heavy-goods manufacturing applications. Pressure-sensitive variants occupy a mature niche in crafting and light retail packaging where convenience outweighs bond permanence.
The EU Green Deal and Packaging and Packaging Waste Regulation shape product standards by mandating recyclability and recycled content thresholds for shipping materials across member states. EPA guidelines on sustainable packaging influence procurement criteria for US-based logistics operators seeking to reduce landfill diversion costs. Stakeholders must monitor how evolving extended producer responsibility frameworks in both jurisdictions will redefine cost allocation between tape manufacturers and their downstream packaging customers.
Market Dynamics
The EU Green Deal and Packaging and Packaging Waste Regulation are compressing adoption timelines for water-activated tape across European e-commerce fulfillment networks. Corrugated box manufacturers face binding recyclability mandates that eliminate plastic tape alternatives from certified packaging streams.
Growth Catalysts
- E-commerce fulfillment automation:High-speed case sealers in German distribution centers require starch-based adhesives that bond permanently with fiberboard. Automated dispensing systems reduce labor cost per carton while meeting tamper-evidence requirements.
- EU Packaging and Packaging Waste Regulation:Recycled content thresholds and extended producer responsibility frameworks mandate recyclable sealing solutions. Member states enforce compliance through national packaging registries that track material flows.
- Kraft paper supply localization:Nordic pulp mills expanding specialty paper capacity are shortening lead times for tape backing substrates. Regional sourcing reduces exposure to transatlantic shipping volatility.
Market Restraints
- Starch adhesive input volatility:Wheat and corn starch prices fluctuate with agricultural commodity cycles and biofuel policy shifts. Tape margins compress when grain markets spike during drought periods in major producing regions.
- Equipment capital requirements:Water-activated tape dispensers require upfront investment that small fulfillment operators defer. Pressure-sensitive alternatives dominate micro-fulfillment sites with limited capex budgets.
- Climate sensitivity of bond formation:Low-humidity warehouse environments in continental interiors degrade activation consistency. Cold-chain logistics facilities report higher seal failure rates during winter months.
Strategic Opportunities
- Heavy-goods manufacturing penetration:Reinforced tape grades with fiberglass or synthetic yarn backing remain underdeployed in machinery and automotive parts shipping. These applications command premium pricing against plastic strapping alternatives.
- Direct-to-consumer craft segment:Artisan paper merchants and subscription box services seek aesthetic-grade gummed tape with custom printing. This channel bypasses industrial distributor markups.
- EU circular economy certification:Cradle-to-Cradle and EU Ecolabel standards create procurement preference for verified sustainable sealing. Early certification locks in supplier status with sustainability-focused retailers.
Industry Challenges
- Adhesive formulation expertise scarcity:Starch modification chemistry requires skills concentrated in legacy paper industry regions. Tape producers compete with food and pharmaceutical sectors for qualified polymer scientists.
- Legacy dispenser fleet incompatibility:Warehouse operators resist retrofitting existing case sealing lines for water-activation. Hybrid dispensing equipment that handles both tape types extends transition timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Gummed Tape Market |
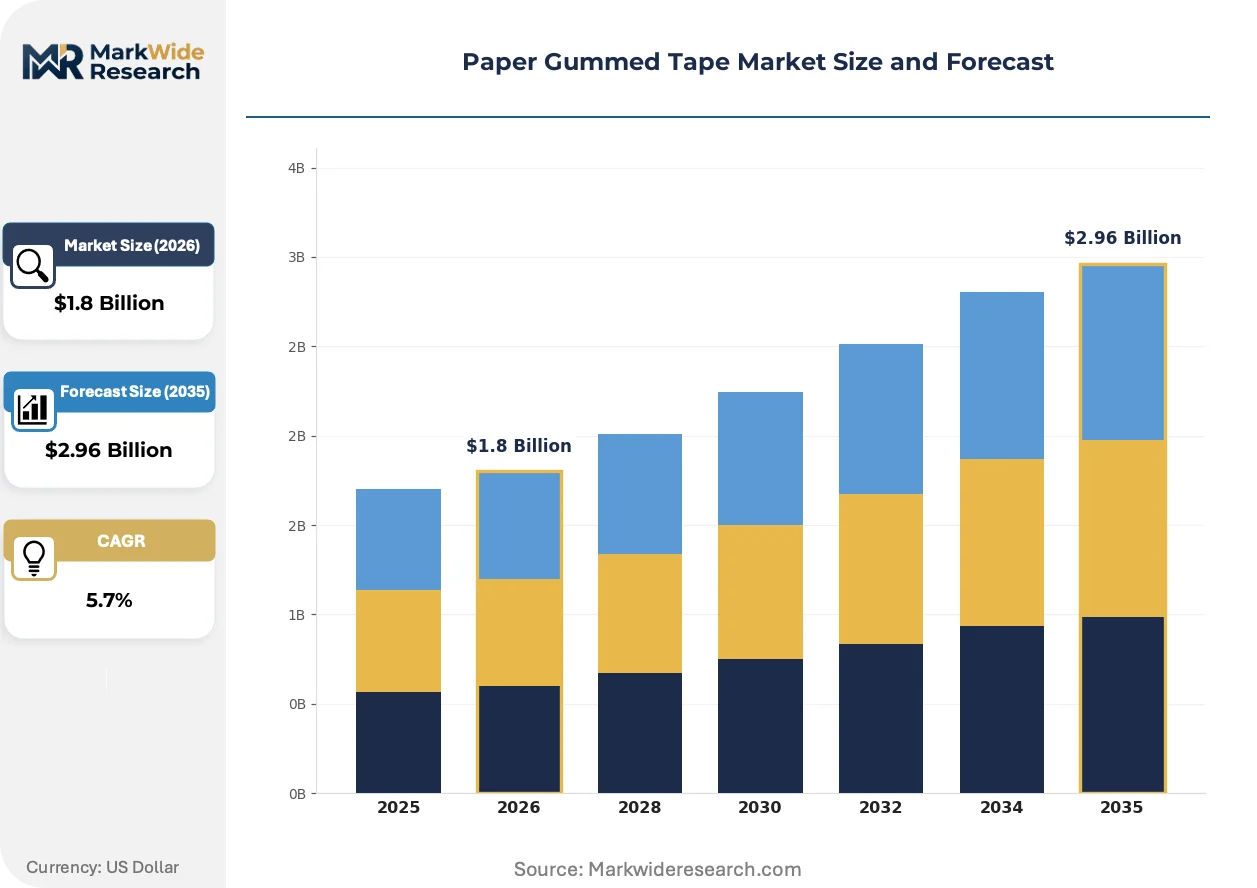
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Activated, Pressure-Sensitive, Custom Printed, Reinforced Application: Packaging, Crafting, Shipping, Sealing End User: Retail, E-Commerce, Manufacturing, Logistics Distribution Channel: Online, Retail Stores, Distributors, Wholesalers |
| Companies Covered | Vibac Group, Berry Global, 3M, Holland Manufacturing, Papertec, Intertape Polymer Group, Tesa SE, Can-Do National Tape, Shurtape Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Gummed Tape Market Evolving Landscape
Material science advances and regulatory stringency are converging to redefine performance benchmarks for fiberboard sealing applications. Product development priorities now center on bond reliability under variable environmental conditions.
Reinforced gummed tape is migrating from manual packing stations to automated production lines in heavy-goods manufacturing. Automotive component suppliers in Stuttgart and Wolfsburg are specifying fiberglass-yarn grades for palletized shipments to assembly plants. This migration from hand-application to robotic dispensing compresses labor content while satisfying OEM tamper-evidence protocols.
The EU Green Deal's packaging waste reduction targets are forcing corrugated converters to eliminate plastic tape from certified recyclable streams. National implementation through Germany's VerpackG registry and France's CITEO eco-modulation fees penalize non-recyclable sealing. E-commerce fulfillment centers in Rotterdam and Antwerp are responding by converting dispenser fleets to water-activated systems ahead of 2025 reporting deadlines.
Consolidated buying by multinational logistics operators is concentrating procurement decisions at regional headquarters rather than facility level. Amazon, Zalando, and Otto Group negotiate master supply agreements that specify adhesive performance standards across their European warehouse networks. This centralization is most visible in Germany, where three buyers account for a disproportionate share of industrial-grade tape volume.
Paper Gummed Tape Market Segmentation
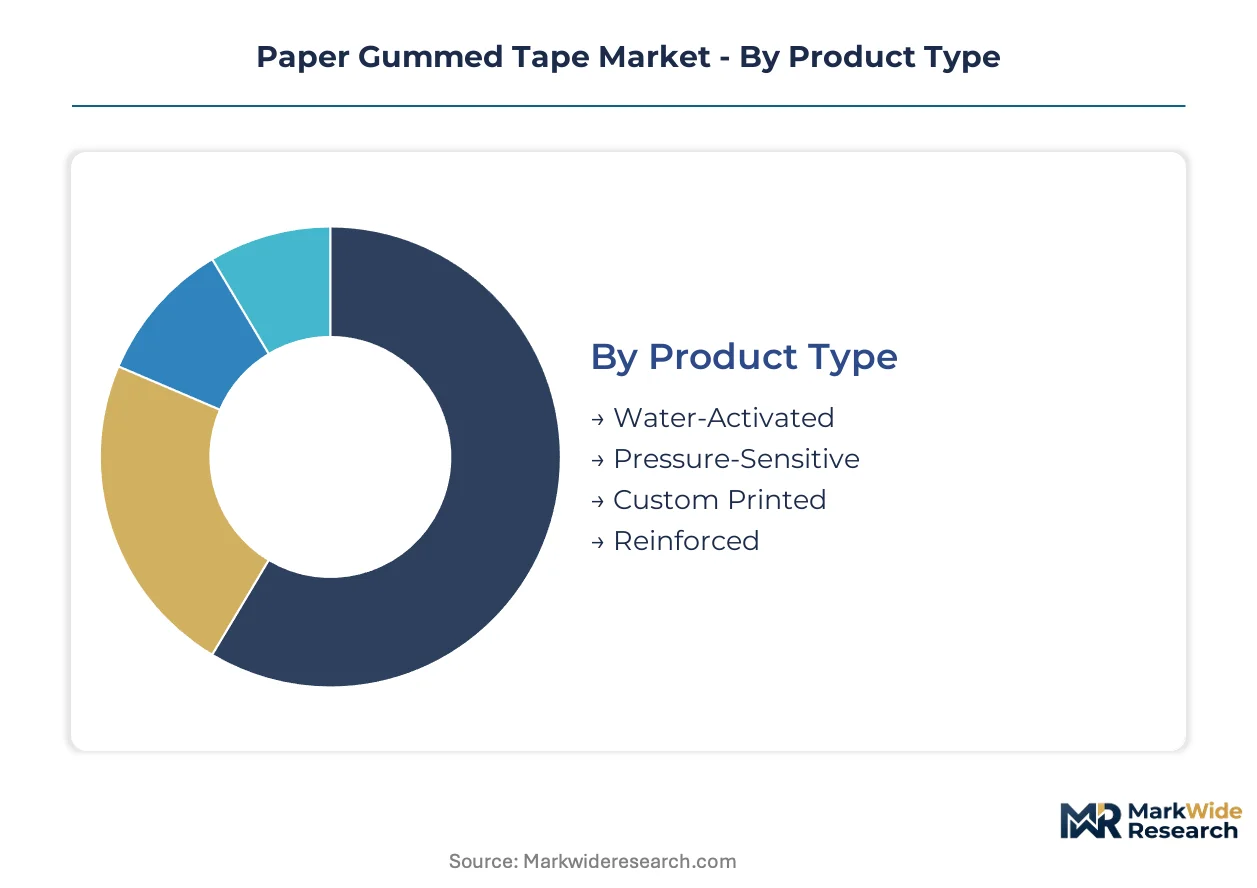
Paper gummed tape segments exhibit divergent turnover velocities, with industrial fulfillment applications cycling inventory weekly while craft-oriented channels turn stock seasonally. Understanding these cadence differences shapes production planning and margin capture strategies for tape manufacturers.
Product Type:
Water-activated grades rotate through distribution centers fastest due to binding EU recyclability mandates, while pressure-sensitive variants linger in retail channels with extended replenishment cycles.
- Water-Activated:Starch-based adhesive requires moisture activation to form permanent bonds with corrugated fiberboard, delivering tamper-evident seals exceeding 60 lbs per inch tensile strength. German e-commerce fulfillment centers in Leipzig and Hamburg are converting dispenser fleets ahead of VerpackG registry deadlines.
- Reinforced:Fiberglass or synthetic yarn backing provides structural integrity for heavy-goods palletization. Stuttgart automotive component suppliers specify these grades for machinery shipments to assembly plants, commanding premium positioning against plastic strapping alternatives.
- Pressure-Sensitive:Pre-coated adhesive enables immediate application without water activation. Craft retailers and subscription box services favor convenience over bond permanence.
- Custom Printed:Aesthetic-grade substrates with branded graphics serve direct-to-consumer unboxing experiences. Artisan paper merchants bypass industrial distributor markups through this channel.
Water-activated tape dominates installed base in European logistics networks. Reinforced grades are where expansion concentrates in heavy-goods manufacturing.
Application:
Cost tier differentiation separates high-volume carton closure from discretionary craft consumption, with fulfillment automation driving procurement consolidation at the premium end.
- Packaging:Corrugated box sealing for distribution networks requires consistent bond formation under variable humidity. Rotterdam and Antwerp fulfillment centers specify starch-based adhesives for certified recyclable streams under EU Green Deal targets.
- Shipping:Long-haul freight protection demands reinforced backing for pallet stability. Cold-chain logistics facilities report seal failure challenges during continental winter months.
- Sealing:Tamper-evidence protocols in pharmaceutical and electronics distribution favor permanent fiberboard adhesion. National packaging registries track compliance across member states.
- Crafting:Hobby and artisan applications prioritize aesthetic presentation over structural performance. Seasonal demand peaks align with gift-giving periods.
Packaging commands the largest revenue pool. Shipping applications are climbing the fastest as heavy-goods manufacturers displace plastic alternatives.
End User:
Volume concentration varies sharply, with consolidated multinational buyers negotiating master supply agreements while fragmented retail operators purchase through distribution intermediaries.
- E-Commerce:Amazon, Zalando, and Otto Group centralize procurement decisions at regional headquarters across German warehouse networks. High-speed automated case sealers reduce labor cost per carton while meeting performance standards.
- Manufacturing:Automotive and machinery producers specify reinforced grades for OEM tamper-evidence protocols. Robotic dispensing systems compress labor content in Stuttgart and Wolfsburg facilities.
- Logistics:Third-party fulfillment operators balance capex constraints against regulatory compliance timelines. Small operators defer water-activation equipment investments.
- Retail:Brick-and-mortar chains stock pressure-sensitive varieties for consumer convenience. Store-level purchasing lacks volume leverage for direct manufacturer negotiation.
E-commerce anchors volume demand. Manufacturing represents the steepest expansion trajectory as industrial automation penetrates heavy-goods shipping.
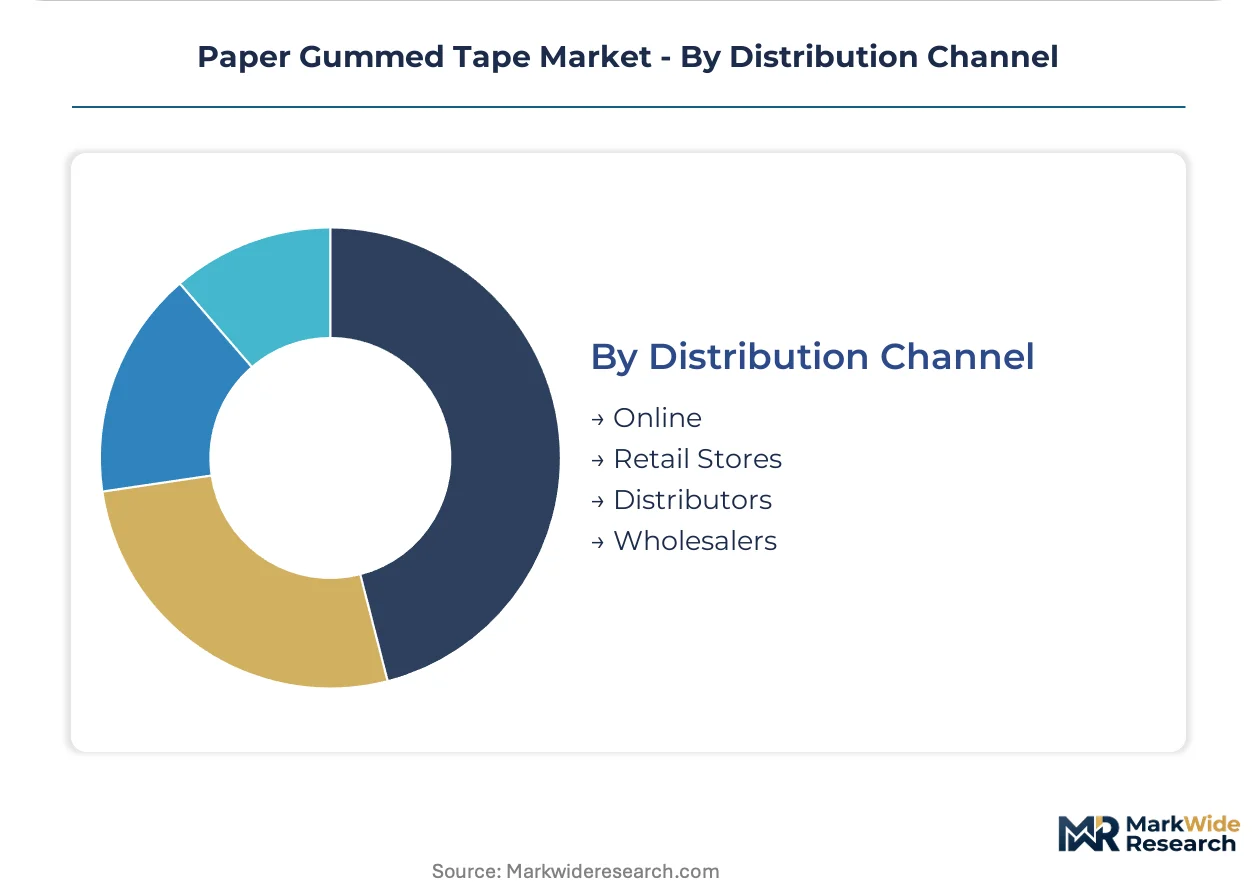
Distribution Channel:
Supply concentration in Nordic pulp regions shortens lead times for direct procurement, while intermediary networks extend reach to capital-constrained smaller operators.
- Distributors:Industrial packaging specialists maintain regional inventory positions for fulfillment center replenishment. German corrugated converters rely on distributor technical support for dispenser fleet conversion.
- Online:Direct manufacturer portals serve consolidated buyers with standardized performance specifications. Amazon Business and Alibaba channels aggregate fragmented demand.
- Wholesalers:Volume aggregation enables price competitiveness for mid-tier producers lacking direct sales infrastructure. Nordic specialty paper mills leverage wholesale relationships for European market access.
- Retail Stores:Consumer-facing outlets stock pressure-sensitive and craft-grade assortments. Limited shelf space constrains SKU breadth.
Distributors control industrial-grade volume flows. Online channels are gaining share fastest as procurement centralization eliminates intermediary layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural export surplus in paper gummed tape machinery and specialty kraft substrates, while the United States and China remain net importers of high-performance adhesive formulations. Nordic pulp mills supply backing materials across European converter networks, compressing lead times for regional manufacturers.
Germany
E-commerce fulfillment centers in Leipzig and Hamburg drive water-activated tape procurement ahead of VerpackG registry deadlines. The EU Green Deal mandates recyclable sealing solutions through extended producer responsibility frameworks. Stuttgart automotive suppliers specify reinforced grades for OEM tamper-evidence protocols in machinery shipments.
United States
EPA sustainable packaging guidelines influence procurement criteria for logistics operators seeking landfill diversion cost reductions. Third-party fulfillment networks balance capex constraints against automation timelines. Chicago and Dallas distribution hubs concentrate demand for high-speed case sealing equipment compatible with starch-based adhesives.
China
Domestic e-commerce platforms accelerate warehouse automation investments compatible with water-activation systems. The country's national packaging regulator enforces recyclability standards for shipping materials in cross-border trade corridors. Yangtze River Delta manufacturing clusters source kraft backing from regional specialty paper mills.
Netherlands
Rotterdam and Antwerp port-centric fulfillment centers convert dispenser fleets to meet EU Packaging and Packaging Waste Regulation reporting deadlines. National packaging registries track material flows across Benelux distribution networks. Eindhoven logistics technology providers integrate tape dispensing systems with automated case sealing lines.
France
CITEO eco-modulation fees penalize non-recyclable sealing solutions in national packaging compliance frameworks. Paris-region e-commerce operators centralize procurement decisions under sustainability mandates. Lyon corrugated converters prioritize certified recyclable streams for export shipments to EU member states.
Paper Gummed Tape Market Competitive Landscape
On the supply side, the industry is consolidating around integrated kraft paper producers and specialty adhesive formulators with captive coating capacity. Three strategic archetypes dominate: diversified materials conglomerates with tape as a packaging segment, regional converters leveraging Nordic pulp proximity, and equipment-integrated solution providers bundling dispensers with consumables. Competitive moves concentrate on backward integration into kraft paper sourcing and geographic expansion through distributor network acquisitions.
Among diversified materials specialists, 3M and Intertape Polymer Group exemplify scale-driven positioning across industrial-grade segments. Tesa SE occupies a position within the European adhesive formulation tier, leveraging proximity to German automotive and logistics clusters. These three anchors represent distinct competitive vectors: materials science depth, integrated North American supply chains, and automated application optimization respectively.
| Leading Market Players |
|---|
| Vibac Group |
| Berry Global |
| 3M |
| Holland Manufacturing |
| Papertec |
| Intertape Polymer Group |
| Tesa SE |
| Can-Do National Tape |
| Shurtape Technologies |
| Others |
Value Network & Pricing Analysis
Nordic pulp mill capacity expansions in Finland and Sweden are compressing lead times for kraft paper backing substrates, translating into downstream pricing leverage for integrated European tape converters serving German automotive and logistics clusters.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—Cradle-to-Cradle and EU Ecolabel tiers command 15-25% premiums—and volume scale under master supply agreements. Pricing pressure stems from starch adhesive input volatility as wheat and corn commodity cycles compress margins in standard grades. Micro-fulfillment operators exhibit highest price sensitivity due to constrained capex budgets, while consolidated e-commerce procurement teams at Amazon and Otto Group prioritize performance specifications over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts specialty adhesive formulation flows, forcing North American converters to qualify alternative suppliers. Geographic supply concentrates in Germany, Finland, and Sweden for kraft paper backing, with China and the United States as secondary sources. Raw material dependencies include Nordic softwood pulp, wheat/corn starch for adhesive modification, and fiberglass yarn for reinforced grades. Single-source vulnerability sits with legacy starch modification chemistry expertise concentrated in legacy paper industry regions. Distribution runs through industrial packaging specialists maintaining regional inventory positions for fulfillment center replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as pressure-sensitive plastic tape alternatives retain footholds in micro-fulfillment sites with limited automation budgets, threatening volume erosion in the craft and light retail packaging tier.
For Market Incumbents: Harden adhesive formulation expertise through captive R&D investment in starch modification chemistry, locking in polymer scientist talent pools against competition from food and pharmaceutical sectors. Secure backward integration into Nordic kraft paper sourcing to insulate margin structures from transatlantic shipping volatility. Prioritize Cradle-to-Cradle certification investment to defend supplier status with sustainability-focused retailers under EU Green Deal procurement mandates.
For New Entrants and Emerging Players: Build out heavy-goods manufacturing penetration in Stuttgart and Wolfsburg automotive clusters, where reinforced tape grades remain underdeployed against plastic strapping alternatives and command premium positioning. Target the direct-to-consumer craft segment through aesthetic-grade custom printed offerings, bypassing industrial distributor markups. Pursue equipment-integrated solution bundling—dispenser fleet leasing paired with consumable supply—to lower capital barriers for small fulfillment operators.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional converters with Nordic pulp proximity and captive coating capacity. Long-term viability hinges on regulatory tailwinds from extended producer responsibility frameworks hardening demand for recyclable sealing solutions. Acquisition target archetype: mid-tier producers with asset-light leasing models for coating and slitting equipment. Monitor conversion timelines for water-activated dispenser fleet deployment across Rotterdam and Antwerp fulfillment centers as inflection indicator for demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Paper Sourcing | Nordic pulp mill partnerships compress lead times and insulate margins from shipping volatility. |
| EU Ecolabel Certification Program | Verified sustainable sealing locks in supplier status with German retailers under VerpackG compliance. |
| Equipment Leasing Model Expansion | Asset-light dispenser fleet offerings lower entry barriers for small fulfillment operators deferring capex. |
| Reinforced Grade Capacity Addition | Fiberglass-yarn backing production captures premium positioning in Stuttgart automotive component shipping. |
| Starch Modification R&D Investment | Captive adhesive formulation expertise defends against polymer scientist talent competition from pharmaceutical sectors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with corrugated box procurement managers at German e-commerce fulfillment centers, coating equipment manufacturers in Eindhoven, and Nordic specialty paper mill technical directors contributing operational perspectives. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, German VerpackG registry filings, EPA sustainable packaging guidelines, customs trade data for kraft paper flows, and SEC 10-K disclosures from diversified materials conglomerates. Bottom-up demand modeling and top-down supply capacity assessments were triangulated to cross-verify volume and value estimates.
Calibration against historical adoption curves for water-activated tape in European logistics networks informed trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product type tier, application intensity, end-user consolidation level, and regional regulatory framework cluster. CAGRs were derived from trend extrapolation adjusted for policy implementation timelines and automation penetration rates. Industry-specific forecast inputs incorporated starch commodity price cycles, dispenser fleet conversion schedules, and EU circular economy certification adoption curves.
Practitioners should monitor VerpackG registry compliance deadlines and CITEO eco-modulation fee structures for early signals of demand acceleration or regulatory enforcement intensity shifts. Forecasts reflect documented assumptions about automation capex recovery timelines and adhesive formulation talent availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Painting Masking Tapes Market
Tapes
Packaging Tapes Market
Tapes
Hydrocolloid Tapes Market
Tapes
Washi Tapes Market
Tapes
Carton Sealing Tape Market
Tapes
Labels, Tapes and Films Market
Tapes
High Bond Tape Market
Tapes
Thermal Transfer Tapes Market
Tapes
Smart Card Tapes Market
Tapes
Moisture Barrier Tapes Market
Tapes
Carbon Tapes Market
Tapes
Pipe Marking Tape Market
Tapes
Security Tape Market
Tapes
Double Coated Film Tapes Market
Tapes
Strapping Tapes Market
Tapes
Wing Walk Tapes Market