
 Thermoplastic Polyurethane (TPU) Market | 2026-2036
Thermoplastic Polyurethane (TPU) Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Polyurethane (TPU) Market Analysis
High-performance TPU grades is reorganizing competitive dynamics as specifications tighten across automotive and medical end uses. Covestro AG leverages its European production network to sustain supply continuity for engineered film applications. Wanhua Chemical Group anchors volume leadership through backward integration into MDI feedstocks. BASF SE differentiates via specialty compounding capabilities that serve medical device OEMs with stringent biocompatibility requirements.
Thermoplastic polyurethane is a block copolymer synthesized from diisocyanates, polyols, and chain extenders, exhibiting Shore hardness ranging from 60A to 85D while retaining elasticity across temperature extremes from minus 40 to plus 120 degrees Celsius; manufacturers extrude, inject, or blow mold it into parts requiring abrasion resistance, oil resistance, and mechanical durability under cyclic loading. Polyester TPU dominates volume due to its cost-efficiency in industrial hose and conveyor belt applications, though bio-based TPU registers the fastest expansion as consumer goods brands mandate renewable content in footwear and packaging films. Polyether TPU commands premium positioning in medical tubing and underwater cable sheathing where hydrolytic stability determines service life.
The EPA oversees VOC emissions from TPU processing facilities in the United States, while REACH restricts certain phthalate plasticizers and isocyanate classifications across European supply chains, and China's MEE enforces dual carbon goals that press domestic producers toward lower-emission polymerization routes. These frameworks elevate compliance costs for commodity-grade suppliers while creating preferential market access for certified bio-based and high-performance product lines. Stakeholders must weigh feedstock provenance against certification premiums when allocating capacity across geographic manufacturing footprints.
Market Dynamics
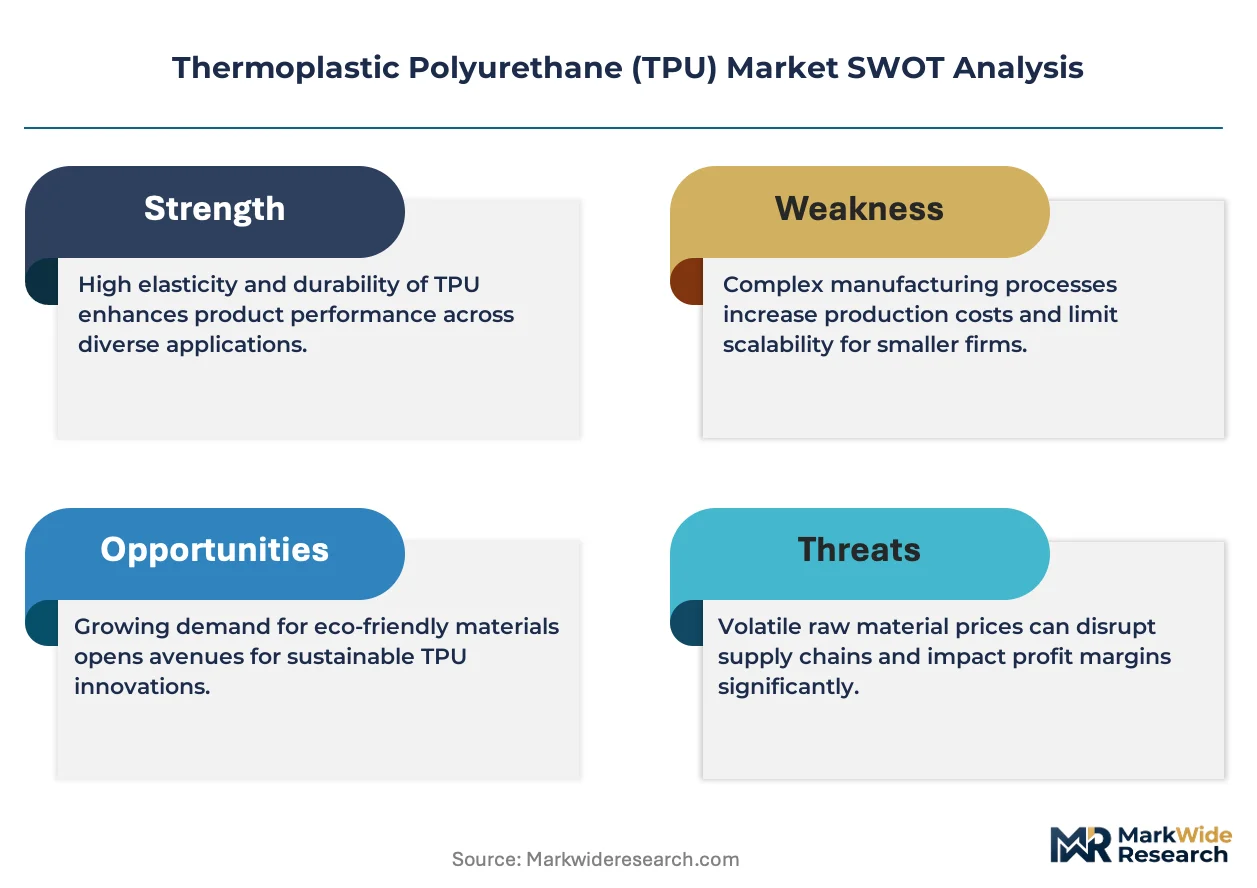
Automotive OEMs are mandating lighter chassis components to meet fleet efficiency targets, pulling high-performance TPU grades into structural applications previously served by metals and engineering plastics.
Growth Catalysts
- REACH compliance deadlines:European manufacturers are accelerating bio-based TPU formulation to preempt phthalate restrictions and isocyanate reclassifications.
- Medical tubing demand:Hydrolytic stability requirements in catheter and infusion set manufacturing are expanding polyether TPU volumes.
- China's dual carbon goals:Domestic producers are retooling polymerization routes to satisfy MEE emissions benchmarks and secure state procurement contracts.
Market Restraints
- MDI feedstock concentration:Three integrated chemical conglomerates control over 70% of Asian diisocyanate supply, creating margin squeeze during upstream volatility.
- Polyol cost exposure:Caprolactone and adipic acid prices track petrochemical indices with limited hedging instruments available to compounders.
- Performance ceiling in extreme heat:Standard polyester grades soften above 120°C, blocking entry into under-hood automotive applications where PPA and PEEK dominate.
Strategic Opportunities
- India's PLI scheme for textiles:Footwear and synthetic leather manufacturers qualify for production-linked incentives when sourcing certified renewable-content polymers.
- Closed-loop chemical recycling:Pyrolysis and glycolysis technologies are enabling post-industrial TPU reprocessing into virgin-equivalent feedstocks.
- 3D printing filament channels:Direct-to-printer distribution models bypass traditional distributor markups for small-batch industrial prototyping.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 and USP Class VI testing protocols extend medical grade qualification cycles to 18-24 months.
- Legacy extrusion asset retrofitting:Converting rigid PVC and TPO lines to TPU processing requires screw and die modifications that idle capacity during transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Polyurethane (TPU) Market |
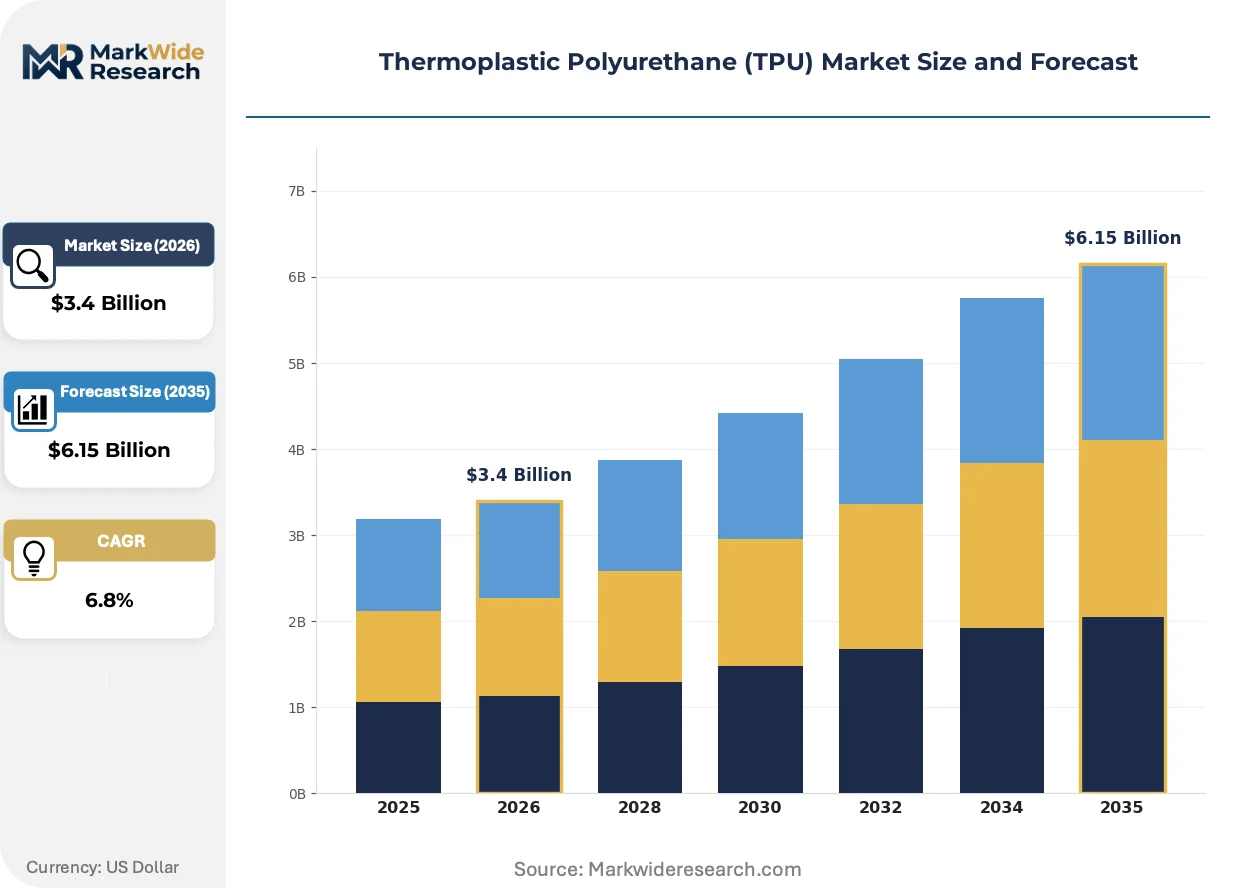
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester TPU, Polyether TPU, Bio-based TPU, High-Performance TPU Application: Footwear, Automotive Components, Film and Sheet, Adhesives Form: Granules, Films, Coatings, Elastomers End User: Consumer Goods, Automotive OEMs, Medical Devices, Industrial Applications |
| Companies Covered | Huntsman Corporation, Mitsui Chemicals, Inc., BASF SE, Miracll Chemicals Co., Ltd., COIM Group, Covestro AG, Wanhua Chemical Group Co., Ltd., American Polyfilm, Inc., The Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Polyurethane (TPU) Market Emerging Trajectories
Bio-based feedstock integration, regulatory chemistry reformulation, and direct digital manufacturing channels are restructuring how TPU compounds reach end-use specifications.
Aliphatic isocyanate formulations are supplanting aromatic MDI systems in optical film and automotive clearcoat applications where UV stability and color retention determine specification compliance. Covestro and specialty compounders in Germany and Japan are qualifying these grades for head-up display laminates and exterior trim. The shift is compressing commodity aromatic TPU margins while creating certification barriers for non-integrated suppliers lacking aliphatic production assets.
REACH Annex XIV authorization requirements for certain phthalate plasticizers are forcing reformulation across European supply chains by 2027. Compounders serving medical device and childcare product OEMs are accelerating migration to bio-based chain extenders and non-phthalate alternatives. German automotive suppliers report 12-18 month qualification cycles for replacement grades, compressing effective implementation windows.
Footwear brands are consolidating polymer procurement around direct mill relationships that bypass regional distributors. Nike, Adidas, and emerging direct-to-consumer labels in Germany and China are specifying renewable-content TPU at the factory level, disintermediating traditional compounder-distributor networks. This concentration is most visible in Fujian and Guangdong manufacturing clusters where 60% of global athletic shoe production occurs.
Thermoplastic Polyurethane (TPU) Market Segmentation
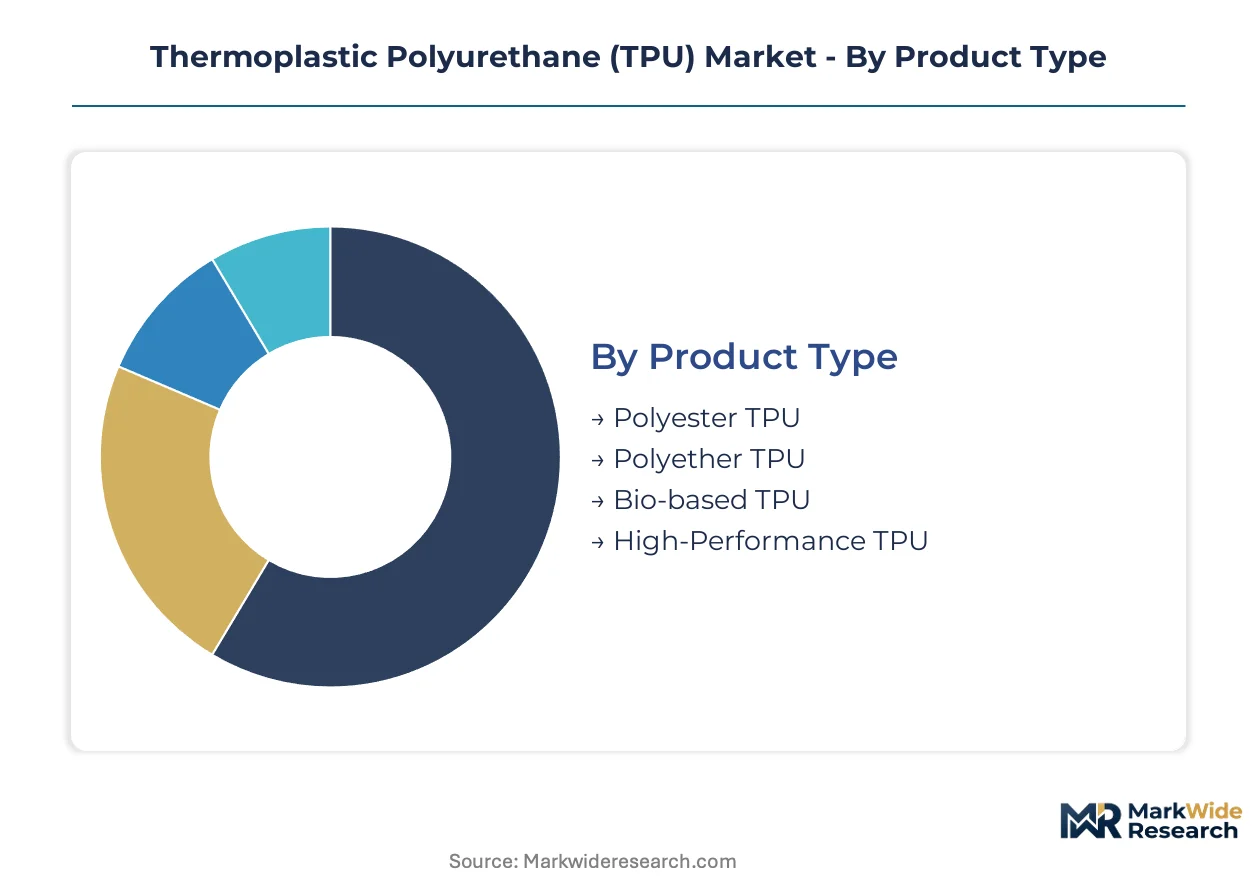
TPU segmentation reveals divergent margin structures across chemistries and conversion formats. Product type and application splits determine feedstock exposure, certification requirements, and pricing power in ways that reshape supplier strategy.
Product Type:
Margin pools concentrate in specialty grades where specification barriers protect pricing.
- Polyester TPU:Synthesized from adipic acid and MDI, this grade offers superior abrasion resistance and tensile strength for industrial belting and hydraulic hoses. Volume concentrates in China's Shandong and Jiangsu manufacturing corridors where compounders serve conveyor OEMs and mining equipment suppliers. REACH phthalate restrictions are compressing margins for commodity polyester suppliers lacking reformulation capabilities.
- Polyether TPU:Built on polytetramethylene ether glycol backbones, this chemistry delivers hydrolytic stability for medical catheters and underwater cable sheathing. Demand clusters in Germany's Baden-Württemberg medical device cluster and Japan's Kanagawa prefecture electronics belt. USP Class VI and ISO 10993 certification timelines create 18-24 month barriers that sustain premium positioning.
- Bio-based TPU:Incorporating renewable polyols from castor oil or sugarcane feedstocks, this segment serves footwear brands with Scope 3 emissions targets. Nike and Adidas direct mill procurement in Fujian province is bypassing traditional distributor networks.
- High-Performance TPU:Aliphatic isocyanate formulations target optical films and automotive clearcoats requiring UV stability. Covestro's European production network anchors supply for head-up display laminates.
The dominant share belongs to polyester TPU, while bio-based TPU is gaining share fastest.
Application:
Application splits track end-use durability requirements and regulatory exposure intensity.
- Footwear:Midsole injection and synthetic leather applications in athletic and safety shoes. Direct brand procurement from German and Chinese manufacturers is consolidating volume around certified renewable-content grades.
- Automotive Components:Cable sheathing, interior skins, and structural damping elements. OEM lightweighting mandates are pulling TPU into chassis applications previously served by metals and engineering plastics.
- Film and Sheet:Protective films for electronics, inflatable structures, and industrial membranes. Extrusion lines in South Korea's Gyeonggi province and Taiwan's Tainan science park serve display panel manufacturers.
- Adhesives:Hot-melt and reactive systems for textile lamination and automotive assembly. Formulators in Italy's Lombardy region specialize in solvent-free systems for EU VOC compliance.
Automotive components command the highest value per kilogram, though footwear is expanding most quickly.
Form:
Form factors determine conversion technology requirements and distributor channel structure.
- Granules:Standard pellet form for injection molding and extrusion. Compounders in the US Gulf Coast and Rotterdam-Antwerp corridor maintain bulk silo infrastructure for high-volume processors.
- Films:Calendered and blown films for lamination and surface protection. German and Japanese producers dominate optical-grade specifications with tight thickness tolerances.
- Coatings:Solvent-based and waterborne systems for textile and leather finishing. Italian formulators lead in fashion applications with rapid color-matching capabilities.
- Elastomers:Castable systems for rollers, wheels, and industrial parts. Machine builders in China's Zhejiang province integrate captive TPU casting for conveyor component manufacturing.
Granules retain the largest volume position, while films are climbing the fastest.
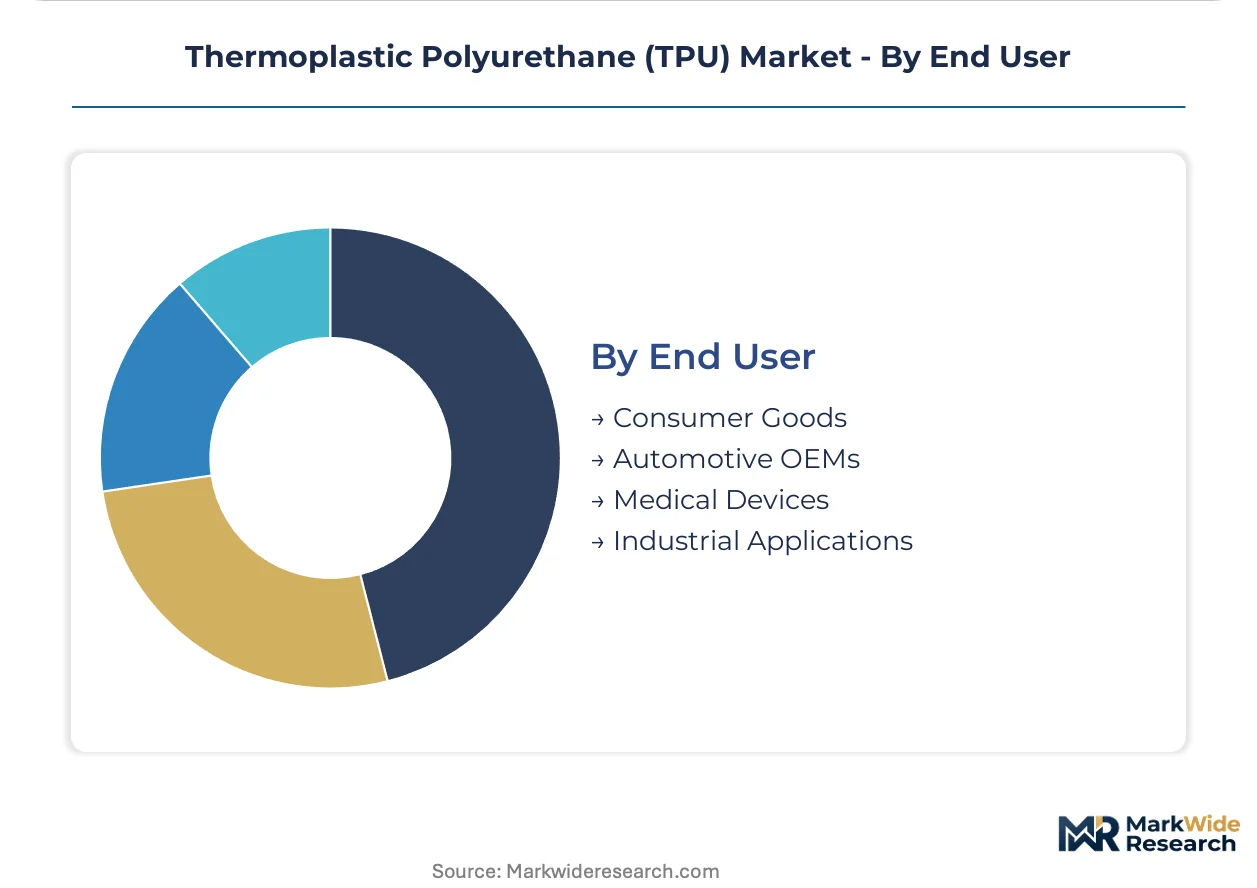
End User:
End user segmentation separates specification intensity from price sensitivity.
- Consumer Goods:Footwear, electronics accessories, and sporting equipment. Brand sustainability mandates are accelerating bio-based grade qualification cycles.
- Automotive OEMs:Tier-1 and Tier-2 suppliers with IATF 16949 quality requirements. German and Japanese OEMs specify aliphatic grades for exterior trim with 10-year color retention guarantees.
- Medical Devices:Catheter tubing, wound care films, and surgical instruments. FDA and EMA biocompatibility protocols extend qualification timelines and protect incumbent suppliers.
- Industrial Applications:Mining, oil and gas, and material handling equipment. Abrasion resistance specifications in hydraulic seals and conveyor belts favor polyester grades with cost-efficient supply chains.
Industrial applications absorb the greatest tonnage, though medical devices deliver the steepest margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's Fujian manufacturing clusters exhibit acute price sensitivity for footwear-grade material, while German automotive OEMs absorb substantial premiums for aliphatic grades with decade-long color warranties. This demand-elasticity divergence shapes supplier footprint decisions across major economies.
China
Footwear factories in Fujian and Guangdong provinces drive volume procurement of polyester grades for midsole injection, with Nike and Adidas mandating renewable-content thresholds at direct mill relationships. MEE enforces dual carbon benchmarks that pressure domestic producers toward lower-emission polymerization routes. Wanhua Chemical anchors supply through backward integration into MDI feedstocks at its Ningbo complex.
Germany
Automotive Tier-1 suppliers in Baden-Württemberg specify aliphatic TPU for exterior trim with stringent UV stability requirements, while medical device clusters demand USP Class VI certified polyether grades for catheter tubing. REACH Annex XIV phthalate restrictions force 12-18 month reformulation cycles across European supply chains. Covestro leverages its European production network to sustain supply continuity for engineered film applications.
United States
Industrial belting manufacturers in the Midwest and hydraulic hose producers along the Gulf Coast absorb commodity polyester volumes for mining and oilfield applications. EPA VOC emission standards elevate compliance costs for processing facilities in Texas and Louisiana. The Lubrizol Corporation maintains compounding operations serving medical device OEMs with biocompatibility requirements.
Japan
Electronics manufacturers in Kanagawa prefecture procure optical-grade films for display panel lamination, while underwater cable sheathing for subsea infrastructure pulls premium polyether volumes. METI industrial standards govern material specifications for telecommunications and energy infrastructure. Mitsui Chemicals occupies a position among domestic suppliers serving these precision-oriented segments.
India
Footwear and synthetic leather manufacturers in Tamil Nadu and Uttar Pradesh qualify for PLI scheme incentives when sourcing certified renewable-content polymers. BIS standards govern material specifications for consumer goods applications. Huntsman Corporation represents multinational presence through local distribution partnerships serving these emerging volume channels.
Thermoplastic Polyurethane (TPU) Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where integrated petrochemical conglomerates compete against specialty compounders with formulation expertise. The market consolidates around three strategic groupings: backward-integrated MDI producers capturing feedstock margin, European and Japanese specialists commanding premium grades, and regional compounders serving price-sensitive industrial applications. Dominant competitive moves include capacity expansion in Asia-Pacific manufacturing corridors and strategic partnerships between footwear brands and direct mill suppliers.
Among integrated chemical conglomerates, Wanhua Chemical Group Co., Ltd. exemplifies scale-driven positioning through captive MDI supply, while Covestro AG represents European technology leadership in aliphatic and high-performance grades. BASF SE anchors the specialty compounding tier with medical-grade certification capabilities. These three companies illustrate how supplier strategy diverges between feedstock control, specification barriers, and application-specific formulation expertise.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Mitsui Chemicals, Inc. |
| BASF SE |
| Miracll Chemicals Co., Ltd. |
| COIM Group |
| Covestro AG |
| Wanhua Chemical Group Co., Ltd. |
| American Polyfilm, Inc. |
| The Lubrizol Corporation |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day inventory cycles for MDI feedstocks concentrate pricing power among backward-integrated producers in China and Germany, while compounders without captive diisocyanate supply absorb margin volatility from spot polyol markets.
Pricing Analysis
After-sales technical service contracts for medical grade qualification support drive lifetime value beyond commodity resin sales. Three-tier pricing structure across premium, standard, and economy levels separates aliphatic optical grades from polyester industrial grades from bio-based footwear grades, with differentiation hinging on certification tier and volume scale. Pricing pressure stems from REACH phthalate restrictions forcing reformulation investments. Footwear manufacturers in Fujian province exhibit acute price sensitivity, while German automotive OEMs absorb substantial premiums for decade-long color warranties.
Supply Chain Analysis
China and Germany anchor global TPU production, with Ningbo and Leverkusen housing integrated MDI-to-polymer complexes that feed downstream compounders. Feedstock exposure centers on adipic acid, caprolactone, and polytetramethylene ether glycol from petrochemical indices with limited hedging instruments. Single-source vulnerability concentrates in Asian diisocyanate supply controlled by three integrated conglomerates. Distribution runs through direct mill relationships with footwear brands and regional distributors serving industrial processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service and certification support layers expand faster than base resin sales, creating service-attach opportunities for compounders with formulation expertise and regulatory navigation capabilities.
For Market Incumbents: Fortify supply continuity through backward integration into MDI feedstocks or long-term offtake agreements with integrated producers. Covestro and Wanhua Chemical demonstrate how European production networks and Ningbo complex scale respectively defend against feedstock disruption. Invest in aliphatic production assets before REACH Annex XIV deadlines eliminate commodity aromatic grade margins in medical and childcare applications. For New Entrants and Emerging Players: Anchor in India's PLI scheme for textiles by qualifying renewable-content TPU for footwear and synthetic leather manufacturers in Tamil Nadu. Bio-based grade penetration remains underdeveloped relative to Fujian and Guangdong volume concentration. Pursue direct mill relationships with emerging direct-to-consumer labels bypassing established distributor networks. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because specification barriers protect medical and optical grade margins while commodity polyester faces structural compression. Target compounders with ISO 10993 certification capabilities and established automotive OEM relationships. Monitor REACH authorization timelines as inflection indicators for aliphatic grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI | Wanhua Chemical's Ningbo complex secures feedstock margin and supply continuity for Asian footwear demand. |
| Aliphatic Grade Capacity Expansion | Covestro's European network captures automotive clearcoat specifications requiring UV stability and color retention. |
| Bio-based Feedstock Transition | Castor oil and sugarcane polyol adoption satisfies Nike and Adidas renewable-content mandates in Fujian mills. |
| Medical Grade Certification Investment | BASF's USP Class VI capabilities extend qualification timelines that protect incumbent supplier positioning. |
| Closed-loop Chemical Recycling | Pyrolysis and glycolysis technologies enable post-industrial TPU reprocessing into virgin-equivalent feedstocks. |
Methodological Framework
Operator-level perspectives from plant managers at integrated producers, procurement leads at automotive Tier-1 suppliers, technical R&D directors at specialty compounders, and channel partners in European distribution anchored the qualitative base. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH regulatory filings. Bottom-up volume estimates triangulated against top-down macroeconomic drivers.
Sensitivity analysis tested forecast robustness across feedstock price volatility scenarios and regulatory implementation timelines. The modeling framework segmented by grade tier, end-use industry, conversion format, and regional production hub. CAGRs derived from historical trajectory analysis and demand elasticity coefficients. Key inputs included automotive lightweighting content-per-vehicle trends and medical device tubing demand intensity.
Material uncertainties — MDI supply consolidation, REACH authorization delays, and bio-based feedstock cost parity timelines — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation and brand sustainability mandate adoption. Recalibration cycles align with material shifts in polymerization technology and certification standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Novolac Resins Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Polypropylene Copolymer Market
Polymers & Resins
Highly Reactive Polyisobutylene (HR-PIB) Market
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Europe Polyurethane Market
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
C5 Resin Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market