
 Thailand Flexible Plastic Packaging Market | 2026-2036
Thailand Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Flexible Plastic Packaging Market Insights
Market Context
A capital-intensity divergence between integrated resin producers and specialized converters is bifurcating competitive dynamics in Thailand's flexible packaging sector. SCG Packaging Public Company Limited leverages captive polyethylene supply from its upstream petrochemical operations to dominate industrial film volumes. Amcor plc sustains premium positioning through barrier technology leadership in retort pouches for Thai processed seafood exports. TPBI Public Company Limited anchors domestic market share via extensive blow-and-cast film capacity across its Samut Prakan and Rayong facilities.
Technical and Segment Structure
Thailand flexible plastic packaging encompasses laminated and coextruded films, typically 15-250 microns thick, manufactured through blown film extrusion, cast extrusion, or rotogravure printing processes to provide moisture, oxygen, and light barrier protection for perishable goods. Polyethylene formulations command the largest material share due to cost efficiency in mass-market bags and wraps, while polypropylene pouches generate superior margins in retort and microwaveable applications. Food Industry end-use demand outpaces other segments, driven by Thailand's position as a regional processed food production hub requiring extended shelf-life packaging for tropical climate distribution.
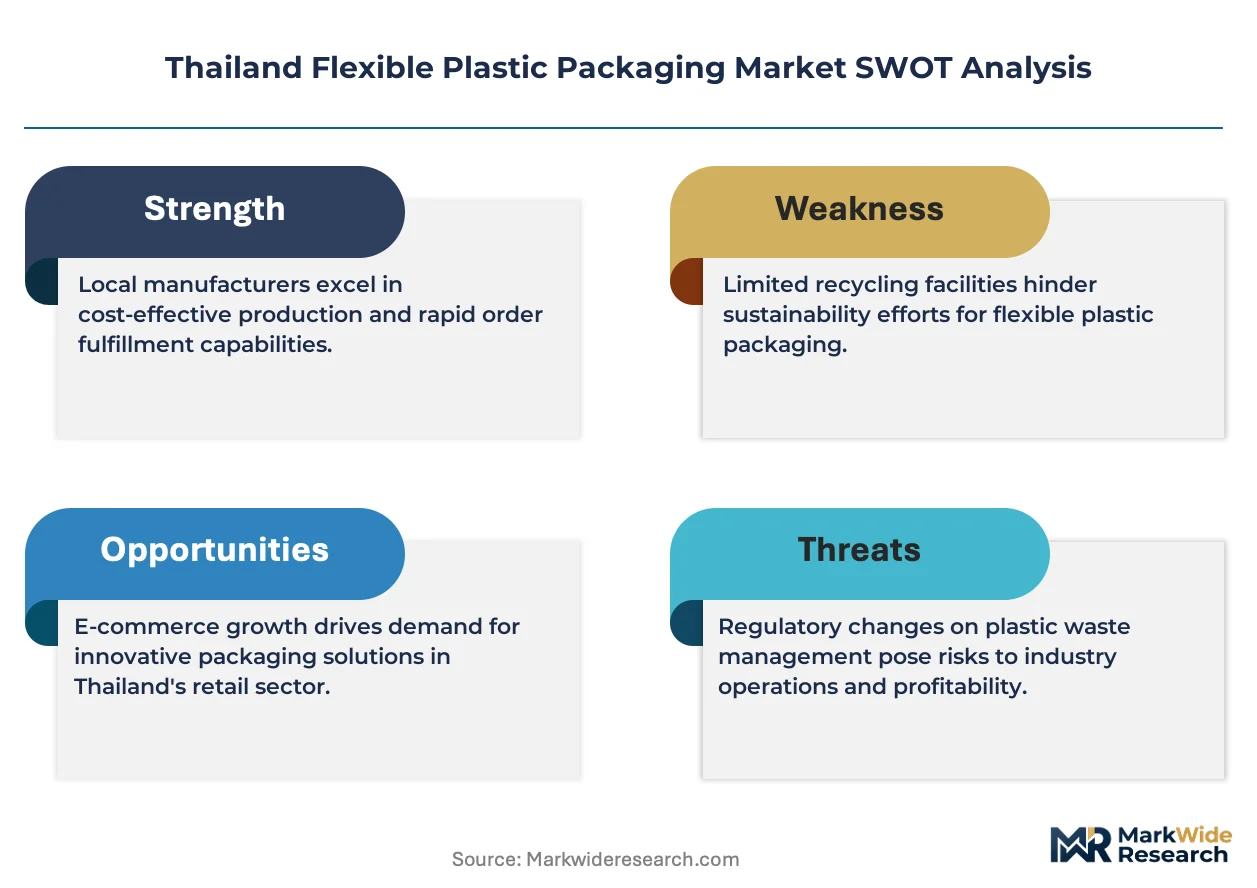
Regulatory Environment
Thailand's Ministry of Natural Resources and Environment enforces the Plastic Waste Management Roadmap, which mandates phased reductions in single-use plastics and incentivizes mono-material recyclable designs through tax preferences. The Thailand Industrial Standards Institute certifies food-contact compliance under TIS standards, while the Bio-Circular-Green economy policy channels investment toward bio-based feedstocks and compostable film pilot lines. Stakeholders must monitor enforcement timelines for extended producer responsibility schemes and calibrate material substitution strategies against actual recycling infrastructure buildout in Greater Bangkok and Eastern Seaboard provinces.
Market Dynamics
Thailand's flexible packaging sector is splitting between integrated petrochemical-backed converters and specialized barrier-film innovators, with the Ministry of Natural Resources and Environment's Plastic Waste Management Roadmap forcing rapid material substitution decisions.
Growth Catalysts
- Bio-Circular-Green economy incentives:Tax preferences for bio-based feedstocks and compostable film pilot lines are accelerating capital deployment toward mono-material recyclable structures in Samut Prakan and Rayong provinces.
- Processed seafood exports:Thai manufacturers serving Japanese and EU buyers require extended shelf-life retort pouches with oxygen barrier properties exceeding 0.1 cc/m²/day.
- Rayong-Chonburi industrial clustering:Co-location of resin production, film extrusion, and food processing plants within the Eastern Economic Corridor reduces logistics costs and enables just-in-time packaging supply.
Market Restraints
- Feedstock price volatility:Naphtha-derived polyethylene margins swing with Singapore refining spreads, compressing converter profitability during crude oil spikes.
- Recycling infrastructure gaps:Post-consumer flexible film collection rates in Greater Bangkok remain below mechanical recycling thresholds, limiting circular economy claims.
- High-barrier technical ceiling:Multi-layer structures incorporating EVOH or metallized films cannot currently achieve full mono-material recyclability without performance trade-offs in tropical humidity.
Strategic Opportunities
- Isaan region underpenetration:Food processors in Khon Kaen and Udon Thani still rely on rigid packaging, creating conversion potential for flexible formats in agricultural product distribution.
- Extended producer responsibility schemes:Pending Ministry mandates will reward early movers designing for recyclability with reduced compliance fees and preferential retailer placement.
- Digital printing convergence:HP Indigo and Xeikon press installations enable short-run customized pouches for craft food brands, collapsing minimum order quantities from 50,000 to 5,000 units.
Industry Challenges
- Mono-material re-engineering expertise:Converter workforce lacks polymer science depth to reformulate sealant and barrier layers without external technical partnerships.
- TIS 656 certification timelines:Food-contact compliance testing for new bio-based films extends 8-12 months, delaying commercial launches behind competitor announcements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Flexible Plastic Packaging Market |
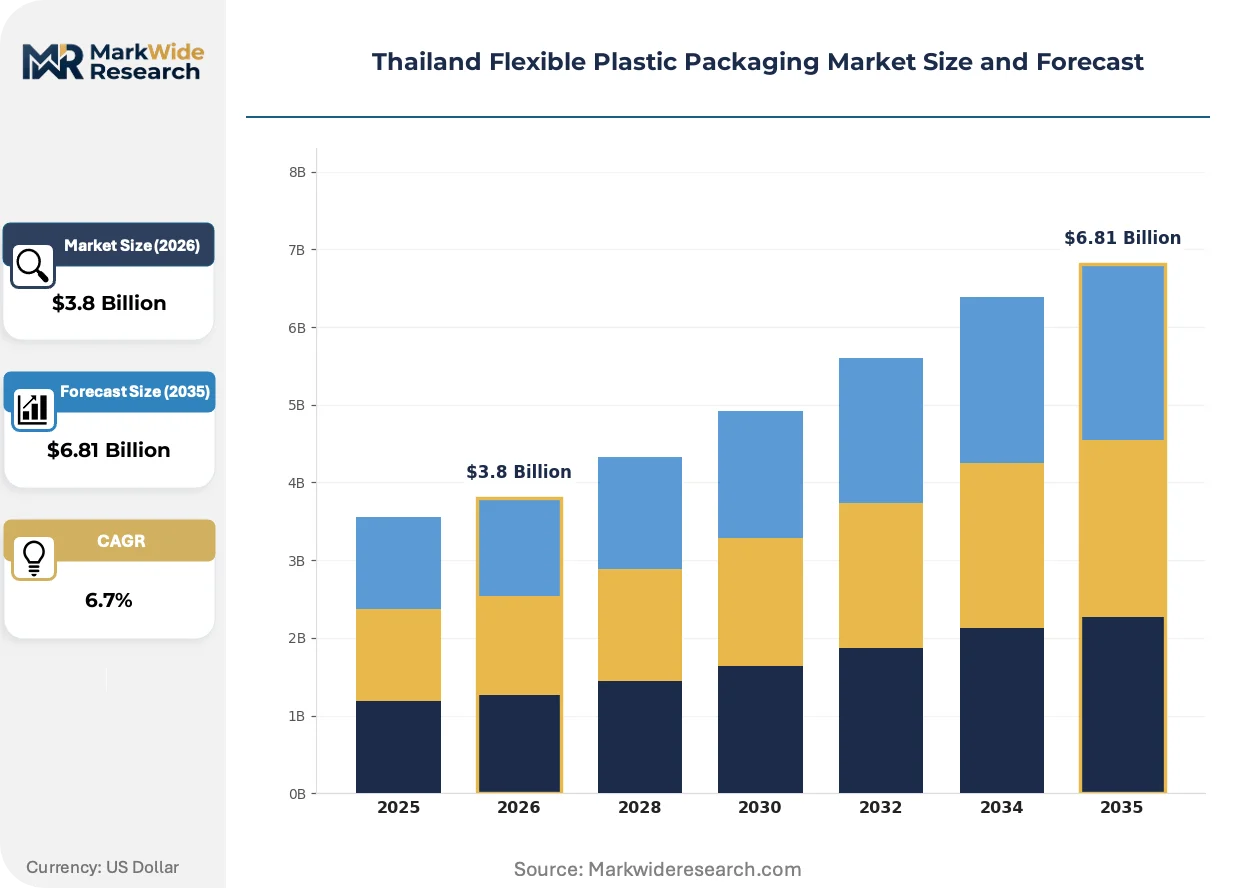
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Wraps Material: Polyethylene, Polypropylene, PVC, PET End User: Food Industry, Beverage Industry, Personal Care, Household Products Application: Retail Packaging, Industrial Packaging, Medical Packaging, Agriculture |
| Companies Covered | Prepack Thailand Co. Ltd., SCG Packaging Public Company Limited, Amcor plc, Huhtamaki Oyj, Sealed Air Corporation, TPBI Public Company Limited, Mondi Plc, Thai Plaspac, PONGSILP PLASTIC CO., LTD., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Flexible Plastic Packaging Market Trends and Innovations
Digitalization of pre-press workflows and barrier coating chemistry are compressing development cycles for Thai converters serving export markets with stringent shelf-life requirements.
Water-based barrier coatings are replacing metallized films in snack and confectionery applications. Bangkok-based converters serving Central Retail and CP All are trialing SiOx-coated PET structures. This technology is miniaturizing the performance gap between conventional multi-layer laminates and recyclable mono-material alternatives.
Thailand's Plastic Waste Management Roadmap mandates 100% recyclable packaging for specific single-use categories by 2027. The Ministry of Natural Resources and Environment enforces phase-out schedules through provincial governor directives. Processed seafood exporters to the EU are pre-emptively adopting TIS-certified mono-material pouches to avoid future customs documentation complications.
Brand owners in the Chao Phraya Basin are consolidating supplier panels from twelve converters to three strategic partners. Central Group and Siam Makro now require annual sustainability scorecards with third-party verified recycled content claims. This concentration is most visible in the frozen food vertical, where buyers negotiate three-year framework agreements locking in volume commitments and technical co-development roadmaps.
Thailand Flexible Plastic Packaging Market Segmentation
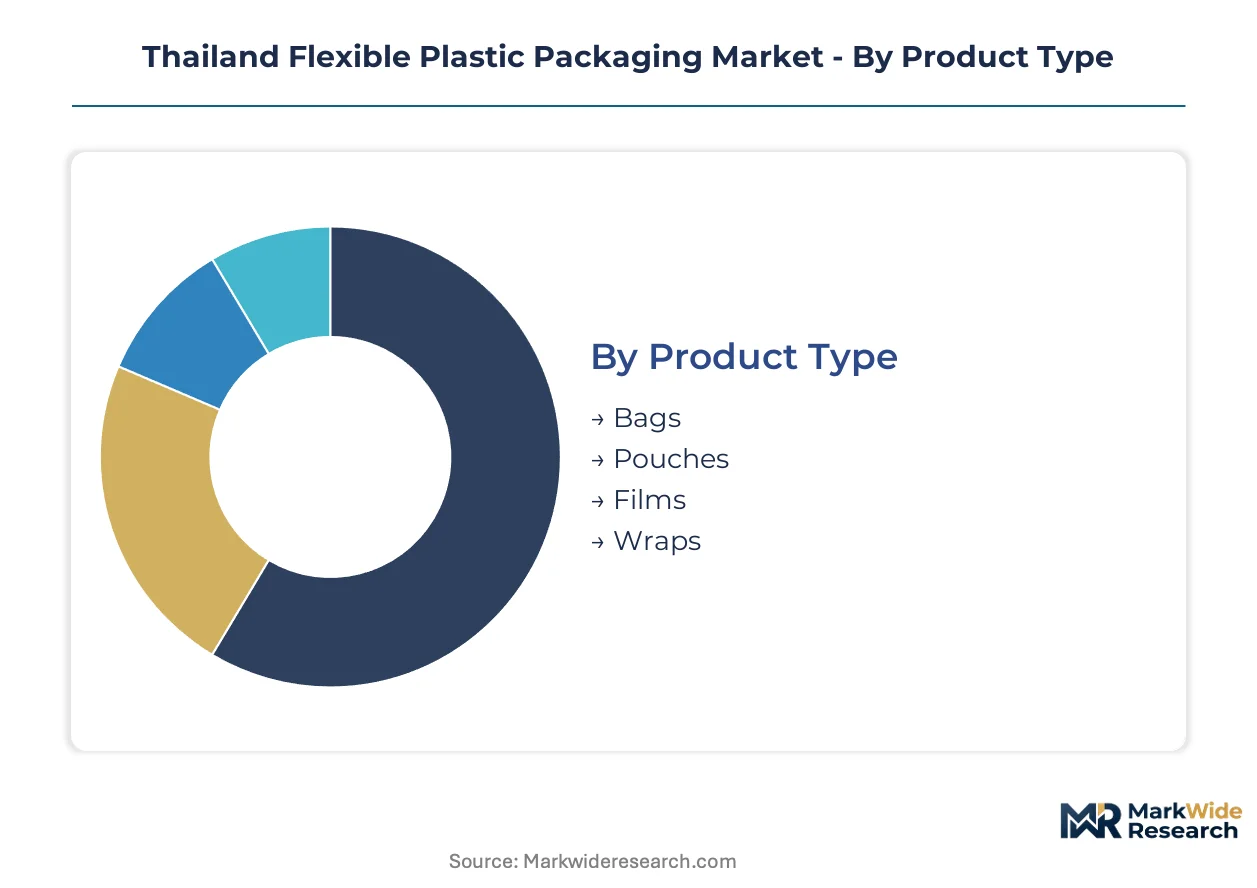
Thailand's flexible packaging segmentation reveals how regulatory pressure and export compliance are fragmenting demand across material grades and barrier specifications. Each dimension carries distinct certification burdens and supply chain implications for converters operating within the Eastern Economic Corridor.
Product Type:
The Ministry of Natural Resources and Environment's Plastic Waste Management Roadmap applies differentiated phase-out timelines across product formats, with single-use bags facing earlier compliance deadlines than industrial films.
- Pouches:High-barrier laminated structures, 80-250 microns, incorporate EVOH or metallized layers for oxygen transmission rates below 0.5 cc/m²/day. Processed seafood exporters in Samut Prakan and Rayong specify retort-capable pouches for Japanese retail chains. The Thailand Industrial Standards Institute's TIS 656 certification timeline of 8-12 months creates qualification barriers for new entrants.
- Films:Cast and blown extrusion outputs, 15-150 microns, dominate agricultural mulch and industrial wrapping applications. Chonburi-based converters supply stretch film to automotive component plants within the Eastern Seaboard industrial zone. Mono-material PE formulations are displacing multi-layer alternatives as Extended Producer Responsibility schemes approach implementation.
- Bags:Standard gauge polyethylene sacks for commodity bulk handling. Rice millers in the Central Plains prefer 25kg woven-laminated bags with moisture barriers for tropical storage.
- Wraps:Cling film and stretch wrap for food service and logistics bundling. Bangkok hospitality distributors source PVC and PE wraps under centralized procurement contracts with sustainability scorecard requirements.
Established volume favors films; emerging adoption favors pouches.
Material:
Cost tier stratification separates mass-market commodity grades from specialty barrier resins, with bio-based feedstocks commanding premium positioning under Bio-Circular-Green economy tax incentives.
- Polyethylene:LDPE and LLDPE formulations capture the largest volume share through cost efficiency in bags, wraps, and industrial films. SCG Chemicals' captive naphtha-derived supply stabilizes input costs for integrated converters. The material's compatibility with mechanical recycling infrastructure in Greater Bangkok supports circular economy claims.
- Polypropylene:BOPP and cast PP films deliver superior heat resistance for retort and microwaveable applications. Margins exceed polyethylene by 15-25% in premium processed food segments. TPBI Public Company's Rayong cast film lines supply retort pouch substrates to Bangkok-based laminators.
- PET:SiOx-coated and metallized polyester structures provide transparent barrier alternatives to aluminum laminates. Central Retail's private label snacks are transitioning to recyclable mono-material PET pouches.
- PVC:Cling film and blister pack applications, declining share due to regulatory scrutiny and substitution by PE alternatives in food contact.
Polyethylene dominates current tonnage; polypropylene captures expanding share in premium export packaging.
End User:
Application maturity varies sharply across customer verticals, with food and beverage processors driving technical specification intensity while personal care and household segments prioritize cost minimization.
- Food Industry:The dominant demand concentration, spanning frozen seafood, ready-to-eat meals, snack foods, and agricultural produce. Thai processors serving EU and Japanese buyers require extended shelf-life formats with humidity resistance for tropical distribution. The sector's conversion to flexible formats is accelerating in Khon Kaen and Udon Thani as cold chain infrastructure penetrates the Isaan region.
- Beverage Industry:Stand-up pouches and bag-in-box formats for juices, dairy, and alcoholic drinks. Aseptic filling compatibility demands specialized laminate structures with ethylene vinyl alcohol barrier layers.
- Personal Care:Sachets and pillow packs for shampoo, conditioner, and skincare samples. 7-Eleven Thailand's single-serve format requirements drive high-volume, low-margin production.
- Household Products:Detergent pods, cleaning wipes, and air freshener refills. Flexible formats are displacing rigid bottles in concentrated product segments.
Food Industry anchors installed capacity; Beverage Industry offers the steepest expansion trajectory as aseptic pouch filling spreads beyond dairy.
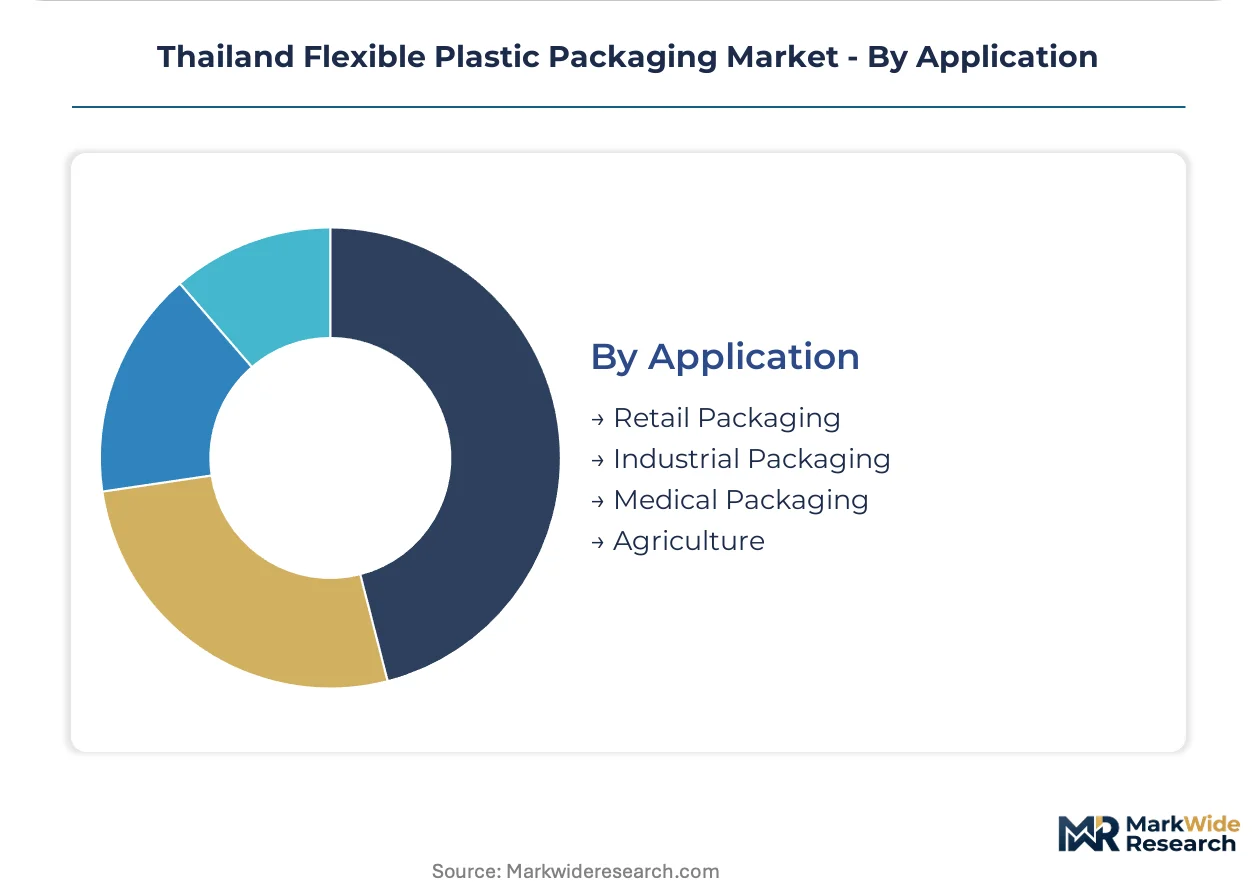
Application:
Customer procurement scale and technical sophistication diverge between fragmented retail channels and concentrated industrial buyers, reshaping converter sales organization structures.
- Retail Packaging:Branded and private label formats for supermarkets, convenience stores, and e-commerce fulfillment. Central Group and Siam Makro's supplier consolidation from twelve converters to three strategic partners is compressing margins while extending contract durations. Digital printing adoption enables short-run customization for craft food brands.
- Industrial Packaging:Heavy-duty sacks, stretch film, and protective wrapping for manufacturing and logistics. Rayong-Chonburi clustering enables just-in-time supply to automotive and electronics plants.
- Medical Packaging:Sterile barrier systems for pharmaceuticals and medical devices. Sterilization compatibility requirements limit qualified supplier pools.
- Agriculture:Mulch films, silage bags, and crop protection netting. Khon Kaen processors are converting from rigid crates to flexible formats for vegetable distribution.
Retail Packaging commands the widest product breadth; Industrial Packaging offers the most predictable volume commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Thailand's sub-regions, with Bangkok-based exporters absorbing premium pricing for barrier-certified formats while Isaan agricultural processors remain highly price-sensitive to base resin fluctuations.
Bangkok Metropolitan Region
Central Retail and CP All headquarters drive specification intensity for private-label packaging. The Ministry of Natural Resources and Environment enforces Plastic Waste Management Roadmap phase-outs through provincial governor directives. Samut Prakan hosts TPBI Public Company's blow-and-cast film capacity serving just-in-time orders from frozen food exporters.
Eastern Economic Corridor
Rayong and Chonburi industrial zones concentrate processed seafood manufacturers requiring retort pouches with oxygen barriers below 0.5 cc/m²/day. Bio-Circular-Green economy tax incentives accelerate mono-material pilot line deployment. SCG Packaging leverages captive polyethylene supply from adjacent petrochemical complexes to compress converter margins.
Central Plains
Rice millers and tapioca processors generate volume demand for 25kg woven-laminated bulk bags with tropical moisture protection. TIS 656 certification requirements extend 8-12 months for new bio-based film entrants. Ayutthaya and Suphan Buri host mid-tier converters supplying commodity agricultural packaging under annual procurement cycles.
Isaan Region
Food processors in Khon Kaen and Udon Thani rely predominantly on rigid crates, creating conversion potential as cold chain infrastructure penetrates agricultural distribution. Provincial industrial promotion zones offer land cost advantages for flexible film extrusion investment. Local converters lack technical depth for high-barrier re-engineering without Bangkok-based technical partnerships.
Southern Seaboard
Rubber and palm oil processors generate industrial film demand for export logistics bundling. Songkhla and Surat Thani ports enable direct shipment to Malaysian and Indonesian buyers. Regional converters compete primarily on freight cost minimization rather than barrier technology differentiation.
Thailand Flexible Plastic Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with SCG Packaging's captive resin supply creating cost advantages that mid-scale converters cannot replicate without external feedstock partnerships. The market separates into three archetypes: petrochemical-backed integrated producers, multinational barrier technology licensors, and domestic volume-focused extruders. Competitive moves concentrate on supplier panel consolidation by retail buyers and rapid mono-material re-engineering to preempt extended producer responsibility compliance deadlines.
Within the integrated tier, SCG Packaging Public Company Limited exemplifies upstream-backed market presence through its polyethylene supply chain control. Amcor plc and Huhtamaki Oyj occupy positions as multinational technology anchors, representing barrier innovation archetypes that Thai exporters reference for Japanese and EU retail compliance. TPBI Public Company Limited anchors the domestic specialist tier, with its Samut Prakan and Rayong facilities exemplifying scale-driven conversion capacity serving Bangkok-based food processors.
| Leading Market Players |
|---|
| Prepack Thailand Co. Ltd. |
| SCG Packaging Public Company Limited |
| Amcor plc |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| TPBI Public Company Limited |
| Mondi Plc |
| Thai Plaspac |
| PONGSILP PLASTIC CO., LTD. |
| Others |
Pricing and Supply Chain Analysis
Mono-material PE substitution for multi-layer laminates simultaneously redraws procurement geography toward Rayong resin complexes and compresses margin premiums previously captured by EVOH barrier specialists. Bangkok-based converters now face pricing discipline from integrated petrochemical-backed competitors while scrambling to recertify structures under Thailand's Plastic Waste Management Roadmap timelines.
Pricing Analysis
After-sales technical service contracts and barrier re-engineering support drive lifetime value capture beyond unit film sales. Three-tier pricing structure across premium certified, standard industrial, and economy commodity levels stratifies the market. Cost compression in standard-grade PE films intensifies because SCG Packaging's captive naphtha supply anchors baseline pricing. Agricultural processors in the Central Plains exhibit highest price sensitivity; Japanese-export seafood packers absorb premium barrier certification costs without volume elasticity.
Supply Chain Analysis
Strait of Malacca transit risk concentrates feedstock vulnerability for Thai converters drawing naphtha-derived resins from Singapore refining hubs. Supply geography centers on Thailand's Eastern Economic Corridor, South Korean barrier film technology licensors, and Chinese equipment manufacturers. Raw material dependencies include polyethylene resins, EVOH barrier polymers, and metallized film substrates. Single-source vulnerability sits with Japanese EVOH suppliers for oxygen barrier specifications. Distribution runs through just-in-time networks serving Rayong-Chonburi food processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's flexible packaging sector fragments into specialist niches as retail buyer consolidation from twelve suppliers to three strategic partners creates white-space opportunities for targeted entrants. This demand-side supplier panel compression generates service gaps that nimble converters can exploit.
For Market Incumbents: Consolidate barrier technology partnerships and backward integration into bio-based feedstock certification to preempt emerging mono-material specialists. Lock in three-year framework agreements with Central Group and Siam Makro before Extended Producer Responsibility schemes alter compliance economics. Prioritize TIS 656 pre-certification investments to compress 8-12 month approval windows for new bio-based structures. For New Entrants and Emerging Players: Digital printing service gaps in short-run craft food packaging offer immediate white-space penetration. Target Khon Kaen and Udon Thani agricultural processors converting from rigid crates to flexible formats as cold chain infrastructure spreads through Isaan. Deploy HP Indigo press capacity with 5,000-unit minimum order thresholds to bypass incumbent 50,000-unit economies of scale. For Investors and Strategic Acquirers: Thailand's Plastic Waste Management Roadmap 2027 compliance deadlines reshape the acquisition landscape toward mono-material-ready converters with pilot line validation. Five-to-ten-year viability favors specialists with polymer science depth to reformulate sealant layers without external partnerships. Watch for Ministry of Natural Resources and Environment enforcement signal acceleration in provincial governor directives as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Pilot Line Deployment | Accelerates compliance with Thailand's Plastic Waste Management Roadmap recyclable packaging mandates. |
| Digital Printing Press Installation | Enables 5,000-unit minimum orders for craft food brands collapsing incumbent scale advantages. |
| TIS 656 Certification Pre-Investment | Compresses 8-12 month food-contact approval timelines ahead of competitor launches. |
| Extended Producer Responsibility Readiness | Positions converters for reduced compliance fees and preferential retailer placement under pending schemes. |
| Rayong-Chonburi Capacity Expansion | Captures just-in-time supply synergies with Eastern Economic Corridor seafood exporters. |
Research Methodology
Cross-validation between Ministry of Natural Resources and Environment regulatory filings and Eastern Economic Corridor industrial zone investment records anchors the qualitative findings. Primary interviews with plant managers at Samut Prakan and Rayong converters, procurement leads at Central Retail and CP All, barrier film R&D directors, and logistics coordinators at Chonburi distribution hubs combined with secondary validation from Thailand Industrial Standards Institute certification databases, customs trade data, and SEC filings from listed packaging firms. Bottom-up capacity aggregation and top-down demand triangulation from food processing export statistics ensured analytical consistency.
Sensitivity analysis across feedstock price volatility scenarios and regulatory enforcement timing variations stress-tested projection robustness. Segmentation dimensions modeled include product type, material grade, end-use vertical, and geographic production cluster across the analysis window. CAGRs derived from historical volume trajectories adjusted for Bio-Circular-Green economy incentive impacts and mono-material substitution elasticities. Industry-specific forecast inputs incorporated naphtha refining spread correlations and TIS certification pipeline backlogs.
Forecasts assume regulatory continuity in Thailand's Plastic Waste Management Roadmap phase-out schedules; material policy acceleration or delay would require re-modeling. Specific risk factors include EVOH supply disruption from Japanese specialty resin producers and mechanical recycling infrastructure buildout shortfalls in Greater Bangkok. Practitioners should keep alternative scenarios live as Ministry enforcement intensity and provincial governor directive patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
China Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
North America Flexible Packaging Market
Flexible Packaging
GCC Flexible Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Flexible Lid Stock Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Stretch Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market