
 China Flexible Plastic Packaging Market | 2026-2036
China Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Flexible Plastic Packaging Market Insights
Market Context
Capital-intensity divergence between integrated film producers and regional converters is reorganizing competitive tiers across China's flexible packaging sector. Qingdao Tongli Packaging leverages captive blown-film capacity to control resin throughput costs across northern China. YLTPACK anchors its position through specialized pouch-forming lines serving multinational food brands. Jindong Packaging competes on narrow-web flexographic printing for mid-tier beverage labels.
Technical Definition and Segments
China Flexible Plastic Packaging refers to pliable polymer-based containment systems—typically under 250 microns in thickness—manufactured through extrusion, lamination, or coextrusion processes for product protection, shelf-life extension, and logistical handling. Polyethylene formulations dominate volume throughput due to cost-efficient sealing properties and compatibility with vertical form-fill-seal equipment. Pouches represent the fastest-expanding product type as single-serve and retort-ready formats displace rigid alternatives in food and personal care. Polypropylene films retain margin concentration in healthcare blister and sterilizable applications where clarity and barrier performance command specification premiums.
Regulatory Environment
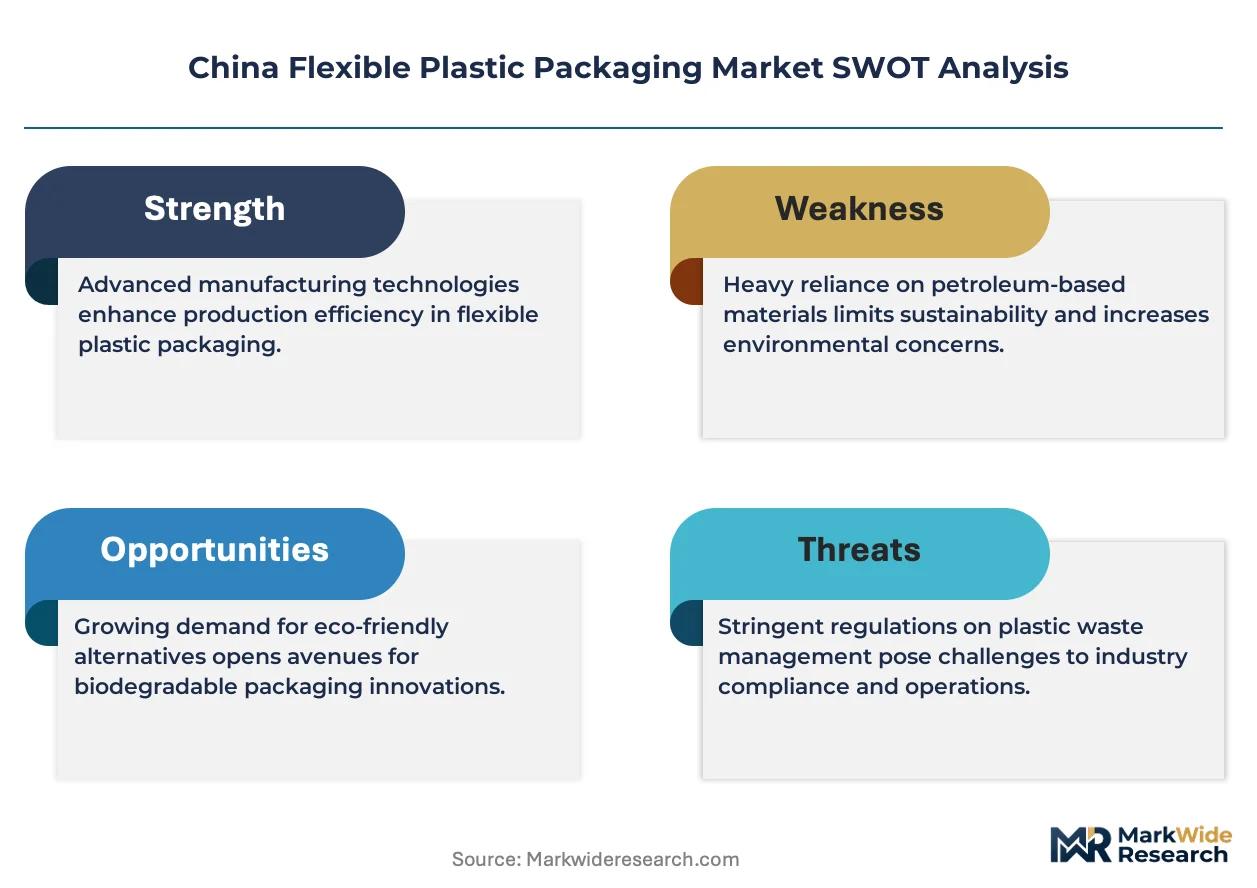
SAMR enforces GB standards governing food-contact migration limits and material traceability, while MEE implements dual carbon goals that restrict virgin resin intensity in provincial manufacturing permits. MEE emissions audits and GB 4806 series compliance are reshaping converter capex toward recycled-content and mono-material structures. Stakeholders must monitor provincial MEE enforcement variance and SAMR labeling rule revisions to anticipate compliance cost redistribution across the value chain.
Market Dynamics
MEE dual carbon goals are compressing virgin resin throughput across Jiangsu and Zhejiang provinces, forcing converters toward mono-material redesigns and recycled-content verification systems that alter competitive economics.
Growth Catalysts
- Retort pouch demand:Food manufacturers in the Yangtze River Delta are expanding single-serve and shelf-stable formats, pulling specialized barrier film capacity toward Shanghai.
- GB 4806 compliance infrastructure:SAMR migration-limit enforcement is creating certified-supplier premiums for converters with in-house testing laboratories.
- Blown-film automation:Seven-layer coextrusion lines are reducing gauge tolerance variance, enabling thinner specifications without seal-strength degradation.
Market Restraints
- Resin import dependency:Polyethylene feedstock concentration in Middle Eastern and US Gulf supply nodes exposes margin compression during freight rate spikes.
- Recyclate quality inconsistency:Post-consumer PE stream contamination rates in domestic collection systems limit food-contact application scalability.
- Mono-material performance gaps:Oxygen barrier specifications for retort applications remain unmet by single-substrate alternatives to PET/PA laminates.
Strategic Opportunities
- Western China penetration:Sichuan and Chongqing beverage processors lack local high-barrier pouch supply, creating logistics-cost arbitrage for qualified entrants.
- Chemical recycling integration:Pyrolysis-derived resin qualifies for MEE carbon-intensity reductions while bypassing mechanical recyclate quality constraints.
- Digital print-on-demand:HP Indigo and Fujifilm inkjet systems enable SKU proliferation without plate costs, matching private-label retailer velocity requirements.
Industry Challenges
- Migration testing bottlenecks:SAMR-accredited laboratory capacity constraints extend new product qualification timelines by four to eight weeks.
- Legacy VFFS retrofit complexity:Mono-material sealant layers require jaw temperature and pressure recalibration that halts production lines during changeover.
- Recycled-content traceability:Mass-balance accounting systems lack standardized verification protocols, creating audit preparation overhead for export shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Flexible Plastic Packaging Market |
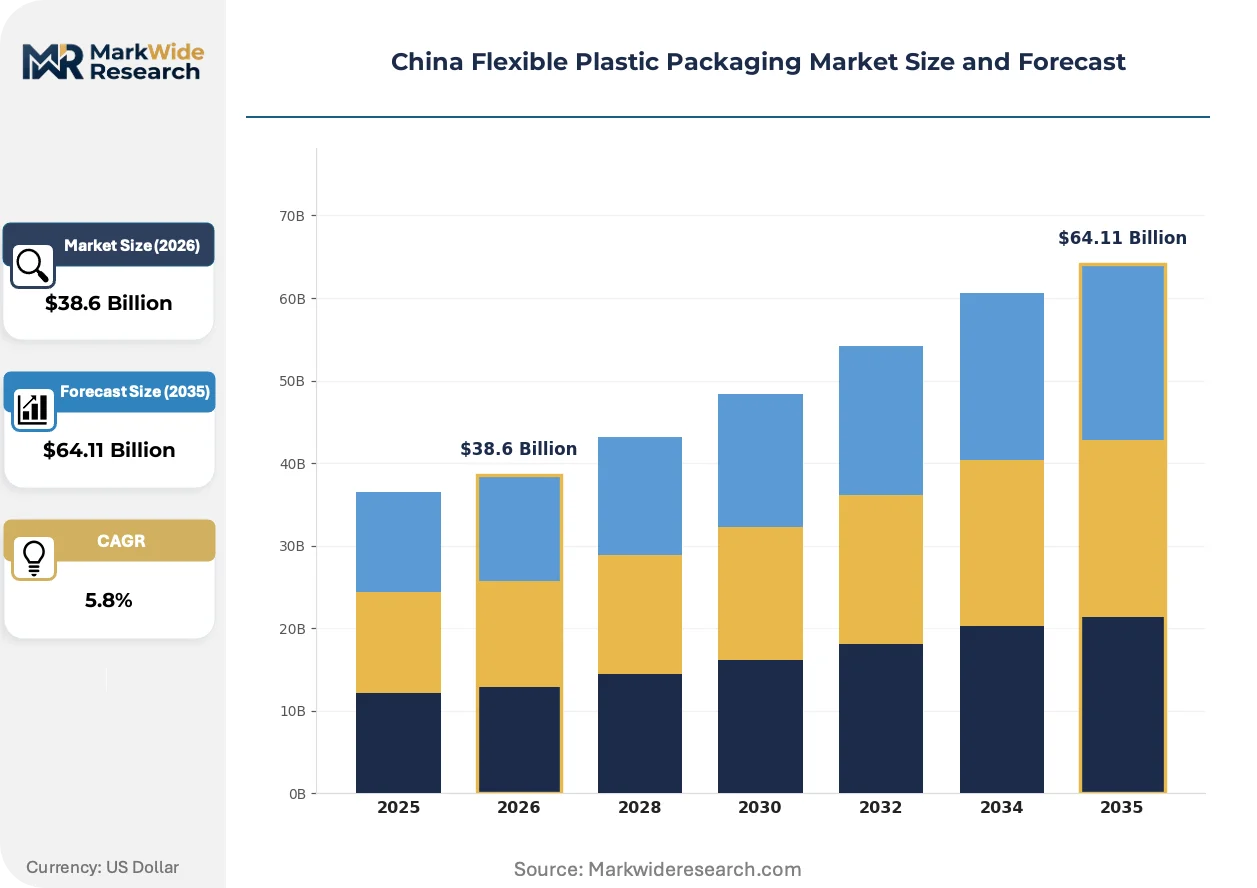
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll Stock, Pouches, Bags, Films Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester End User: Food, Beverage, Healthcare, Personal Care Application: Packaging, Printing, Labeling, Wrapping |
| Companies Covered | Biopouches, Qingdao Tongli Packaging, YLTPACK, Jindong Packaging, Xiongxian Chengtai, LD PACK, Logos Pack, Earthycores, Sunkey Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Flexible Plastic Packaging Market Trends and Innovations
Material science advances and regulatory carbon accounting are converging to redefine specification standards across China's converter base, with automation and digitalization compressing traditional equipment replacement cycles.
Mono-material polyethylene structures are fragmenting the laminated film segment by enabling full-polyolefin pouch designs that qualify for MEE recycling-stream targets. Multinational food brands operating in Shanghai and Suzhou are accelerating qualification timelines for these specifications. The shift is compressing demand for nylon and EVOH barrier layers while expanding blown-film capacity requirements for high-stiffness PE grades.
MEE provincial emissions audits are tightening manufacturing permit renewals across Jiangsu, forcing film producers to document carbon intensity per ton of output. Converters with captive renewable energy contracts or chemical recycling feedstock agreements are securing preferential permit treatment. Healthcare and infant nutrition segments are most exposed due to their reliance on energy-intensive multi-step lamination processes.
Brand-owner sustainability scorecards are altering supplier selection criteria beyond unit cost, with recycled-content percentage and carbon footprint disclosure now weighted in procurement evaluations. Domestic dairy and snack processors are consolidating vendor lists to favor converters with integrated recycling partnerships. This pattern is most pronounced among buyers headquartered in Guangdong and Fujian provinces with export market exposure.
China Flexible Plastic Packaging Market Segmentation
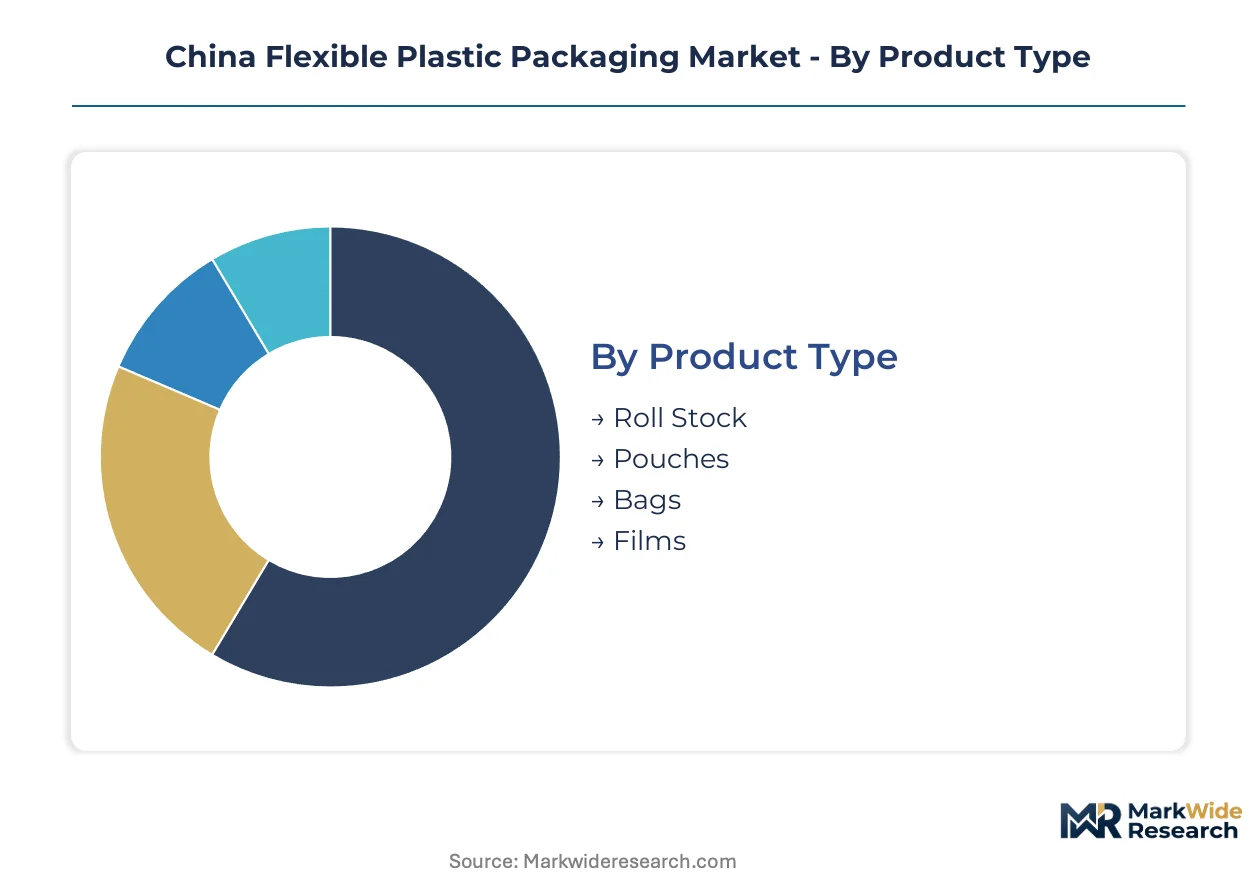
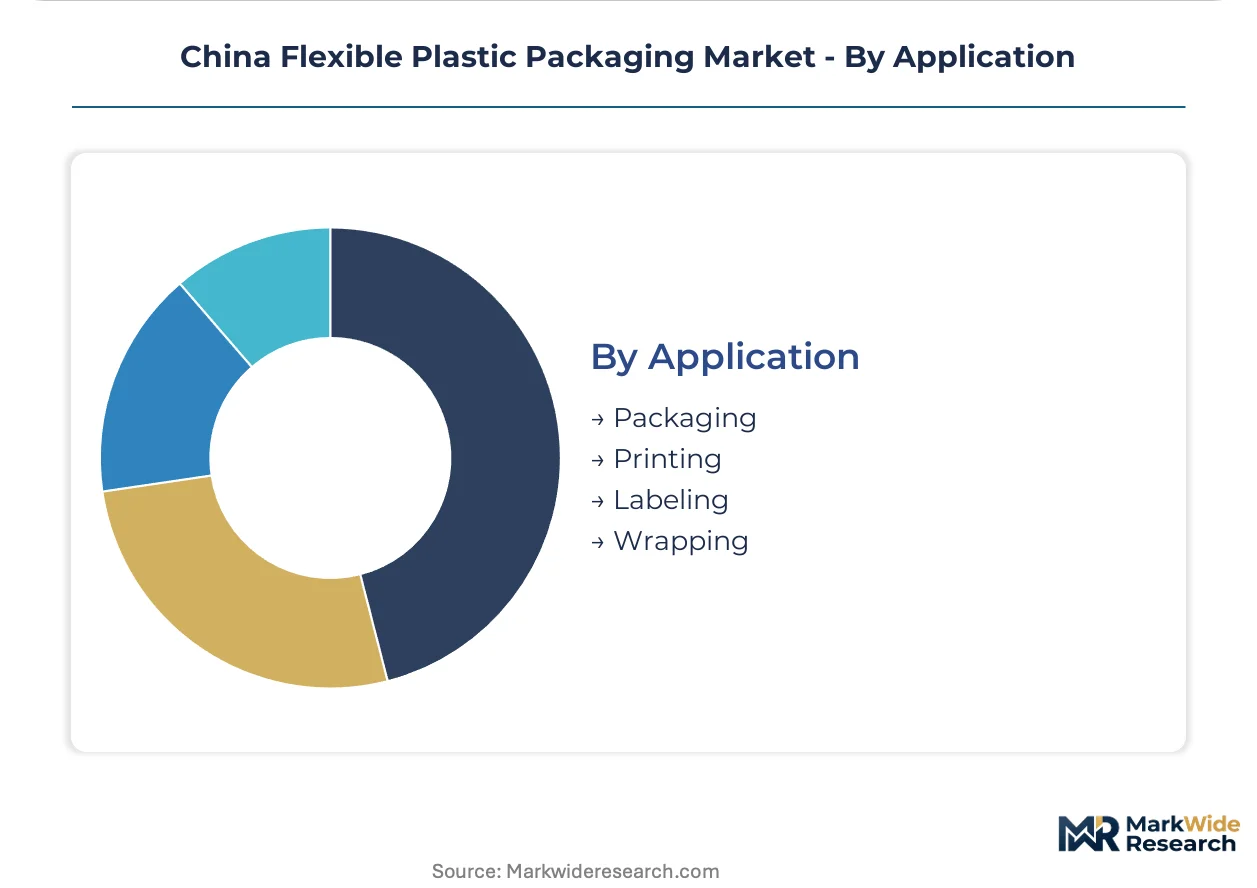
Segmentation reveals how MEE dual carbon goals and SAMR compliance requirements are fragmenting demand patterns across China's flexible packaging value chain. Distinct product specifications, material formulations, and end-use requirements are creating specialized supplier tiers that reward technical capability over scale alone.
Product Type:
Domestic food processors in the Yangtze River Delta drive pouch and roll stock volumes, while export-oriented electronics and textile manufacturers in Guangdong pull specialized film and bag specifications.
- Pouches:Retort-ready and single-serve formats utilize multi-layer barrier structures with aluminum oxide coatings. Shanghai-based dairy and ready-meal processors are expanding pouch specifications to replace rigid trays, though mono-material redesigns lag due to oxygen barrier gaps.
- Roll Stock:Unformed flexible substrates feed vertical form-fill-seal lines across Jiangsu beverage bottling plants. Seven-layer coextrusion advances are compressing gauge tolerances to 8-10% variance, enabling downgauging without seal degradation.
- Bags:Side-gusseted and wicketed formats serve bulk agricultural and industrial chemical distribution in Shandong and Henan provinces.
- Films:Cast and oriented substrates support lidding and overwrap applications for healthcare blister packs in Suzhou manufacturing clusters.
Pouches hold the largest share; momentum sits with roll stock as blown-film automation accelerates.
Material:
Cost tiers stratify around resin import dependency and recyclability qualification under MEE carbon accounting rules.
- Polyethylene:LDPE and LLDPE formulations dominate volume throughput through cost-efficient sealing and VFFS compatibility. Captive blown-film capacity at northern China converters controls resin cost exposure during Middle Eastern supply disruptions.
- Polypropylene:BOPP and CPP films retain margin concentration in healthcare blister and sterilizable applications. Clarity and barrier performance command specification premiums from Suzhou medical device manufacturers.
- Polyvinyl Chloride:Shrink-sleeve and blister applications face declining food-contact approvals under tightening GB 4806 migration limits.
- Polyester:PET films anchor high-barrier laminates for retort pouches, though mono-material substitution pressure intensifies from MEE recycling-stream targets.
Polyethylene commands volume leadership; polypropylene captures margin concentration.
End User:
Customer type determines compliance burden and sustainability disclosure requirements, with multinational food brands imposing stricter scorecards than domestic processors.
- Food:Shelf-stable and ready-to-eat segments absorb the fastest capacity expansion. Yangtze River Delta processors are consolidating supplier lists to favor converters with integrated recycling partnerships and SAMR-certified testing laboratories.
- Beverage:Pouch and bag-in-box formats displace rigid containers for juice and dairy applications. Western China processors in Sichuan and Chongqing lack local high-barrier supply, creating logistics-cost arbitrage opportunities.
- Healthcare:Sterilizable blister and IV overwrap specifications demand multi-step lamination with EVOH and nylon barrier layers. Energy-intensive processes expose this segment to MEE emissions audit pressure in Jiangsu province.
- Personal Care:Single-serve sachets and stand-up pouches for shampoo and cosmetics drive digital print adoption for SKU proliferation.
Food holds the largest share; healthcare maintains the steepest specification premium.
Application:
Supply concentration varies by functional requirement, with printing and labeling capacity clustering around brand-owner design centers in Shanghai and Shenzhen.
- Packaging:Primary containment functions dominate resin consumption across all end-use segments. MEE provincial permit renewals are forcing carbon-intensity documentation per ton of packaged output.
- Printing:Flexographic and gravure systems serve high-volume beverage labels, while HP Indigo and Fujifilm inkjet enable private-label retailer velocity requirements without plate costs.
- Labeling:Pressure-sensitive and shrink-sleeve formats attach to rigid containers, with demand tied to Guangdong beverage and chemical exports.
- Wrapping:Stretch and collation films support palletization and distribution logistics for e-commerce fulfillment centers in Zhejiang province.
Packaging holds the largest share; printing is expanding most quickly through digital system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across China's flexible plastic packaging sector diverge sharply between coastal export corridors and inland processing zones, with Yangtze River Delta buyers prioritizing high-barrier specifications while western provinces absorb simpler formats for local beverage and agricultural markets.
Yangtze River Delta
Shanghai and Jiangsu province processors drive demand for retort-ready pouches and seven-layer coextruded films serving multinational food brands. MEE dual carbon audits force carbon-intensity documentation per ton of output. Suzhou manufacturing clusters concentrate healthcare blister capacity requiring energy-intensive multi-step lamination.
Pearl River Delta
Guangdong electronics and textile exporters pull specialized bag specifications for anti-static and moisture-barrier applications. SAMR labeling rule revisions create compliance preparation overhead for export shipments. Shenzhen and Dongguan converter bases cluster around brand-owner design centers demanding digital print velocity.
Shandong Peninsula
Qingdao and Yantai processors leverage captive blown-film capacity to control resin throughput costs across northern China. GB 4806 food-contact migration limits tighten material specifications for domestic dairy packaging. Weihai and Zibo house agricultural chemical distribution hubs consuming side-gusseted bulk formats.
Sichuan-Chongqing
Beverage processors in western China lack local high-barrier pouch supply, creating logistics-cost arbitrage for qualified entrants from coastal bases. Provincial MEE enforcement variance permits longer qualification timelines than Jiangsu counterparts. Chengdu and Chongqing urban clusters absorb single-serve sachet growth for convenience food segments.
Beijing-Tianjin-Hebei
Pharmaceutical and infant nutrition manufacturers in the capital corridor demand sterilizable barrier specifications with EVOH and nylon layers. MEE emissions restrictions on energy-intensive processes expose this segment to permit renewal pressure. Tianjin port logistics support resin import dependency for regional converters.
China Flexible Plastic Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with blown-film captivity separating cost-control performers from margin-dependent converters. The market structure rewards backward integration into resin throughput management and SAMR-certified laboratory infrastructure. Strategic archetypes include northern China resin-integrated producers, Yangtze Delta barrier-film specialists, and digital-print-enabled private-label suppliers. Competitive moves concentrate on mono-material redesign partnerships with multinational brand owners and chemical recycling feedstock agreements securing preferential MEE permit treatment.
Within the integrated tier, Qingdao Tongli Packaging exemplifies northern China converters leveraging captive blown-film capacity for resin cost control. YLTPACK anchors the specialized pouch-forming segment serving multinational food brands with retort-ready specifications. Jindong Packaging occupies a position among mid-tier converters competing on narrow-web flexographic printing capabilities for beverage label applications. These three represent distinct competitive vectors: upstream integration, format specialization, and print technology differentiation.
| Leading Market Players |
|---|
| Biopouches |
| Qingdao Tongli Packaging |
| YLTPACK |
| Jindong Packaging |
| Xiongxian Chengtai |
| LD PACK |
| Logos Pack |
| Earthycores |
| Sunkey Packaging |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty days of resin inventory at Yangtze River Delta converters compresses pricing power toward Middle Eastern suppliers during freight spikes, while spot resin procurement exposes regional players to margin volatility that long-term contract holders avoid.
Pricing Analysis
Long-term offtake contracts dominate resin procurement for integrated northern China converters, insulating Qingdao Tongli Packaging from spot polyethylene volatility that squeezes margin-dependent Jiangsu competitors. Three-tier pricing structure across premium certified, standard industrial, and economy grades reflects SAMR laboratory certification status and volume scale. Cost compression in standard-grade roll stock is intensifying because blown-film automation expands effective capacity. Domestic beverage processors show highest price sensitivity; multinational food brands in Shanghai tolerate premium pricing for verified carbon-intensity documentation.
Supply Chain Analysis
Strait of Malacca transit underwrites polyethylene feedstock flows from Saudi Arabian and Qatari production nodes to Shanghai and Ningbo port terminals. China's flexible packaging sector draws from Middle Eastern resin supply, Korean barrier film imports, and domestic Zhejiang coextrusion equipment. Single-source vulnerability concentrates in EVOH and nylon barrier layers from Japanese and German specialty producers. Distribution runs through provincial converter clusters feeding brand-owner packaging lines in Yangtze and Pearl River Delta manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated Yangtze River Delta food processors that are narrowing supplier lists to three certified partners per packaging category, fragmenting revenue access for mid-tier converters without SAMR laboratory infrastructure.
For Market Incumbents: Fortify backward integration into captive blown-film capacity to control resin throughput costs against Middle Eastern supply volatility. Deepen SAMR-certified testing laboratory investments to capture certified-supplier premiums as migration-limit enforcement tightens. Secure preferential MEE permit treatment through renewable energy contracts or chemical recycling feedstock agreements before Jiangsu provincial audits intensify. For New Entrants and Emerging Players: SAMR fast-track certification partnerships with accredited third-party laboratories compress qualification timelines from twelve to six weeks. Western China beverage processors in Sichuan and Chongqing present the most penetrable geography due to absent local high-barrier pouch supply. Lead with digital print-on-demand capabilities matching private-label retailer SKU velocity requirements without plate cost barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across seven-layer coextrusion line deployments as gauge tolerance requirements tighten. Target acquisition candidates with mono-material redesign partnerships already qualified by multinational food brands, positioned for MEE recycling-stream compliance. Watch for chemical recycling pyrolysis feedstock agreements as the inflection signal separating permit-favored producers from carbon-intensive legacy operations.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Redesign Partnership | Qualifies converters for MEE recycling-stream targets preferred by Shanghai-based multinational brands. |
| Chemical Recycling Feedstock Agreement | Secures carbon-intensity reductions bypassing mechanical recyclate quality constraints for food-contact applications. |
| Digital Print System Deployment | Matches Guangdong private-label retailer velocity requirements without gravure plate cost amortization. |
| SAMR Laboratory Certification Investment | Captures supplier premiums as migration-limit enforcement extends qualification timelines for uncertified competitors. |
| Western China Distribution Expansion | Exploits logistics-cost arbitrage in Sichuan-Chongqing beverage markets lacking local high-barrier pouch supply. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at Jiangsu and Shandong converter facilities, procurement leads at Yangtze River Delta food processors, and MEE provincial enforcement officers; combined with secondary validation through customs resin import records, SAMR GB standard revision notices, and provincial manufacturing permit databases. Bottom-up capacity modeling triangulated against top-down end-use demand estimates across food, beverage, healthcare, and personal care segments.
Across the projection horizon, the analytical framework modeled volume and value outputs through product type, material formulation, end-use industry, and regional manufacturing cluster segmentation. CAGRs were derived from trend extrapolation of blown-film automation adoption rates and mono-material substitution curves, calibrated against MEE dual carbon permit issuance trajectories and SAMR compliance cost inflation assumptions.
Decision-makers should treat outputs as directional under sustained MEE enforcement intensity and stable Middle Eastern resin supply; material deviation would warrant model refresh. Specific risks include abrupt GB standard revisions, chemical recycling feedstock cost spikes, and provincial emissions audit enforcement variance. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
Bakery Flexible Packaging Market
Flexible Packaging
Canada Flexible Packaging Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
North America Flexible Packaging Market
Flexible Packaging
GCC Flexible Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market