
 Flexible Food Packaging Market | 2026-2036
Flexible Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Food Packaging Market Analysis
Polyethylene is expanding its share in frozen food applications as converters replace multi-layer barrier structures with recyclable mono-material alternatives. Amcor leverages vertical integration across resin compounding and film extrusion to control cost positions in North American snack packaging. Mondi Group anchors European supply through kraft paper-based flexible solutions targeting the dairy segment. ProAmpac differentiates via high-barrier pouch formats for retort-ready meals, competing against rigid tray systems.
Flexible food packaging comprises pliable substrates engineered to conform to product geometry while providing moisture, oxygen, and light barriers through laminated or coextruded films typically measuring 50-200 micrometers in total caliper. The primary commercial purpose centers on extending shelf stability, reducing transport cube, and enabling portion-controlled dispensing across retail and foodservice channels. Polyethylene and polypropylene together dominate material type volumes given their sealability and cost efficiency, though paper substrates are gaining structural share where fiber-based claims support brand positioning. Pouches represent the fastest-expanding packaging format as stand-up and spouted variants displace glass and metal in beverages and sauces. Dairy products and snacks concentrate margin pools due to barrier complexity and volume scale.
EU REACH and the Packaging and Packaging Waste Regulation shape material compliance trajectories across European converters, while FDA food contact substance notifications govern migration limits for US-bound exports. China's GB standards for composite food packaging materials enforce solvent residue and heavy metal thresholds that influence laminate adhesive selection. Stakeholders must monitor evolving extended producer responsibility frameworks and chemical disclosure requirements as these determine which substrate combinations retain market access.
Market Dynamics
Mono-material recyclable structures are compressing multi-layer laminate demand as the EU's Packaging and Packaging Waste Regulation mandates design-for-recycling compliance across European supply chains.
Growth Catalysts
- PPWR Compliance Deadlines:The EU's Packaging and Packaging Waste Regulation is forcing converters to retool extrusion lines for polyethylene mono-materials, pulling forward capital deployment across Germany, France, and Italy.
- Ready-to-Eat Meal Proliferation:Pouched formats with extended shelf stability are capturing share from rigid trays in North American and Asian prepared food segments.
- Barrier Coating Advances:Water-based and plasma-deposited barrier technologies are enabling paper substrates to compete in oxygen-sensitive dairy and snack applications.
Market Restraints
- Resin Price Volatility:Ethylene and propylene feedstock costs swing with crude oil and naphtha indices, compressing converter margins on fixed-price annual contracts.
- Adhesive Reformulation Costs:Solvent-based polyurethane laminating adhesives face phase-out pressure under REACH, requiring expensive migration-compliant alternatives.
- Recycling Infrastructure Gaps:Flexible film collection and sorting systems remain underdeveloped outside Northern European markets, limiting circularity claims.
Strategic Opportunities
- China's Coastal Export Clusters:Food processing zones in Jiangsu and Shandong provinces are upgrading to premium barrier films for seafood and frozen vegetable exports.
- Retort Pouch Conversion:Metal can and glass jar replacement in shelf-stable pet food and infant nutrition creates high-barrier pouch demand.
- Extended Producer Responsibility Tailwinds:Germany's Verpackungsgesetz and France's AGEC law are creating compliance-service revenue streams for packaging suppliers.
Industry Challenges
- Migration Testing Bottlenecks:FDA food contact substance notifications and EU overall migration limits require 12-18 month certification timelines for new laminate structures.
- Skilled Extrusion Technician Scarcity:Coextrusion die design and blown film process control expertise is concentrating among aging workforces in Midwestern US and German converter bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Food Packaging Market |
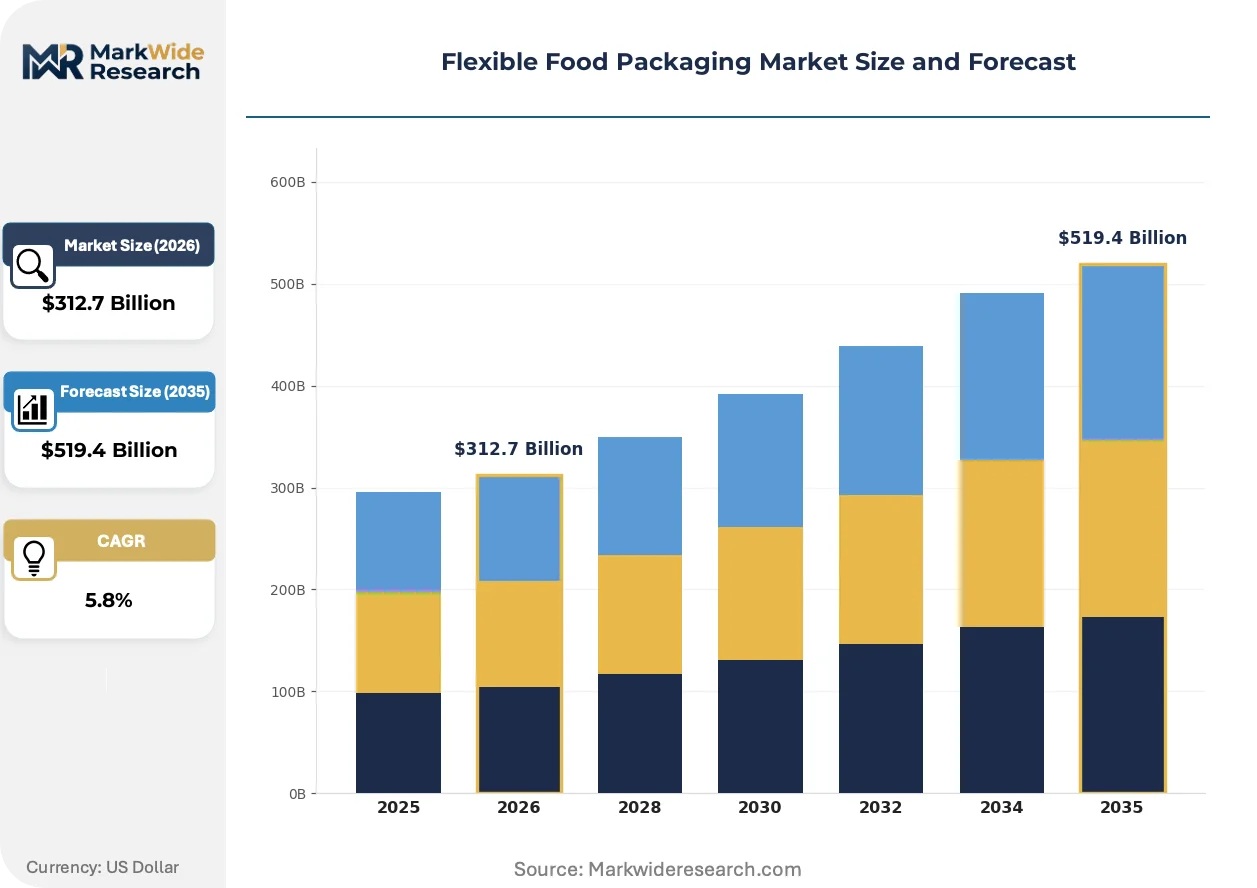
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $519.4 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Paper, Aluminum Foil Packaging Format: Bags, Pouches, Wraps, Films End User: Snacks, Beverages, Frozen Foods, Dairy Products Printing Technology: Flexographic, Gravure, Digital, Offset |
| Companies Covered | Mondi Group, ProAmpac, Amcor, TC Transcontinental, Constantia Flexibles, Berry Global, Sonoco, Smurfit Westrock, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Food Packaging Market Emerging Trajectories
Digital printing and smart packaging integration are compressing minimum order quantities while enabling batch-level traceability demanded by food safety auditors.
High-barrier ethylene vinyl alcohol copolymer is absorbing oxygen protection duties previously assigned to aluminum foil layers in retort pouch structures. European dairy processors are adopting these metallized-film alternatives at accelerated qualification paces. The shift is absorbing capital from metallizer equipment suppliers while redirecting investment toward coextrusion line expansion.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical coatings from paper-based flexible packaging. Converters are pivoting toward bio-wax and clay-barrier substitutes. The snack and fast-food wrapper segments are absorbing the highest compliance costs and longest reformulation timelines.
Direct-to-manufacturer procurement contracts are fragmenting traditional distributor channels in North American flexible packaging. Large food brands are building in-house specification teams to negotiate resin-indexed pricing. This pattern is most visible in the US snack and pet food verticals where volume concentration justifies dedicated supplier management functions.
Flexible Food Packaging Market Segmentation
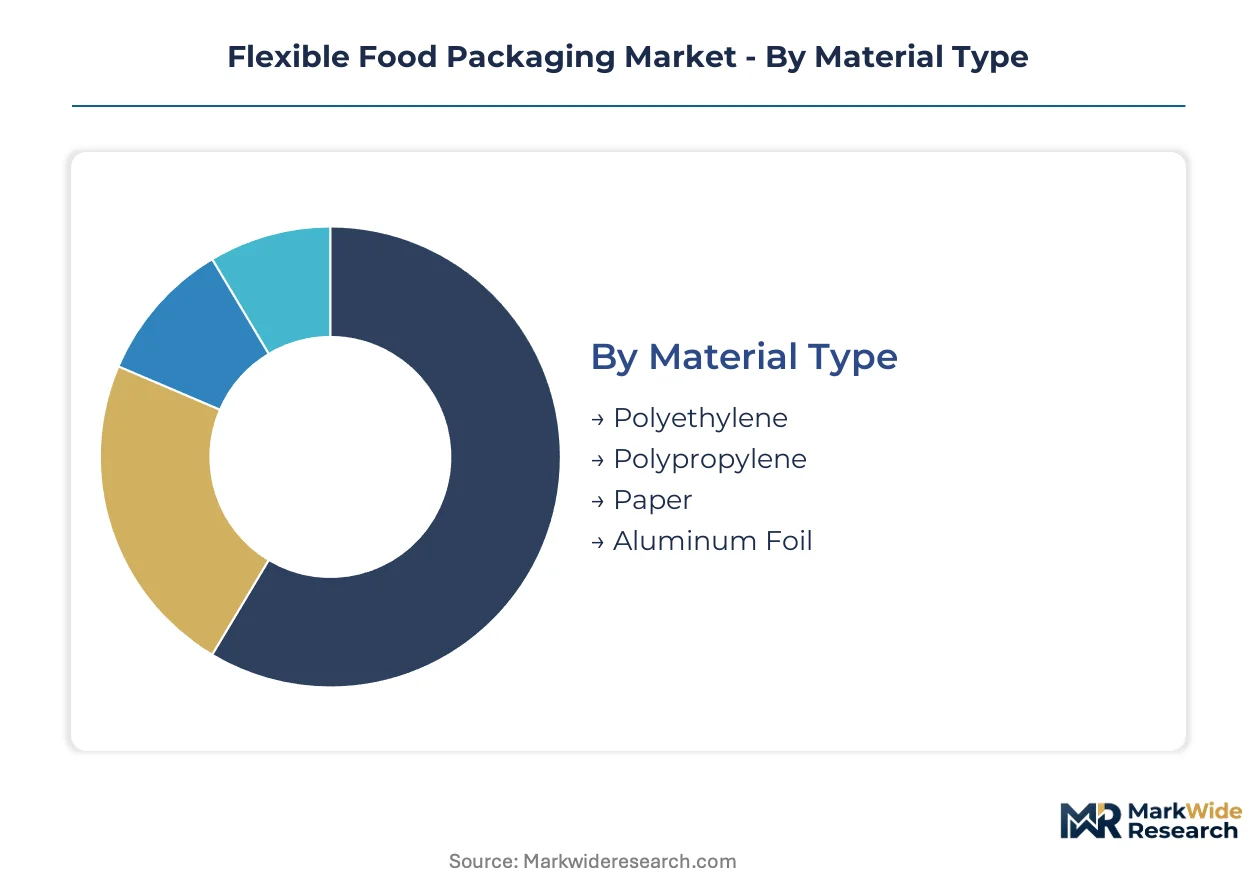
Segmentation in flexible food packaging reveals how material science, format engineering, and end-use requirements intersect to determine converter specialization and margin capture. Each axis—substrate chemistry, physical configuration, application demand, and decoration method—carries distinct capital intensity and regulatory exposure.
Material Type:
Sealability, barrier performance, and recyclability credentials define competitive positioning across substrate categories.
- Polyethylene:Linear low-density and metallocene grades dominate mono-material pouch structures, with converters in Germany and France accelerating extrusion line conversions to meet EU Packaging and Packaging Waste Regulation mandates for design-for-recycling compliance.
- Polypropylene:Biaxially oriented films provide stiffness and clarity for snack lamination, though propylene feedstock volatility compresses margin stability for converters locked into annual pricing contracts with retail brand owners.
- Paper:Fiber-based substrates are gaining structural share where brand positioning emphasizes renewable sourcing, with kraft-based solutions anchoring European dairy supply through Mondi Group's integrated pulp-to-converter operations.
- Aluminum Foil:Metallized barrier layers face displacement pressure from ethylene vinyl alcohol copolymer alternatives in retort applications, though foil retains dominance in ultra-high-barrier pharmaceutical-adjacent food segments.
Mature deployment sits with aluminum foil. Newer deployment is concentrated in polyethylene mono-material structures.
Packaging Format:
Physical configuration determines transport cube efficiency, shelf presence, and dispensing functionality across retail and foodservice channels.
- Pouches:Stand-up and spouted variants are displacing glass and metal in beverages and sauces, with China's coastal manufacturing provinces driving premium film consumption for seafood and frozen vegetable export processing.
- Bags:Pillow and gusseted formats retain volume leadership in snack verticals where high-speed form-fill-seal equipment amortization favors standardized geometries over customization.
- Wraps:Cling and stretch films serve foodservice portion control, though REACH restrictions on per- and polyfluoroalkyl substances are forcing rapid reformulation of grease-resistant fluorochemical coatings.
- Films:Single-wind rolls supply downstream converters and in-house packaging operations at large food processors, with direct-to-manufacturer procurement contracts fragmenting traditional distributor channels in North America.
Format selection tracks end-use shelf-life requirements and equipment infrastructure—pouches climbing fastest where retort sterilization enables shelf-stable ready-to-eat meal proliferation.
End User:
Application-specific barrier demands and volume scale determine converter customer concentration and contract structure.
- Snacks:Oxygen and moisture sensitivity drives multi-layer lamination complexity, with nitrogen flush requirements creating specification lock-in between converters and salty snack brand owners.
- Dairy:Yogurt and cheese applications concentrate margin pools due to stringent hygiene protocols and light-blocking requirements, with European processors adopting metallized-film alternatives at accelerated qualification paces.
- Frozen Foods:Puncture resistance and low-temperature seal integrity define material selection, with polyethylene expanding share as converters replace multi-layer barrier structures with recyclable mono-material alternatives.
- Beverages:Spouted pouch adoption in juices and functional drinks creates demand for fitment welding expertise, competing against established rigid bottle supply chains on convenience and transport efficiency.
Volume concentration favors snacks. Barrier complexity and margin capture favor dairy.
Printing Technology:
Decoration method determines minimum order quantities, color consistency, and regulatory compliance pathways for food contact surfaces.
- Flexographic:Water-based and UV-curable ink systems dominate high-volume snack and beverage segments, with central impression drum presses enabling efficient substrate utilization across thin film gauges.
- Digital:Inkjet and toner systems compress minimum order quantities while enabling batch-level traceability demanded by food safety auditors, gaining traction in seasonal and promotional packaging runs.
- Gravure:Cylinder-engraved printing retains dominance in premium photographic reproduction for confectionery and gift packaging, though cylinder inventory costs disadvantage shorter run lengths.
- Offset:Lithographic transfer finds limited flexible packaging application, primarily serving paper-based label and wrapper segments where substrate rigidity accommodates blanket cylinder pressure.
Gravure holds established high-volume deployment. Digital represents the steepest expansion trajectory as brand owners fragment SKUs and compress time-to-market windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal manufacturing provinces concentrate the highest flexible food packaging demand intensity, with Jiangsu and Shandong food export processing clusters driving premium barrier film consumption. Germany, France, and Italy anchor European converter retooling activity under EU Packaging and Packaging Waste Regulation compliance deadlines. The United States maintains volume leadership in snack and pet food pouch applications.
China
Food export processing zones in Jiangsu and Shandong provinces upgrade to high-barrier films for seafood and frozen vegetable shipments. GB standards for composite food packaging materials enforce solvent residue and heavy metal thresholds that influence laminate adhesive selection. Shanghai and Qingdao converter clusters absorb the majority of ethylene vinyl alcohol copolymer imports for retort pouch production.
Germany
Converters accelerate extrusion line conversions for polyethylene mono-materials to meet design-for-recycling compliance under the Packaging and Packaging Waste Regulation. Verpackungsgesetz extended producer responsibility frameworks create compliance-service revenue streams for packaging suppliers. The Rhine-Ruhr industrial corridor hosts the densest concentration of blown film extrusion capacity serving dairy and snack brand owners.
United States
Ready-to-eat meal producers adopt pouched formats with extended shelf stability, capturing share from rigid trays in prepared food segments. FDA food contact substance notifications govern migration limits for laminate structures bound for domestic retail channels. Midwestern converter bases in Illinois and Wisconsin concentrate coextrusion die design expertise among aging workforces.
France
AGEC law anti-waste provisions accelerate demand for mono-material recyclable structures in retail food packaging applications. ECHA REACH restrictions on per- and polyfluoroalkyl substances eliminate grease-resistant fluorochemical coatings from paper-based flexible formats. Lyon and Paris basin converters specialize in high-barrier pouch formats for retort-ready meals competing against rigid tray systems.
Italy
Pasta and preserved food exporters drive demand for metallized-film alternatives to aluminum foil in oxygen-sensitive applications. EU Packaging and Packaging Waste Regulation mandates force qualification paces for ethylene vinyl alcohol copolymer barrier layers. Emilia-Romagna packaging machinery manufacturers supply form-fill-seal equipment to domestic and export converter markets.
Flexible Food Packaging Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated resin-to-film operators commanding pricing leverage in polyethylene mono-material supply. The vendor base concentrates around three strategic archetypes: vertically integrated multinationals with captive resin compounding, regional converters serving single-country brand portfolios, and equipment-anchored specialists bundling machinery with substrate supply. Competitive moves center on extrusion line capacity expansion for recyclable structures and strategic partnerships with food safety certification laboratories to compress migration testing timelines.
Among integrated packaging multinationals, Amcor, Mondi Group, and ProAmpac occupy positions that exemplify divergent specialization vectors. Amcor represents the vertically integrated archetype with upstream control over resin compounding and film extrusion. Mondi Group anchors European supply through kraft paper-based flexible solutions targeting fiber-positioned brand claims. ProAmpac sits within the high-barrier pouch specialist tier, competing against rigid tray systems in retort-ready meal segments.
| Leading Market Players |
|---|
| Mondi Group |
| ProAmpac |
| Amcor |
| TC Transcontinental |
| Constantia Flexibles |
| Berry Global |
| Sonoco |
| Smurfit Westrock |
| Sealed Air |
| Others |
Supply Flow & Price Mechanics
Mono-material extrusion line conversions are simultaneously raising capital intensity for compliant converters and concentrating supply among integrated resin-to-film operators capable of absorbing retooling costs. The EU's Packaging and Packaging Waste Regulation is compressing margins for smaller laminate specialists while rewarding polyethylene mono-material scale players with pricing power in German and French supply chains.
Pricing Analysis
Volume leadership in snack and frozen food segments runs on thin converter margins, while dairy and retort-ready meal applications capture premium pricing through barrier complexity and certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates metallized high-barrier films from mono-material polyethylene and basic polypropylene laminates. Cost compression in standard-tier polyethylene supply is intensifying because resin-indexed contracts expose converters to ethylene feedstock volatility. Snack brand owners exhibit highest price sensitivity due to volume concentration and equipment amortization pressures, whereas infant nutrition and pharmaceutical-adjacent food segments accept premium pricing for migration-compliant structures.
Supply Chain Analysis
Direct-to-manufacturer procurement contracts handle hyperscale buyer demand from North American snack and pet food brand owners, fragmenting traditional distributor channels. Raw material supply concentrates in Germany, China, and the United States, with ethylene and propylene feedstock production anchoring converter cost positions. Key inputs include metallocene polyethylene grades, ethylene vinyl alcohol copolymer barrier resins, and water-based laminating adhesives reformulated for REACH compliance. Single-source vulnerability sits with specialized coextrusion die suppliers concentrated in German and Midwestern US engineering bases. Distribution runs through converter-direct relationships with large food processors, bypassing regional packaging distributors in high-volume verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Flexible Food Packaging Market reads as a cost-of-compliance story where EU REACH and Packaging and Packaging Waste Regulation mandates erect barrier-to-entry moats for converters with certified migration-compliant structures. Players lacking capital for extrusion line retooling face displacement as mono-material qualification timelines stretch 12-18 months.
For Market Incumbents: Lock in converter-direct relationships with large snack and dairy brand owners before EPR frameworks mature. Prioritize captive resin compounding capacity to hedge ethylene feedstock volatility eroding margins on annual fixed-price contracts. Defend against emerging mono-material specialists by accelerating EVOH barrier layer qualifications in retort applications. For New Entrants and Emerging Players: The premium-to-economy price gap in Chinese coastal export clusters offers white-space entry for barrier film specialists serving Jiangsu and Shandong seafood processors. Target paper-based flexible formats where REACH fluorochemical coating bans force rapid snack wrapper reformulation. Lead with digital printing capabilities to capture seasonal promotional packaging runs from brands fragmenting SKUs. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated packaging multinationals seeking polyethylene mono-material capacity in European compliance markets. Long-term viability favors converters with backward integration into resin compounding and film extrusion. Watch EPR enforcement intensity in Germany's Verpackungsgesetz and France's AGEC law as inflection indicators for compliance-service revenue scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Line Conversion | EU PPWR compliance deadlines in Germany and France pull forward capital deployment for design-for-recycling capacity. |
| Barrier Coating Technology Partnership | Water-based and plasma-deposited alternatives enable paper substrate competition in oxygen-sensitive dairy applications. |
| Retort Pouch Qualification Acceleration | EVOH barrier layers displace aluminum foil in shelf-stable pet food and infant nutrition segments. |
| Extended Producer Responsibility Service Buildout | Germany's Verpackungsgesetz creates compliance-service revenue streams beyond substrate supply. |
| Digital Printing Platform Integration | Inkjet systems compress minimum order quantities for seasonal promotional packaging in fragmented SKU environments. |
Methodological Framework
Trade association filings, customs records, and SEC 10-K disclosures formed the secondary backbone for resin and film production volume estimation. Primary interviews with blown film extrusion plant managers, procurement leads at snack and dairy brand owners, laminating adhesive technical directors, and food safety certification laboratory heads validated secondary data points. Bottom-up triangulation across converter capacity utilization rates and top-down cross-checks against end-use demand segmentation ensured consistency in volume and value outputs.
Historical trendline analysis of polyethylene and polypropylene film production established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation across material type, packaging format, end-use application, and printing technology dimensions. CAGRs were derived from elasticity-adjusted demand projections incorporating EPR policy implementation schedules and retort pouch conversion rates in prepared food segments. Forecast inputs included ethylene feedstock price indices, extrusion line capacity expansion announcements, and REACH compliance timeline assumptions.
Inputs from converter associations and resin producer disclosures were available through the study window; gaps in real-time inventory positioning data introduce uncertainty bands around quarterly volume estimates. Forecasts reflect assumptions regarding PPWR enforcement consistency and EVOH supply expansion timelines. Periodic stress-testing of base assumptions against regulatory implementation delays and feedstock price volatility scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
United States Flexible Plastic Packaging Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
Mexico Flexible Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market
Flexible Packaging
Flexible Packaging Paper Market
Flexible Packaging
GCC Flexible Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
UK Flexible Plastic Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Flexible Detergent Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
Russia Flexible Plastic Packaging Market