
 Thermochromic Labels Market | 2026-2036
Thermochromic Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Thermochromic Labels Market Analytics
Microencapsulation chemistry is narrowing the performance gap between reversible and irreversible thermochromic systems, enabling broader industrial deployment. Chromatic Technologies Inc. leverages proprietary leuco-dye encapsulation to sustain color precision across extreme thermal cycles. LCR Hallcrest LLC anchors North American supply through backward integration into liquid crystal substrate production. Avery Dennison Corporation competes by extending its pressure-sensitive adhesive platform into temperature-indicating laminate structures.
Thermochromic labels are temperature-responsive substrates incorporating leuco dyes, liquid crystals, or thermochromic pigments that undergo reversible or irreversible color transitions at defined thermal thresholds, typically calibrated between minus twenty and plus sixty degrees Celsius for cold-chain verification, sterilization confirmation, or consumer engagement applications. Liquid crystal technology dominates medical diagnostics where sub-degree precision proves essential, while polymer-based formulations capture fastest expansion in food packaging as converters seek compliance with REACH and EU Green Deal chemical restrictions. Sticker labels retain the largest volume share across temperature indicators and safety labels, though smart textiles emerge as a margin-rich niche where Matsui International specializes in textile-grade thermochromic inks.
FDA 21 CFR Part 211 guidelines for pharmaceutical distribution mandate temperature documentation, directly stimulating demand for irreversible indicator labels in vaccine and biologic logistics. EMA's Good Distribution Practice and the EU AI Act's traceability requirements for high-risk product categories further tighten compliance obligations across European pharmaceutical supply chains. Stakeholders must monitor how evolving EPA and ECHA substance restrictions on microplastic-containing formulations redirect R&D investment toward bio-based leuco dye carriers before regulatory deadlines crystallize competitive displacement.
Market Dynamics
Pharmaceutical cold-chain verification requirements are compressing label procurement cycles as biologics manufacturers demand irreversible temperature indicators with forensic-grade documentation trails. This structural pull is restructuring converter capacity allocation toward medical-grade microencapsulation lines.
Growth Catalysts
- FDA 21 CFR Part 211:Mandated temperature documentation for pharmaceutical distribution forces vaccine and biologic logistics providers to deploy irreversible indicator labels at every shipment node.
- EU F-Gas Regulation:Chemical restrictions on fluorinated greenhouse gases push European converters toward polymer-based leuco dye carriers with reduced environmental footprints.
- Precision manufacturing clusters:German pharmaceutical packaging standards anchor regional demand for sub-degree liquid crystal precision in diagnostic applications.
Market Restraints
- Leuco dye feedstock concentration:Specialty dye synthesis capacity concentrates among a handful of European and Asian chemical suppliers, creating input volatility.
- Microplastic formulation bans:ECHA substance restrictions on microplastic-containing carriers force premature R&D redirection before bio-based alternatives achieve cost parity.
- Liquid crystal substrate scarcity:Medical-grade cholesteric liquid crystal production requires captive semiconductor-grade cleanroom capacity that few converters possess.
Strategic Opportunities
- Smart textile integration:Wearable temperature monitoring in healthcare and athletic apparel opens margin-rich deployment for textile-grade thermochromic ink systems.
- EU AI Act traceability:High-risk product category documentation requirements create bundled demand for temperature indicators with digital authentication layers.
- Biologic cold-chain expansion:Cell and gene therapy logistics in emerging Asian markets present first-mover positioning for irreversible threshold indicators calibrated to cryogenic ranges.
Industry Challenges
- Microencapsulation talent scarcity:Cross-disciplinary expertise spanning polymer chemistry, colorimetric science, and pharmaceutical validation remains concentrated among legacy specialists.
- Dual certification timelines:Simultaneous FDA 21 CFR Part 211 and EMA Good Distribution Practice approvals extend product launch cycles by eighteen to thirty-six months.
- Legacy adhesive incompatibility:Existing pressure-sensitive label application equipment requires retrofitting to handle temperature-responsive laminate structures without compromising indicator accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermochromic Labels Market |
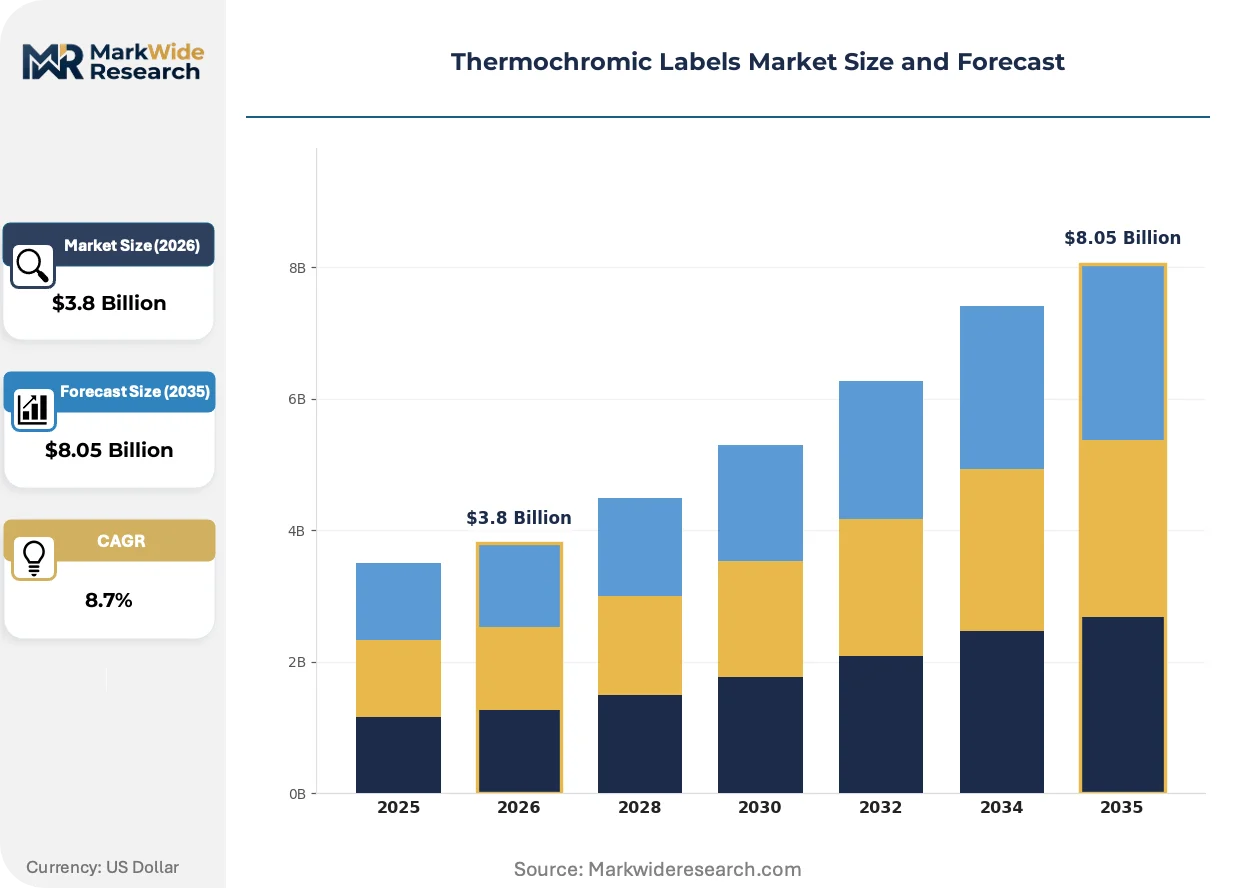
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sticker Labels, Food Packaging, Promotional Items, Smart Textiles Application: Temperature Indicators, Safety Labels, Brand Promotion, Medical Diagnostics End User: Food Industry, Healthcare, Retail, Industrial Sector Technology: Liquid Crystal, Photochromic, Polymer-Based, Others |
| Companies Covered | LCR Hallcrest LLC, Chromatic Technologies Inc., New Color Chemical Co., Ltd., Inkron Oy, OliKrom, Matsui International, Avery Dennison Corporation, Thermographic Measurements Ltd., MCP Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermochromic Labels Market Evolving Landscape
Convergence between colorimetric chemistry and digital traceability architectures is redefining how temperature excursions get documented, verified, and adjudicated across pharmaceutical supply chains.
Microencapsulated leuco dye systems is collapsing the performance differential between reversible consumer-engagement labels and irreversible cold-chain indicators. Pharmaceutical packagers in Germany and Switzerland are adopting hybrid formulations that switch states precisely at clinical thresholds while retaining consumer-readable color bands. This technological compression enables single-label architectures to satisfy both regulatory documentation and patient-facing communication requirements.
REACH authorization procedures and EU Green Deal chemical restrictions are forcing systematic reformulation of thermochromic pigment carriers before 2030 deadlines. Converters serving food packaging applications face immediate substitution mandates for petroleum-based encapsulation resins. The regulatory pressure concentrates impact on mid-tier European label producers lacking captive polymer synthesis capabilities.
Direct procurement relationships between biologics manufacturers and specialized indicator converters are displacing traditional distributor intermediaries in temperature-sensitive logistics. Large pharmaceutical shippers in the United States now specify indicator performance parameters in master service agreements rather than accepting converter-standard catalog offerings. This channel restructuring concentrates volume among vertically integrated suppliers capable of custom calibration across cryogenic, refrigerated, and controlled ambient ranges.
Thermochromic Labels Market Segmentation
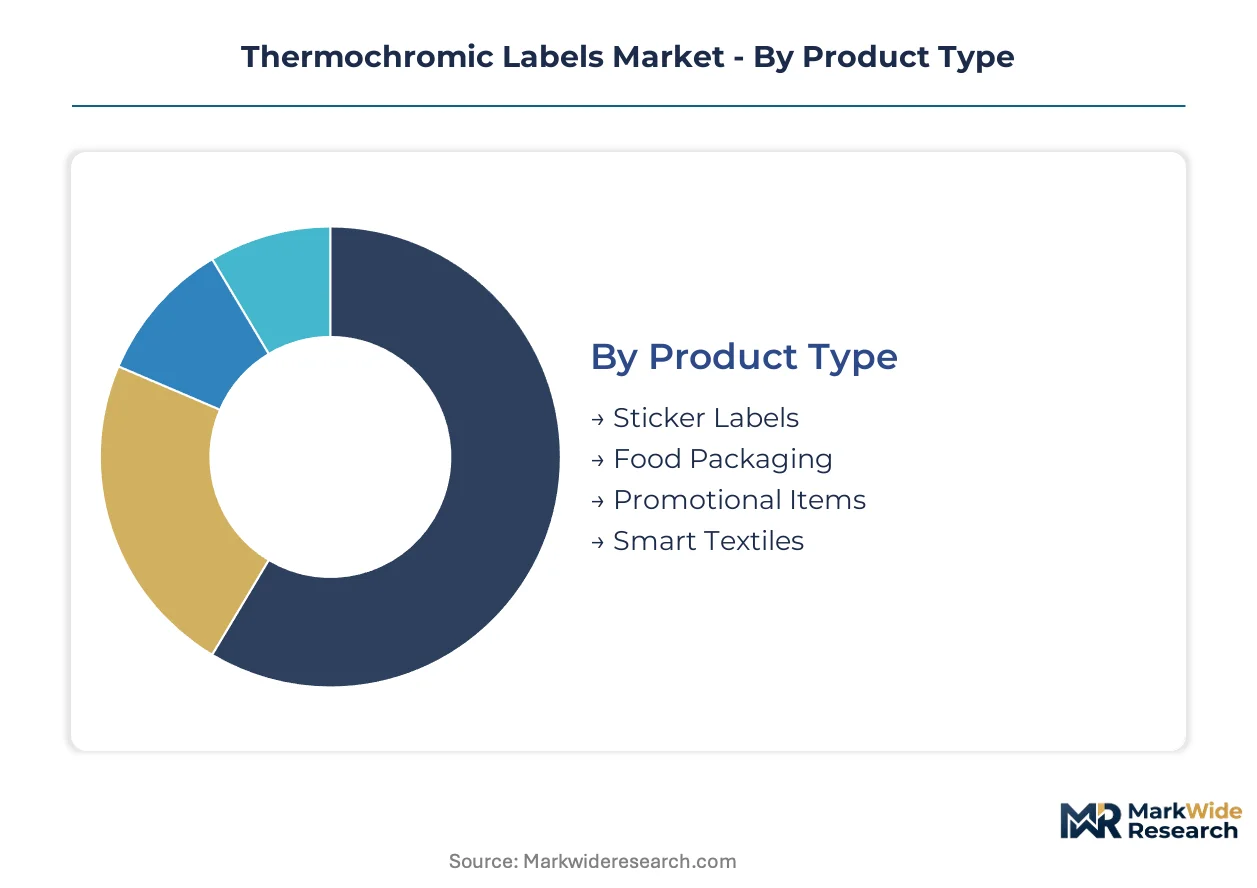
Thermochromic label procurement patterns diverge sharply across end-use contexts, with pharmaceutical cold-chain verification demanding forensic-grade documentation while consumer packaging prioritizes cost-efficient color-change engagement. Segment boundaries blur as hybrid formulations emerge, yet technology choices and application requirements still dictate supplier selection criteria and margin structures.
Product Type:
After-sales calibration and technical support intensity varies dramatically across product formats, with medical-grade systems requiring validation documentation and food-packaging solutions emphasizing converter responsiveness.
- Sticker Labels:Pressure-sensitive constructions incorporating leuco dye or liquid crystal layers dominate pharmaceutical cold-chain deployment. German and Swiss biologics manufacturers specify irreversible threshold indicators calibrated to 2-8°C ranges with lot-traceable documentation trails. Sticker labels hold the largest share; momentum sits with smart textiles.
- Food Packaging:Polymer-based thermochromic films signal freshness or temperature abuse in refrigerated supply chains. European converters reformulate encapsulation resins to satisfy REACH authorization deadlines and EU Green Deal chemical restrictions. Adoption concentrates in Germany where retail chains mandate visual temperature verification for prepared meal segments.
- Promotional Items:Reversible color-change substrates engage consumers through temperature-triggered brand interactions. Beverage and cosmetics sectors in the United States deploy these for seasonal campaigns requiring rapid converter turnaround.
- Smart Textiles:Matsui International specializes in textile-grade thermochromic inks for wearable temperature monitoring in athletic and healthcare apparel. Medical applications in Switzerland demand sub-degree precision for patient skin-contact diagnostics.
Sticker labels command volume leadership through pharmaceutical compliance mandates; smart textiles climb fastest as healthcare wearables expand.
Application:
Cost tier stratification separates premium medical diagnostics from economy brand promotion segments, with certification requirements driving pricing spreads.
- Temperature Indicators:Irreversible threshold systems document cold-chain integrity for vaccines and biologics. FDA 21 CFR Part 211 mandates force deployment at every US pharmaceutical distribution node. Temperature indicators anchor revenue concentration; medical diagnostics expand most quickly.
- Safety Labels:Visual warnings signal overheating in industrial equipment or sterilization completion in surgical kits. German precision manufacturing clusters specify liquid crystal precision for sub-degree thermal monitoring.
- Brand Promotion:Reversible color transitions create interactive consumer experiences in beverage and personal care packaging. European food retailers leverage these for private-label differentiation.
- Medical Diagnostics:Cholesteric liquid crystal substrates enable fever detection and wound monitoring with clinical-grade accuracy. Production requires semiconductor-grade cleanroom capacity that limits qualified suppliers.
Temperature indicators dominate procurement volumes; medical diagnostics gain share fastest through diagnostic wearable expansion.
End User:
Customer type determines specification rigor, with healthcare and food industry buyers imposing distinct validation protocols that reshape converter capability requirements.
- Food Industry:Retail chains and prepared meal producers deploy thermochromic packaging to signal freshness and temperature compliance. EFSA guidelines and national food safety regulators across Europe tighten visual documentation requirements. Healthcare commands premium pricing; food industry scales volume fastest.
- Healthcare:Biologics manufacturers and hospital systems mandate irreversible indicators with forensic-grade lot traceability. EMA Good Distribution Practice and FDA validation protocols extend supplier qualification timelines. Demand concentrates in German pharmaceutical packaging corridors.
- Retail:Private-label brands and promotional merchandise buyers prioritize cost-efficient reversible systems with rapid design turnaround.
- Industrial Sector:Equipment manufacturers integrate temperature-warning labels into machinery safety systems, with German automotive and chemical producers setting durability standards.
Healthcare generates the highest margins; food industry captures steepest volume expansion through retail chain standardization.
Technology:
Supply concentration in leuco dye synthesis and liquid crystal substrate production creates input bottlenecks that favor backward-integrated converters.
- Liquid Crystal:Cholesteric formulations deliver sub-degree precision essential for medical diagnostics and pharmaceutical cold-chain verification. Medical-grade production concentrates among specialists with captive cleanroom infrastructure. Liquid crystal leads precision applications; polymer-based formulations scale fastest.
- Polymer-Based:Encapsulated leuco dye systems in bio-based carriers address EU F-Gas Regulation and REACH chemical restrictions. German and Swiss converters pioneer reformulation to preempt regulatory deadlines.
- Photochromic:Light-activated color change serves niche applications where UV exposure indicates product authenticity or storage conditions.
- Others:Emerging thermochromic technologies including hybrid organic-inorganic systems target cryogenic biologic logistics and extreme industrial environments.
Liquid crystal dominates medical-grade revenue; polymer-based systems gain share fastest through regulatory-driven substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturers and pharmaceutical packagers concentrate procurement authority across three distinct buyer archetypes: multinational cold-chain operators, regional generic drug distributors, and specialized diagnostic device producers.
Germany
Precision pharmaceutical packaging and diagnostic device manufacturing anchor thermochromic label demand. The EU F-Gas Regulation accelerates converter migration toward polymer-based leuco dye carriers with reduced environmental footprints. The Rhine-Main cluster around Frankfurt hosts biologics distribution centers specifying irreversible threshold indicators with forensic-grade documentation.
United States
Vaccine logistics networks and cell therapy cold-chain expansion drive irreversible indicator deployment. FDA 21 CFR Part 211 mandates temperature documentation at every pharmaceutical distribution node. The Boston-Cambridge biotech corridor demands sub-degree liquid crystal precision for diagnostic wearable integration.
Switzerland
Specialized pharmaceutical manufacturing and medical diagnostics production concentrate high-precision thermochromic applications. Swissmedic validation protocols extend supplier qualification timelines for cold-chain verification systems. The Basel pharmaceutical packaging corridor anchors regional demand for hybrid reversible-irreversible label architectures.
China
Domestic biologics manufacturing scale-up and vaccine export logistics create first-mover positioning for cryogenic-range indicators. NMPA cold-chain guidelines tighten visual temperature documentation requirements across pharmaceutical distribution. The Yangtze River Delta biopharma cluster concentrates converter capacity for medical-grade microencapsulation lines.
Japan
Diagnostic device manufacturing and healthcare wearable production drive sub-degree precision thermochromic demand. PMDA pharmaceutical distribution standards mandate temperature excursion documentation for biologics shipments. The Kansai region around Osaka hosts precision liquid crystal substrate production for medical-grade applications.
Thermochromic Labels Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where backward-integrated converters capture pharmaceutical-grade volume and regional specialists serve food-packaging and promotional segments. The vendor base organizes around three strategic archetypes: multinational adhesive and label platform extenders, captive liquid crystal substrate producers, and textile-grade ink specialists. Competitive dynamics center on M&A activity targeting microencapsulation capabilities and strategic partnerships bundling temperature indicators with digital authentication layers.
Among North American platform extenders, Avery Dennison Corporation and LCR Hallcrest LLC occupy positions spanning pharmaceutical compliance and industrial safety applications. Chromatic Technologies Inc. exemplifies the specialty converter archetype with proprietary encapsulation expertise. Matsui International anchors the textile-grade segment for wearable healthcare monitoring.
| Leading Market Players |
|---|
| LCR Hallcrest LLC |
| Chromatic Technologies Inc. |
| New Color Chemical Co., Ltd. |
| Inkron Oy |
| OliKrom |
| Matsui International |
| Avery Dennison Corporation |
| Thermographic Measurements Ltd. |
| MCP Industries |
| Others |
Value Network & Pricing Analysis
The Rhine-Main pharmaceutical logistics corridor anchors cost-plus contract structures indexed to specialty dye feedstock indices, with freight volatility from German biologics distribution centers compressing margins for converters lacking backward integration into leuco dye synthesis while amplifying price differentiation between forensic-grade medical indicators and economy food-packaging labels.
Pricing Analysis
Cost-plus contracts with leuco dye feedstock indexation dominate procurement between German pharmaceutical packagers and specialized indicator converters. Price differentiation rests on FDA 21 CFR Part 211 certification tier and captive microencapsulation capability, with premium medical-grade systems commanding substantial spreads over economy food-packaging alternatives. Cost compression in standard-tier sticker labels is intensifying as REACH reformulation mandates force premature R&D redirection. Food industry retail chains exhibit highest price sensitivity, while biologics manufacturers prioritize lot-traceable documentation over unit cost.
Supply Chain Analysis
Extended payment terms from German pharmaceutical distributors and supply-chain finance facilities from Swiss diagnostic device manufacturers stabilize working capital for qualified converters. Raw material dependencies center on leuco dye synthesis from European and Asian chemical suppliers, liquid crystal substrates from Japanese semiconductor-grade facilities, and bio-based encapsulation resins from German polymer specialists. Single-source vulnerability in medical-grade cholesteric liquid crystal production creates structural risk. Distribution runs through direct procurement relationships between biologics manufacturers and vertically integrated converters, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermochromic label demand follows pharmaceutical capital expenditure cycles, with biologics cold-chain expansion now entering an upswing phase after pandemic-era overcapacity correction.
For Market Incumbents: Insulate market position by deepening captive supply of leuco dye carriers and expanding medical-grade microencapsulation capacity in the Rhine-Main corridor. ECHA microplastic formulation bans threaten converters dependent on petroleum-based encapsulation resins; FDA 21 CFR Part 211 dual-certification investment with EMA Good Distribution Practice creates switching costs that lock in biologics manufacturer relationships. For New Entrants and Emerging Players: Build out textile-grade thermochromic ink capabilities for healthcare wearable applications, where Matsui International's specialization leaves room for regional challengers. Smart textiles for patient skin-contact diagnostics in Switzerland represent the most penetrable white-space segment. Partner with athletic apparel brands for co-development of temperature-monitoring fitness garments as a go-to-market angle. For Investors and Strategic Acquirers: Mid-tier European converters with captive polymer synthesis capabilities and pending REACH-compliant bio-based formulations present the most compelling acquisition target archetype. Long-term viability hinges on regulatory-driven substitution timelines rather than cyclical demand swings. Monitor ECHA substance restriction enforcement intensity as the inflection signal for competitive displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leuco Dye Synthesis | Captive supply of specialty dye feedstock insulates converters from European chemical supplier concentration. |
| Bio-Based Encapsulation Resin Reformulation | Preemptive REACH compliance positions converters ahead of 2030 EU Green Deal chemical restriction deadlines. |
| Hybrid Reversible-Irreversible Label Architecture | Single-label systems satisfying both FDA documentation and patient-facing communication reduce pharmaceutical packager procurement complexity. |
| Smart Textile Ink System Development | Textile-grade thermochromic capabilities unlock margin-rich healthcare wearable segments beyond traditional label markets. |
| Digital Authentication Layer Integration | EU AI Act traceability requirements for high-risk products create bundled demand for temperature indicators with forensic-grade documentation trails. |
Research Methodology
Operator-level perspectives from pharmaceutical packaging procurement managers, diagnostic device regulatory affairs leads, leuco dye synthesis plant managers, and food retail chain category buyers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 21 CFR guidance documents, EMA Good Distribution Practice submissions, ECHA REACH authorization registers, and customs trade data for specialty dye feedstocks. Bottom-up segment sizing triangulated against top-down pharmaceutical cold-chain expenditure estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation modeling spanning product format, application context, end-user industry, and technology platform dimensions. CAGRs derived from regression analysis against biologics shipment volume trajectories and pharmaceutical capital expenditure patterns. Forecast inputs incorporated EU F-Gas Regulation implementation timelines and NMPA cold-chain guideline adoption curves for Chinese vaccine logistics.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by adhesive platform extenders or sudden ECHA enforcement acceleration would shift outcomes. Macroeconomic deviation in pharmaceutical R&D spending, regulatory timeline compression, or breakthrough organic-inorganic hybrid thermochromic technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Classic Organic Pigments Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Cacao Husk Pigment Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Pearl Pigment Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Ultramarine Pigments Market
Dyes and Pigments
Polymer Colorant Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Global Paper Dyes Market
Dyes and Pigments
Phycoerythrin Market
Dyes and Pigments
Inorganic Color Pigments Market