
 Cacao Husk Pigment Market | 2026-2036
Cacao Husk Pigment Market Size, Share, and Industry Trends Forecast 2026-2036
Cacao Husk Pigment Market Analytics
West African cocoa processing cooperatives is realigning toward valorization streams as bean prices pressure traditional margins. Barry Callebaut leverages its integrated supply chain to secure husk volumes across origin countries. Cargill sustains R&D programs targeting standardized color stability in natural extracts. ADM anchors North American distribution through its food ingredient network.
Cacao husk pigment comprises anthocyanin and flavonoid compounds extracted from the fibrous outer shell of Theobroma cacao beans, typically yielding brown to reddish-brown colorants with pH-sensitive tinctorial properties used primarily for food and cosmetic coloring applications. The extraction process involves aqueous or solvent-based separation followed by concentration and drying to achieve powder or liquid extract forms with defined color intensity metrics. Natural colorant formulations command premium positioning in food additive applications as clean-label mandates intensify across retail channels. Powder form dominates current volume due to extended shelf stability and ease of logistics handling, while liquid extract variants are gaining traction in cosmetic ingredient segments where solubility requirements favor aqueous delivery systems.
EU REACH regulation and the EU Green Deal framework restrict synthetic azo dye usage in consumer products, directly expanding addressable demand for botanical colorant alternatives. The US FDA maintains Generally Recognized As Safe pathways for natural colorants but requires batch certification exemptions that shape formulation documentation burdens. Brazil's ANVISA and the US FDA both influence import compliance structures for cosmetic ingredient applications. Stakeholders must monitor evolving colorant purity standards and origin certification requirements as supply chain traceability becomes a procurement gate.
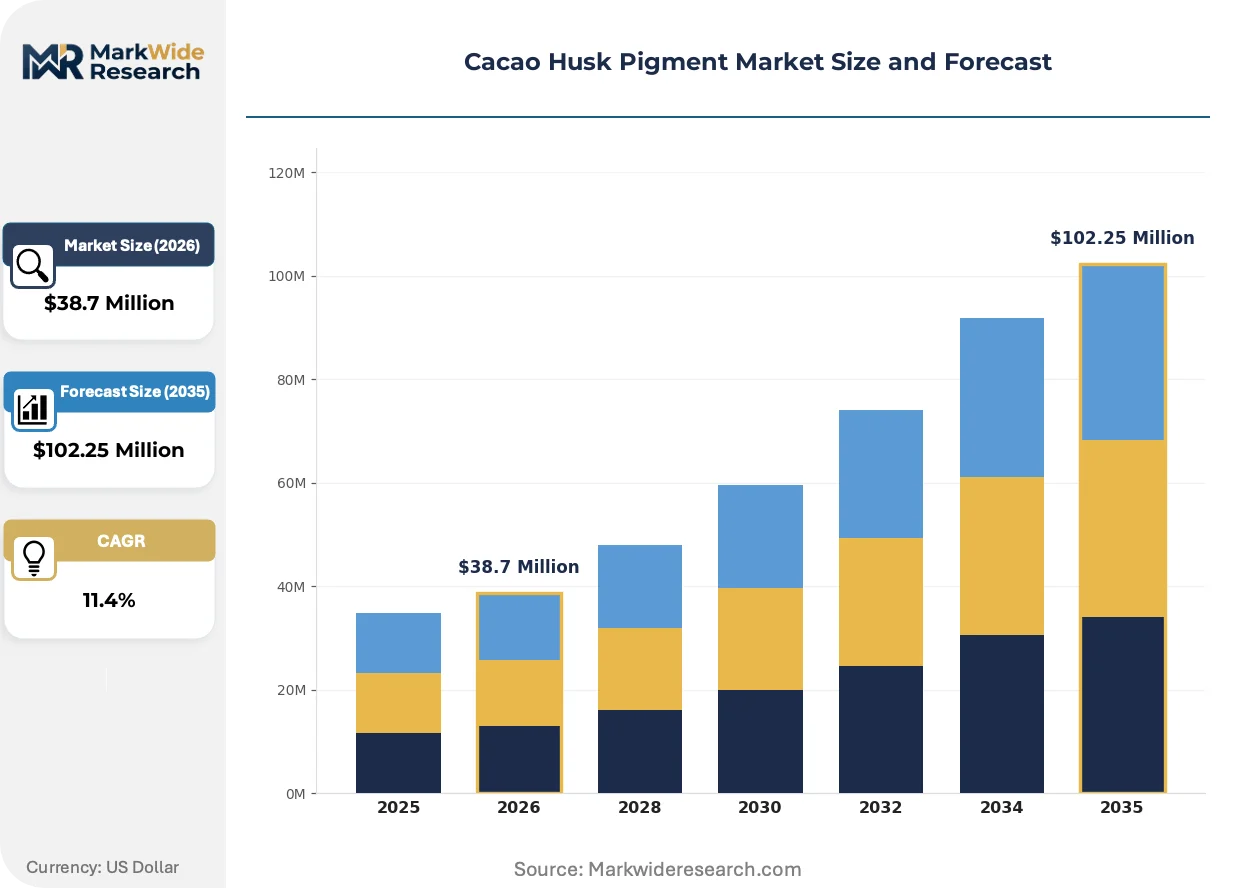
Market Dynamics
EU REACH and the EU Green Deal framework are compressing synthetic azo dye availability while cocoa processing clusters in Brazil and West Africa generate concentrated husk feedstock for pigment extraction. This regulatory-supply intersection is restructuring procurement geography and extraction capacity deployment.
Growth Catalysts
- REACH dye restrictions:The EU Green Deal framework bans specific synthetic azo compounds in consumer products, forcing cosmetic and food formulators toward botanical colorant alternatives with documented safety profiles.
- Brazilian processing concentration:Cocoa processing clusters in Bahia and São Paulo states generate abundant husk feedstock within tight radiuses, reducing collection logistics costs for extraction facilities.
- Clean-label retail mandates:Major European grocery retailers now require natural ingredient declarations on packaged foods, directly expanding formulation demand for pH-stable brown colorants.
Market Restraints
- Bean price volatility:Cocoa futures on ICE exchange swing with West African weather patterns, compressing processor margins and diverting husk from pigment streams toward lower-value agricultural applications.
- Extraction yield limits:Aqueous and solvent-based separation methods recover only fractional anthocyanin content from fibrous husks, constraining unit economics against synthetic dye production scales.
- Spirulina and beetroot substitution:Alternative natural colorants with established GRAS status and broader pH stability ranges compete for clean-label formulation slots in beverage applications.
Strategic Opportunities
- Underpenetrated North American cosmetics:US FDA batch certification exemptions for natural colorants create faster market entry pathways than EU novel food processes, attracting extraction capacity investment.
- Encapsulation technology convergence:Liposome and microencapsulation methods paired with husk pigment extracts are opening stability-enhanced cosmetic ingredient applications with extended shelf performance.
- Direct-to-manufacturer platforms:Digital procurement channels are collapsing traditional ingredient distributor markups, allowing extraction cooperatives to capture margin previously lost to intermediaries.
Industry Challenges
- Color standardization skill scarcity:Formulation chemists with expertise in pH-sensitive natural colorant behavior remain concentrated in European cosmetic hubs, limiting quality control capabilities in origin-country processing facilities.
- Organic certification timeline compression:EU organic processing standards require multi-year field conversion and documentation audits that delay premium pricing realization for West African cooperative ventures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cacao Husk Pigment Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colorant, Synthetic Colorant, Organic Pigment, Industrial Dye End User: Food Industry, Cosmetic Manufacturers, Textile Industry, Paint Producers Application: Food Additive, Cosmetic Ingredient, Fabric Dye, Coating Agent Form: Powder, Liquid Extract, Granules, Concentrates |
| Companies Covered | ADM, Cargill, Olam, Barry Callebaut, Kemin Industries, Döhler, Naturex, Givaudan, Symrise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cacao Husk Pigment Market Evolving Landscape
Supercritical CO2 extraction systems are displacing conventional solvent methods across natural colorant processing, altering capital requirements and extraction purity benchmarks simultaneously. This technology rotation is compressing incumbent equipment depreciation schedules while opening new application segments.
Supercritical CO2 extraction technology is electrifying pigment recovery efficiency from cacao husk matrices by operating at tunable temperature-pressure points that preserve anthocyanin integrity. European cosmetic ingredient manufacturers are adopting these systems at accelerated replacement cycles, retiring solvent-based equipment ahead of depreciation schedules. The technology is electrifying competitive positioning among extraction specialists by enabling pharmaceutical-grade purity claims that aqueous methods cannot match.
EU REACH annex amendments are systematically restricting synthetic dye molecular structures in consumer-facing products, forcing reformulation across food and cosmetic categories. Industrial consequence includes mandatory supply chain requalification and novel food dossier preparation for botanical alternatives. Cosmetic ingredient applications face the most acute compliance burden, with formulators accelerating natural colorant validation programs to maintain product registration continuity.
Buyer concentration among clean-label retail chains is consolidating procurement negotiation power and compressing supplier margins across natural ingredient categories. Direct sourcing relationships between extraction cooperatives and European cosmetic houses are displacing traditional distributor intermediaries in colorant procurement. Brazil-based processing clusters show the most visible channel restructuring, with origin-country facilities establishing dedicated export relationships bypassing regional trading houses.
Cacao Husk Pigment Market Segmentation
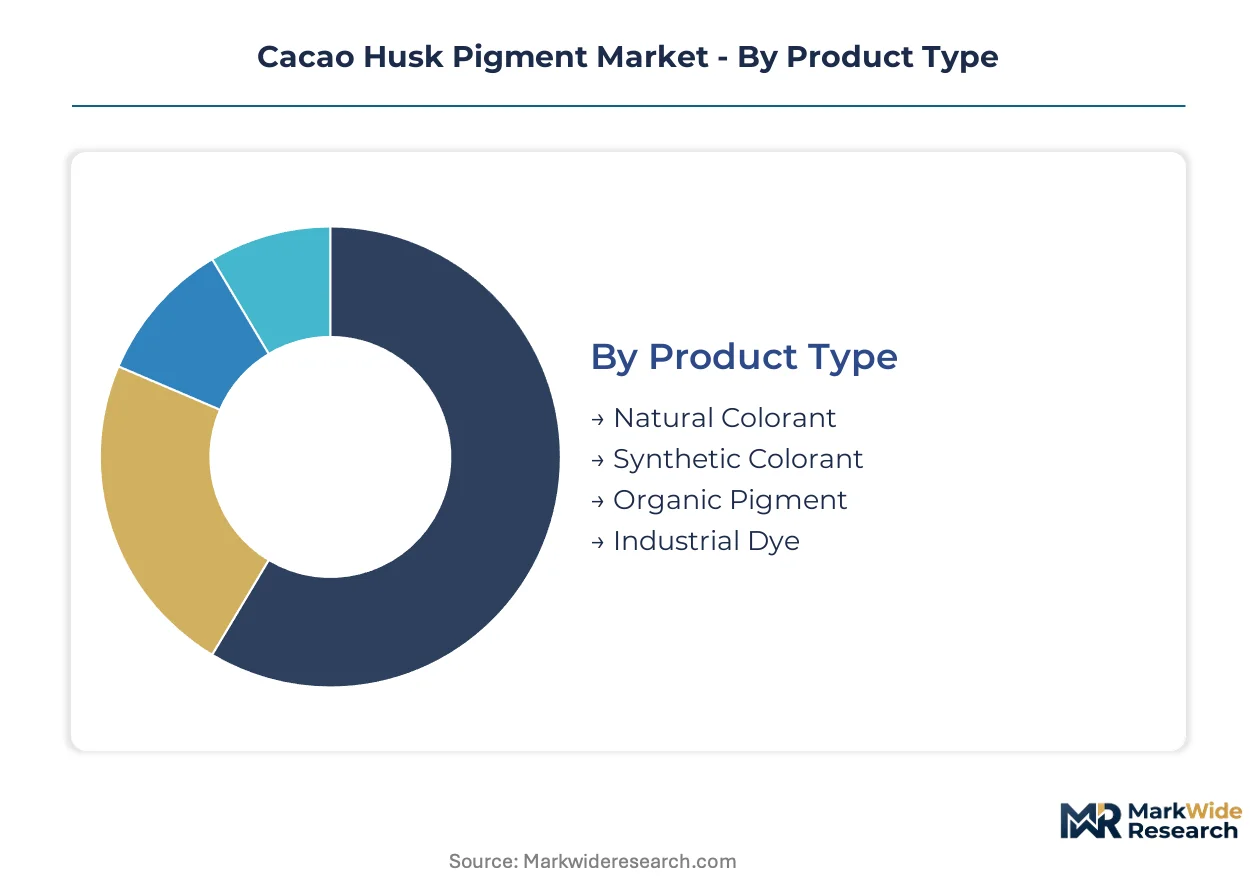
Cacao husk pigment applications fragment across distinct technical specifications and purity thresholds that reshape procurement patterns. Formulators select grades based on end-use regulatory burdens, with cosmetic and food additive pathways demanding divergent certification documentation.
Product Type:
Standardization intensity varies from commodity industrial dyes to bespoke organic certifications that command documentation premiums.
- Natural Colorant:Anthocyanin and flavonoid compounds extracted from Theobroma cacao husks yield brown to reddish-brown colorants with pH-sensitive properties. European cosmetic manufacturers concentrate procurement here as REACH dye restrictions eliminate synthetic azo alternatives from formulation palettes.
- Synthetic Colorant:Petroleum-derived molecular structures with standardized tinctorial strength and batch-to-batch consistency. Demand concentrates in industrial coating applications where regulatory scrutiny remains lighter and cost minimization dominates procurement criteria.
- Organic Pigment:Certified cultivation and extraction protocols with multi-year field conversion documentation. Brazilian processing clusters in Bahia generate concentrated feedstock for premium positioning.
- Industrial Dye:Bulk volume applications in textile and coating sectors with minimal purity requirements. Price-sensitive procurement from Asian manufacturing hubs.
Leading the category by volume: Natural Colorant. Expanding most quickly: Organic Pigment.
End User:
Margin structures diverge sharply between regulated consumer-facing applications and industrial bulk consumption.
- Food Industry:Clean-label retail mandates from European grocery chains now require natural ingredient declarations on packaged foods. Formulators source pH-stable brown colorants for bakery and confectionery applications.
- Cosmetic Manufacturers:EU REACH annex amendments systematically restrict synthetic dye molecular structures, forcing accelerated natural colorant validation programs. Liposome encapsulation methods paired with husk extracts open stability-enhanced ingredient applications.
- Textile Industry:Lower-margin bulk dye consumption with established synthetic supply chains. Natural pigment penetration remains limited by cost competitiveness.
- Paint Producers:Architectural and industrial coating applications where UV stability requirements favor synthetic alternatives.
Cosmetic Manufacturers capture the steepest expansion trajectory. Food Industry maintains volume leadership.
Application:
Technical performance requirements separate high-specification cosmetic pathways from commodity food and industrial uses.
- Food Additive:GRAS pathway documentation for US FDA batch certification exemptions shapes supplier selection. Powder forms dominate for extended shelf stability in retail distribution.
- Cosmetic Ingredient:Solubility requirements favor liquid extract variants where aqueous delivery systems integrate with formulation chemistries. Supercritical CO2 extraction enables pharmaceutical-grade purity claims.
- Fabric Dye:Wash-fastness and light-stability specifications constrain natural pigment adoption in apparel applications.
- Coating Agent:Industrial protective coatings with durability requirements that synthetic dyes satisfy more economically.
Cosmetic Ingredient shows the fastest climb. Food Additive anchors current volume.
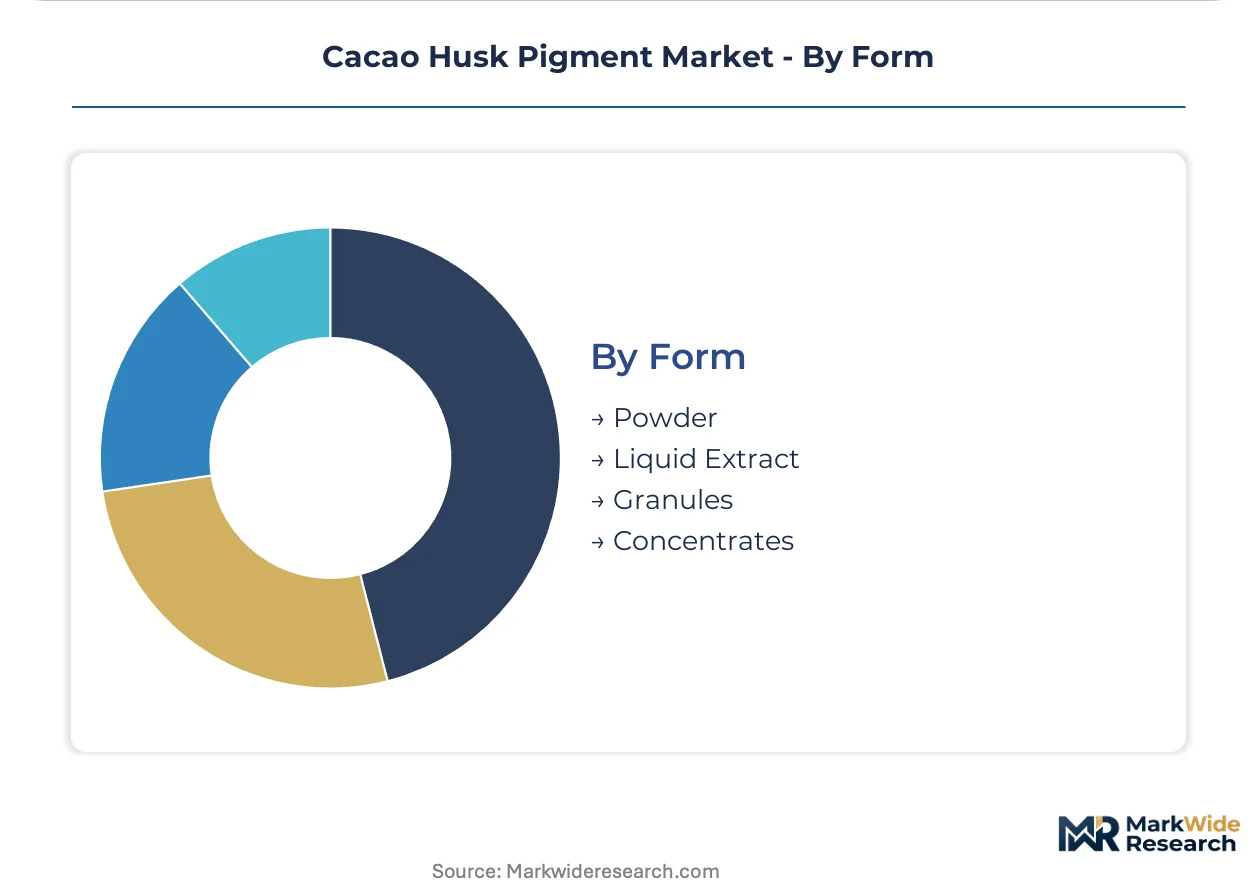
Form:
Logistics economics and shelf-life requirements dictate format selection across downstream applications.
- Powder:Dried extract with defined color intensity metrics enables extended storage and simplified freight handling. Dominates food additive procurement.
- Liquid Extract:Aqueous or solvent-based concentrates with immediate solubility for cosmetic formulation workflows. Gaining share in ingredient manufacturing.
- Granules:Intermediate processing format with controlled dissolution rates for specific industrial applications.
- Concentrates:High-potency reduced-volume extracts for premium cosmetic and pharmaceutical-grade specifications.
Powder leads by shipment volume. Liquid Extract gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian cocoa processing clusters in Bahia and São Paulo states anchor feedstock availability for pigment extraction, while European regulatory pressure from REACH and the EU Green Deal redirects procurement geography toward origin-country facilities.
Brazil
Cocoa processing cooperatives in Bahia state generate concentrated husk volumes within tight collection radiuses. ANVISA regulates cosmetic ingredient imports, shaping compliance documentation for export-bound extracts. São Paulo-based facilities are deploying supercritical CO2 extraction capacity to serve European cosmetic manufacturer procurement.
Germany
Cosmetic formulators in Hamburg and Frankfurt procurement hubs source pH-stable brown colorants for clean-label product lines. ECHA administers REACH annex amendments that systematically restrict synthetic azo dyes. Bavarian extraction technology suppliers are retrofitting solvent-based equipment with CO2 systems ahead of depreciation schedules.
United States
Food and beverage manufacturers in Chicago and New Jersey seek GRAS-certified natural colorants for retail distribution. FDA batch certification exemptions for natural colorants accelerate supplier qualification timelines. California-based cosmetic ingredient distributors are establishing direct sourcing relationships with Brazilian extraction cooperatives.
France
Luxury cosmetic houses in Paris and Grasse reformulate product lines to eliminate restricted synthetic dyes. ANSM enforces cosmetic safety standards that elevate documentation requirements for botanical extracts. Lyon-area ingredient traders are consolidating procurement negotiation power across natural colorant categories.
Ivory Coast
Cocoa processing cooperatives in Abidjan and San-Pédro reorient toward valorization streams as bean price volatility compresses traditional margins. The country's national agricultural regulator monitors export certification for processed derivatives. West African facilities are piloting aqueous extraction methods with European technical assistance programs.
Cacao Husk Pigment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue organic certification and encapsulation technology partnerships. The vendor base stratifies across integrated cocoa processors, specialized extraction firms, and diversified ingredient suppliers. Three archetypes dominate: vertically integrated chocolate manufacturers securing captive husk supply, independent extraction specialists licensing supercritical technology, and broad-line ingredient distributors anchoring regional logistics. Competitive moves center on backward integration into origin-country processing capacity and technology licensing agreements for purity-enhanced extraction methods.
Among integrated cocoa processors, Barry Callebaut and Cargill exemplify the captive-supply archetype through their Brazil and West African processing footprints. ADM represents the distribution-anchored tier, leveraging North American food ingredient networks to aggregate demand for natural colorant procurement. These three occupy positions that reflect divergent strategic bets on origin-country extraction versus regional formulation support.
| Leading Market Players |
|---|
| ADM |
| Cargill |
| Olam |
| Barry Callebaut |
| Kemin Industries |
| Döhler |
| Naturex |
| Givaudan |
| Symrise |
| Others |
Value Network & Pricing Analysis
EU clean-label procurement mandates from major grocery retailers and cosmetic formulators are compressing supplier margins and forcing extraction facilities to absorb certification documentation costs that synthetic dye producers bypass. This demand-side specification tightening propagates backward through Brazilian and West African processing clusters, reshaping how origin-country facilities price organic versus conventional pigment grades.
Pricing Analysis
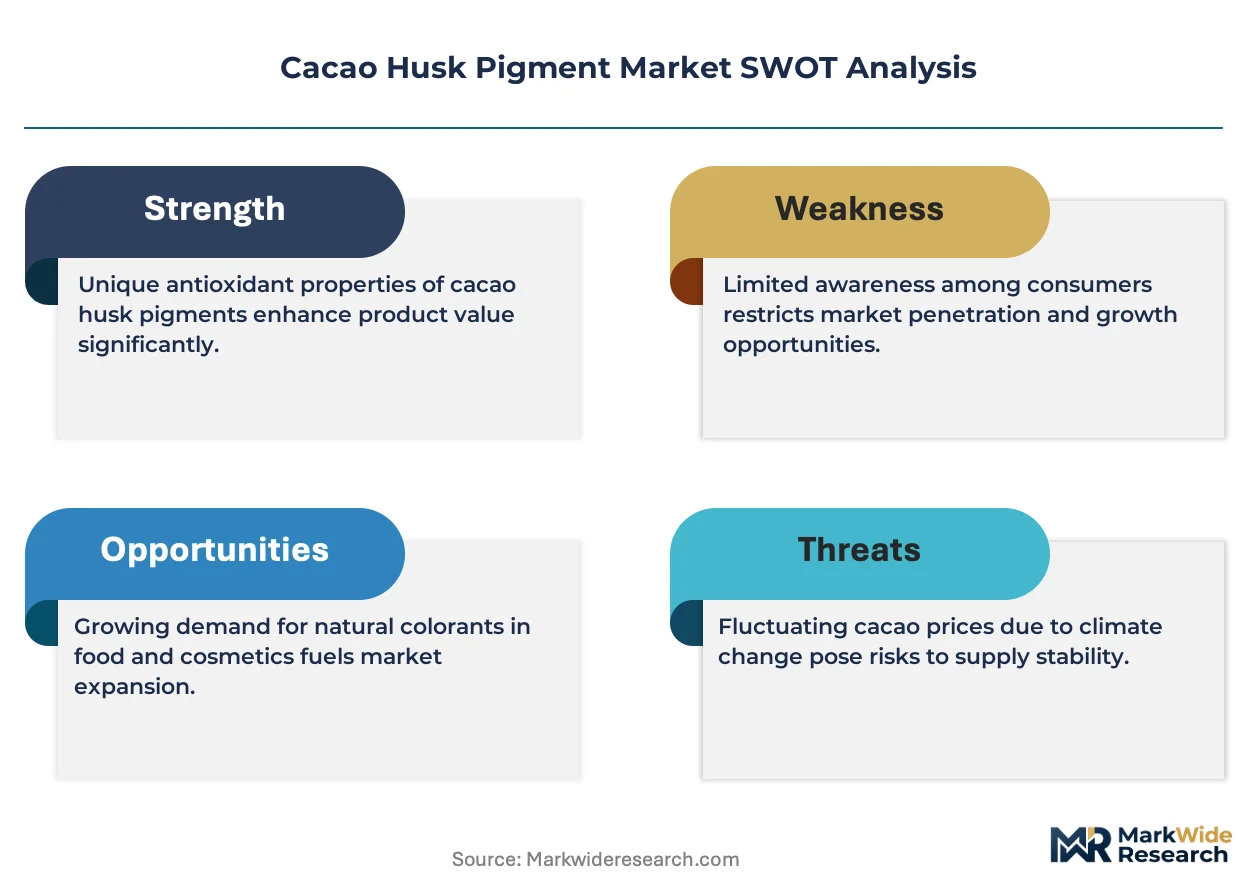
Certification bundling separates quoted pigment prices, with organic-grade extracts commanding documentation premiums while conventional natural grades compete on volume scale. Three-tier pricing structure across organic-certified, standard natural, and industrial commodity levels reflects extraction method differentiation—supercritical CO2 systems justify premium positioning against aqueous extraction outputs. Pricing pressure stems from spirulina and beetroot substitution in beverage applications, compressing brown colorant premiums. Food additive buyers exhibit highest price sensitivity due to thin retail margins, while cosmetic manufacturers absorb certification premiums for REACH compliance assurance.
Supply Chain Analysis
Freight economics from Bahia and São Paulo processing clusters to European ports dominate landed cost structures for Brazilian-origin pigment, while West African routes through Abidjan face container availability volatility. Supply concentrates in Brazil, Ivory Coast, and Ghana as cocoa processing geography dictates husk feedstock availability. Raw material flows draw from cocoa bean processing volumes, agricultural collection logistics, and seasonal harvest timing. Single-source vulnerability runs through Brazilian cluster concentration as ANVISA export documentation bottlenecks compound logistics risk. Distribution runs through direct-to-manufacturer digital platforms that displace traditional ingredient distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into origin-country extraction capacity has become the defining competitive race, with players securing captive husk supply in Brazil and West Africa to control feedstock access and certification timelines.
For Market Incumbents: Deepen supercritical CO2 extraction technology deployment to defend pharmaceutical-grade purity positioning against aqueous-method competitors. Secure multi-year offtake agreements with Bahia processing cooperatives before organic certification timelines compress available premium feedstock. Barry Callebaut and Cargill already anchor this strategy through integrated Brazil footprints; laggards risk husk diversion to agricultural applications during bean price spikes. For New Entrants and Emerging Players: Direct-to-manufacturer digital procurement platforms offer the lowest-friction entry vector, collapsing traditional distributor markups and enabling origin-country extraction cooperatives to capture margin previously lost to intermediaries. Target underpenetrated North American cosmetic ingredient applications where FDA batch certification exemptions accelerate supplier qualification versus EU novel food pathways. Liposome encapsulation technology partnerships provide differentiated positioning in stability-enhanced cosmetic formulations. For Investors and Strategic Acquirers: The window for entry favors extraction specialists with ANVISA-compliant Brazil facilities and supercritical CO2 equipment already operational. Long-term viability hinges on organic certification pipeline depth and direct relationships with European cosmetic houses bypassing regional trading houses. Watch EU REACH annex amendment timing as the inflection signal—accelerated synthetic dye restrictions would trigger immediate procurement requalification demand and valuation step-ups for compliant natural colorant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origin Processing | Captive husk supply in Brazil and West Africa secures feedstock access against bean price volatility and agricultural diversion. |
| Supercritical CO2 Technology Licensing | Pharmaceutical-grade purity claims from CO2 extraction enable premium positioning in EU cosmetic ingredient procurement. |
| Organic Certification Pipeline Investment | Multi-year field conversion documentation unlocks premium pricing tiers as EU organic processing standards tighten. |
| Direct-to-Manufacturer Platform Launch | Digital procurement channels displace distributor intermediaries and capture margin compression in colorant categories. |
| Encapsulation Technology Partnership | Liposome and microencapsulation methods extend shelf stability and open cosmetic formulation applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across extraction facility operators, cosmetic formulation chemists, cocoa processing cooperative managers, and European ingredient procurement directors. ECHA REACH annex amendments, ANVISA export documentation requirements, and FDA GRAS pathway records provided regulatory validation. Customs records from Brazilian and West African export authorities tracked pigment extract flow volumes. Bottom-up facility capacity estimates triangulated against top-down end-use demand modeling across food additive and cosmetic ingredient applications.
Segment-level granularity modeled product type across natural, synthetic, organic, and industrial grades; end user across food, cosmetic, textile, and paint sectors; application across food additive, cosmetic ingredient, fabric dye, and coating uses; and form across powder, liquid extract, granules, and concentrates. CAGRs derived from regression analysis against cocoa processing volume forecasts and regulatory restriction timelines. Extraction yield assumptions, pH stability performance curves, and supercritical CO2 adoption rates informed industry-specific forecast inputs across the projection horizon.
The model holds under stable EU regulatory enforcement trajectories and continued clean-label retail mandate expansion; deviation in cocoa futures volatility or REACH amendment acceleration would shift pigment availability and pricing assumptions. Stakeholders should weight assumptions against their own operating context and feedstock security positions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Azo Pigments Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Light Interference Pigments Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Brilliant Blue FCF Colors Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
Organic Lake Pigments Market
Dyes and Pigments
Global Cosmetic Pigments Market
Dyes and Pigments
Thermochromic Labels Market
Dyes and Pigments
Pearlescent Pigments Market
Dyes and Pigments
White Pigment Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market
Dyes and Pigments
Ultramarine Pigments Market