
 Riboflavin Pigment Market | 2026-2036
Riboflavin Pigment Market Size, Share, and Industry Trends Forecast 2026-2036
Riboflavin Pigment Market Analytics
The riboflavin pigment market is pivoting on a widening split between pharmaceutical-grade specifications and commodity feed-grade volumes. Chr. Hansen Holding A/S leverages its microbial fermentation expertise to dominate high-purity applications for food and nutraceutical clients. DSM-Firmenich anchors European supply through integrated biotechnology platforms that sustain consistent output across vitamin B2 derivatives. BASF SE competes on synthetic process scale, occupying bulk positions in industrial feed additive channels where cost efficiency determines procurement decisions.
Riboflavin pigment denotes a yellow water-soluble coloring agent derived from vitamin B2, typically manufactured through microbial fermentation of Ashbya gossypii or chemically synthesized, with absorption maxima near 445 nm and 375 nm in aqueous solution. Food and beverage applications command premium positioning due to stringent purity thresholds and clean-label substitution trends displacing azo dyes. Feed additives represent the volume anchor, while pharmaceutical-grade riboflavin 5'-phosphate concentrates margin pools through compounding requirements in parenteral nutrition formulations. Powder form dominates logistics and stability profiles across all channels, though liquid dispersions are gaining traction in beverage manufacturing for direct dosing integration.
EMA pharmaceutical guidelines and FDA color additive regulations shape product standards for human consumption segments, while REACH compliance governs chemical manufacturing and import access across European markets. China's NMPA and GB food safety standards enforce domestic purity benchmarks that influence export qualification for fermentation-origin material. Stakeholders must monitor evolving biotechnology patent landscapes and fermentation yield improvements that could redraw cost structures between synthetic and bio-based production routes.
Market Dynamics
Fermentation yield improvements are compressing cost structures between bio-based and synthetic riboflavin routes, while EU REACH chemical standards and China's NMPA purity mandates force simultaneous compliance upgrades across export supply chains.
Growth Catalysts
- EU Green Deal chemical substitution mandates:Clean-label food manufacturers are reformulating with riboflavin to displace azo dyes under tightening environmental frameworks.
- Fermentation biotechnology advances:Ashbya gossypii strain optimization is lifting yields and narrowing cost gaps with synthetic production.
- China:Domestic pharmaceutical and feed additive producers are scaling fermentation capacity to capture import substitution opportunities.
Market Restraints
- Feedstock volatility:Corn-derived carbohydrate costs for fermentation fluctuate with agricultural commodity cycles.
- Supply concentration:A limited number of microbial fermentation specialists control high-purity pharmaceutical-grade output.
- Technical limitation:Light instability of riboflavin in transparent packaging restricts beverage applications without encapsulation.
Strategic Opportunities
- Underpenetrated nutraceuticals:Fortified functional foods in Southeast Asia offer expansion vectors for vitamin B2 derivatives.
- Converging technologies:Encapsulation with modified starches is opening shelf-stable beverage applications previously closed to riboflavin.
- Channel innovation:Direct-to-manufacturer liquid dispersion platforms are bypassing traditional distributor networks in beverage manufacturing.
Industry Challenges
- Specialized fermentation expertise:Industrial microbiologists capable of optimizing Ashbya gossypii strains remain scarce relative to demand.
- Dual certification timelines:Simultaneous FDA color additive and EMA pharmaceutical qualification processes extend product launch cycles.
- IP licensing complexity:Proprietary strain patents and process patents create overlapping royalty obligations in bio-based production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Riboflavin Pigment Market |
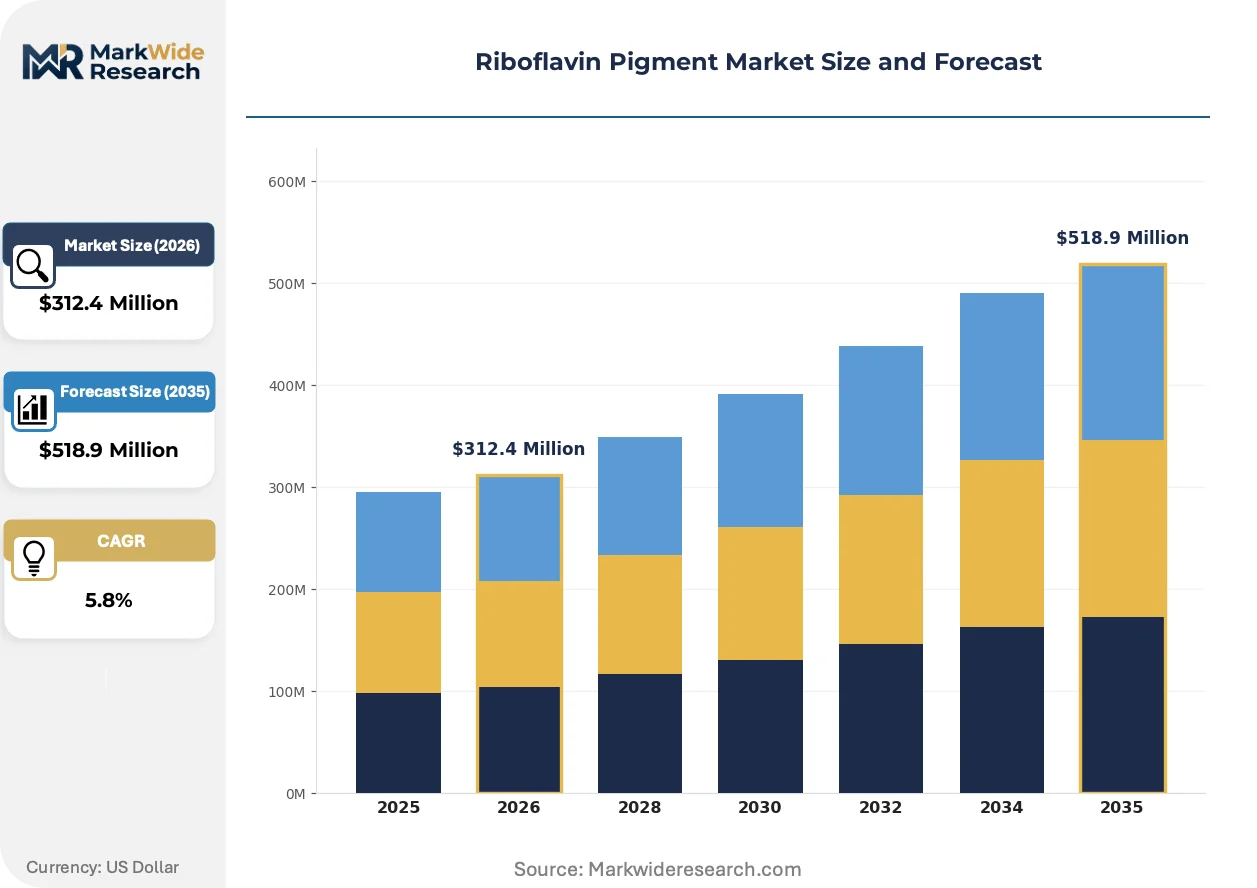
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Riboflavin 5'-Phosphate, Riboflavin-Na, Riboflavin 3'-Phosphate, Riboflavin Acetate Application: Food & Beverage, Feed Additives, Pharmaceuticals, Cosmetics Form: Powder, Liquid, Granule, Crystal End User: Food Manufacturers, Nutraceutical Companies, Cosmetic Producers, Animal Feed Suppliers |
| Companies Covered | Chr. Hansen Holding A/S, Symrise A.G., DSM-Firmenich, Shanghai Acebright Pharmaceuticals Group, Hubei Guangji Pharmaceutical, BASF SE, Sensient Technology Corporation, Advanced Technology and Industrial Co. Ltd., Xinfa Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Riboflavin Pigment Market Evolving Landscape
Biotechnology patent landscapes and regulatory chemical substitution mandates are simultaneously reshaping production economics and end-use specifications across food, feed, and pharmaceutical channels.
Continuous fermentation systems with real-time metabolite monitoring are electrifying yield consistency in microbial riboflavin manufacturing. Pharmaceutical-grade producers are adopting these platforms to reduce batch-to-batch variation. The technology is compressing quality control costs while enabling tighter specification compliance for parenteral nutrition applications.
REACH authorization requirements for synthetic food colorants are forcing reformulation investments across European food manufacturing. Manufacturers face substance-by-substance evaluation timelines that extend product development cycles. The regulatory pressure is accelerating clean-label substitution with fermentation-derived riboflavin in confectionery and dairy segments.
Direct specification contracts between pigment suppliers and multinational beverage brands are displacing traditional distributor-mediated procurement in North America and Western Europe. Large-scale manufacturers are consolidating supplier bases to secure volume commitments and technical service integration. The buying-pattern shift is most visible in carbonated soft drink and sports beverage verticals where color consistency drives brand equity.
Riboflavin Pigment Market Segmentation
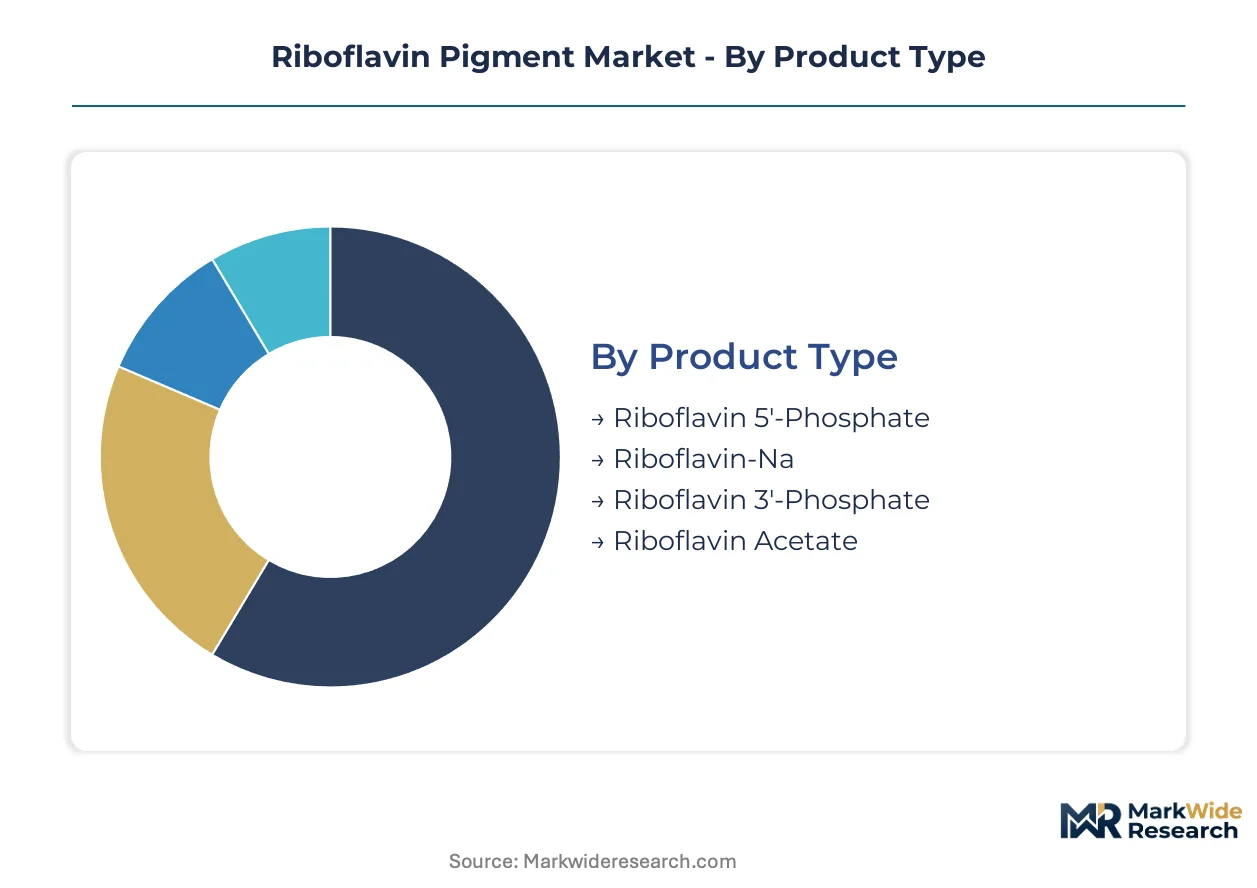
Riboflavin pigment segmentation reveals divergent purity requirements and supply chain configurations across pharmaceutical, food, and feed channels. Each category carries distinct technical specifications that determine manufacturing process selection and regulatory compliance pathways.
Product Type:
Supply concentration in high-purity derivatives creates tiered manufacturing capabilities among fermentation specialists and synthetic producers.
- Riboflavin 5'-Phosphate:The phosphorylated ester form required for parenteral nutrition formulations and pharmaceutical compounding. Demand concentrates in European pharmaceutical manufacturing where EMA guidelines enforce strict impurity profiles for injectable applications, with qualification timelines extending procurement cycles for new suppliers.
- Riboflavin-Na:The sodium salt variant optimized for enhanced water solubility in beverage fortification and liquid nutritional supplements. China's NMPA-certified producers are scaling fermentation capacity to serve domestic functional food manufacturers seeking clean-label vitamin fortification alternatives.
- Riboflavin 3'-Phosphate:The positional isomer with distinct absorption characteristics used in specialized diagnostic and research applications.
- Riboflavin Acetate:The acetylated derivative offering improved lipophilicity for cosmetic formulations and oil-based nutritional products.
Today's leader: Riboflavin 5'-Phosphate. Tomorrow's challenger: Riboflavin-Na.
Application:
Cost tier differentiation separates premium human-consumption segments from commodity feed-grade volumes, with regulatory burden determining margin capture.
- Food & Beverage:Clean-label coloring and fortification applications governed by FDA color additive regulations and EU REACH chemical substitution mandates. Powder forms dominate bakery and confectionery while liquid dispersions penetrate carbonated beverage manufacturing for direct dosing integration.
- Feed Additives:The volume anchor where synthetic process economics compete with fermentation yield improvements for cost-sensitive poultry and swine nutrition. China's domestic producers are displacing imports through scaled fermentation platforms serving regional animal agriculture.
- Pharmaceuticals:Parenteral nutrition and oral supplement formulations requiring compendial-grade material with documented batch-to-batch consistency.
- Cosmetics:Topical applications leveraging riboflavin's photoluminescent properties in skincare and hair care formulations.
Feed Additives command present volume. Food & Beverage captures expanding value.
Form:
Logistics infrastructure and stability requirements favor powder dominance, though liquid formats are gaining traction in automated manufacturing environments.
- Powder:The standard format for dry blending in bakery premixes, feed compounding, and tablet manufacturing, offering extended shelf stability and bulk handling efficiency.
- Liquid:Direct-to-dispersion platforms for beverage manufacturing where color consistency and dosing precision drive brand equity, particularly in North American sports drink production.
- Granule:Free-flowing agglomerated particles optimized for reduced dust generation in high-speed packaging operations.
- Crystal:High-purity crystalline forms for pharmaceutical API requirements and analytical standard preparation.
Powder retains logistical dominance. Liquid formats are climbing the fastest in beverage channel penetration.
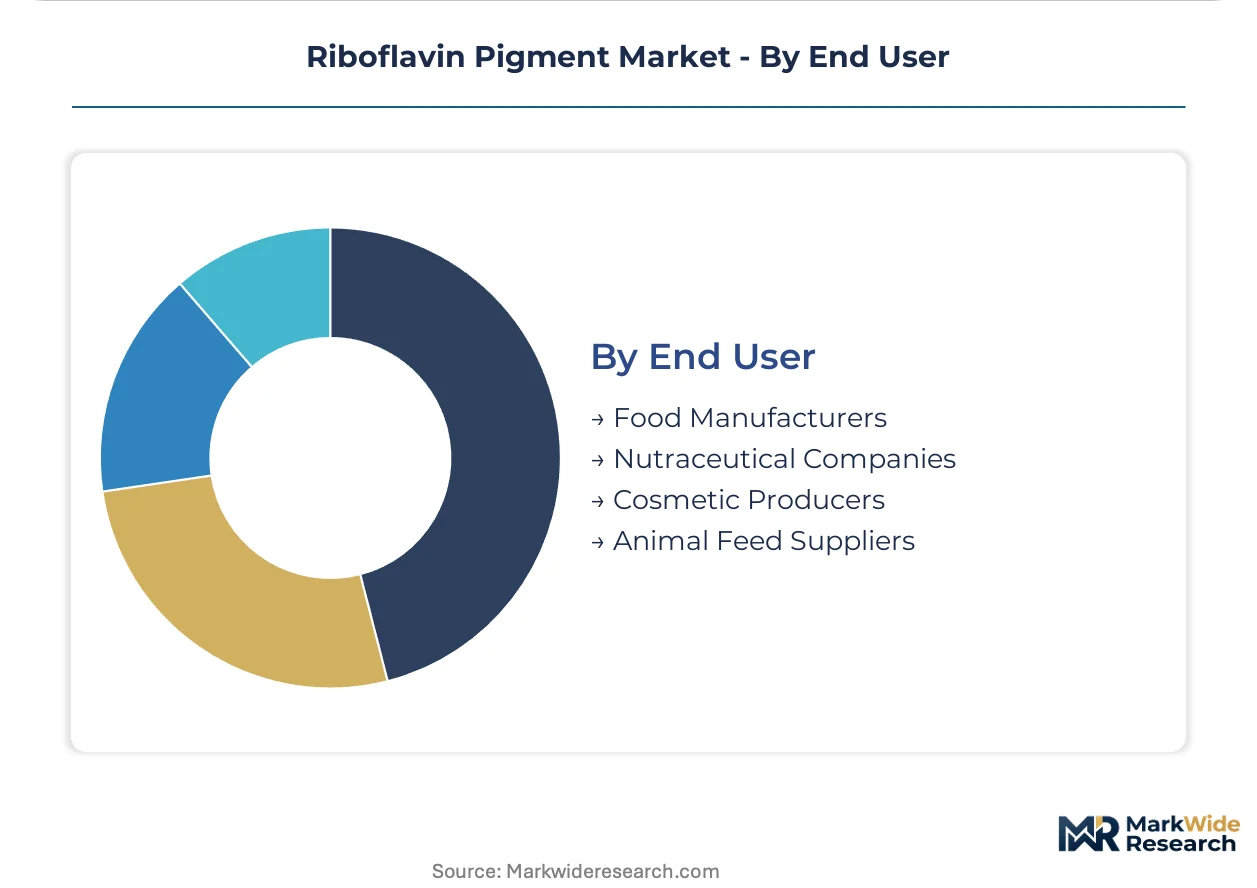
End User:
Customer type determines technical service intensity, with direct specification contracts displacing distributor relationships among large-scale manufacturers.
- Food Manufacturers:Multinational brands consolidating supplier bases to secure volume commitments and integrated color matching services, particularly in European confectionery and dairy reformulation projects.
- Nutraceutical Companies:Functional food and dietary supplement producers driving demand for encapsulated and stabilized forms to address riboflavin's light sensitivity in transparent packaging.
- Cosmetic Producers:Formulators seeking photoluminescent and antioxidant properties in premium skincare lines.
- Animal Feed Suppliers:Cost-optimized procurement from synthetic and fermentation sources with specification flexibility around minor impurity profiles.
Food Manufacturers anchor current procurement consolidation. Nutraceutical Companies represent the steepest expansion trajectory for value-added derivatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands fermentation-based output volume while Germany anchors European pharmaceutical-grade specifications, creating divergent supply chain configurations across major consumption centers.
China
Domestic pharmaceutical and feed additive producers scale Ashbya gossypii fermentation platforms to capture import substitution opportunities. NMPA purity mandates and GB food safety standards enforce export qualification benchmarks that shape regional trade flows. Shandong Peninsula clusters host scaled biomanufacturing operations serving both domestic functional food manufacturers and international pharmaceutical clients.
Germany
EMA pharmaceutical guidelines drive stringent impurity profile requirements for parenteral nutrition formulations. REACH chemical standards and EU Green Deal substitution mandates accelerate clean-label reformulation investments across confectionery and dairy manufacturing. North Rhine-Westphalia biotechnology corridors concentrate microbial fermentation expertise for high-purity vitamin B2 derivatives.
United States
FDA color additive regulations shape procurement specifications for beverage fortification and dietary supplement applications. Direct specification contracts between pigment suppliers and multinational brands displace traditional distributor networks in carbonated soft drink manufacturing. Midwest agricultural processing centers supply corn-derived carbohydrate feedstocks for regional fermentation operations.
India
FSSAI fortification standards expand addressable demand for vitamin B2 derivatives in edible oil and wheat flour programs. CDSCO pharmaceutical guidelines govern injectable-grade material qualification for domestic parenteral nutrition compounding. Maharashtra pharmaceutical manufacturing clusters scale fermentation capacity to serve Southeast Asian export markets.
Japan
METI biotechnology promotion frameworks support strain optimization research for enhanced fermentation yields. PMDA pharmaceutical standards enforce batch-to-batch consistency documentation for clinical nutrition applications. Kansai region chemical manufacturers maintain synthetic process capabilities for industrial feed additive supply.
Riboflavin Pigment Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade specifications, while mid-tier fermentation specialists compete on yield optimization and regional feed additive supply. The vendor base stratifies across integrated biotechnology platforms, synthetic chemical producers, and specialized microbial fermentation houses. Three archetypes dominate: European nutraceutical-grade specialists, Chinese scaled fermentation operators, and diversified chemical conglomerates with vitamin B2 derivative portfolios. Competitive moves concentrate on backward integration into carbohydrate feedstock supply and technology licensing for continuous fermentation systems.
Within the high-purity fermentation tier, Chr. Hansen Holding A/S and DSM-Firmenich exemplify European biotechnology platform operators. BASF SE occupies a position among diversified chemical producers competing on synthetic process scale. Shanghai Acebright Pharmaceuticals Group and Hubei Guangji Pharmaceutical represent Chinese scaled fermentation specialists capturing domestic volume expansion. These anchors illustrate the geographic split between specification-driven European supply and cost-optimized Asian output.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Symrise A.G. |
| DSM-Firmenich |
| Shanghai Acebright Pharmaceuticals Group |
| Hubei Guangji Pharmaceutical |
| BASF SE |
| Sensient Technology Corporation |
| Advanced Technology and Industrial Co. Ltd. |
| Xinfa Pharmaceutical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
EU Green Deal chemical substitution mandates gate qualified supply access and premium-tier pricing power, compressing margins for non-compliant synthetic producers while elevating fermentation-derived riboflavin premiums. Buyers face bifurcated procurement economics between REACH-certified European supply and cost-optimized Asian fermentation output.
Pricing Analysis
Capacity additions in China are reshaping price floors for feed-grade material while pharmaceutical-grade premiums widen. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade levels separates EMA-compliant producers from NMPA-certified and commodity synthetic suppliers. Cost compression in feed-grade synthetic riboflavin is intensifying because Ashbya gossypii yield improvements narrow fermentation cost gaps. Animal feed suppliers exhibit highest price sensitivity; parenteral nutrition compounders show lowest.
Supply Chain Analysis
Freight cost volatility from Shandong Peninsula fermentation clusters to European pharmaceutical manufacturers amplifies landed cost differentials. Supply concentrates in China, Germany, and India for distinct grade tiers. Corn-derived carbohydrate feedstocks, proprietary microbial strains, and encapsulation polymers anchor input dependencies. Single-source vulnerability runs through high-purity Ashbya gossypii strain licensing. Distribution runs through direct specification contracts with multinational beverage brands and pharmaceutical compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH authorization timelines for synthetic colorants accelerate clean-label substitution demand.
For Market Incumbents: Extend backward integration into corn-derived carbohydrate supply to defend against agricultural commodity volatility. Lock proprietary Ashbya gossypii strain patents before yield optimization IP expires. Capacity expansion in North Rhine-Westphalia biotechnology corridors reinforces EMA-compliant supply positioning against Chinese fermentation scale. For New Entrants and Emerging Players: Capture underpenetrated nutraceutical fortification in Southeast Asian functional food manufacturing. Direct-to-manufacturer liquid dispersion platforms bypass entrenched distributor networks in North American sports beverage production. Encapsulation technology partnerships with modified starch suppliers unlock shelf-stable beverage applications previously closed to riboflavin. For Investors and Strategic Acquirers: Roll-up economics work for Chinese mid-tier fermentation specialists because NMPA export qualification creates acquisition premiums for European buyers seeking dual-certification capabilities. Five-to-ten year viability hinges on continuous fermentation technology adoption rates. Monitor EMA pharmaceutical guideline revisions for parenteral nutrition impurity thresholds as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbohydrate Feedstock Supply | Corn processing captive supply insulates fermentation economics from agricultural commodity cycles. |
| Continuous Fermentation Technology Licensing | Real-time metabolite monitoring reduces batch-to-batch variation for pharmaceutical-grade output. |
| Encapsulation Partnership Development | Modified starch stabilization opens transparent-packaged beverage applications to riboflavin. |
| Dual Certification Investment (FDA/EMA) | Simultaneous color additive and pharmaceutical qualification extends product launch cycles but locks premium positioning. |
| Direct Specification Contract Expansion | Bypassing distributor networks in carbonated soft drink manufacturing captures technical service integration value. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with fermentation technology directors, pharmaceutical procurement managers, food manufacturing R&D leads, and feed additive supply chain officers combined with secondary validation from EMA guideline documents, FDA color additive regulations, NMPA certification databases, and customs trade flow records. Bottom-up volume modeling and top-down market sizing triangulated across production capacity disclosures and end-use consumption patterns.
Segment-weighted forecasting anchored projections across product type, application channel, and geographic production hub dimensions. Modeled growth trajectories incorporated fermentation yield improvement curves, REACH authorization timelines for synthetic substitutes, and China domestic substitution rates. CAGRs derived from year-over-year segment momentum and cross-referenced against capacity expansion announcements.
Underlying measurement precision varies by segment; pharmaceutical-grade riboflavin 5'-phosphate carries tighter precision than commodity feed-grade volumes due to documented batch certification requirements. Forecasts embed assumptions around regulatory enforcement consistency and strain patent expiration schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Metal Complex Dyes Market
Dyes and Pigments
Cadmium Pigments Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Pharmaceutical Dyes Market
Dyes and Pigments
Pigment Dispersion Resin Market
Dyes and Pigments
Brilliant Black BN Colors Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Europe Natural Dyes and Pigments Market
Dyes and Pigments
Global Paint Pigments Market