
 Global Paper Dyes Market | 2026-2036
Global Paper Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paper Dyes Market Foresight
Color-matching software subscriptions and predictive maintenance contracts for dye dosing systems is broadening what paper mills purchase beyond bulk chemicals. Archroma leverages its integrated color management platform to lock in multi-year supply agreements with European coated paper producers. Kemira Oyj anchors its position through captive R&D facilities in Finland that develop low-AOX formulations for bleached kraft grades. DyStar Singapore Pte Ltd dominates Southeast Asian distribution through direct technical service teams stationed in Indonesia and Thailand.
Paper dyes are synthetic or natural colorants formulated with specific chromophore groups and auxiliaries, typically applied at temperatures between 40°C and 80°C during the stock or surface coloring stage to achieve uniform shade, lightfastness, and bleed resistance in finished paper products. Direct dyes retain the largest volume share across uncoated writing and printing grades due to cost efficiency and ease of application, while reactive dyes capture expanding share in specialty paper where wet-fastness requirements exceed standard specifications. Azo dyes face structural pressure from regulatory limits on aromatic amine release, shifting margin pools toward metal-complex and sulfur-based alternatives that command premium positioning in food-contact packaging segments.
REACH registration requirements in Europe, EPA effluent guidelines under the Clean Water Act in the United States, and China's GB standards for heavy metal content collectively determine which dye chemistries gain market access and which face substitution pressure. India's BIS certification for paper products intended for food contact is tightening import specifications and redirecting formulation priorities among suppliers serving the subcontinent. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned product development pipelines.
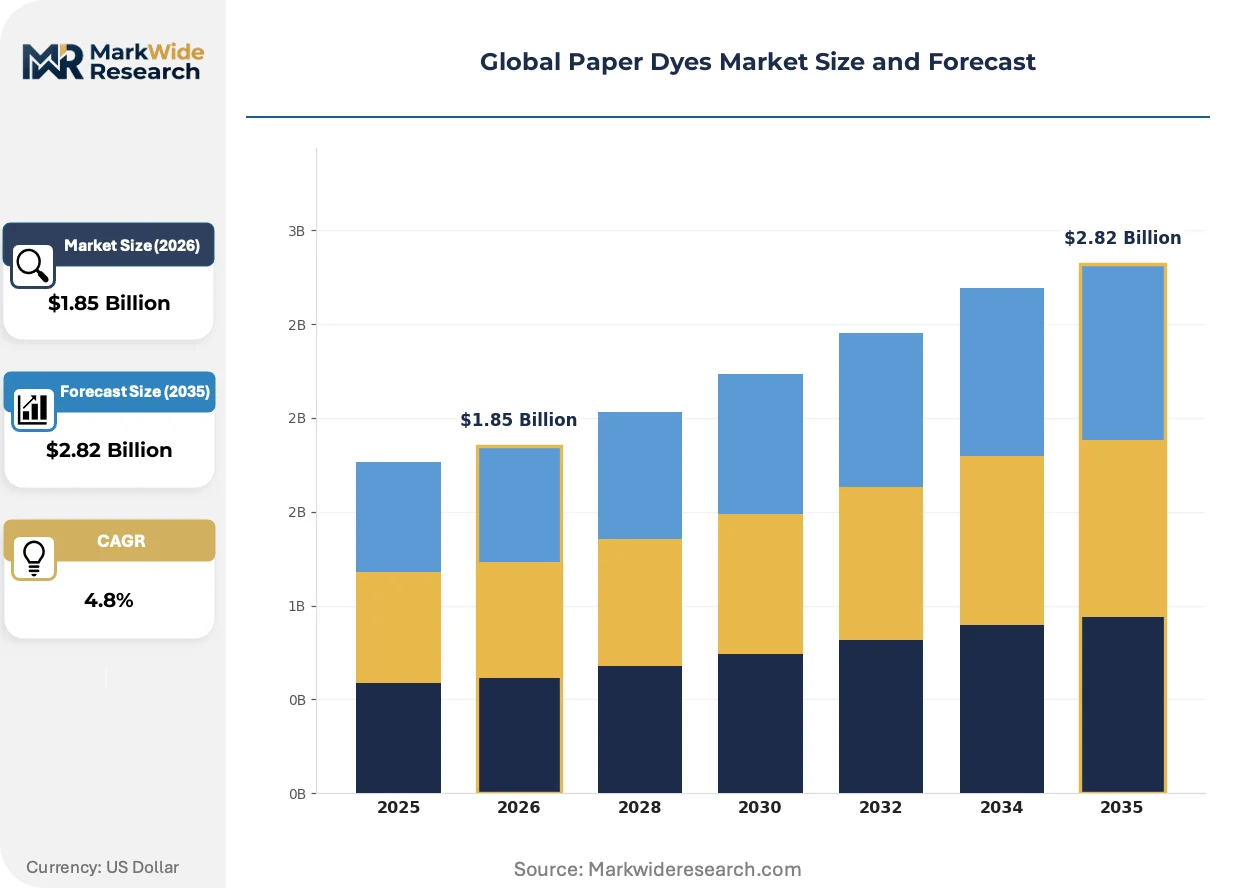
Market Dynamics
Regulatory fragmentation across REACH, EPA effluent guidelines, and India's BIS certification is forcing dye suppliers to maintain parallel formulation portfolios, compressing R&D efficiency while opening premium positioning for compliant chemistries.
Growth Catalysts
- Food-grade packaging conversion:Brand owners are eliminating plastic from direct-contact applications, creating specification demand for low-migration dye systems in folding carton and flexible paper substrates.
- REACH authorization timelines:European restrictions on aromatic amine release are accelerating substitution toward metal-complex and sulfur-based alternatives that command structural premiums in compliant segments.
- India capacity expansion:Domestic paper production scaling near Mumbai and Ahmedabad is concentrating regional formulation demand, pulling technical service infrastructure toward South Asian manufacturing clusters.
Market Restraints
- Petroleum-derived intermediate volatility:Naphthalene and benzene feedstock costs swing with crude differentials, compressing margin predictability for azo and direct dye families.
- China supply concentration:Intermediate synthesis and active ingredient production clusters in Jiangsu and Zhejiang provinces create single-source vulnerability for global formulators.
- AOX emission ceilings:Scandinavian and German mill permits restrict halogenated dye application in bleached kraft grades, limiting chemistry options for Nordic suppliers.
Strategic Opportunities
- Indonesia technical service gaps:Archipelago geography fragments dye dosing support, creating first-mover advantage for suppliers establishing direct mill engineering presence outside Java.
- Digital color matching platforms:Cloud-based spectrophotometry and AI shade prediction are compressing lab-to-production cycles, enabling subscription revenue streams alongside chemical sales.
- EU Green Deal procurement mandates:Public sector paper purchasing specifications are embedding carbon footprint thresholds, favoring regional suppliers with verified low-emission production routes.
Industry Challenges
- Colorimetric expertise scarcity:Mill operators with deep knowledge of dye-fiber interaction mechanics are aging out of European and North American workforces faster than training pipelines replenish.
- Legacy dosing system incompatibility:Southeast Asian paper mills running 1990s-vintage stock preparation lines face retrofit complexity when integrating precision injection equipment for low-volume specialty dyes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paper Dyes Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Azo Dyes, Direct Dyes, Reactive Dyes, Disperse Dyes Application: Coated Paper, Uncoated Paper, Brown Paper, Specialty Paper End User: Publishing, Packaging, Stationery, Textile Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Archroma, BASF SE, Kemira Oyj, Atul Ltd, DyStar Singapore Pte Ltd, Synthesia, Axyntis Group, Clariant International Ltd, Chromatech Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paper Dyes Market Shifts & Advancements
Digital instrumentation and predictive analytics are redistributing value capture from bulk chemical sales toward integrated color management ecosystems that lock in multi-year mill relationships.
Spectrophotometric cloud platforms are decentralizing shade matching authority from centralized lab facilities to machine operators on production floors. Mid-size coated paper producers in Italy and Spain are adopting these systems fastest, lured by reduced lab staffing and compressed customer approval cycles. The technology is decentralizing color decision-making while compressing the addressable market for traditional shade-matching services.
EPA effluent guidelines under the Clean Water Act are tightening permissible color units in discharged process water. US mills serving food-contact segments now face capital decisions on tertiary treatment or chemistry substitution toward inherently lower-BOD dye families. Specialty paper grades with stringent wet-fastness requirements are absorbing the steepest compliance costs, redirecting specification priorities among domestic suppliers.
Buyer consolidation among European packaging converters is compressing supplier rosters and extending payment terms. Tier-one cartonboard producers in Germany and France now demand integrated color management plus inventory management services, displacing transactional dye purchasing. This pattern is most visible in coated folding carton segments where three converters control majority share of premium brand contracts.
Global Paper Dyes Market Segmentation
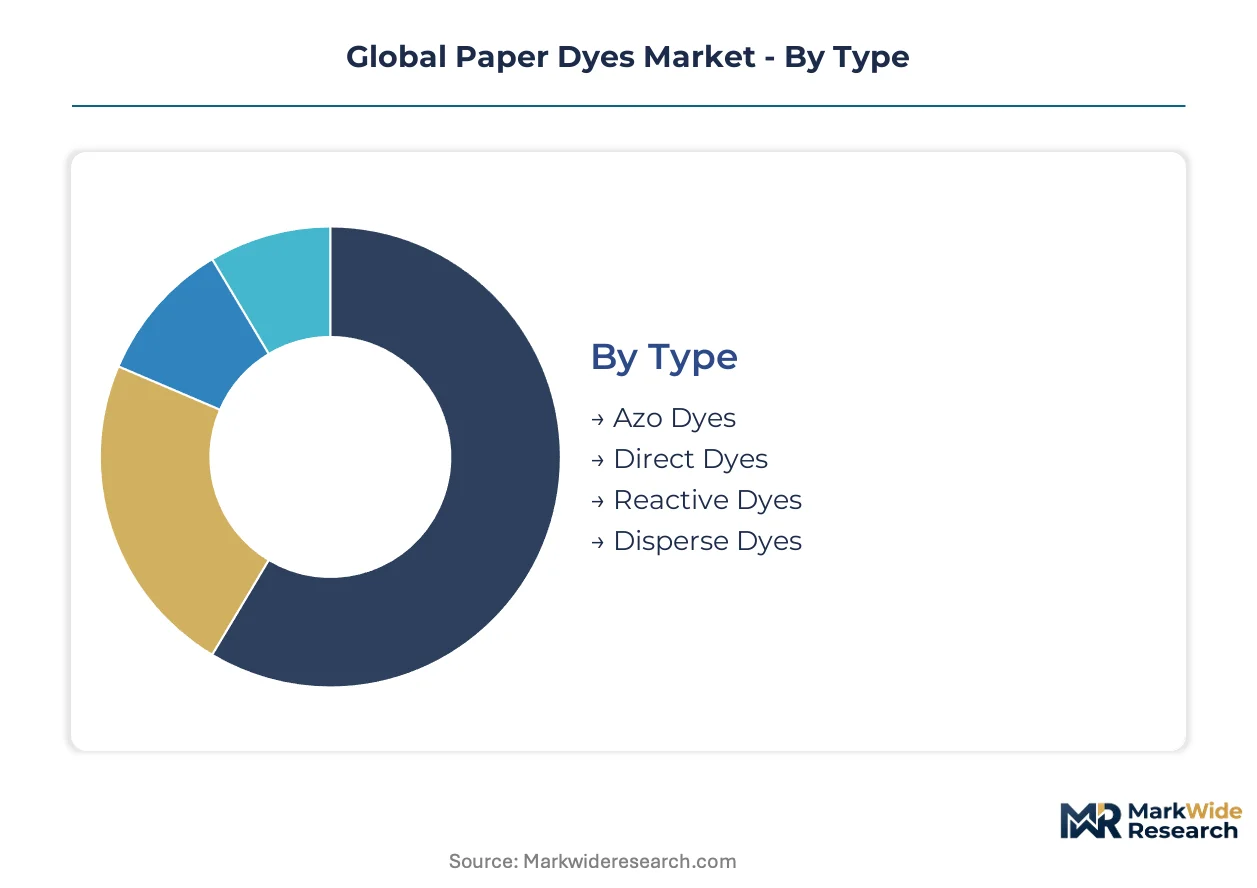
Paper dye procurement diverges sharply across end-use specifications, with food-contact grades demanding REACH-registered metal-complex formulations while commodity printing accepts standard direct dye systems. Segmentation strategy determines which certification burdens suppliers must absorb and where margin premiums concentrate.
Type:
REACH registration requirements and EPA effluent guidelines split this category between aromatic amine-restricted and compliant chemistries, reshaping accessible market volume by jurisdiction.
- Direct Dyes:Sulfonated aromatic structures bond directly to cellulose fibers without mordants, delivering cost-efficient coloration for high-volume uncoated writing and printing grades. Demand concentrates in Indian domestic mills scaling near Mumbai, where BIS certification for food-contact paper is tightening import specifications and favoring established direct dye suppliers with local technical presence.
- Reactive Dyes:Chromophores with labile reactive groups form covalent bonds with hydroxyl sites on cellulose, yielding superior wet-fastness for specialty grades. European coated paper producers in Germany and France specify these systems for premium folding cartons, absorbing structural premiums as REACH aromatic amine limits accelerate substitution away from conventional azo platforms.
- Azo Dyes:Diazo-coupled chromophores face structural pressure from regulatory limits on aromatic amine release.
- Disperse Dyes:Low-water-soluble particles suit synthetic fiber blends and specialty coated substrates.
Direct dyes sit at the top of the volume ranking, with reactive dyes climbing the fastest.
Application:
Cost tiers separate commodity substrates from specification-driven segments where compliance premiums exceed raw material differentials.
- Specialty Paper:Substrates engineered for thermal resistance, barrier properties, or direct food contact command dye systems with migration testing and heavy metal certification. Brand owners eliminating plastic from direct-contact applications in the United States and Europe are pulling low-migration metal-complex formulations into folding carton and flexible paper specifications.
- Coated Paper:Kaolin or calcium carbonate surface layers require dyes compatible with binders and calendering stress. Italian and Spanish mid-size producers are adopting cloud-based spectrophotometric platforms fastest, compressing lab-to-production cycles and locking in multi-year supply relationships with integrated color management providers.
- Uncoated Paper:Standard writing and printing grades absorb volume share through cost-optimized direct dye application.
- Brown Paper:Unbleached kraft substrates for corrugated and wrapping applications tolerate lower purity dye streams.
Uncoated paper holds the largest volume position, though specialty paper gains share fastest.
End User:
Customer procurement maturity determines whether dye purchasing remains transactional or shifts toward integrated color management subscriptions.
- Packaging:Converter consolidation in Germany and France is compressing supplier rosters, with tier-one cartonboard producers demanding inventory management services alongside chemical supply. Three converters control majority share of premium brand contracts, extending payment terms and displacing spot-market dye purchasing.
- Publishing:Magazine and catalog printers face secular volume pressure from digital substitution.
- Stationery:Premium writing paper segments in Japan and South Korea maintain specification discipline for lightfastness.
- Textile:Paper-backed fabric applications absorb dye volumes through separate formulation channels.
Packaging dominates absolute consumption, with stationery showing the steepest margin expansion.
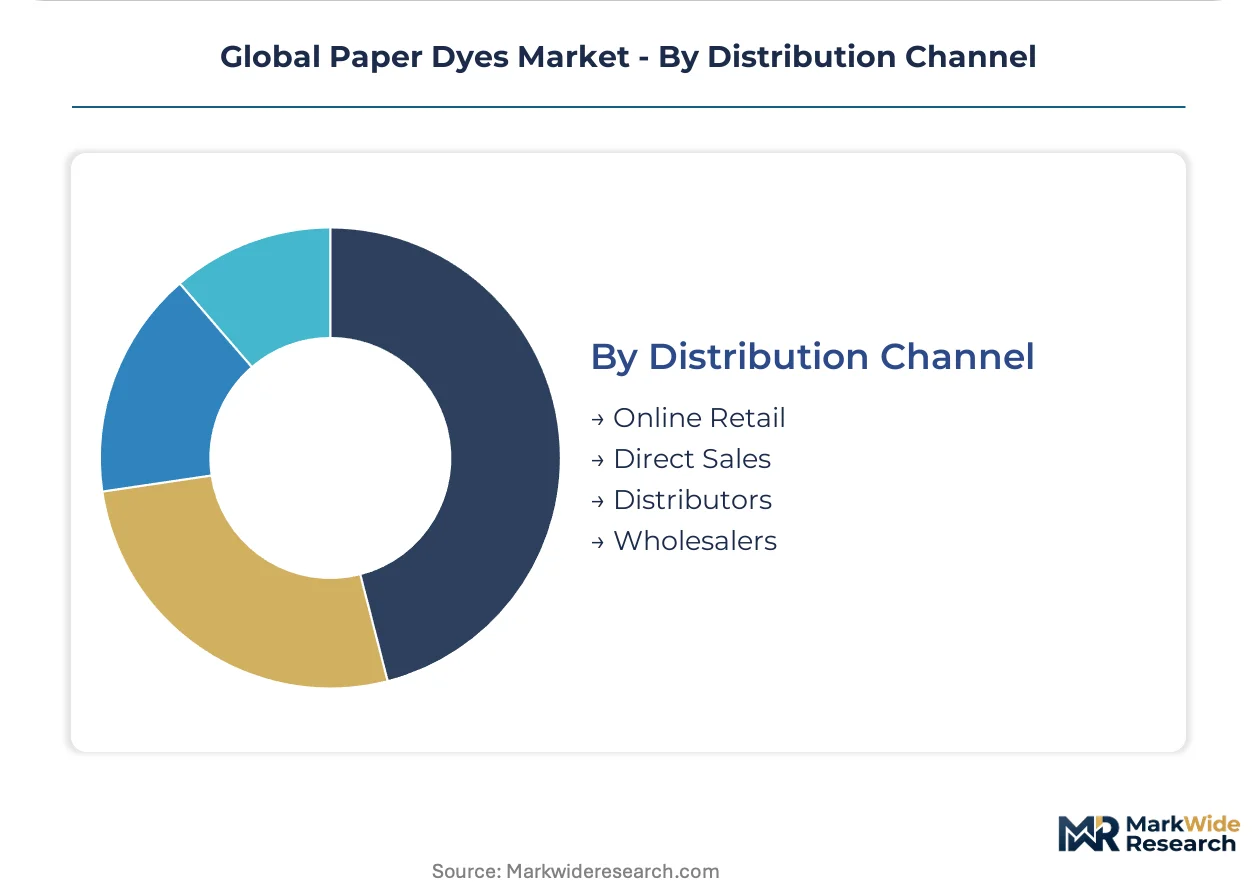
Distribution Channel:
Supply chain configuration determines technical service reach and inventory carrying cost allocation between supplier and mill.
- Direct Sales:Archroma and Kemira Oyj anchor positions through captive technical teams stationed at major mill clusters. DyStar Singapore Pte Ltd maintains direct engineering presence in Indonesia and Thailand, exploiting archipelago geography that fragments competitor support networks.
- Distributors:Regional chemical distributors hold inventory for smaller mills lacking bulk storage infrastructure.
- Online Retail:E-procurement platforms capture spot volumes for R&D sampling and small-batch specialty grades.
- Wholesalers:Bulk intermediaries serve fragmented Southeast Asian mills running 1990s-vintage stock preparation lines.
Direct sales commands the highest volume share, while online retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates formulation demand near Mumbai and Ahmedabad while Germany absorbs structural premiums for REACH-compliant chemistries, illustrating how regulatory divergence splits margin capture across jurisdictions.
United States
EPA effluent guidelines under the Clean Water Act tighten permissible color units in discharged process water, forcing mills serving food-contact segments toward tertiary treatment or chemistry substitution. FDA migration testing requirements for direct-contact paper packaging pull low-migration metal-complex formulations into folding carton specifications. Wisconsin and Georgia mill clusters absorb compliance costs through capital investment in treatment infrastructure.
Germany
ECHA REACH authorization timelines accelerate substitution away from aromatic amine-releasing azo platforms toward sulfur-based alternatives. Scandinavian and German mill permits restrict halogenated dye application in bleached kraft grades through AOX emission ceilings. Bavarian and North Rhine-Westphalian coated paper producers extend payment terms while demanding integrated color management services.
China
GB standards for heavy metal content determine market access for dye chemistries serving domestic paper production. Jiangsu and Zhejiang provinces concentrate intermediate synthesis and active ingredient production, creating single-source vulnerability for global formulators. Shanghai and Ningbo mill clusters scale capacity for regional packaging demand while navigating environmental compliance tightening.
India
BIS certification for paper products intended for food contact tightens import specifications and redirects formulation priorities among suppliers. Domestic paper production scales rapidly near Mumbai and Ahmedabad to serve regional packaging needs. Technical service infrastructure pulls toward South Asian manufacturing clusters as capacity concentrates in Gujarat and Maharashtra.
Indonesia
Archipelago geography fragments dye dosing support across dispersed mill locations outside Java, creating technical service gaps for precision injection equipment. FSSAI-equivalent food contact standards tighten as regional packaging demand expands. Sumatran and Kalimantan mill clusters face retrofit complexity when integrating dosing systems for low-volume specialty dyes.
Global Paper Dyes Market Competitive Landscape
Top-tier vendors anchor integrated color management platforms, while mid-tier suppliers compete on formulation flexibility and regional technical presence. The vendor base stratifies between multi-national chemical conglomerates with captive R&D facilities and specialized dye houses focused on niche compliance segments. Strategic archetypes include subscription-based color service providers, low-AOX formulation specialists, and archipelago technical service operators. Dominant competitive moves encompass multi-year supply agreement lock-ins and direct mill engineering presence establishment.
Among European-based integrated solution providers, Archroma and Kemira Oyj occupy positions exemplifying platform-anchored competitive strategy, while DyStar Singapore Pte Ltd represents the technical service-intensive archetype for Southeast Asian market penetration. These three entities illustrate how geographic origin and organizational structure shape strategic positioning without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| Archroma |
| BASF SE |
| Kemira Oyj |
| Atul Ltd |
| DyStar Singapore Pte Ltd |
| Synthesia |
| Axyntis Group |
| Clariant International Ltd |
| Chromatech Incorporated |
| Others |
Supply & Pricing Matrix
Naphthalene and benzene feedstock indices cascade through paper dye supply chains into three distinct pricing tiers that separate REACH-registered metal-complex formulations from standard direct dye systems. Petroleum-derived intermediate volatility compresses margin predictability for azo and direct dye families while concentrating pricing power among suppliers with captive upstream synthesis.
Pricing Analysis
Capacity additions in India are reshaping price floors for commodity direct dyes as domestic mills near Mumbai and Ahmedabad scale production. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and volume scale, with BIS food-contact compliance commanding structural premiums. Pricing pressure stems from buyer consolidation among European packaging converters extending payment terms. Small Southeast Asian mills running vintage stock preparation lines exhibit highest price sensitivity, while tier-one cartonboard producers in Germany absorb premium positioning for integrated color management.
Supply Chain Analysis
Freight cost differentials between Jiangsu-Zhejiang synthesis clusters and end-use mills fragment inventory carrying cost allocation across global formulators. Supply concentrates in China for intermediate synthesis, India for formulation finishing, and Germany for specialty compliance-grade production. The chain draws from naphthalene, benzene, and chromophore precursor inputs. Single-source vulnerability in Jiangsu and Zhejiang provinces creates structural risk for global dye availability. Distribution runs through direct technical service teams for major mill clusters and regional distributors for fragmented smaller operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Paper Dyes Market functions as a geographic-arbitrage play where REACH compliance costs in Germany exceed formulation premiums available in India by margins sufficient to redirect supplier R&D investment.
For Market Incumbents: Deploy captive technical service infrastructure as the primary defensive lever. Archroma and Kemira Oyj anchor positions through mill-embedded engineering teams that lock in multi-year supply agreements. Backward integration into chromophore synthesis defends margin position against naphthalene feedstock volatility. Incumbents must counter DyStar Singapore Pte Ltd's archipelago penetration by replicating direct dosing support outside Java before competitor relationships solidify. For New Entrants and Emerging Players: Capture technical service gaps in Indonesia's Sumatran and Kalimantan mill clusters where geography fragments incumbent support networks. The most penetrable segment sits in cloud-based spectrophotometric platforms for mid-size coated paper producers in Italy and Spain. New entrants should angle through subscription-based color management partnerships that displace transactional chemical purchasing. For Investors and Strategic Acquirers: Asymmetric upside sits with regional formulation specialists possessing BIS certification pathways and established Gujarat technical presence. Long-term viability hinges on regulatory divergence persisting between REACH aromatic amine limits and India's food-contact tightening. Watch for EPA effluent guideline acceleration as the signal indicating capital rotation toward tertiary treatment-integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromophore Synthesis | Captive naphthalene processing insulates margin from crude volatility for azo dye families. |
| Cloud-Based Color Management Platform Launch | AI shade prediction compresses lab-to-production cycles for Italian and Spanish mid-size producers. |
| Direct Mill Engineering Presence Establishment | Technical teams in Sumatra and Kalimantan exploit archipelago geography gaps before competitors consolidate. |
| REACH-Compliant Metal-Complex Formulation Scale-Up | Sulfur-based alternatives capture substitution demand as ECHA aromatic amine timelines accelerate. |
| Multi-Year Supply Agreement with Inventory Management | Tier-one German and French cartonboard converters displace spot purchasing through integrated service bundling. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct supply-demand balances for paper dye categories. Primary engagement captured perspectives from paper mill procurement directors, dye formulation R&D leads, technical service engineers, and packaging converter specification managers. Secondary validation drew from customs trade databases, ECHA REACH registration filings, EPA effluent guideline dockets, and BIS certification records. Bottom-up mill capacity modeling and top-down chemical consumption estimates were cross-referenced for triangulation.
Segment-weighting approaches distributed value and volume across dye type, application grade, end-use industry, and regional regulatory cluster throughout the forecast period. The analytical framework modeled direct, reactive, azo, and disperse dye families against specialty, coated, uncoated, and brown paper substrates. CAGRs were derived from regression analysis of historical capacity utilization and projected substitution elasticities. Forecast inputs incorporated REACH authorization timeline acceleration and India domestic production scaling curves.
Feedstock price volatility, regulatory timeline acceleration, and buyer consolidation momentum are the dominant revision risks that could shift trajectory. Forecasts reflect documented assumptions on aromatic amine substitution rates and technical service penetration timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Dyes and Pigments Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Dyestuff (Black Color) Market
Dyes and Pigments
Ultramarine Pigments Market
Dyes and Pigments
Colorants Market
Dyes and Pigments
Global Cosmetic Pigments Market
Dyes and Pigments
Thermochromic Pigments Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
South America Hair Colorants Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Titanium Dioxide Color Market