
 Pearl Pigment Market | 2026-2036
Pearl Pigment Market Size, Share, and Industry Trends Forecast 2026-2036
Pearl Pigment Market Analytics
Modular color-kit bundling is rebalancing procurement patterns across the pearl pigment value chain. BASF SE leverages its integrated coatings chemistry platform to anchor supply relationships with tier-one automotive painters. Merck KGaA sustains technology leadership through advanced substrate-coating capabilities for high-luster applications. Sudarshan Chemical Industries competes on manufacturing scale from its Indian production base, serving cost-sensitive plastics compounders across Asia.
Pearl pigments are synthetic or natural mica flakes coated with metal oxides—typically titanium dioxide or iron oxide—creating interference colors through thin-film optical physics, with particle sizes ranging from 5 to 150 micrometers depending on luster grade. These pigments deliver aesthetic depth, UV stability, and temperature resistance for surfaces where metallic flake alternatives fail. The coatings application segment leads absolute volume, anchored by automotive OEM specification lock-in and architectural facade durability standards. Cosmetics represents the fastest-growing product type, driven by clean-label formulation shifts and premium color-shifting effects in skincare packaging. Powder form dominates industrial handling efficiency, though liquid dispersions gain share in automated inkjet and digital printing workflows.
REACH registration requirements in Europe and EPA TSCA oversight in the United States constrain raw material sourcing and mandate extensive substance safety documentation for mica-based inputs. China's GB standards and evolving MEE environmental enforcement reshape production economics for domestic manufacturers and export-bound competitors. India's BIS certification for pigment imports adds compliance layers for multinational suppliers entering the subcontinent. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
Automotive OEM specification lock-in is compressing supplier qualification timelines while forcing pigment houses to pre-certify formulations against REACH SVHC candidate lists and China GB standards before volume sampling begins.
Growth Catalysts
- REACH SVHC compliance mandates:European automotive painters now require pre-certified pearl pigment grades, eliminating spot-market sourcing and anchoring long-term supply contracts with qualified houses.
- Cosmetics clean-label formulation:Skincare brands in South Korea and France are specifying interference-grade pearl pigments to replace banned microplastics in color-shifting packaging.
- India plastics cluster expansion:Gujarat and Maharashtra processing hubs are absorbing volume shipments for consumer appliance housings, creating dedicated demand lanes from domestic pigment producers.
Market Restraints
- Mica supply concentration:Jharkhand and Bihar states in India control premium natural mica extraction, exposing processors to export licensing volatility and informal mining crackdowns.
- Titanium dioxide feedstock cost:Chloride-process TiO2 prices track sulfuric acid and energy input swings, compressing coating-grade pigment margins during upstream spikes.
- Metallic flake substitution:Vacuum-metallized aluminum pigments from Japanese suppliers are displacing mid-luster pearl grades in mass-market automotive refinish.
Strategic Opportunities
- Brazil ANVISA cosmetic registration pathway:Pre-registered pearl pigment dossiers can capture formulation share as Latin American skincare manufacturing localizes.
- Digital printing inkjet dispersion:Liquid pearl concentrate formats are penetrating packaging prototyping workflows, bypassing powder handling infrastructure requirements.
- EU Green Deal sustainable sourcing incentives:ESG-linked procurement tenders favor mica traceability-certified suppliers in German automotive coating supply chains.
Industry Challenges
- Substrate coating process engineering:Thin-film metal oxide deposition requires vacuum or chemical vapor expertise scarce outside German and Japanese equipment houses.
- Multi-jurisdiction substance dossier maintenance:Parallel TSCA, REACH, and China MEE notification cycles consume 18-24 month qualification windows for new interference color grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pearl Pigment Market |
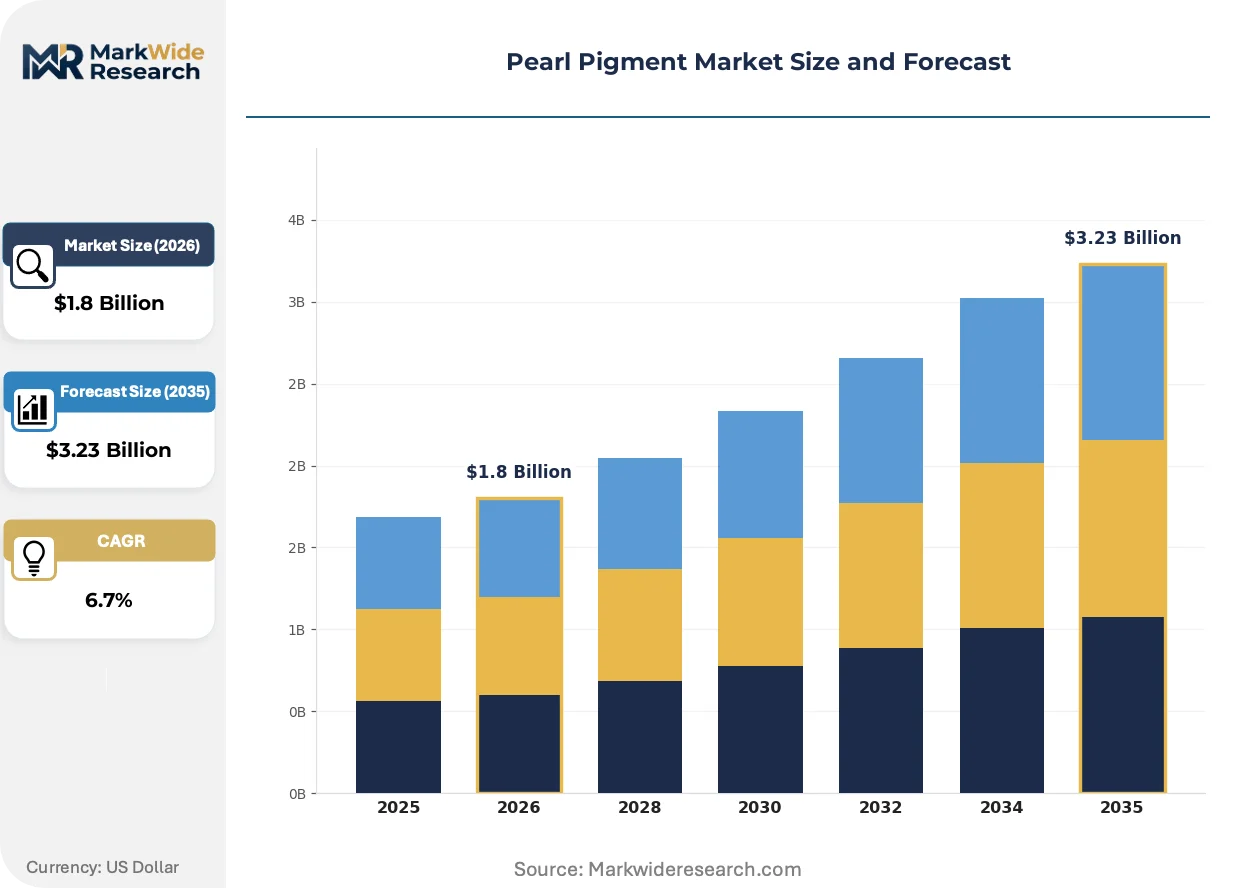
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Plastics, Ink, Cosmetics Application: Automotive, Architecture, Consumer Goods, Personal Care Form: Powder, Liquid, Paste, Gel End User: Manufacturers, Retailers, Distributors, Artisans |
| Companies Covered | Altana AG, Sudarshan Chemical Industries, BASF SE, Kolortek, DIC Corporation, Merck KGaA, Eckart GmbH, CQV Co., Ltd., Sun Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pearl Pigment Market Evolving Landscape
Multi-layer optical stack engineering is redefining performance benchmarks across automotive and cosmetics segments, compressing development cycles while fragmenting supplier tiering.
Synthetic fluorphlogopite substrates are integrating titanium dioxide and iron oxide interference layers to achieve temperature stability above 800°C for under-hood automotive coatings. Tier-one German automotive painters are qualifying these grades for electric vehicle battery pack enclosures. The technology is integrating thermal management requirements with aesthetic specification, collapsing the traditional separation between functional and decorative coating tiers.
China MEE enforcement of wastewater discharge standards for mica wet-processing facilities is forcing domestic manufacturers to install closed-loop water recovery systems or face production halts. Shandong and Jiangsu province pigment houses are consolidating smaller wet-grinding operations to share centralized treatment infrastructure. Export-bound suppliers are absorbing 12-18 month capex cycles to maintain EU and US market access.
Automotive refinish distributors are unbundling color-matching software subscriptions from physical pigment purchases, shifting technician loyalty from product brands to digital platform ecosystems. BASF's integrated color-kit bundling and independent spectrophotometer vendors are competing for bay-floor adoption in German and US collision repair networks. This behavior is most visible in North American MSO consolidation, where centralized procurement favors platform-integrated suppliers over standalone pigment houses.
Pearl Pigment Market Segmentation
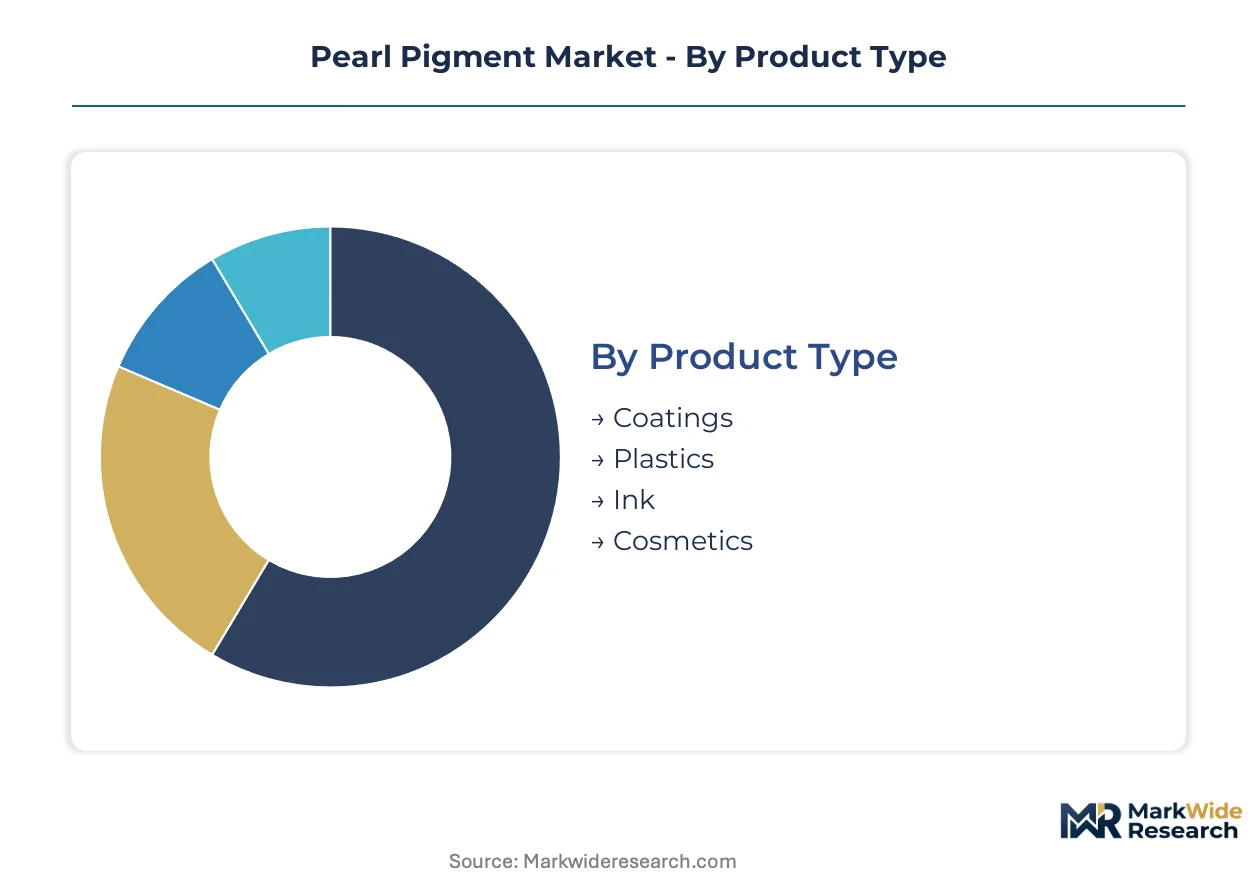
Pearl pigment procurement patterns diverge sharply across formulation chemistry and handling requirements. Specification lock-in at automotive OEMs and cosmetics houses fragments supplier qualification pathways by segment.
Product Type:
Technical performance thresholds separate premium-grade interference pigments from commodity replacements in each formulation category.
- Coatings:Automotive OEM specifications demand titanium dioxide interference layers with thermal stability above 300°C for engine-bay applications. German tier-one painters anchor volume demand through REACH pre-certified supply contracts, eliminating spot-market sourcing flexibility.
- Cosmetics:Clean-label skincare brands in South Korea and France specify synthetic mica substrates to replace banned microplastics in color-shifting packaging, driving fastest-formulation growth across the product matrix.
- Plastics:Gujarat and Maharashtra processing clusters absorb volume shipments for consumer appliance housings from domestic Indian producers.
- Ink:Digital printing workflows favor liquid dispersion formats bypassing powder handling infrastructure.
Mature deployment sits with Coatings. Newer deployment is concentrated in Cosmetics.
Application:
End-use durability standards and color-matching complexity create distinct procurement economics across sectors.
- Automotive:Specification lock-in at German OEMs compresses supplier qualification to 18-24 month cycles against REACH SVHC and China GB standards. Electric vehicle battery pack enclosures now integrate thermal management with aesthetic requirements.
- Personal Care:ANVISA registration pathways in Brazil and ESG-linked tenders in Germany favor traceability-certified mica suppliers.
- Architecture:Facade durability standards in Germany and UAE drive demand for UV-stable interference grades.
- Consumer Goods:India's plastics clusters serve appliance housing markets with cost-optimized standard luster pigments.
Volume concentration rests with Automotive. Steepest expansion trajectory belongs to Personal Care.
Form:
Handling efficiency and automation compatibility determine form-factor adoption across industrial and artisanal workflows.
- Powder:Dominates industrial scale handling for coatings and plastics compounding with established pneumatic conveying infrastructure.
- Liquid:Inkjet dispersion formats penetrate packaging prototyping workflows, eliminating powder containment capex for digital printers.
- Paste:Pre-dispersed concentrates serve small-batch cosmetics formulators requiring consistency without in-house milling.
- Gel:Specialized viscosity grades target artisanal applications and craft markets with direct-handling requirements.
Established infrastructure favors Powder. Automation tailwinds push Liquid fastest.
End User:
Procurement scale and technical capability separate integrated manufacturers from fragmented downstream channels.
- Manufacturers:Automotive OEMs and cosmetics houses drive specification lock-in through pre-certified formulation requirements.
- Distributors:Refinish networks unbundle color-matching software from physical pigment purchases, shifting technician loyalty to digital platforms.
- Retailers:Craft and hobby channels absorb gel and paste formats for artisanal end-users.
- Artisans:Small-batch creators favor pre-formulated pastes eliminating capital equipment requirements.
Contract security concentrates with Manufacturers. Channel fragmentation deepens among Artisans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal special economic zones concentrate wet-grinding and coating operations for export-bound pearl pigment output. Germany's automotive corridor anchors premium-grade qualification requirements. India's Jharkhand-Bihar mineral belt supplies natural mica feedstock amid licensing volatility.
China
Shandong and Jiangsu province pigment houses consolidate wet-processing operations under MEE wastewater enforcement. GB standards compliance now requires 12-18 month capex cycles for closed-loop water recovery systems. Export-oriented manufacturers in these coastal clusters absorb qualification costs to maintain EU and US market access.
Germany
Tier-one automotive painters in Baden-Württemberg and Bavaria compress supplier qualification to 18-24 month cycles. REACH SVHC pre-certification eliminates spot-market sourcing flexibility. The KBA oversees vehicle coating compliance while ESG-linked procurement tenders favor traceability-certified mica suppliers.
India
Gujarat and Maharashtra plastics processing hubs absorb volume shipments for consumer appliance housings. Jharkhand and Bihar states control premium natural mica extraction, exposing processors to DGFT export licensing volatility. Domestic producers compete on manufacturing scale for cost-sensitive Asian compounders.
United States
Automotive refinish distributors unbundle color-matching software from physical pigment purchases. EPA TSCA oversight constrains raw material sourcing for mica-based inputs. Collision repair networks in Michigan and Ohio favor platform-integrated suppliers over standalone pigment houses.
South Korea
Clean-label skincare brands specify interference-grade pearl pigments to replace banned microplastics. MFDS cosmetic registration requirements favor pre-certified synthetic mica grades. Seoul-based formulators drive fastest-growing demand across the cosmetics segment.
Pearl Pigment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The market structure consolidates around three to four integrated coatings chemistry platforms alongside regional grinding specialists. Strategic archetypes include substrate-coating technology leaders, scale-driven wet-processing operators, and digital color-platform integrators. Dominant competitive moves center on REACH pre-certification bundling and synthetic fluorphlogopite capacity expansion.
Among German-based diversified chemical groups, BASF SE and Merck KGaA exemplify integrated platform positions. BASF anchors supply relationships through modular color-kit bundling with tier-one automotive painters. Merck occupies the high-luster interference tier through advanced substrate-coating capabilities. Sudarshan Chemical Industries represents the scale-driven specialist archetype from its Indian production base.
| Leading Market Players |
|---|
| Altana AG |
| Sudarshan Chemical Industries |
| BASF SE |
| Kolortek |
| DIC Corporation |
| Merck KGaA |
| Eckart GmbH |
| CQV Co., Ltd. |
| Sun Chemical |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap wet-processing specialists in India's Jharkhand-Bihar mineral belt anchor feedstock supply while exerting disciplined pricing power through export licensing leverage. Their informal mining consolidation under DGFT enforcement tightens raw material release schedules, forcing coating-grade purchasers into longer contract tenors with limited spot-market flexibility.
Pricing Analysis
Margin tightening in automotive refinish traces to metallic flake substitution from Japanese vacuum-metallized suppliers compressing mid-luster pearl grades. Three-tier pricing structure across premium interference, standard coating, and economy plastics grades separates REACH-certified synthetic mica from uncertified natural alternatives. Cost-down pressure on commodity tiers accelerates because titanium dioxide feedstock volatility passes through chloride-process input swings. Tier-one automotive OEMs show least price sensitivity given specification lock-in, while Indian plastics compounders absorb maximum cost pressure.
Supply Chain Analysis
REACH SVHC pre-certification and China GB standards gating compress supplier qualification windows to 18-24 months, fragmenting sourcing options. Geographic supply concentrates in China for wet-grinding and coating operations, India for natural mica extraction, and Germany for high-luster interference substrate engineering. Raw material dependencies rest on Jharkhand-Bihar mica, chloride-process titanium dioxide, and synthetic fluorphlogopite substrates. Single-source vulnerability runs through Indian export licensing volatility for premium natural mica. Distribution runs through automotive OEM direct contracts, refinish distributor platforms, and plastics compounder volume agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pearl pigment procurement consolidation favors integrated coatings chemistry platforms as multi-jurisdiction compliance costs force independent grinding specialists toward exit or acquisition. REACH SVHC dossier maintenance and China MEE wastewater capex cycles disproportionately burden unintegrated players lacking captive synthetic mica capacity.
For Market Incumbents: Anticipate metallic flake substitution accelerating in mass-market automotive refinish by anchoring specification lock-in through bundled color-kit platforms with tier-one painters. Deepen backward integration into synthetic fluorphlogopite substrate production to decouple from Jharkhand-Bihar licensing volatility. Prioritize EU Green Deal traceability certification to capture ESG-linked procurement tenders in German automotive supply chains. For New Entrants and Emerging Players: ANVISA cosmetic registration pathways in Brazil open a window for pre-certified synthetic mica suppliers to capture formulation share as Latin American skincare manufacturing localizes. Target digital printing liquid dispersion formats for packaging prototyping workflows where powder handling infrastructure barriers exclude incumbent powder specialists. Pursue spectrophotometer platform partnerships to embed pigment specifications within color-matching software ecosystems. For Investors and Strategic Acquirers: Distressed-cycle entries favor wet-processing specialists in China's Shandong and Jiangsu provinces facing MEE enforcement consolidation pressure. Five-to-ten-year viability hinges on synthetic substrate technology transition completion and automotive EV battery pack enclosure qualification. Monitor German KBA coating compliance bulletins for thermal stability specification shifts signaling interference-grade demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Fluorphlogopite Capacity Expansion | Captures EV battery pack enclosure specifications requiring 800°C thermal stability from German OEMs. |
| REACH SVHC Pre-Certification Bundling | Locks tier-one automotive painters into multi-year supply contracts eliminating spot-market competition. |
| Closed-Loop Water Recovery Installation | Satisfies China MEE enforcement for Shandong and Jiangsu wet-processing facilities maintaining EU export access. |
| Liquid Dispersion Format Development | Penetrates inkjet packaging prototyping workflows bypassing powder containment infrastructure requirements. |
| Mica Traceability Certification Program | Qualifies suppliers for EU Green Deal ESG-linked procurement tenders in German automotive coating chains. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with coating formulators, automotive procurement leads, plastics compounding managers, and cosmetics R&D directors provided demand-side validation. ECHA REACH registrations, China MEE discharge permits, and Indian DGFT export licenses supplied regulatory constraint calibration. Bottom-up volume builds across product type, application, and form segments triangulated against top-down value estimates from trade flow analysis.
Data-stream reconciliation across production capacity surveys, pigment shipment manifests, and end-use consumption patterns generated consistent trajectory outputs across the projection horizon. Segmentation dimensions modeled include luster grade tier, substrate type, end-use industry, form factor, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating automotive OEM specification cycles, cosmetics clean-label formulation shifts, and plastics processing cluster expansion rates. Forecast inputs weighted synthetic mica substitution elasticity and TiO2 feedstock price volatility assumptions.
The model assumes a particular technology adoption path; alternative pathways for multi-layer optical stack engineering would alter the outlook if thermal stability requirements shift below current 800°C thresholds. Forecasts reflect documented assumptions regarding REACH SVHC list expansion timing and China MEE enforcement intensity. A model refresh is warranted upon material change in German automotive OEM electric vehicle platform specifications or Jharkhand-Bihar export licensing regime restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Pearlescent Pigments Market
Dyes and Pigments
Basic Violet 10 Market
Dyes and Pigments
Micronized Color Powder Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Global Cosmetic Dyes Market
Dyes and Pigments
Pigment Additive Film Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Pharmaceutical Dyes Market
Dyes and Pigments
Resin Pigments Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
LAMEA Optical Brighteners Market