
 Ultramarine Pigments Market | 2026-2036
Ultramarine Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Ultramarine Pigments Market Analytics
Specialty chemical distribution is rewriting access patterns for ultramarine pigments across regional markets. BASF SE leverages its integrated pigments network to sustain supply continuity for coatings formulators in Western Europe. Ferro Corporation anchors its position through specialized high-heat grades targeting engineered plastics processors. Ultramarine & Pigments Ltd competes on cost-optimized powder grades for bulk textile dyers in South Asia.
Ultramarine pigments are synthetic inorganic colorants composed primarily of sodium aluminosilicate with entrapped polysulfide radicals, manufactured via the traditional kiln-firing of kaolin, sulfur, and sodium carbonate at temperatures exceeding 700°C to produce the characteristic blue hue valued for its lightfastness and alkali resistance. The pigments serve primarily as non-toxic replacements for heavy-metal-based blue colorants in applications requiring FDA or toy-safety compliance. Ultramarine Blue dominates volume flows across the product type split, reflecting entrenched demand from architectural coatings and laundry detergent whitening applications. Powder form leads packaging economics for bulk industrial buyers, though liquid dispersions are gaining traction among cosmetics compounders seeking dust-free handling and batch consistency.
REACH registration requirements in Europe and FDA color additive regulations in the United States constrain formulation flexibility and elevate compliance costs for imported pigment lots. India's BIS certification mandates for textile dyes and the EU's F-Gas Regulation indirectly shape investment priorities by favoring low-VOC, waterborne coating systems that rely on ultramarine's chemical stability. Stakeholders must monitor evolving heavy-metal thresholds across multiple jurisdictions while assessing whether captive synthesis or merchant supply better secures specification-grade pigment access.
Market Dynamics
REACH compliance deadlines in Europe are compressing formulation timelines for coatings and plastics manufacturers, forcing accelerated reformulation away from cobalt-based blues toward ultramarine alternatives. This regulatory pressure is concentrating procurement decisions among buyers capable of certifying supply chain traceability.
Growth Catalysts
- Heavy-metal bans in children's products:EU Toy Safety Directive and US CPSIA restrictions on cobalt and copper phthalocyanine blues are redirecting specification-grade demand toward ultramarine pigments in molded plastics.
- India's PLI scheme for chemicals:Domestic pigment manufacturers are expanding kiln capacity to serve export markets, lowering landed costs for Southeast Asian plastics converters.
- Waterborne coating mandates:Low-VOC architectural paint regulations across multiple jurisdictions favor ultramarine's alkali stability over organic alternatives prone to hydrolysis.
Market Restraints
- Sulfur feedstock volatility:Petrochemical-derived sulfur pricing fluctuations compress margins for kiln operators running continuous-batch processes.
- Technical ceiling in high-heat applications:Ultramarine's thermal decomposition threshold below 350°C excludes it from certain engineering polymer compounding lines.
- Substitution by organic pigments:Phthalocyanine blues retain cost advantages in non-food-contact packaging where regulatory constraints do not apply.
Strategic Opportunities
- Cosmetics-grade dispersion formats:Liquid ultramarine concentrates address dust-control requirements in pressed-powder manufacturing for personal care formulators.
- Recycled plastics whitening:Post-consumer polyolefin processors require consistent blue masking for aesthetic upgrading, creating specification demand for high-tint-strength grades.
- BIS certification arbitrage:Indian textile dyers with certified export capacity can access preferential duty structures in Gulf Cooperation Council markets.
Industry Challenges
- Kiln operator skill scarcity:Traditional sulfur-firing expertise is retiring faster than apprenticeship programs replenish qualified furnace technicians.
- REACH registration timelines:Extended data-gap analysis periods for sodium aluminosilicate compositions delay market entry for new production entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultramarine Pigments Market |
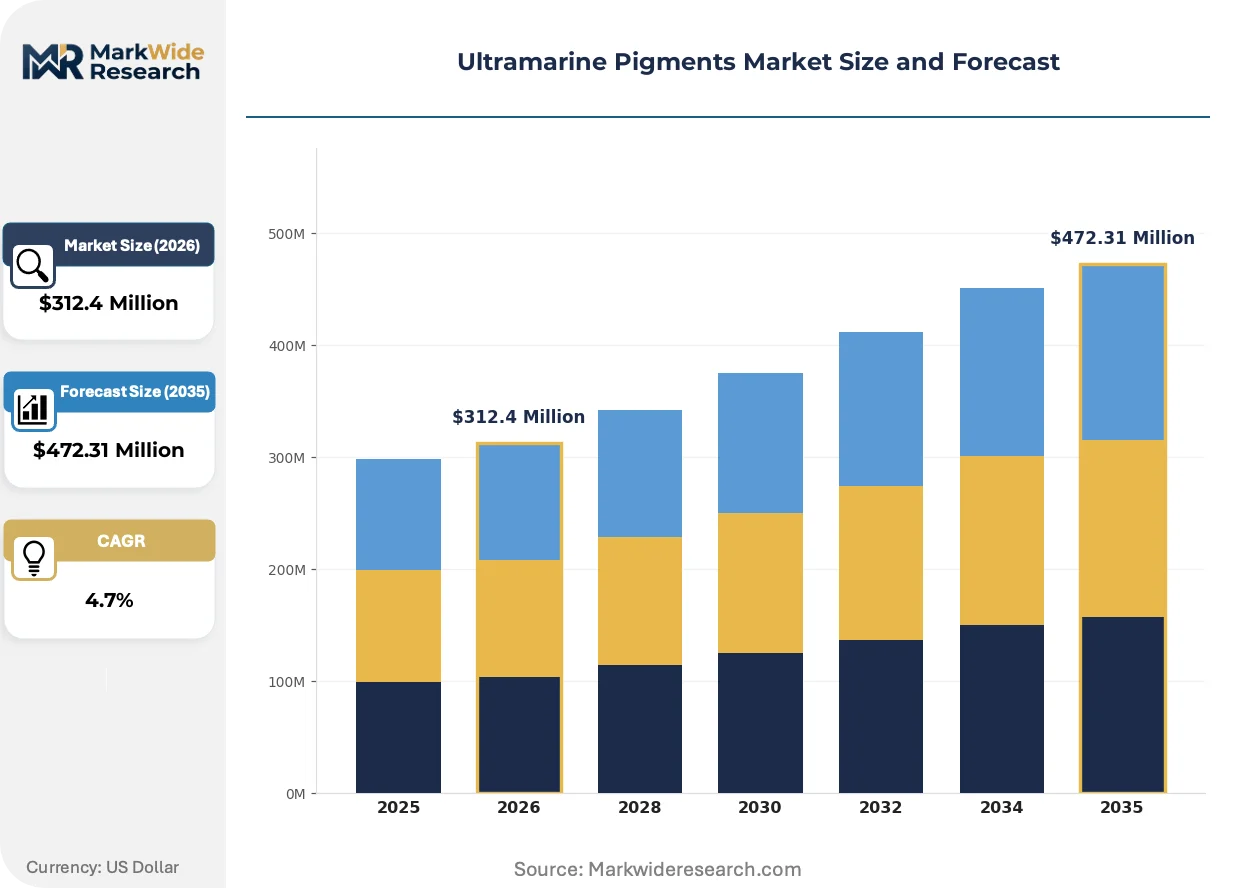
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultramarine Blue, Ultramarine Violet, Ultramarine Green, Ultramarine Red End Use Industry: Paints, Plastics, Cosmetics, Textiles Form: Powder, Liquid, Granular, Paste Packaging Type: Bags, Drums, Containers, Boxes |
| Companies Covered | Ultramarine & Pigments Ltd, Ferro Corporation, BASF SE, DIC Corporation, Venator Materials PLC, Lapis Lazuli Pigments Co., Ltd, Habich GmbH, R.S. Pigments, Dominion Colour Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultramarine Pigments Market Evolving Landscape
Formulation science is advancing across three vectors: hybrid pigment architectures, tightening chemical safety protocols, and evolving procurement specifications that reward verified supply chain transparency over unit economics alone.
Surface-modified ultramarine pigments are hybridizing with silica encapsulation layers to enhance dispersibility in polar resin systems. Masterbatch compounders serving automotive interior specifications are adopting these grades to reduce melt-flow variation. The technology is compressing qualification cycles for pigment suppliers seeking Tier-1 automotive approval.
ECHA's 2023 restriction proposal on microplastics in leave-on cosmetics is accelerating reformulation timelines for color cosmetic manufacturers. Ultramarine's inorganic stability satisfies the draft biodegradability screening criteria where organic lake colors face scrutiny. French and German formulators are front-loading inventory transitions ahead of anticipated enforcement windows.
Specification audits now dominate long-term supply agreements in the coatings sector. Purchasing departments at German architectural paint manufacturers are unbundling pigment supply from broader additive packages to secure dedicated batch certification. This behavioral shift is most pronounced in waterborne exterior coating lines where color consistency warranties extend to fifteen years.
Ultramarine Pigments Market Segmentation
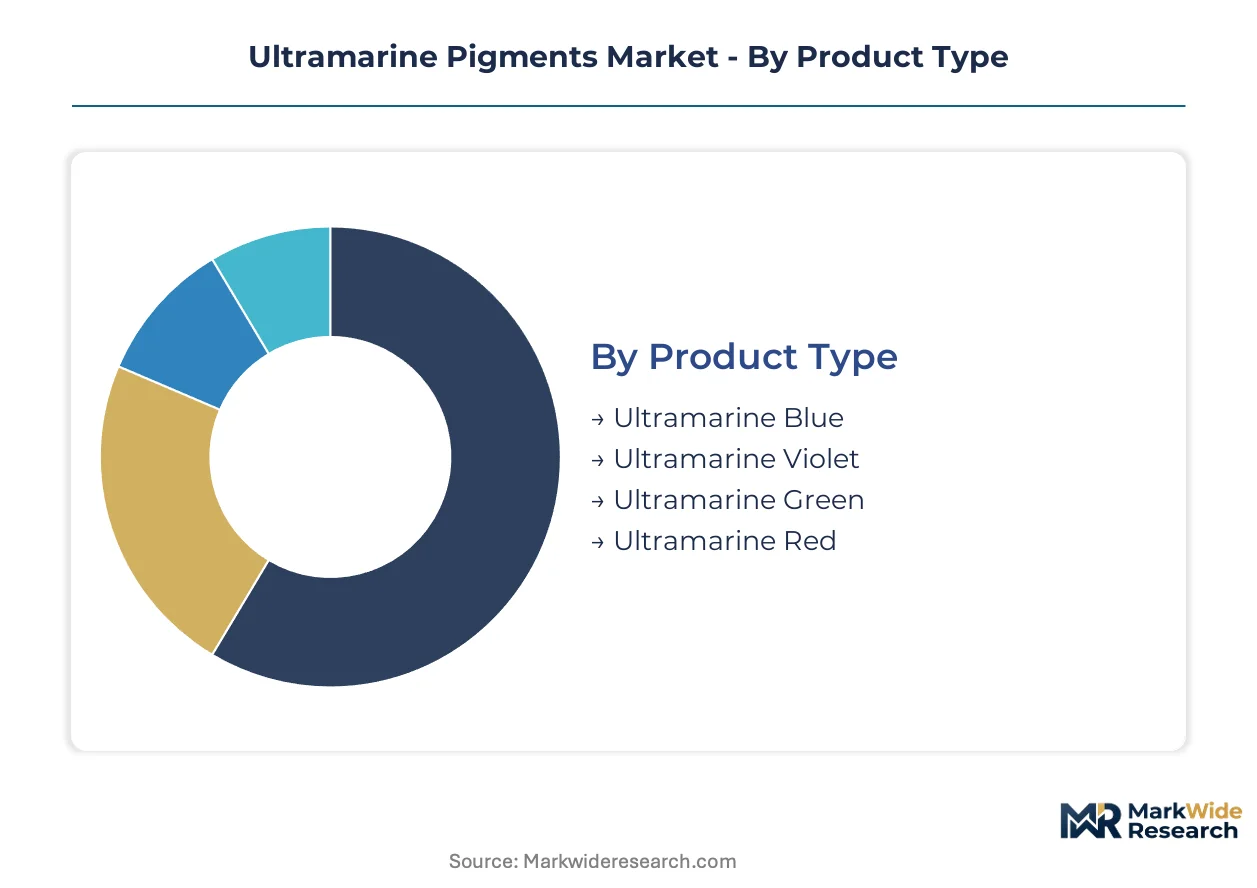
Ultramarine pigment buyers segment procurement by technical performance thresholds, regulatory compliance tiers, and handling economics. Formulators across coatings, plastics, and personal care verticals specify grades based on thermal stability, dispersibility, and certification requirements rather than color alone.
Product Type:
Mature formulations dominate commercial volumes while emerging variants address specification gaps in high-performance applications.
- Ultramarine Blue:Sodium aluminosilicate with polysulfide radicals entrapped in the sodalite cage structure produces the characteristic azure tone. Demand concentrates in architectural coatings and laundry detergent whitening across Western Europe, where REACH-compliant reformulation away from cobalt blues accelerates procurement. Thermal decomposition limits above 350°C constrain engineering polymer adoption.
- Ultramarine Violet:Modified sulfur ratios during kiln firing shift the absorption spectrum toward violet wavelengths. Cosmetics formulators in France and Germany front-load inventory transitions ahead of ECHA microplastics restrictions, favoring inorganic stability over organic lake alternatives facing biodegradability scrutiny.
- Ultramarine Green:Hybrid compositions blending blue and yellow chromophores within the aluminosilicate matrix serve specialty coatings requiring unique hue positioning.
- Ultramarine Red:Rare sulfur-deficient variants occupy niche decorative applications where conventional organic reds fail alkali resistance tests.
Ultramarine Blue retains volume leadership; Ultramarine Violet holds the steepest expansion curve.
End Use Industry:
Cost tier stratification separates commodity volume buyers from specification-grade purchasers willing to absorb certification premiums.
- Paints:Waterborne architectural coatings mandate ultramarine's alkali stability over hydrolysis-prone organic alternatives. German manufacturers unbundle pigment supply from additive packages to secure dedicated batch certification for fifteen-year color consistency warranties.
- Plastics:EU Toy Safety Directive and US CPSIA restrictions on cobalt and copper phthalocyanine blues redirect molded plastics demand toward ultramarine alternatives. Masterbatch compounders serving automotive interior specifications adopt surface-modified grades to reduce melt-flow variation.
- Cosmetics:ECHA's draft microplastics restriction accelerates reformulation timelines for pressed-powder manufacturers seeking dust-free handling through liquid dispersion formats.
- Textiles:India's BIS-certified dyers leverage preferential duty structures in Gulf Cooperation Council markets, scaling kiln capacity under PLI scheme incentives.
Paints commands the largest procurement volumes; Cosmetics is climbing the fastest on regulatory displacement.
Form:
Customer type determines format preference — bulk industrial processors prioritize unit economics while precision formulators value handling characteristics.
- Powder:Traditional kiln-fired particulate dominates bulk industrial procurement for architectural coatings and textile dyeing. Indian domestic producers scale powder-grade capacity to serve Southeast Asian plastics converters with cost-optimized supply.
- Liquid:Aqueous dispersions eliminate dust exposure in cosmetics compounding and enable batch consistency for personal care manufacturers. French formulators specify liquid concentrates to meet dust-control requirements in pressed-powder manufacturing.
- Granular:Low-dust agglomerated formats bridge handling efficiency and dispersibility for mid-scale coatings operations.
- Paste:High-solids preparations serve specialty ink and artist colorant applications requiring precise viscosity control.
Powder maintains dominant share; Liquid is gaining share fastest on cosmetics safety mandates.
Packaging Type:
Supply concentration among kiln operators shapes packaging standardization rather than differentiation.
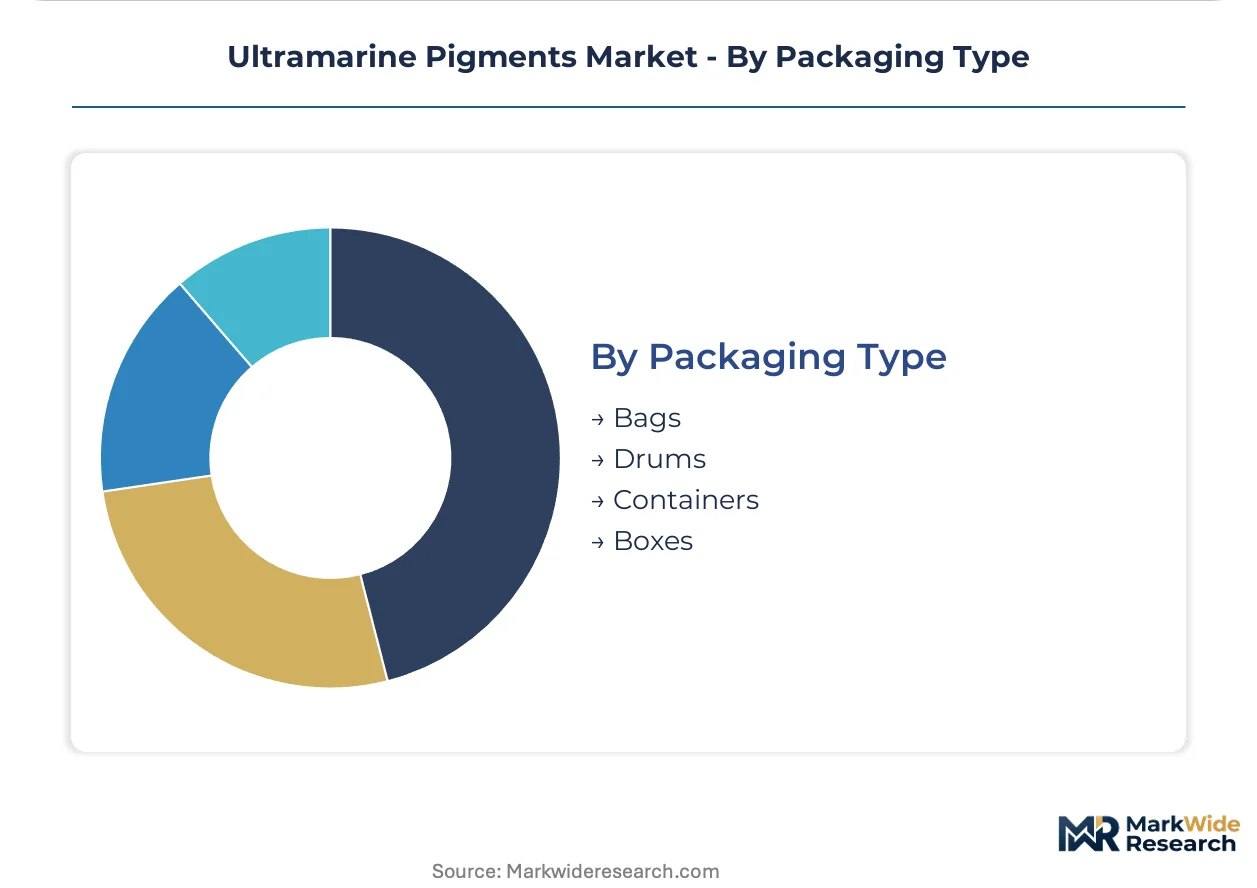
- Bags:Multi-wall paper or woven polypropylene sacks handle powder shipments to bulk coatings and textile operations. European distributors specify bagged supply for REACH-traceable lots.
- Drums:Steel or fiber containers protect liquid and paste formulations from moisture ingress during ocean freight to Southeast Asian converters.
- Containers:Intermediate bulk formats reduce handling costs for high-volume plastics masterbatch producers.
- Boxes:Corrugated packaging serves sample quantities and specialty artist-grade pigments requiring retail presentation.
Bags and Drums together anchor industrial logistics; specialized Containers are expanding most quickly for integrated supply contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-BASF Antwerp pipeline corridor underwrites Western Europe's pigment logistics, moving sulfur feedstocks and finished colorants between the Netherlands and Belgium. This infrastructure anchors REACH-compliant supply chains for coatings formulators across the Rhine-Ruhr manufacturing belt.
Germany
Waterborne architectural coatings manufacturers in North Rhine-Westphalia drive specification-grade ultramarine procurement. ECHA's REACH registration timelines compress qualification cycles for imported pigment lots. Cologne-Düsseldorf chemical distributors unbundle pigment supply from additive packages to secure dedicated batch certification for fifteen-year color consistency warranties.
India
Domestic plastics converters and export-oriented textile dyers scale kiln capacity under the PLI scheme for chemicals. BIS certification mandates for textile dyes shape investment priorities among Mumbai-Gujarat pigment producers. Ankleshwar-Vadodara industrial clusters expand powder-grade output to serve Southeast Asian masterbatch compounders with cost-optimized supply.
United States
FDA color additive regulations constrain formulation flexibility for cosmetics and food-contact plastics manufacturers. Gulf Coast petrochemical corridors supply sulfur feedstocks to domestic kiln operators. Houston-New Orleans distribution hubs handle liquid dispersion imports for personal care formulators seeking dust-free handling systems.
China
Architectural coatings producers in the Yangtze River Delta absorb volume flows of standard-grade ultramarine for domestic construction markets. GB standards for indoor air quality indirectly favor low-VOC, waterborne systems relying on inorganic pigment stability. Shanghai-Ningbo port complexes export powder grades to Southeast Asian plastics processors.
France
Cosmetics formulators in Île-de-France front-load inventory transitions ahead of ECHA's draft microplastics restrictions for leave-on products. ANSM oversight of cosmetic ingredient safety elevates documentation requirements for ultramarine violet grades. Paris-region personal care manufacturers specify liquid concentrates to meet dust-control mandates in pressed-powder operations.
Ultramarine Pigments Market Competitive Landscape
On the supply side, the industry is consolidating around integrated chemical conglomerates and specialized pigment houses with captive kiln capacity. Tiered competition separates specification-grade suppliers serving automotive and cosmetics verticals from cost-optimized powder producers targeting bulk textile and coatings markets. Strategic archetypes include diversified pigment portfolios, regional kiln specialists, and distribution-anchored traders. Dominant competitive moves encompass backward integration into sulfur sourcing and geographic expansion through certified export capacity.
Among Germany-based chemical conglomerates, BASF SE exemplifies the integrated pigments archetype with network infrastructure spanning feedstock logistics to formulated dispersions. Ferro Corporation anchors the specialty-grade tier, occupying a position defined by high-heat engineering plastics specifications. Ultramarine & Pigments Ltd represents the cost-optimized regional specialist model, with Indian kiln capacity scaled to serve South Asian and Gulf Cooperation Council export markets under preferential duty structures.
| Leading Market Players |
|---|
| Ultramarine & Pigments Ltd |
| Ferro Corporation |
| BASF SE |
| DIC Corporation |
| Venator Materials PLC |
| Lapis Lazuli Pigments Co., Ltd |
| Habich GmbH |
| R.S. Pigments |
| Dominion Colour Corporation |
| Others |
Value Network & Pricing Analysis
Indian kiln capacity concentration around Ankleshwar-Vadodara clusters anchors global powder-grade supply, concentrating margin capture among integrated operators while forcing merchant buyers into longer-term offtake commitments to secure specification-grade access.
Pricing Analysis
Volume-discount tiering structures separate bulk textile dyers securing cost-optimized powder shipments from cosmetics formulators absorbing certification premiums for liquid dispersion formats. Price differentiation hinges on REACH traceability documentation and BIS certification status rather than tint strength alone. Cost compression in standard-grade powder runs through sulfur feedstock volatility and continuous-batch kiln economics. Plastics masterbatch compounders exhibit highest price sensitivity, while automotive Tier-1 suppliers prioritize batch consistency over unit cost.
Supply Chain Analysis
Extended payment terms from Indian producers to Southeast Asian distributors are compressing working capital cycles across the merchant tier. Supply concentrates in India, China, and Germany, with sulfur sourcing drawn from Gulf Coast petrochemical corridors and European refinery byproduct streams. Single-source vulnerability sits with specialized high-heat grade producers serving engineering plastics specifications. Distribution runs through Rotterdam-Antwerp pipeline infrastructure for Western European coatings formulators and Shanghai-Ningbo port complexes for Southeast Asian plastics processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultramarine pigments trace a cyclical recovery pattern as REACH-driven reformulation waves crest across European coatings and plastics verticals, compressing substitution timelines for cobalt-based alternatives.
For Market Incumbents: Build certification moats by securing dual REACH-FDA registration coverage ahead of emerging competitor entry. Backward integration into sulfur sourcing secures margin stability against petrochemical volatility. Capacity expansion in Indian BIS-certified clusters captures PLI scheme arbitrage for Gulf Cooperation Council export markets. Channel control through dedicated batch unbundling strengthens position against additive package competitors.
For New Entrants and Emerging Players: Pursue cosmetics-grade liquid dispersion formats where dust-control mandates and ECHA microplastics restrictions displace organic lake colors. France and Germany present the most penetrable geographies given front-loaded reformulation timelines. Surface-modified silica encapsulation technology offers a differentiated go-to-market angle for automotive interior specifications.
For Investors and Strategic Acquirers: Capital is best deployed toward Indian kiln operators with certified export capacity and established Southeast Asian distributor relationships. Long-term viability over the coming decade rests on regulatory displacement durability rather than commodity pigment economics. The signal to watch is ECHA enforcement window timing for microplastics restrictions in leave-on cosmetics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Sourcing | Captive sulfur supply from Gulf Coast refineries insulates margins against petrochemical volatility. |
| REACH-FDA Dual Registration Investment | Dual jurisdiction coverage accelerates qualification cycles for multinational coatings formulators. |
| Surface-Modified Silica Encapsulation Scale-Up | Enhanced dispersibility grades reduce melt-flow variation for automotive Tier-1 masterbatch compounders. |
| Liquid Dispersion Format Expansion | Aqueous concentrates address ANSM dust-control mandates for Île-de-France cosmetics manufacturers. |
| BIS-Certified Export Capacity Addition | Preferential duty structures in Gulf Cooperation Council markets reward certified Indian kiln output. |
Research Methodology
Initial hypotheses were tested against primary input from kiln operations managers, coatings procurement leads, plastics masterbatch compounders, and REACH regulatory consultants and refined through secondary validation across customs trade data, Cefic sector reports, SEC chemical company filings, and ECHA registration databases. Bottom-up volume estimates from individual kiln capacity and top-down demand triangulation from end-use industry consumption patterns were cross-referenced for convergence.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling segmentation dimensions spanning product grade tier, end-use vertical, packaging format, and regional production hub. CAGRs were derived from fitted growth curves applied to disclosed capacity expansion timelines and regulatory-driven substitution elasticities. Forecast inputs incorporated REACH registration completion schedules and PLI scheme incentive disbursement patterns.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles and sulfur pricing volatility would shift the trajectory. Forecasts reflect documented assumptions around regulatory enforcement timing and kiln capacity utilization rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Basic Violet 10 Market
Dyes and Pigments
Asia-Pacific Pigments Market
Dyes and Pigments
Mulch Colorants Market
Dyes and Pigments
Reactive Dyes Market
Dyes and Pigments
Metal Complex Dyes Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
Global Thermochromic Paint Market
Dyes and Pigments
Brilliant Blue FCF Colors Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Natural Colorants Market
Dyes and Pigments
Resin Pigments Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Riboflavin Pigment Market