
 Water-Based Pigments Market | 2026-2036
Water-Based Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Based Pigments Market Outlook
REACH compliance is repositioning the cost-of-entry calculus for pigment suppliers entering European coatings value chains. BASF SE leverages its integrated R&D pipeline to sustain leadership in high-performance organic pigments. Clariant anchors its position through specialized colorant solutions for plastics and textiles. LANXESS competes on manufacturing scale across its German production network.
Water-based pigments are finely dispersed colorants suspended in aqueous media, typically containing 30-60% solids by weight with particle sizes below 5 microns for optimal tinting strength and transparency. Their primary purpose is to deliver coloration without volatile organic compound emissions, replacing solvent-borne alternatives in regulated applications. Acrylic formulations dominate volume due to established supply chains and broad substrate compatibility, while emulsion pigments capture expanding share in architectural coatings where film-forming efficiency matters. Inks remains the fastest-growing application segment as digital and flexographic printing accelerate aqueous system adoption.
EPA regulations in the United States restrict VOC content in architectural and industrial maintenance coatings, directly steering formulation choices toward water-based pigment systems. ECHA maintains REACH substance authorization requirements that filter non-compliant colorants from EU supply chains. China's MEE enforces dual carbon goals that tighten emissions standards for pigment manufacturing clusters. Stakeholders must monitor how regulatory divergence between these jurisdictions reshapes product registration costs and regional sourcing strategies.
Market Dynamics
REACH substance authorization is filtering non-compliant colorants from EU supply chains while EPA VOC restrictions steer US formulation choices, creating a bifurcated regulatory environment that reshapes product registration costs and regional sourcing strategies for pigment manufacturers.
Growth Catalysts
- REACH Enforcement:ECHA's tightening authorization requirements for hazardous substances are accelerating pigment system replacements in German architectural coatings, pulling demand toward low-VOC aqueous alternatives.
- Digital Printing Expansion:Flexographic and inkjet adoption in packaging is driving fastest-segment growth for water-based pigment dispersions as brand owners eliminate solvent residues from food-contact materials.
- India's Industrial Corridor Scaling:Concentrated paint production expansion across Maharashtra, Gujarat, and Tamil Nadu is concentrating procurement volumes for domestic pigment suppliers.
Market Restraints
- Titanium Dioxide Volatility:Feedstock cost swings for TiO2, the dominant white pigment base, compress margin stability for water-based formulation producers.
- Performance Gap in Harsh Environments:Aqueous pigment systems exhibit inferior weathering resistance versus solvent-borne alternatives in industrial maintenance coatings exposed to chemical splash and thermal cycling.
- Substitution Pressure from Pre-Coated Substrates:Coil-coated metals and factory-applied finishes reduce field coating demand, displacing downstream pigment consumption in construction applications.
Strategic Opportunities
- China's Dual Carbon Mandate:MEE emissions standards tightening on pigment manufacturing clusters create first-mover advantage for aqueous technology licensors serving domestic producers.
- Textile Digital Printing:Direct-to-garment and dye-sublimation expansion opens underpenetrated pigment volume in fashion and home furnishings outside traditional coatings channels.
- Biobased Dispersion Convergence:Integration of cellulosic stabilizers with aqueous pigment chemistry addresses sustainability scoring requirements in premium consumer packaging.
Industry Challenges
- Colorimetric Expertise Scarcity:Formulation chemistry talent capable of matching solvent-borne performance in water-based systems commands premium compensation and extends R&D timelines.
- Multi-Jurisdiction Registration Burden:Divergent substance notification requirements across EPA, ECHA, and China's MEE compound compliance costs and delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Based Pigments Market |
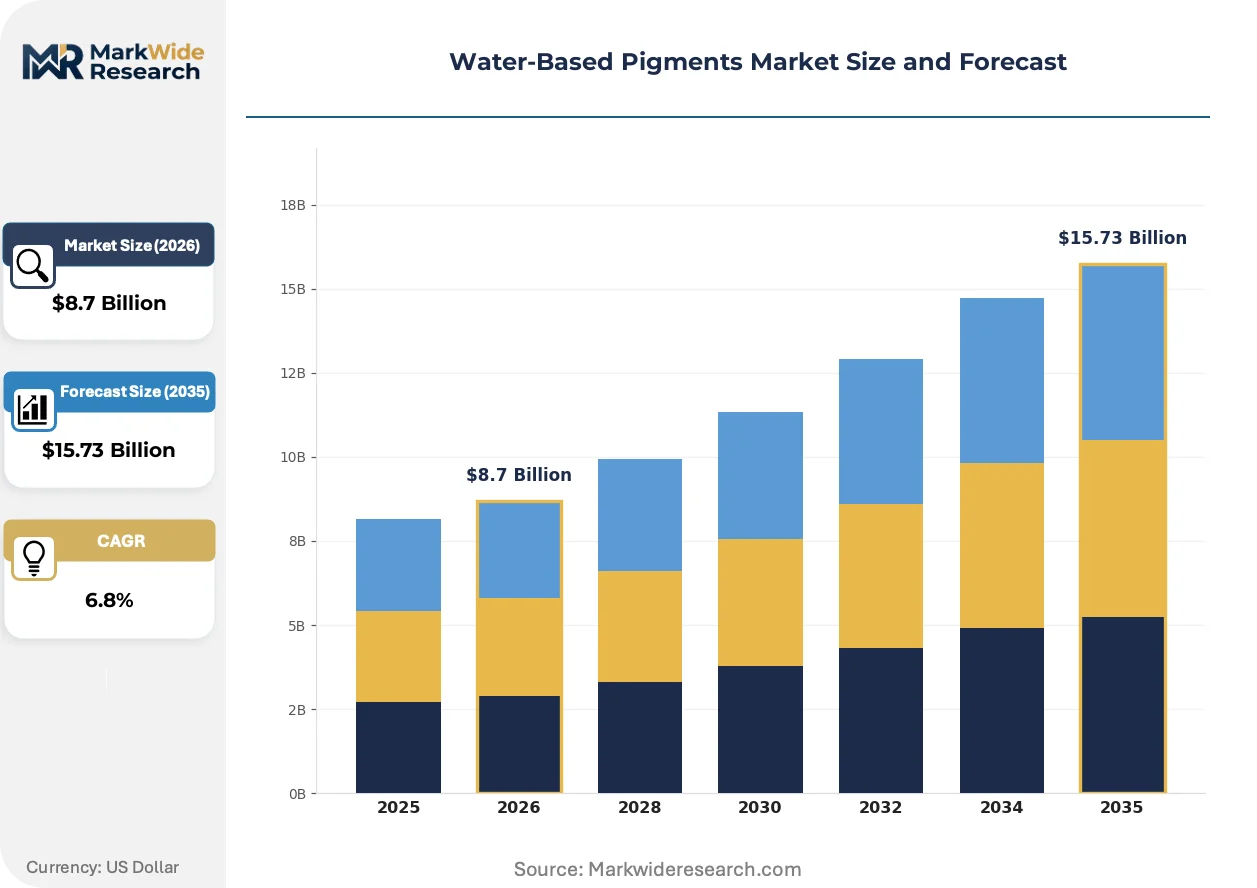
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Dyes, Emulsions, Inks Application: Textiles, Coatings, Plastics, Printing End User: Manufacturing, Construction, Arts & Crafts, Automotive Formulation: Powdered, Liquid, Paste, Gel |
| Companies Covered | BASF SE, AkzoNobel N.V, Clariant, LANXESS, Huntsman, PPG Industries, Inc, DIC Corporation, Sudarshan Chemical Industries Ltd., Heubach GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Based Pigments Market Strategic Shifts
Formulation science is compressing the performance gap between aqueous and solvent-borne systems while regulatory pressure accelerates technology substitution cycles across industrial and decorative coatings.
Polymer-encapsulated pigment technology is decentralizing colorant supply chains by enabling just-in-time dispersion production at coating manufacturing sites rather than centralized pigment milling. Mid-size architectural coatings producers in North America are piloting in-house encapsulation systems to reduce working capital tied to pigment inventory. This distributed production model is compressing logistics costs and shortening reformulation cycles for custom color matching.
ECHA's REACH authorization list expansion is systematically removing chromate and lead-based pigments from EU supply chains, forcing reformulation of corrosion-resistant industrial coatings. Manufacturers serving German automotive and machinery sectors are accelerating qualification of organic alternatives with equivalent hiding power. The construction segment faces the steepest transition costs given the volume of legacy specifications referencing now-restricted substances.
Brand-owner sustainability scorecards are rewriting procurement criteria for packaging inks, with aqueous pigment systems capturing share from UV-cured alternatives in folding carton applications. Major food and personal care companies are unbundling print specifications from converter relationships to directly mandate VOC-free colorant systems. This specification shift is most visible in Western European premium packaging where retailer environmental commitments cascade through supply contracts.
Water-Based Pigments Market Segmentation
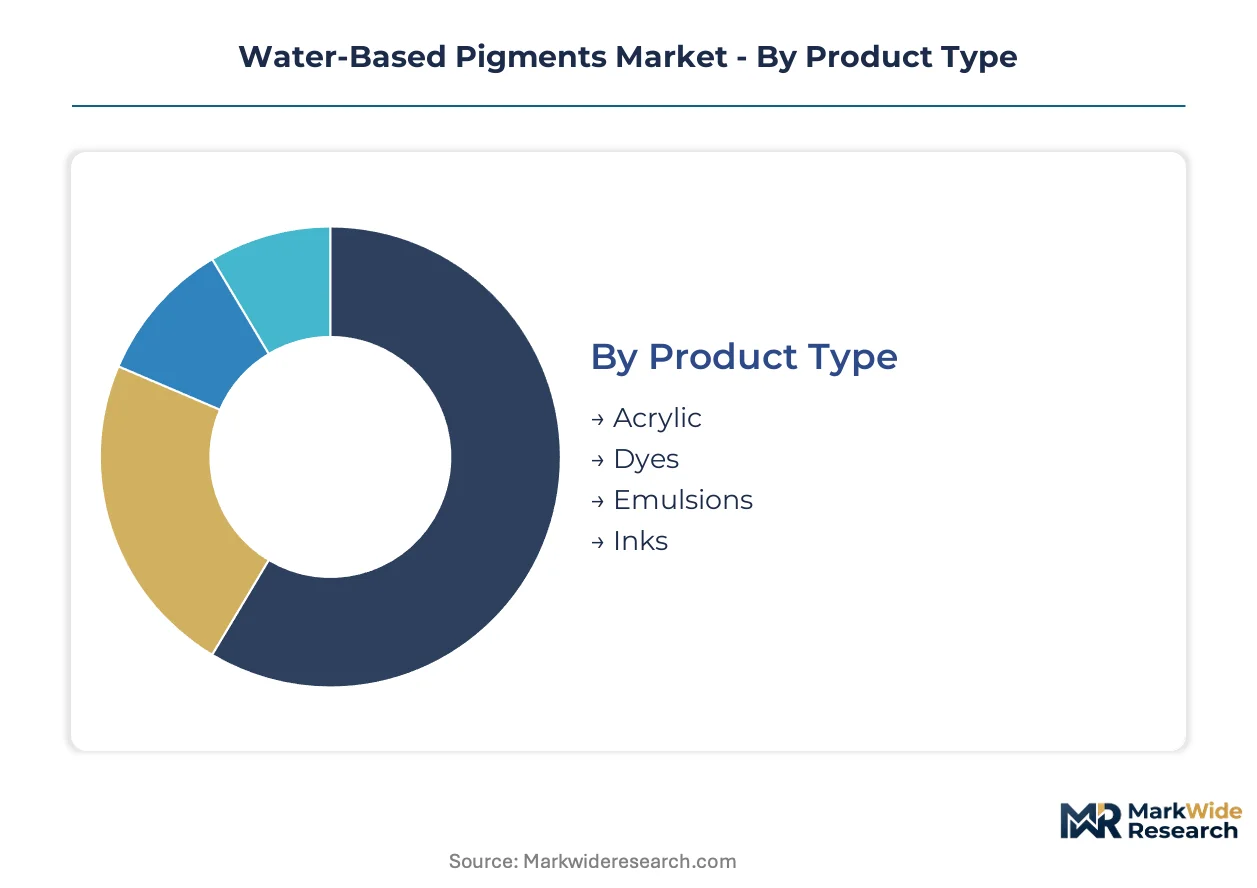
Water-based pigment suppliers face divergent technical requirements across end-use verticals. Formulation chemistry, regulatory exposure, and customer scale reshape profitability within each segment cluster.
Product Type:
Buyers in this category separate by film-forming requirements and substrate compatibility needs.
- Acrylic:Polymer-stabilized dispersions with 30-60% solids content dominate architectural coatings procurement. Demand concentrates in Germany's low-VOC coatings reformulation driven by ECHA REACH enforcement tightening on solvent-borne alternatives.
- Inks:Aqueous pigment preparations for flexographic and inkjet systems capture packaging specification shifts. Brand owners in Western Europe now mandate VOC-free colorants for food-contact cartons, displacing UV-cured alternatives.
- Dyes:Molecular colorants for textile immersion dyeing retain volume in conventional fabric processing.
- Emulsions:Surfactant-stabilized pigment concentrates serve industrial maintenance coatings requiring extended pot life.
Volume sits with Acrylic; growth tilts toward Inks.
Application:
Margin profiles in this category diverge sharply between specification-driven industrial coatings and price-sensitive decorative markets.
- Coatings:Architectural and industrial formulations demanding weathering resistance and chemical stability command premium positioning. Procurement in India's Maharashtra and Gujarat industrial corridors is scaling rapidly as domestic paint production expands.
- Printing:Digital and flexographic ink systems for packaging represent the steepest expansion trajectory. Converter specifications in Western Europe now require aqueous pigment compliance for retailer sustainability scorecards.
- Textiles:Direct-to-garment and dye-sublimation applications open fashion and home furnishings volume outside traditional coatings channels.
- Plastics:Masterbatch coloration for polymer processing requires thermal stability above 200°C.
Coatings holds installed base; Printing climbs the fastest on digital adoption.
End User:
Customer scale in this category ranges from bulk industrial procurement to fragmented specialty purchasing.
- Manufacturing:OEM coating operations for machinery and equipment drive specification-locked pigment volumes. German automotive suppliers are accelerating organic pigment qualification as ECHA removes chromate alternatives from REACH authorization.
- Construction:Field-applied architectural coatings face displacement pressure from pre-coated metal substrates reducing downstream pigment demand.
- Automotive:OEM refinish and assembly plant coating systems require batch-to-batch color consistency.
- Arts & Crafts:Hobbyist and professional artist supply channels purchase smaller volumes with higher SKU complexity.
Manufacturing dominates procurement tonnage; Construction faces headwinds from substrate substitution.
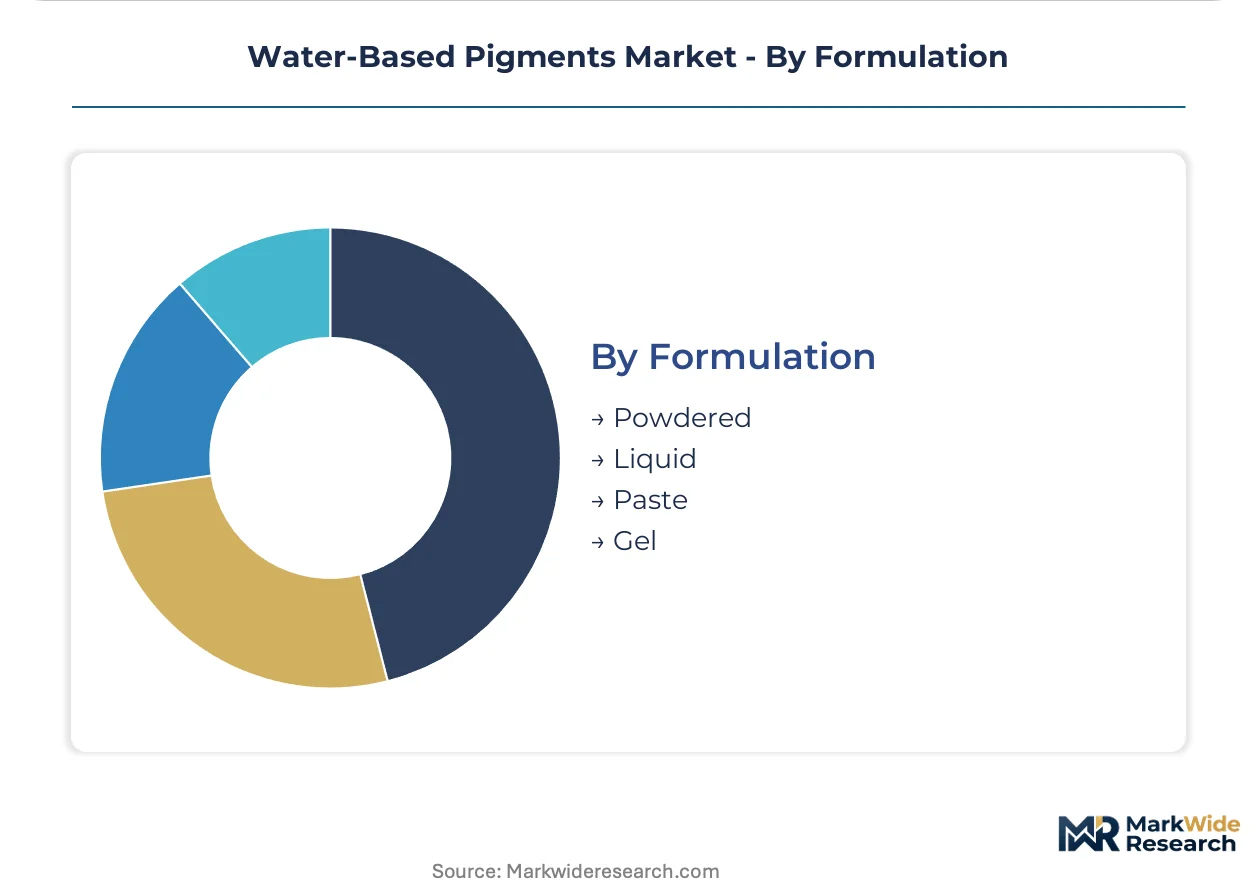
Formulation:
Supply chain configuration in this category determines working capital intensity and logistics cost structures.
- Liquid:Ready-to-disperse aqueous concentrates enable just-in-time production at coating manufacturing sites. North American mid-size architectural producers pilot in-house systems to compress inventory carrying costs.
- Paste:High-solids preparations for industrial tinting systems reduce transportation expenditure versus lower-concentration alternatives.
- Powdered:Dry pigment requiring on-site dispersion equipment suits integrated manufacturers with milling capabilities.
- Gel:Thixotropic preparations for specialized screen printing and textile applications.
Liquid captures share on distributed production trends; Paste defends position in bulk industrial supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Petroleum, Chemicals and Petrochemicals Investment Regions concentrate new water-based pigment capacity as state governments compete for coating industry relocation. Gujarat's PCPIR zone at Dahej anchors domestic dispersion manufacturing scale-up.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria are accelerating organic pigment qualification for corrosion-resistant primers. ECHA's REACH authorization list expansion removes chromate alternatives from Q3 2024, forcing machinery coating reformulations. The Rhine-Ruhr industrial corridor concentrates procurement shifts toward aqueous systems as BASF and LANXESS retrofit legacy solvent-borne lines.
China
MEE enforcement of dual carbon goals tightens emissions permits for titanium dioxide and organic pigment manufacturing clusters. The Yangtze River Delta around Shanghai faces the steepest compliance deadlines for aqueous technology conversion. Zhejiang and Jiangsu provinces concentrate dispersion capacity expansion as domestic paint producers scale water-based architectural output.
United States
EPA VOC restrictions under 40 CFR Part 59 steer architectural coating procurement toward low-emission pigment systems. The Southeast manufacturing belt spanning Georgia and the Carolinas attracts dispersion plant investment as European suppliers establish regional production. Mid-size architectural producers in Ohio and Michigan pilot polymer-encapsulated pigment systems to compress inventory cycles.
India
Maharashtra and Gujarat industrial corridors concentrate rapid paint production scaling as Asian Paints and Berger Paints expand domestic supply chains. BIS certification requirements for low-VOC architectural products tighten from 2025, pulling pigment procurement toward aqueous alternatives. The Dahej PCPIR zone anchors new dispersion manufacturing investments serving western India's coating demand.
Water-Based Pigments Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and application verticals. The market exhibits tiered concentration: integrated chemical majors control high-performance organic pigments, while regional specialists capture architectural coatings volume. Three archetypes dominate: R&D-integrated multinationals, manufacturing-scale European producers, and Asia-Pacific dispersion specialists. Competitive moves center on REACH-compliant portfolio restructuring and distributed production licensing for mid-size coating manufacturers.
Among R&D-integrated majors, BASF SE anchors the high-performance organic pigment tier through its Ludwigshafen-centered innovation pipeline. Clariant occupies a specialized position in plastics and textile colorant solutions, exemplifying the focused-application archetype. LANXESS represents manufacturing-scale competitiveness across German production networks. These three entities collectively illustrate how European chemical majors are repositioning aqueous pigment portfolios under tightening ECHA authorization requirements.
| Leading Market Players |
|---|
| BASF SE |
| AkzoNobel N.V |
| Clariant |
| LANXESS |
| Huntsman |
| PPG Industries, Inc |
| DIC Corporation |
| Sudarshan Chemical Industries Ltd. |
| Heubach GmbH |
| Others |
Value Chain & Pricing Dynamics
Large architectural coatings manufacturers in Germany's Rhine-Ruhr corridor negotiate annual pigment contracts indexed to titanium dioxide feedstock volatility, compressing margin buffers for aqueous dispersion suppliers serving this concentrated buyer base.
Pricing Analysis
Short lead-time premiums of 15-20% apply to spot orders from mid-size North American producers lacking in-house milling capacity. Contract pricing stratifies across REACH-certified premium tiers, standard industrial grades, and economy aqueous bases for decorative applications. Pricing pressure stems from TiO2 cost swings transmitted through feedstock pass-through clauses. Price-sensitive construction contractors in India's industrial corridors squeeze margins on bulk architectural tinting systems.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke logistics for liquid pigment concentrates serving coating manufacturing sites. Supply concentrates in Germany, China, and India as domestic dispersion capacity scales to serve local architectural coatings production. Raw material dependencies center on titanium dioxide from chloride-process plants, acrylic emulsion polymers, and cellulosic stabilizers. Single-source vulnerability runs through specialized organic pigment intermediates concentrated in Zhejiang manufacturing clusters. Distribution runs through just-in-time tanker delivery networks for liquid formulations and bulk silo systems for paste concentrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based pigments occupy a technology-transition phase as polymer-encapsulated dispersion systems displace legacy centralized milling infrastructure, compressing working capital requirements for early adopters.
For Market Incumbents: To counter polymer-encapsulation technology licensing by equipment suppliers, BASF and LANXESS should deepen backward integration into titanium dioxide feedstock through captive chloride-process capacity in German production networks. Certification investment in ECHA REACH-compliant organic pigment portfolios anchors specification-locked relationships with automotive OEMs facing chromate pigment elimination. For New Entrants and Emerging Players: Capture textile digital printing volume in Maharashtra and Gujarat as direct-to-garment adoption outpaces established coatings channel penetration. India's BIS low-VOC certification requirements from 2025 create regulatory pull for domestic aqueous pigment suppliers with localized dispersion capacity. Partner with regional coating manufacturers on distributed encapsulation system pilots to bypass incumbent logistics networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap aqueous dispersion specialists with installed capacity in China's Yangtze River Delta facing MEE emissions compliance deadlines. Long-term viability over the next decade rests on technology licensing revenue streams rather than commodity pigment manufacturing. Watch for ECHA authorization list expansion signals as inflection indicators for organic pigment substitution demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into TiO2 Feedstock | Captive chloride-process supply insulates margin stability from commodity volatility in German production networks. |
| REACH-Compliant Portfolio Restructuring | ECHA authorization list expansion forces chromate pigment replacement in automotive corrosion-resistant primer specifications. |
| Distributed Encapsulation Licensing | Mid-size North American producers pilot in-house systems to compress inventory cycles and logistics expenditure. |
| Textile Digital Printing Capacity Expansion | Direct-to-garment adoption in Maharashtra opens fashion and home furnishings volume outside traditional coatings channels. |
| Dual Carbon Technology Conversion | MEE emissions permits in Zhejiang and Jiangsu provinces drive aqueous dispersion substitution in domestic architectural coatings. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with coating plant managers, procurement leads at architectural OEMs, distribution channel partners, and technical R&D directors specializing in aqueous formulation chemistry. Bottom-up volume modeling triangulated against top-down industry value estimates derived from Cefic coatings reports, EPA VOC compliance databases, and BIS certification registries.
Granularity-level modeling tracked pigment type, application vertical, end-user scale, and formulation format across the projection horizon. CAGRs derived from segment-level demand elasticity analysis incorporating regulatory enforcement timelines, feedstock cost trajectories, and technology substitution rates. Forecast inputs included ECHA authorization list expansion schedules, MEE dual carbon compliance deadlines, and India's PCPIR capacity buildout announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to titanium dioxide supply disruptions, REACH substance authorization surprises, and coil-coated metal substrate substitution acceleration in construction applications. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Photoluminescent Paints Market
Dyes and Pigments
Laser Sensitive Pigments Market
Dyes and Pigments
Ultramarine Pigments Market
Dyes and Pigments
Light Interference Pigments Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Inorganic Cosmetics Pigments Market
Dyes and Pigments
Brilliant Black BN Colors Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Acid Dyes Market
Dyes and Pigments
Global Aluminum Anodizing Dyes Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
Phthalocyanine Pigments Market
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
Aluminum Pigments Market
Dyes and Pigments
Quinacridone Pigments Market