
 Phycoerythrin Market | 2026-2036
Phycoerythrin Market Size, Share, and Industry Trends Forecast 2026-2036
Phycoerythrin Market Analytics
Modular conjugate kit configurations are restructuring how research laboratories evaluate phycoerythrin procurement, shifting preference from bulk pigment orders toward pre-activated, site-specific labeling systems. Thermo Fisher Scientific sustains dominance in conjugate chemistry through its integrated reagent-instrument ecosystem. DIC Corporation anchors supply security via backward integration into spirulina cultivation in Japan. Ag Technologies competes on recombinant expression platforms that reduce lot-to-lot spectral variability.
Phycoerythrin denotes a red photosynthetic pigment-protein complex harvested from cyanobacteria and red algae, comprising alpha and beta subunits with covalently linked phycoerythrobilin chromophores that absorb light at approximately 565 nm and emit at 575 nm; manufacturers extract the protein through aqueous disruption of algal cell walls followed by ammonium sulfate precipitation and chromatographic purification for use as fluorescent tags in biomedical detection. Natural phycoerythrin retains primacy in food coloring applications where clean-label positioning commands premium positioning, though recombinant phycoerythrin captures margin pools in medical diagnostics by satisfying stringent endotoxin and aggregate specifications. Phycoerythrin conjugates represent the fastest-expanding product configuration as multiplexed assay panels multiply fluorophore attachment points per detection event.
FDA biologics guidance and EMA's REACH chemicals framework jointly shape purity thresholds and impurity profiling obligations for diagnostic-grade phycoerythrin entering clinical workflows. ISO 13485 quality management standards govern conjugate manufacturing for in-vitro diagnostic device suppliers, while China's GB standards for food additives regulate pigment grades destined for nutraceutical and food industry channels. Stakeholders must monitor how regulatory divergence between pharmaceutical and food-grade specifications influences facility certification requirements and capital allocation across production sites.
Market Dynamics
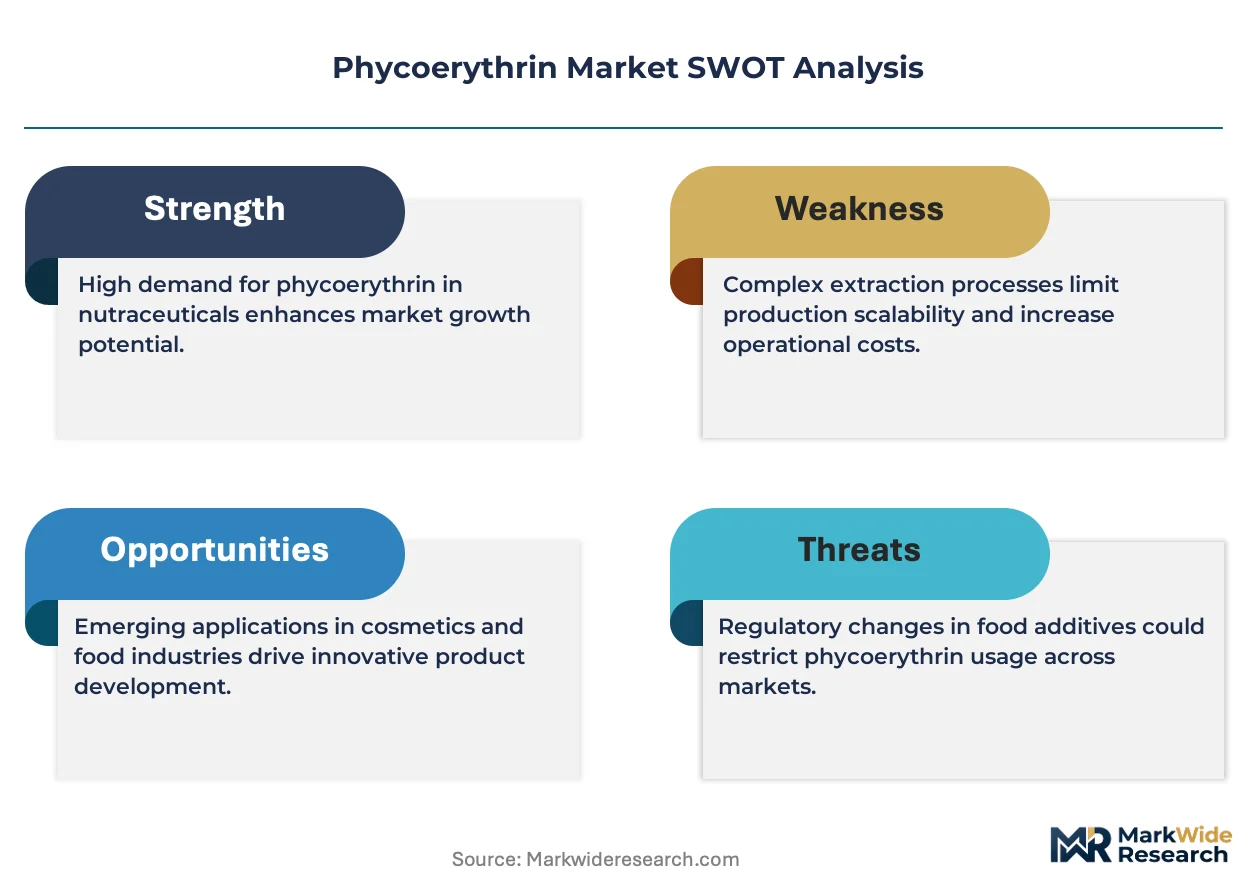
Recombinant protein expression platforms are compressing the competitive moat of wild-harvest extraction, forcing facility reinvestment and spectral standardization investments across supplier tiers.
Growth Catalysts
- Multiplexed immunoassay expansion:Clinical laboratories in the United States are scaling fluorescence-based detection panels, each requiring site-specific phycoerythrin conjugates with precise Förster resonance energy transfer pairing.
- EMA biologics guidance harmonization:Diagnostic-grade purity thresholds under EMA's evolving framework are consolidating demand around GMP-certified suppliers capable of endotoxin-controlled recombinant production.
- Flow cytometry instrument proliferation:Contract research organizations in Germany are deploying high-parameter cell analyzers, multiplying fluorophore attachment points per detection event and tightening lot-to-lot consistency requirements.
Market Restraints
- Spirulina biomass cost volatility:Wild-harvest phycoerythrin remains tethered to agricultural commodity cycles and climate-dependent cyanobacterial bloom yields in subtropical cultivation zones.
- Japanese supply concentration:Backward-integrated spirulina cultivators in Japan control a disproportionate share of food-grade pigment extraction capacity, creating single-source vulnerability for natural product lines.
- Recombinant chromophore folding inefficiency:Bacterial expression systems struggle with proper phycoerythrobilin ligation, yielding truncated apoproteins that fail to meet diagnostic-grade quantum yield specifications.
Strategic Opportunities
- Chinese diagnostic reagent localization:NMPA's import substitution policies for in-vitro diagnostic device components are opening procurement pathways for domestic phycoerythrin conjugate manufacturers with ISO 13485 certification.
- Site-specific conjugation chemistry:Enzymatic labeling technologies that bypass random lysine modification are enabling precisely defined dye-to-protein ratios for quantitative multiplexing applications.
- Clean-label food coloring premiumization:Consumer packaged goods manufacturers in Western Europe are reformulating away from synthetic azo dyes, creating pull-through for spirulina-derived phycoerythrin in confectionery and beverage applications.
Industry Challenges
- Bioprocess engineering talent scarcity:Recombinant phycoerythrin production requires hybrid expertise in algal photosynthesis and industrial fermentation, a skill intersection concentrated in limited academic programs.
- Dual-facility certification burden:Suppliers serving both food and diagnostic channels must maintain parallel quality systems under China's GB standards and ISO 13485, duplicating audit and documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phycoerythrin Market |
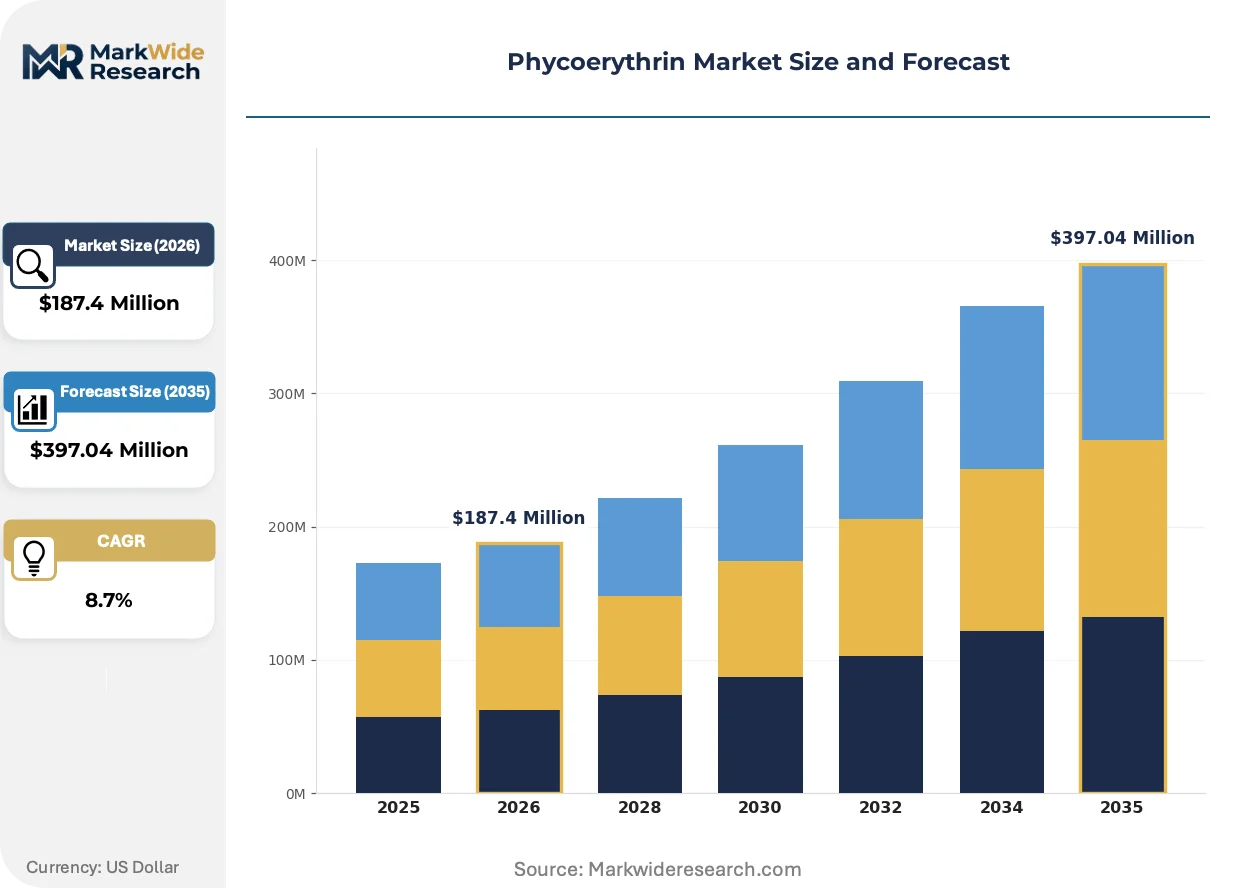
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Phycoerythrin, Recombinant Phycoerythrin, Synthetic Phycoerythrin, Phycoerythrin Conjugates End User: Research Laboratories, Pharmaceutical Companies, Nutraceutical Manufacturers, Food Industry Form: Powder, Liquid, Gel, Tablet Application: Cosmetics, Food Coloring, Biotechnology, Medical Diagnostics |
| Companies Covered | DIC Corporation, Binmei Biotechnology, Thermo Fisher Scientific Inc., Norland Products Inc., Assay Biotech Company Inc., Agilent Technologies, Phyco-Biotech, Jackson Immuno Research, Sigma-Aldrich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phycoerythrin Market Evolving Landscape
Conjugate chemistry automation and regulatory data integrity requirements are compressing development timelines while expanding the addressable application set beyond traditional biomedical detection.
CRISPR-enabled cyanobacterial strain engineering is integrating heterologous chromophore biosynthesis pathways into production hosts. Thermo Fisher Scientific and specialized contract manufacturers are adopting these platforms to reduce dependence on exogenous phycoerythrobilin supplementation. The technology is integrating upstream pigment synthesis with downstream conjugation workflows, collapsing what were previously discrete supply chain stages.
EMA's REACH chemicals framework is tightening impurity profiling obligations for substances of very high concern in diagnostic reagents. Manufacturers must now submit extended safety data sheets documenting trace heavy metal content and aggregate formation kinetics. European in-vitro diagnostic device suppliers are responding by qualifying alternative expression hosts with cleaner secretion profiles.
Research procurement is consolidating around pre-activated labeling kits that eliminate in-house conjugation protocols. University core facilities and biotechnology startups are displacing bulk pigment purchases with site-specific chemistry modules that reduce technical labor requirements. This behavioral shift is most pronounced in the United States, where National Institutes of Health funding pressures are compressing operational headcounts.
Phycoerythrin Market Segmentation
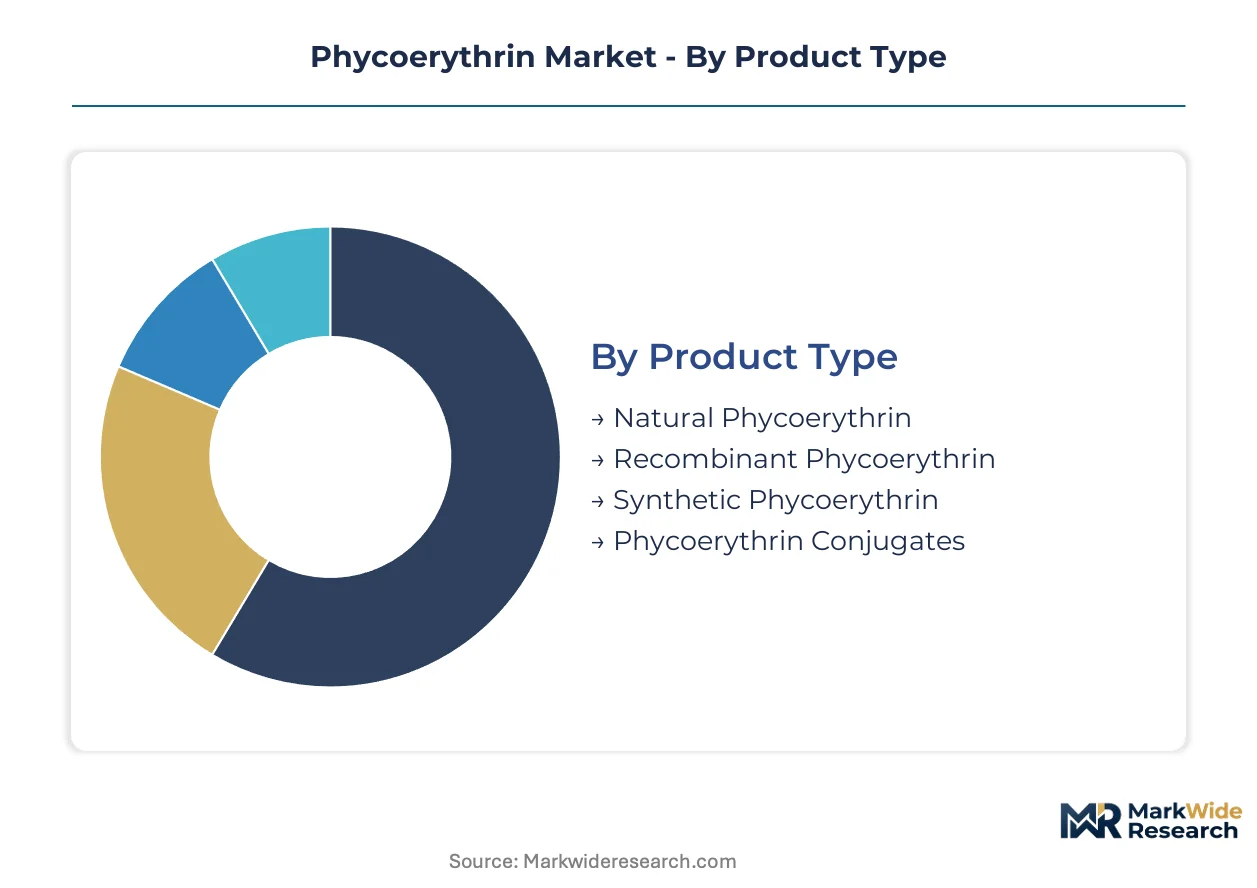
Phycoerythrin procurement patterns diverge sharply across buyer types, with diagnostic laboratories prioritizing spectral consistency while food manufacturers emphasize clean-label positioning. Understanding these segment-specific decision drivers enables suppliers to align certification investments with margin pools.
Product Type:
Buyers select product types based on purity thresholds and regulatory pathway requirements, with diagnostic applications demanding recombinant grades and food applications tolerating natural extraction methods.
- Natural Phycoerythrin:Extracted from spirulina and red algae through aqueous disruption and ammonium sulfate precipitation, this grade retains primacy in food coloring where clean-label positioning commands premium shelf placement. Demand concentrates in Western Europe as confectionery and beverage manufacturers reformulate away from synthetic azo dyes under EFSA scrutiny.
- Recombinant Phycoerythrin:Bacterial and cyanobacterial expression platforms produce this grade with controlled endotoxin profiles and reduced lot-to-lot spectral variability. Pharmaceutical companies in the United States are scaling procurement for flow cytometry conjugates as FDA biologics guidance tightens impurity specifications.
- Synthetic Phycoerythrin:Chemically synthesized chromophore analogs offer batch-to-batch uniformity but lack the quantum yield efficiency of protein-based systems. Limited adoption persists in industrial staining applications where cost minimization outweighs performance requirements.
- Phycoerythrin Conjugates:Pre-activated labeling systems with site-specific chemistry are displacing bulk pigment orders in research procurement. Multiplexed immunoassay expansion in German contract research organizations is multiplying fluorophore attachment points per detection event.
Natural phycoerythrin leads on scale through established spirulina cultivation infrastructure; phycoerythrin conjugates lead on momentum as multiplexed panels gain clinical adoption.
End User:
End-user concentration patterns reflect regional clustering of fluorescence-based diagnostic instrument manufacturing and contract research capacity.
- Research Laboratories:University core facilities and biotechnology startups are consolidating procurement around modular conjugate kits that eliminate in-house labeling protocols. National Institutes of Health funding pressures in the United States are compressing operational headcounts and favoring pre-activated reagents.
- Pharmaceutical Companies:Large-scale GMP-grade phycoerythrin procurement supports biologics development workflows and companion diagnostic programs. EMA biologics guidance harmonization is consolidating demand around endotoxin-controlled recombinant suppliers.
- Nutraceutical Manufacturers:Spirulina-derived pigment incorporation into dietary supplements targets antioxidant positioning in Asian markets. China's GB standards for food additives govern quality specifications for this channel.
- Food Industry:Clean-label reformulation drives substitution of synthetic dyes in confectionery, dairy, and beverage applications. Consumer packaged goods manufacturers prioritize Japanese backward-integrated spirulina supply for provenance verification.
Pharmaceutical companies anchor revenue concentration; research laboratories are expanding most quickly as core facility automation spreads.
Form:
Form selection trade-offs center on stability duration, reconstitution labor, and cold chain requirements across distribution distances.
- Powder:Lyophilized formulations offer extended shelf stability and reduced cold chain burden for international shipment. Diagnostic reagent manufacturers in Germany prefer this form for large-scale conjugate production workflows.
- Liquid:Ready-to-use solutions eliminate reconstitution variability in clinical laboratory settings. United States hospital systems favor liquid phycoerythrin conjugates for point-of-care instrument compatibility.
- Gel:Semi-solid matrices support topical cosmetic applications and specialized chromatography resin formulations. Limited demand persists in niche dermatological product development.
- Tablet:Compressed formulations serve direct-to-consumer nutraceutical channels with standardized dosing convenience. Chinese dietary supplement manufacturers dominate procurement for this form factor.
Powder dominates manufacturing throughput; liquid is gaining share fastest as clinical automation standardizes reconstitution protocols.
Application:
Application-specific performance requirements span quantum yield precision, regulatory burden, and consumer perception dimensions.
- Cosmetics:Pigment incorporation into skincare and color cosmetics leverages antioxidant marketing claims alongside visual appeal. Korean beauty brands drive formulation innovation in this segment.
- Food Coloring:Spirulina-derived red pigments replace carmine and synthetic alternatives in confectionery, dairy, and beverage categories. EFSA clean-label positioning requirements accelerate Western European adoption.
- Biotechnology:Fluorescent tagging supports protein purification monitoring, cell sorting, and microscopy applications. Recombinant grades with ISO 13485 certification capture margin pools in this channel.
- Medical Diagnostics:Flow cytometry and immunoassay workflows demand site-specific conjugates with precise Förster resonance energy transfer pairing. This application commands the steepest expansion trajectory as high-parameter cell analyzers proliferate in German and United States contract research organizations.
Food coloring anchors volume scale; medical diagnostics leads on momentum as multiplexed assay panels multiply fluorophore attachment points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spirulina cultivation originated in subtropical lake systems and scaled industrially through Japanese biotechnology investments in the 1980s. Diagnostic-grade phycoerythrin production subsequently concentrated in pharmaceutical clusters where fluorescence-based detection workflows matured.
United States
Flow cytometry instrument proliferation drives procurement of site-specific phycoerythrin conjugates among Boston and San Diego contract research organizations. FDA biologics guidance tightens endotoxin specifications for diagnostic-grade material entering clinical workflows. NIH funding pressures compress operational headcounts at university core facilities, accelerating consolidation around pre-activated labeling kits.
Germany
High-parameter cell analyzer deployment across Frankfurt and Munich CROs multiplies fluorophore attachment points per detection event. EMA REACH chemicals framework mandates extended safety data sheets documenting trace heavy metal content and aggregate formation kinetics. ISO 13485 certification requirements govern conjugate manufacturing for in-vitro diagnostic device suppliers serving European hospital systems.
China
NMPA import substitution policies open procurement pathways for domestic phycoerythrin conjugate manufacturers with ISO 13485 certification. GB standards for food additives regulate pigment grades destined for nutraceutical channels, creating dual-facility certification burdens. Yangtze River Delta biotech clusters concentrate recombinant expression platform development for diagnostic reagent localization.
Japan
Backward-integrated spirulina cultivators control disproportionate share of food-grade pigment extraction capacity, creating single-source vulnerability for natural product lines. METI industrial biotechnology programs support CRISPR-enabled cyanobacterial strain engineering for heterologous chromophore biosynthesis. Osaka and Tokyo metropolitan areas anchor conjugate chemistry automation investments serving Asia-Pacific diagnostic markets.
Phycoerythrin Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with integrated reagent-instrument ecosystems. Recombinant production specialists and backward-integrated algal cultivators occupy distinct tier positions based on purity grade capabilities. Three archetypes dominate: diversified conglomerates with conjugate chemistry depth, regional spirulina cultivators with food-grade extraction infrastructure, and recombinant expression specialists with GMP-certified facilities. Capacity expansion and site-specific conjugation technology licensing constitute the dominant competitive moves.
Within the diversified conglomerate tier, Thermo Fisher Scientific exemplifies integrated reagent-instrument positioning. DIC Corporation anchors the backward-integrated cultivator archetype through captive spirulina supply chains. Among recombinant expression specialists, Ag Technologies occupies a position emphasizing lot-to-lot spectral consistency for diagnostic applications.
| Leading Market Players |
|---|
| DIC Corporation |
| Binmei Biotechnology |
| Thermo Fisher Scientific Inc. |
| Norland Products Inc. |
| Assay Biotech Company Inc. |
| Agilent Technologies |
| Phyco-Biotech |
| Jackson Immuno Research |
| Sigma-Aldrich |
| Others |
Value Network & Pricing Analysis
Hybrid expertise in algal photosynthesis and industrial fermentation, concentrated in limited academic programs across Japan and coastal China, drives labor-cost differentials that widen pricing-tier spreads between GMP-certified recombinant grades and commodity natural extracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates diagnostic-grade recombinant phycoerythrin with ISO 13485 certification from food-grade natural extracts and bulk industrial pigments. Price differentiation hinges on endotoxin-controlled production and lot-to-lot spectral consistency guarantees. Cost compression in the natural extraction tier is intensifying because spirulina biomass cost volatility exposes wild-harvest suppliers to agricultural commodity cycles. Research laboratories exhibit the highest price sensitivity, while pharmaceutical companies prioritize performance specifications over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from diagnostic reagent manufacturers mandate multi-supplier qualification across Japanese backward-integrated spirulina cultivators, Chinese recombinant expression platforms, and German conjugate chemistry specialists. Raw material dependencies center on phycoerythrobilin chromophores, ammonium sulfate precipitation reagents, and chromatography resins. Single-source vulnerability concentrates in Japanese food-grade pigment extraction capacity. Distribution runs through cold-chain logistics networks serving pharmaceutical clusters in Boston, Frankfurt, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phycoerythrin market functions as a regulatory compounder, with EMA's evolving REACH chemicals framework and FDA biologics guidance tightening purity thresholds and consolidating procurement around certified suppliers.
For Market Incumbents: Acquire CRISPR-enabled cyanobacterial strain engineering capabilities to reduce dependence on exogenous chromophore supplementation and counter recombinant production specialists threatening spectral consistency moats. Expand ISO 13485-certified capacity in the Yangtze River Delta to capture NMPA import substitution procurement pathways. For New Entrants and Emerging Players: Site-specific enzymatic conjugation chemistry offers a technology-first wedge into the pre-activated labeling kit segment displacing bulk pigment orders in United States university core facilities. Target white-space opportunities in Chinese domestic diagnostic reagent manufacturing and Western European clean-label food coloring reformulation. Lead with modular kit configurations that eliminate in-house technical labor requirements. For Investors and Strategic Acquirers: Life science conglomerates with integrated reagent-instrument ecosystems are the most active acquirer in this space, seeking conjugate chemistry depth to fortify fluorescence-based detection workflows. The five-to-ten-year viability window favors recombinant expression platforms with GMP certification over wild-harvest extraction infrastructure. Target acquisition archetypes include ISO 13485-certified contract manufacturers with site-specific chemistry capabilities. Watch NMPA localization policy implementation velocity as the signal indicating inflection in Chinese domestic supplier market share.| Strategic Initiative | Industry Significance |
|---|---|
| Site-Specific Conjugation Chemistry Licensing | Enables precise dye-to-protein ratios for quantitative multiplexing in German CRO workflows. |
| Backward Integration into Spirulina Cultivation | DIC Corporation's captive supply chains in Japan reduce food-grade pigment cost volatility exposure. |
| CRISPR-Enabled Strain Engineering Adoption | Collapses upstream pigment synthesis with downstream conjugation for Thermo Fisher Scientific's integrated ecosystem. |
| ISO 13485 Certification Investment | Opens NMPA procurement pathways for Chinese domestic manufacturers targeting import substitution. |
| Modular Pre-Activated Kit Expansion | Captures NIH funding-compressed United States research laboratory procurement consolidation. |
Research Methodology
Coverage spans the United States, Germany, China, and Japan, with primary inputs from each market combining structured interviews with regulatory affairs leads at diagnostic reagent manufacturers, procurement directors at contract research organizations, and technical R&D directors at algal cultivation facilities. Secondary validation draws from FDA biologics guidance documents, EMA REACH chemicals framework submissions, NMPA in-vitro diagnostic device regulations, and Japanese METI industrial biotechnology program disclosures. Bottom-up segment sizing triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models product type segmentation (natural, recombinant, synthetic, conjugates), end-user categories (research laboratories, pharmaceutical companies, nutraceutical manufacturers, food industry), form factors (powder, liquid, gel, tablet), and application-specific performance requirements. CAGRs derive from regression analysis against fluorescence-based detection instrument installation bases and multiplexed immunoassay panel adoption curves. Industry-specific inputs include flow cytometry parameter expansion rates and clean-label food reformulation commitment timelines from European consumer packaged goods manufacturers.
The model holds under steady regulatory harmonization trajectories; deviation in EMA-FDA biologics guidance divergence or NMPA localization policy acceleration would shift supplier competitive positioning materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Asia-Pacific Feed Pigments Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Europe Natural Dyes and Pigments Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Brilliant Blue FCF Colors Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Pharmaceutical Dyes Market
Dyes and Pigments
Azo Pigments Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Reactive Dyes Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Asia-Pacific Pigments Market