
 Inorganic Color Pigments Market | 2026-2036
Inorganic Color Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Color Pigments Market Intelligence
Automotive coatings demand is recalibrating the inorganic color pigments landscape as electric vehicle manufacturers prioritize heat-stable formulations. BASF SE leverages its pigment R&D intensity across European coating hubs. LANXESS AG anchors its position through specialized iron oxide production for high-performance applications. Cathay Industries dominates Asian supply chains with integrated titanium dioxide operations.
Inorganic color pigments encompass metal oxide and mineral-derived colorants engineered for thermal stability, UV resistance, and chemical inertness, typically manufactured through calcination or precipitation processes to achieve particle sizes between 0.1 and 10 micrometers for industrial coloration. Titanium dioxide commands the largest product type position due to its opacity efficiency across coating matrices, while iron oxides sustain mature volume flows in construction applications. The coatings application segment leads value generation, though plastics applications compete for margin pools as polymer compatibility requirements intensify.
REACH regulations in Europe restrict cadmium and lead-based pigment formulations, while EPA oversight in the United States governs heavy metal discharge from manufacturing facilities, collectively elevating compliance costs for non-compliant producers. China's MEE enforces emission standards at titanium dioxide production sites, reshaping export availability from Shandong and Sichuan provinces. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation portfolios and manufacturing footprints.
Market Dynamics
REACH restrictions on cadmium and lead-based formulations are forcing manufacturers to rebuild pigment portfolios from the ground up, while electric vehicle thermal management requirements pull heat-stable metal oxides into premium coating specifications.
Growth Catalysts
- Automotive thermal coating specifications:Electric vehicle battery enclosures and powertrain components require pigments with thermal stability exceeding 300°C, redirecting R&D budgets toward complex inorganic colorants.
- REACH compliance deadlines:ECHA authorization requirements for legacy heavy metal pigments are accelerating substitution programs across German, French, and Italian coating formulators.
- Construction sector mineral pigment standardization:Iron oxide demand concentrates in infrastructure concrete coloration, with public works specifications in India and Brazil mandating UV-stable earth pigments for aesthetic durability.
Market Restraints
- Titanium dioxide feedstock concentration:Ilmenite and rutile supply chains cluster around Australian and South African mining operations, exposing pigment manufacturers to concentrate pricing volatility and shipping disruption.
- Calcination energy intensity:Synthetic iron oxide production requires sustained thermal processing above 800°C, tying manufacturing economics to natural gas and electricity tariff structures.
- Organic pigment substitution in plastics:High-performance organic colorants with improved heat resistance are capturing share in polymer masterbatch applications below 200°C service temperatures.
Strategic Opportunities
- Indonesian industrial corridor expansion:Batam and Java manufacturing zones are attracting coating compounders serving ASEAN automotive assembly plants, creating localized pigment formulation demand.
- Solar reflectance index compliance:Cool roof mandates in California Title 24 and similar codes in the UAE are driving specification of infrared-reflective complex inorganic color pigments for energy-efficient building envelopes.
- Digital color matching integration:Spectrophotometry and cloud-based formulation databases are compressing custom color development cycles from weeks to days for architectural coating clients.
Industry Challenges
- Particle engineering expertise scarcity:Sub-micron pigment dispersion for automotive clearcoat compatibility requires specialized colloid chemistry capabilities that outpace current technical training pipelines.
- Multi-jurisdiction certification timelines:Simultaneous EPA TSCA notification, REACH registration, and China MEE environmental assessment create 18-36 month product launch delays for novel pigment chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Color Pigments Market |
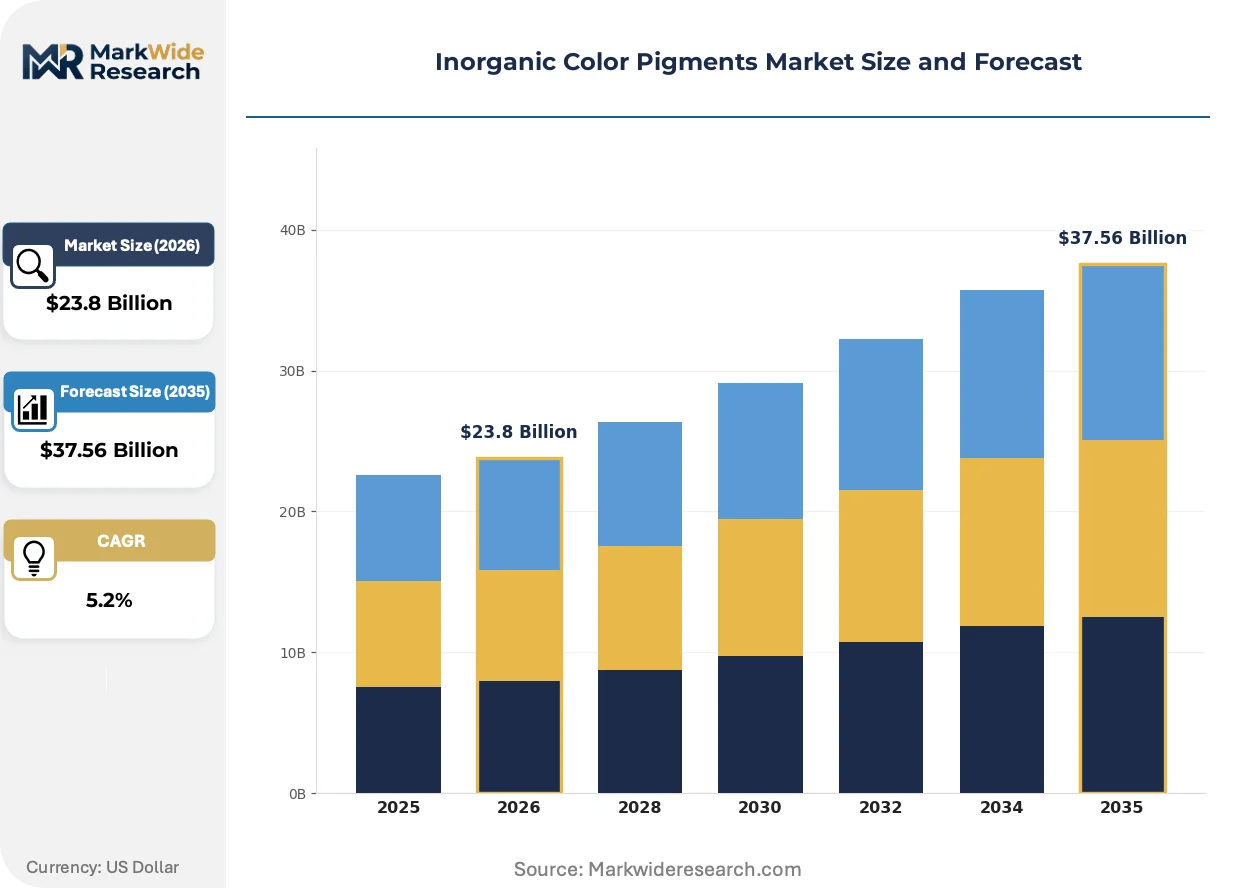
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $37.56 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Oxides, Titanium Dioxide, Chromium Oxide, Ultramarine Blue Application: Coatings, Plastics, Construction, Inks End User: Automotive, Aerospace, Packaging, Textiles Distribution Channel: Direct Sales, Online, Distributors, Retail |
| Companies Covered | Shepherd Color Company, Venator Materials PLC, LANXESS AG, Heubach GmbH, Ferro Corporation, BASF SE, Clariant AG, Cathay Industries, Tata Pigments Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Color Pigments Market Strategic Shifts & Innovations
Formulation science is pivoting toward multi-functional pigments that combine coloration with thermal management or corrosion inhibition, collapsing separate additive categories into single-particle solutions.
Complex inorganic color pigments engineered through controlled calcination of metal oxide precursors are consolidating technical differentiation in automotive OEM clearcoat applications. Premium vehicle manufacturers in Germany and Japan specify these materials for their combined UV durability and infrared reflectance. The technology is consolidating supplier tiers as smaller pigment houses lack the capital intensity for high-temperature synthesis infrastructure.
EPA effluent guidelines for metal finishing operations are tightening discharge limits for chromium and nickel compounds, compelling US-based pigment manufacturers to install closed-loop wastewater systems. The rulemaking affects surface treatment steps in titanium dioxide post-processing most severely. Coating formulators in Michigan and Ohio are pre-qualifying alternative corrosion-resistant pigments to avoid supply interruption.
Specification behavior among architectural coating buyers is compressing color development cycles and unbundling technical service from pigment supply contracts. Large formulators in Texas and Florida now maintain in-house spectrophotometry laboratories rather than relying on supplier-managed color matching. The shift is most visible in North American commercial building projects where general contractors demand real-time formulation adjustments during construction phases.
Inorganic Color Pigments Market Segmentation
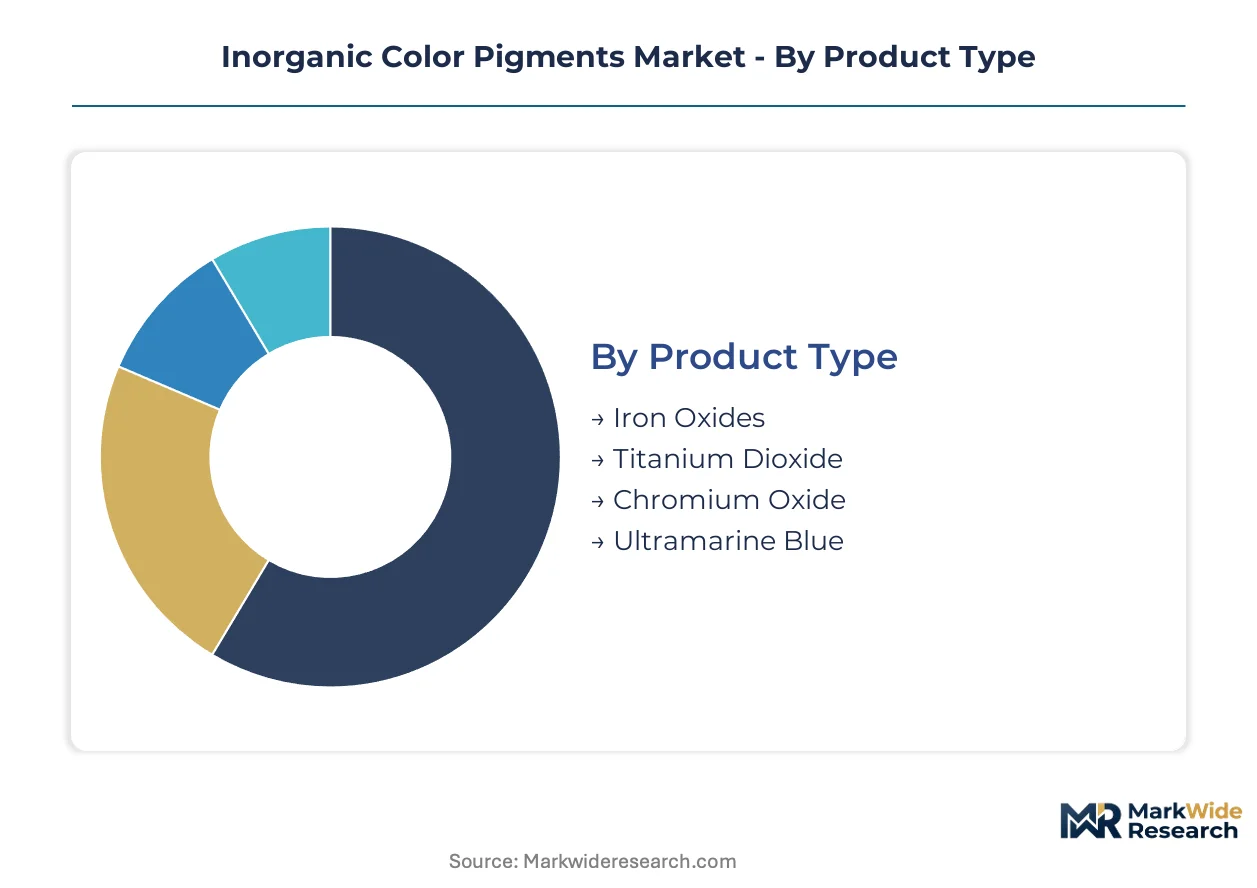
Segmentation in the inorganic color pigments market reveals how capital intensity and regulatory exposure concentrate margin pools across distinct technical specifications. Understanding these divides allows suppliers to align R&D spend with segments where particle engineering expertise commands pricing power.
Product Type:
Capital intensity varies dramatically across synthesis routes, with high-temperature calcination infrastructure separating integrated producers from toll manufacturers.
- Titanium Dioxide:Rutile and anatase crystal structures deliver unmatched opacity efficiency across coating matrices. Chloride-process capacity concentrates at integrated sites in Germany and China, where ilmenite-to-pigment verticality insulates margin structures from feedstock volatility.
- Iron Oxides:Synthetic red, yellow, and black variants require sustained thermal processing above 800°C, tying manufacturing economics to natural gas tariff structures. Construction sector demand in India and Brazil concentrates volume flows, though automotive specifications are pulling higher-purity grades into premium coating applications.
- Chromium Oxide:Refractory-grade green pigments serve high-temperature industrial coatings with thermal stability exceeding 1000°C.
- Ultramarine Blue:Sulfur-based complex pigments maintain niche positions in plastics and cosmetics where FDA and EFSA food-contact compliance is mandatory.
Titanium dioxide absorbs the bulk of installed capacity; iron oxides are expanding most quickly as infrastructure investment accelerates across emerging economies.
Application:
Customer technical requirements fragment the market by polymer compatibility thresholds and service temperature ceilings.
- Coatings:Architectural, automotive OEM, and industrial formulations demand distinct particle size distributions and dispersion stability. ECHA REACH restrictions on heavy metal content are accelerating reformulation toward compliant complex inorganic colorants in German and French coating hubs.
- Plastics:Masterbatch applications require heat resistance above polymer processing temperatures, with polymer-specific surface treatments determining compatibility. Polypropylene and polyethylene compounders in the US Midwest and Germany's Ruhr region are tightening specifications for migration-resistant pigments.
- Construction:Concrete coloration relies on UV-stable earth pigments for aesthetic durability in infrastructure projects.
- Inks:Publication gravure and packaging flexo applications prioritize fine particle grades for print clarity.
Coatings command the deepest technical service relationships; plastics applications are gaining share fastest as polymer processing temperatures rise.
End User:
Specification authority sits with distinct buyer types, each imposing unique certification and performance validation protocols.
- Automotive:OEM clearcoat specifications require combined UV durability and infrared reflectance for thermal management in electric vehicle battery enclosures. German and Japanese premium manufacturers are consolidating supplier tiers around producers with high-temperature synthesis infrastructure.
- Aerospace:Mil-spec and OEM coatings demand extreme thermal stability and corrosion inhibition for airframe and engine applications.
- Packaging:Food-contact compliance drives migration testing requirements across flexible film and rigid container segments.
- Textiles:Fiber dyeing and printing applications concentrate in South Asian manufacturing zones with distinct wastewater discharge constraints.
Automotive absorbs the majority of premium pigment R&D investment; aerospace specifications are climbing fastest as next-generation engine programs advance.
Distribution Channel:
Channel economics reflect order scale, technical service intensity, and geographic proximity to manufacturing clusters.
- Direct Sales:Large coating formulators and polymer compounders negotiate volume contracts with dedicated technical service support. BASF SE and LANXESS AG maintain direct relationships with German automotive OEMs and tier-one suppliers.
- Distributors:Regional stocking points serve mid-size formulators with just-in-time delivery and color matching support.
- Online:E-procurement platforms capture spot purchases and standard-grade transactions from small-scale buyers.
- Retail:Specialty arts and DIY channels move small-package decorative pigments with minimal technical support.
Direct sales anchor revenue concentration; distributor networks are expanding most quickly as ASEAN coating compounders localize supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Batam and Java manufacturing zones in Indonesia attract coating compounders through special economic zone tax incentives, creating localized demand clusters that reshape ASEAN supply chain geography.
United States
Automotive OEM clearcoat specifications in Michigan and Ohio drive premium pigment consumption for electric vehicle thermal management. EPA effluent guidelines tighten discharge limits for chromium and nickel compounds, compelling closed-loop wastewater investments. Coating formulators in Texas and Florida maintain in-house spectrophotometry laboratories for real-time color matching on commercial building projects.
Germany
ECHA REACH authorization deadlines for cadmium and lead-based pigments accelerate substitution programs across coating formulators. The country's national chemical regulator enforces heavy metal content restrictions that elevate compliance costs for legacy formulations. Industrial pigment consumption concentrates in the Ruhr region, where specialty compounders serve automotive tier-one suppliers with heat-stable metal oxide specifications.
China
Titanium dioxide production capacity clusters in Shandong and Sichuan provinces, with the Ministry of Ecology and Environment enforcing emission standards that reshape export availability. The country's national environmental regulator monitors discharge from ilmenite processing sites. Coating manufacturers in the Yangtze River Delta integrate digital color matching platforms to compress formulation development cycles for architectural clients.
India
Infrastructure concrete coloration mandates UV-stable iron oxide pigments for public works durability in Maharashtra and Gujarat. The Bureau of Indian Standards certifies construction-grade mineral pigments for highway and bridge applications. Pigment distributors in Delhi-NCR and Bangalore serve mid-size formulators with just-in-time delivery and technical support for polymer masterbatch applications.
Japan
Premium vehicle manufacturers in Kansai and Chubu regions consolidate supplier tiers around producers with high-temperature synthesis infrastructure for complex inorganic colorants. METI oversees industrial chemical safety assessments for novel pigment introductions. Coating R&D facilities in Nagoya collaborate with automotive OEMs on infrared-reflective formulations for battery enclosure thermal management.
Inorganic Color Pigments Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated producers controlling titanium dioxide value chains while toll manufacturers serve niche iron oxide applications. The vendor base organizes around three strategic archetypes: capital-intensive integrated miners with ilmenite-to-pigment verticality, specialized calcination houses with high-temperature synthesis expertise, and regional compounders with polymer-specific surface treatment capabilities. Competitive moves concentrate on backward integration into feedstock sources and geographic expansion through ASEAN manufacturing partnerships.
Among Germany-based chemical conglomerates, BASF SE and LANXESS AG occupy positions within the integrated producer archetype, leveraging R&D intensity across European coating hubs. Shepherd Color Company exemplifies the specialized calcination house model, with Cincinnati-based operations reflecting American industrial pigment heritage. Cathay Industries anchors the Asia-Pacific supply chain vector through integrated titanium dioxide production.
| Leading Market Players |
|---|
| Shepherd Color Company |
| Venator Materials PLC |
| LANXESS AG |
| Heubach GmbH |
| Ferro Corporation |
| BASF SE |
| Clariant AG |
| Cathay Industries |
| Tata Pigments Limited |
| Others |
Cost & Logistics Intelligence
Colloid chemistry expertise scarcity in Germany's Ruhr industrial corridor widens pricing spreads between premium automotive-grade pigments and commodity construction grades, as labor-cost differentials compound calcination energy intensity to stratify tier boundaries.
Pricing Analysis
Short lead-time premiums dominate pigment procurement economics, with automotive OEMs paying substantial markups for just-in-time complex inorganic colorant delivery against spot-market discounts for standard iron oxide inventory held by regional distributors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—REACH-compliant heat-stable formulations command substantial premiums over legacy heavy metal alternatives, while construction-grade mineral pigments face margin compression from ilmenite feedstock volatility. Price differentiation hinges on volume scale and geographic delivery cost, with large coating compounders in Michigan and Texas extracting favorable terms through captive supply arrangements. Buyers in the plastics masterbatch segment exhibit highest price sensitivity due to organic pigment substitution threats below 200°C service temperatures.
Supply Chain Analysis
Automotive OEM qualification protocols gate supply chain participation, with 18-36 month certification timelines for novel pigment chemistries creating structural barriers to new supplier entry. Raw material sourcing concentrates in Australia and South Africa for ilmenite and rutile feedstocks, with synthetic iron oxide production anchored in Germany and China where natural gas tariff structures determine manufacturing economics. The supply chain draws from Shandong and Sichuan provinces for titanium dioxide base materials, while high-temperature calcination infrastructure clusters in the US Midwest and Japan's Kansai region. Single-source vulnerability persists for chloride-process rutile feedstock, exposing pigment manufacturers to concentrate pricing volatility and shipping disruption. Distribution runs through direct sales relationships with large formulators, supplemented by regional distributors serving mid-size coating compounders in ASEAN manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inorganic color pigments sector sits in a technology-transition phase as complex inorganic colorants displace legacy cadmium and lead-based formulations under regulatory pressure.
For Market Incumbents: Lock in automotive OEM qualification status by accelerating REACH-compliant reformulation programs ahead of ECHA authorization deadlines, while securing captive ilmenite supply through backward integration into Australian mining partnerships. High-temperature synthesis infrastructure represents a defendable moat against toll manufacturers lacking capital intensity for multi-jurisdiction certification investments. For New Entrants and Emerging Players: REACH restrictions in Europe open a window for specialized calcination houses targeting infrared-reflective complex pigments for California Title 24 cool roof compliance, bypassing entrenched automotive supply tiers. Indonesian industrial corridor expansion presents the most penetrable geography, with Batam and Java manufacturing zones attracting ASEAN automotive assembly plants seeking localized pigment formulation partners. A go-to-market angle emphasizing digital color matching integration—spectrophotometry platforms compressing custom development cycles—differentiates against incumbent technical service bundles. For Investors and Strategic Acquirers: Re-rating potential sits with specialized calcination houses possessing high-temperature synthesis expertise given consolidation pressure from German and Japanese automotive OEMs reducing supplier tiers. Long-term viability over a 5-10 year window favors producers with demonstrated multi-jurisdiction certification capabilities and backward integration into feedstock sources. The signal to watch is EPA effluent guideline tightening for chromium and nickel discharge, which would accelerate closed-loop wastewater investment requirements and strand non-compliant manufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Sources | Captive ilmenite supply from Australian mining operations insulates margin structures from concentrate pricing volatility. |
| High-Temperature Synthesis Capacity Expansion | Complex inorganic colorant production above 800°C qualifies suppliers for German automotive OEM clearcoat specifications. |
| REACH Compliance Reformulation Program | Substitution of cadmium and lead-based pigments ahead of ECHA deadlines preserves European coating formulator relationships. |
| Digital Color Matching Platform Deployment | Cloud-based spectrophotometry databases compress architectural coating development cycles from weeks to days. |
| ASEAN Manufacturing Partnership | Indonesian special economic zone presence captures localized demand from Batam and Java coating compounders. |
Research Approach
Document review covered ECHA REACH registration databases, EPA effluent guideline rulemakings, and China MEE emission standards, complemented by interviews with plant managers at titanium dioxide production facilities, procurement leads at German automotive OEMs, technical R&D directors at coating formulators, and distribution channel partners serving ASEAN industrial zones. Secondary validation drew from SEC 10-K filings of listed pigment producers, Cefic chemical industry reports, and customs trade data for ilmenite and rutile concentrate flows. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across the analysis window.
Segmented outputs reflect product type stratification by synthesis route capital intensity, application-grade differentiation by polymer compatibility thresholds, and end-user certification requirements by automotive versus construction specification authority. CAGRs were derived from regression analysis against ilmenite pricing volatility, natural gas tariff trajectories, and electric vehicle production forecasts. Industry-specific forecast inputs include calcination energy cost curves and multi-jurisdiction regulatory compliance timelines for novel pigment chemistries.
The model assumes a particular technology adoption path; alternative pathways for organic pigment heat resistance advancement above 200°C would alter the outlook for inorganic colorant displacement in plastics masterbatch applications. Forecasts reflect assumptions regarding ECHA enforcement intensity and EPA effluent guideline implementation pace. A model refresh is warranted upon material change in titanium dioxide feedstock concentration or REACH authorization timeline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Europe Natural Dyes and Pigments Market
Dyes and Pigments
Pearlescent Pigments Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Global Thermochromic Paint Market
Dyes and Pigments
LAMEA Optical Brighteners Market
Dyes and Pigments
Pigment Additive Film Market
Dyes and Pigments
Cacao Husk Pigment Market
Dyes and Pigments
Organic Lake Pigments Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Pigment Dispersion Resin Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Fluorescent Brightening Agents Market
Dyes and Pigments
Mulch Colorants Market