
 Hybrid Air Conditioner Market | 2026-2036
Hybrid Air Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Air Conditioner Market Insights
Chinese compressor manufacturing clusters are restructuring supply chains for hybrid thermal-electric cooling modules. Gree Electric leverages captive semiconductor foundry partnerships to stabilize inverter component flows. Daikin Industries anchors premium positioning through proprietary refrigerant management systems. Mitsubishi Electric dominates variable-speed drive integration for residential split configurations across East Asian markets.
Hybrid air conditioners combine vapor-compression cycles with auxiliary thermal or electrical inputs to reduce grid dependency during peak cooling loads. These systems typically integrate inverter-driven compressors with solar thermal collectors or battery buffers, achieving coefficient of performance ratings that exceed conventional single-source units by drawing from dual energy reservoirs. Split systems lead volume shipments due to retrofit compatibility and modular installation economics. Inverter technology captures the fastest expansion trajectory as utility time-of-use tariffs penalize fixed-speed compressor operation. Smart-connected controls concentrate margin pools through recurring software service attachments and predictive maintenance contracts.
EPA refrigerant phase-down schedules under the AIM Act and EU F-Gas Regulation are forcing manufacturers toward lower-global-warming-potential working fluids. China's GB standards for seasonal energy efficiency ratio testing and India's Bureau of Energy Efficiency mandatory labeling create divergent compliance pathways that fragment product platform strategies. Stakeholders must monitor how regional efficiency test conditions and refrigerant quotas reshape platform economics before committing capital to localized assembly capacity.
Market Dynamics
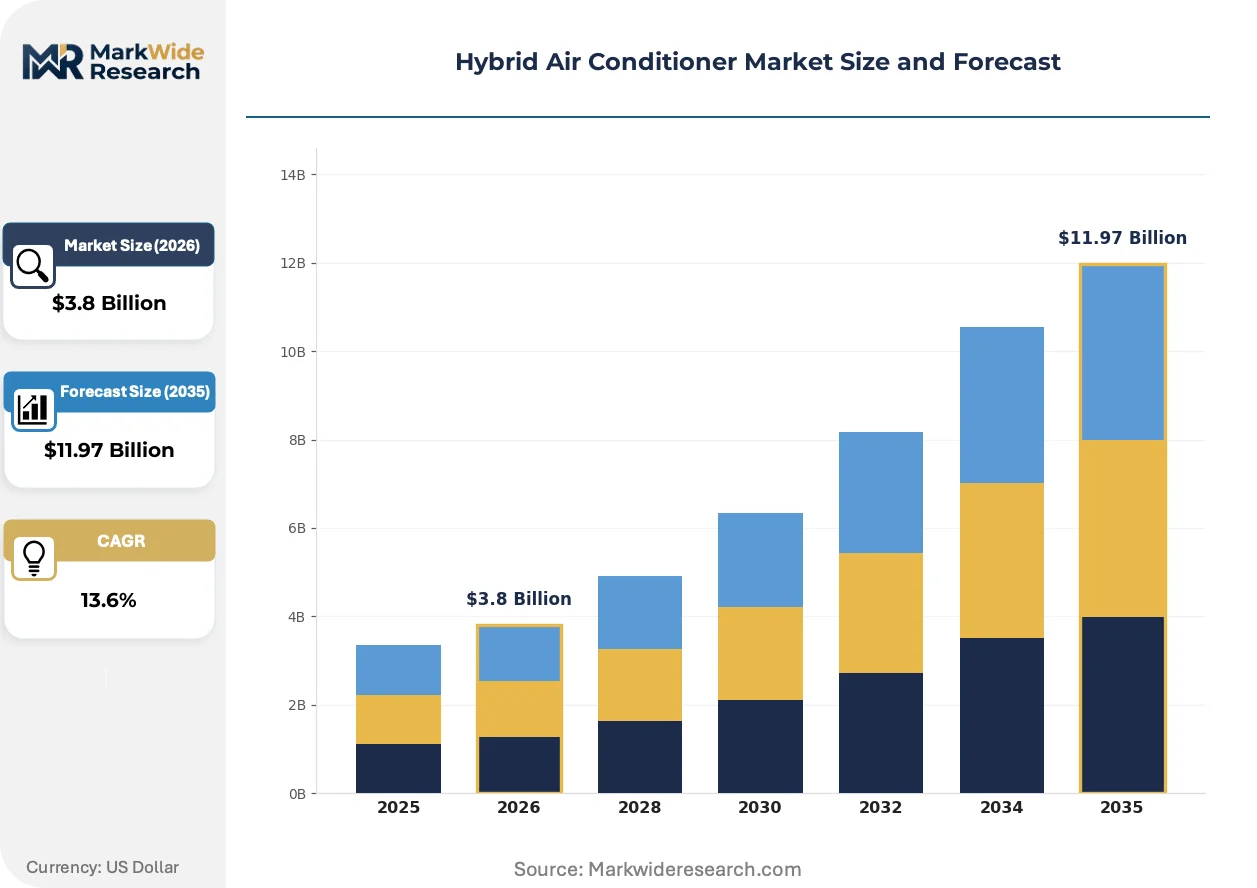
Inverter-integrated compressor architectures are compressing fixed-speed equipment margins while dual-energy cooling configurations absorb capital flows previously directed toward conventional vapor-compression platforms. This technological displacement is restructuring procurement criteria across commercial building portfolios and residential retrofit channels.
Growth Catalysts
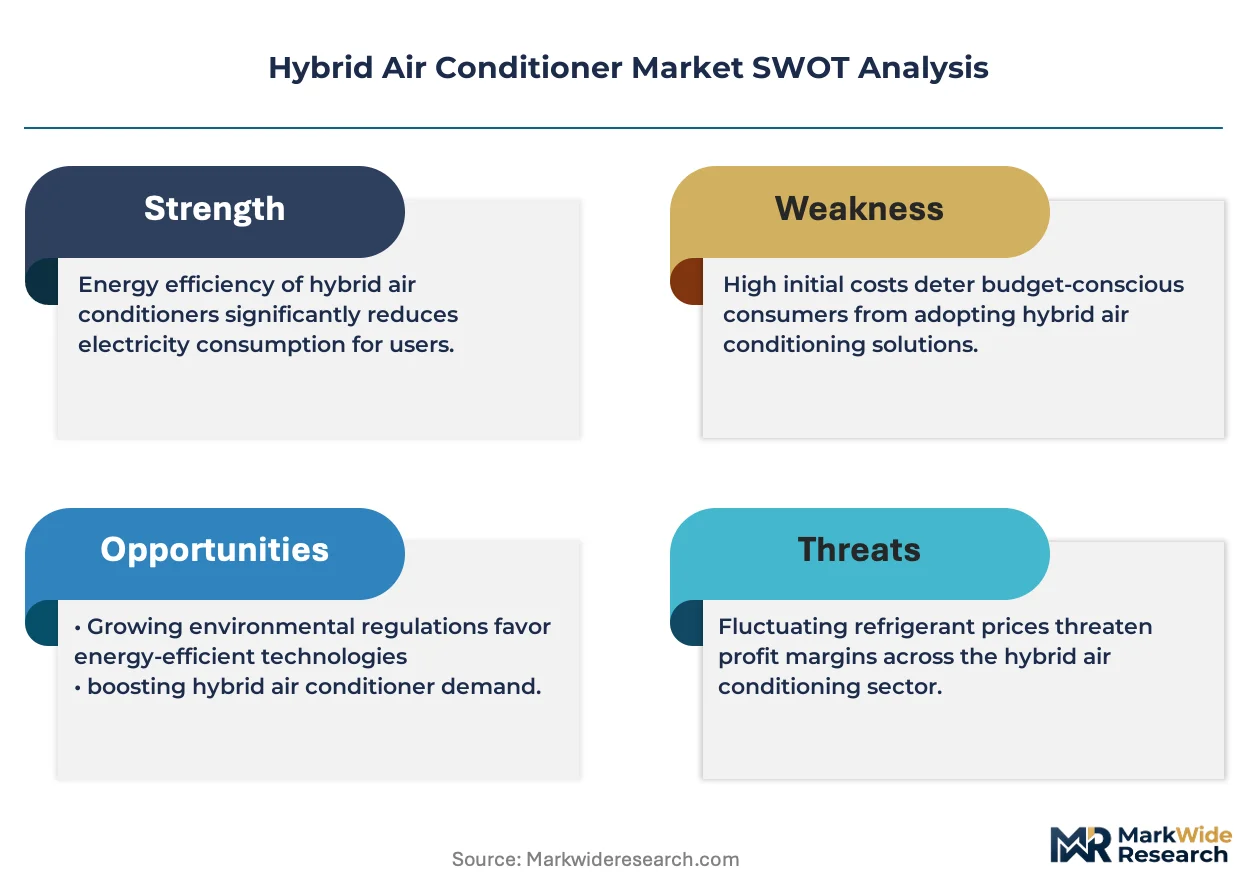
- EU F-Gas Regulation phase-down schedules:The refrigerant quota system accelerates manufacturer migration toward lower-global-warming-potential working fluids, expanding addressable market for hybrid thermal-electric systems that reduce refrigerant charge volumes.
- Solar thermal collector integration:Building-integrated photovoltaics with thermal recovery modules enable coefficient-of-performance improvements that satisfy tightening seasonal energy efficiency ratio testing under China's GB standards.
- Commercial building operators in Southeast Asia:Anticipatory procurement of dual-energy cooling systems ahead of mandatory efficiency labeling creates demand pull for inverter-driven split configurations with battery buffering.
Market Restraints
- Semiconductor component concentration:Inverter control module supply chains cluster in East Asian foundry networks, exposing manufacturers to input volatility when captive semiconductor partnerships face capacity constraints.
- Copper-aluminum alloy pricing volatility:Heat exchanger material costs fluctuate with commodity exchange movements, compressing gross margins on mid-tier equipment categories where price elasticity limits pass-through.
- Refrigerant handling certification complexity:The EPA's Section 608 technician certification requirements and EU F-Gas company certification obligations create compliance friction that slows retrofit installation velocity.
Strategic Opportunities
- India's Bureau of Energy Efficiency mandatory labeling expansion:Star rating program broadening to include hybrid cooling configurations creates regulatory tailwind for inverter-integrated equipment penetration in residential and light-commercial segments.
- Predictive maintenance software attachments:Smart-connected control platforms enable recurring service revenue streams through compressor health monitoring and refrigerant leak detection algorithms.
- Phase-change material thermal storage convergence:Integration of solid-liquid phase change buffers with vapor-compression cycles enables load-shifting capabilities that align with utility time-of-use tariff structures.
Industry Challenges
- Inverter drive calibration expertise scarcity:Variable-speed compressor commissioning requires specialized technician training that outpaces vocational program output in emerging installation markets.
- Dual-energy system integration complexity:Sizing algorithms must reconcile thermal collector output variability with battery state-of-charge management, extending project engineering cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Air Conditioner Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Window, Split, Central Technology: Inverter, Non-Inverter, Smart, Traditional End User: Residential, Commercial, Industrial, Institutional Seasonal Use: Summer, Winter, Year-Round, Transitional |
| Companies Covered | Gree Electric, Mitsubishi Electric, Daikin Industries, Rheem Manufacturing, LG Electronics, Carrier Global, Trane Technologies, Bosch Thermotechnik, Lennox International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Air Conditioner Market Trends and Innovations
Software-defined thermal management is displacing hardware-centric cooling architectures across commercial building portfolios. Predictive control algorithms now govern compressor modulation, thermal storage dispatch, and grid-interactive load response through unified platforms.
Refrigerant leak detection sensor networks are automating compliance documentation for EPA AIM Act reporting obligations and EU F-Gas Regulation inventory requirements. Facility operators in California and Germany deploy these systems to preempt regulatory penalties. The technology is automating maintenance scheduling by triggering service dispatches before charge loss thresholds breach compliance limits.
The EPA's refrigerant phase-down schedules under the AIM Act compress hydrofluorocarbon availability for servicing existing equipment. Manufacturers respond by accelerating platform transitions to hydrofluoroolefin blends and natural refrigerant alternatives. Commercial rooftop unit segments face the steepest retrofit cost exposure, driving premature replacement cycles toward hybrid thermal-electric configurations.
Building automation system procurement now prioritizes open-protocol interoperability over proprietary control ecosystems. Facility managers in Singapore and Dubai specify BACnet and Modbus compatibility to avoid vendor lock-in. This specification shift fragments incumbent equipment suppliers' software attachment strategies and elevates third-party control integrators in vendor selection criteria.
Hybrid Air Conditioner Market Segmentation
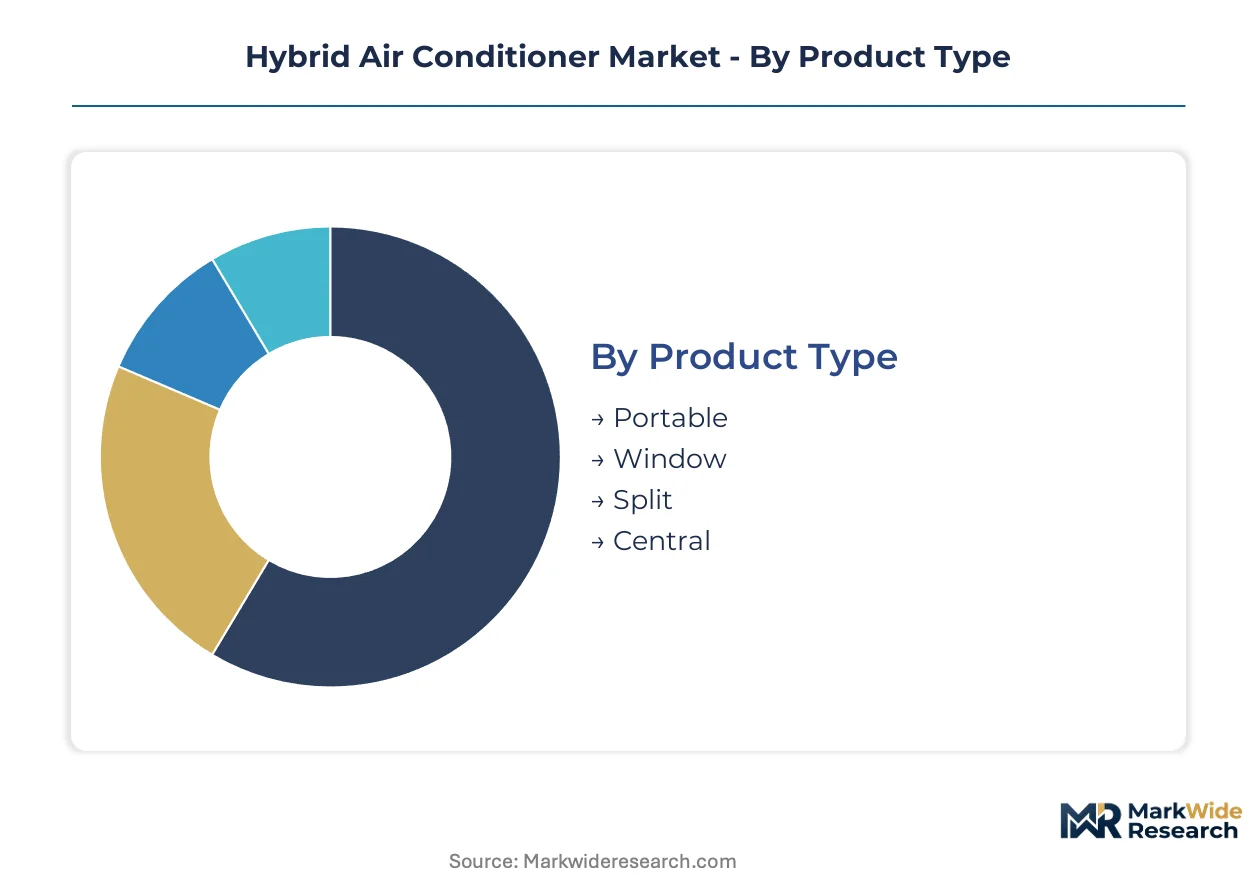
Segmentation in the hybrid air conditioner market reveals how dual-energy configurations and inverter integration reshape procurement patterns across building types and climate zones. Manufacturers calibrate platform strategies against divergent efficiency test conditions and retrofit compatibility requirements that vary by product format and end-use intensity.
Product Type:
Standardization dominates portable and window formats, while split and central systems demand extensive customization for thermal collector integration and battery buffering specifications.
- Portable:Self-contained units with plug-and-play thermal-electric modules suit rental properties and temporary cooling needs. Demand concentrates in European urban apartments where landlord-tenant regulations restrict permanent installations, constrained by limited solar collector surface area.
- Window:Through-wall units combine vapor-compression with photovoltaic thermal recovery in compact form factors. Southeast Asian residential retrofits absorb volume as grid instability drives interest in battery-buffered configurations, though refrigerant charge limits cap efficiency gains.
- Split:Modular indoor-outdoor architectures dominate new installations across East Asian markets. Inverter-driven compressors with variable-speed drives enable coefficient-of-performance ratings that satisfy China's GB seasonal energy efficiency testing protocols.
- Central:Packaged rooftop and chiller systems integrate phase-change material thermal storage for commercial building load shifting. Procurement accelerates in Singapore and Dubai as building automation specifications mandate open-protocol interoperability.
Leading the category by volume: Split. Growing fastest: Central.
Technology:
Cost tier stratification separates premium inverter-smart configurations from economy non-inverter platforms, with margin pools concentrating in control software and predictive maintenance attachments.
- Inverter:Variable-speed compressor modulation reduces energy consumption by matching output to cooling load rather than cycling on-off. Commercial building operators in Southeast Asia specify these systems to avoid utility time-of-use tariff penalties during peak demand periods.
- Non-Inverter:Fixed-speed compressors retain share in price-sensitive residential segments where first-cost considerations override lifecycle operating expense calculations. India's Bureau of Energy Efficiency mandatory labeling program pressures this segment toward obsolescence.
- Smart:Connected control platforms enable predictive maintenance, refrigerant leak detection, and grid-interactive demand response. Software-defined thermal management displaces hardware-centric architectures in California and Germany as EPA AIM Act and EU F-Gas Regulation automate compliance documentation.
- Traditional:Conventional vapor-compression without auxiliary thermal or electrical inputs faces accelerating displacement. Replacement cycles compress as refrigerant phase-down schedules under EPA and EU regulations reduce hydrofluorocarbon availability for servicing.
Highest margin capture: Smart. Steepest volume decline: Traditional.
End User:
Application intensity varies dramatically—residential procurement emphasizes retrofit compatibility and first-cost thresholds, while industrial and institutional buyers prioritize uptime reliability and regulatory compliance documentation.
- Residential:Single-family and multi-family installations favor split configurations with modular thermal collector add-ons. India's star rating program expansion creates regulatory tailwind for inverter-integrated equipment penetration in this segment.
- Commercial:Office buildings, retail, and hospitality drive anticipatory procurement of dual-energy cooling ahead of efficiency mandates. Singapore facility managers specify BACnet-compatible systems to avoid vendor lock-in.
- Industrial:Manufacturing and process cooling applications demand robust compressor architectures with battery buffering for grid instability protection. Heat exchanger material cost volatility in copper-aluminum alloys compresses margins where price elasticity limits pass-through.
- Institutional:Healthcare, education, and government facilities prioritize refrigerant leak detection sensor networks for automated EPA and EU F-Gas compliance. Procurement specifications emphasize technician certification for variable-speed drive commissioning.
Deepest retrofit penetration: Residential. Fastest regulatory-driven replacement: Institutional.
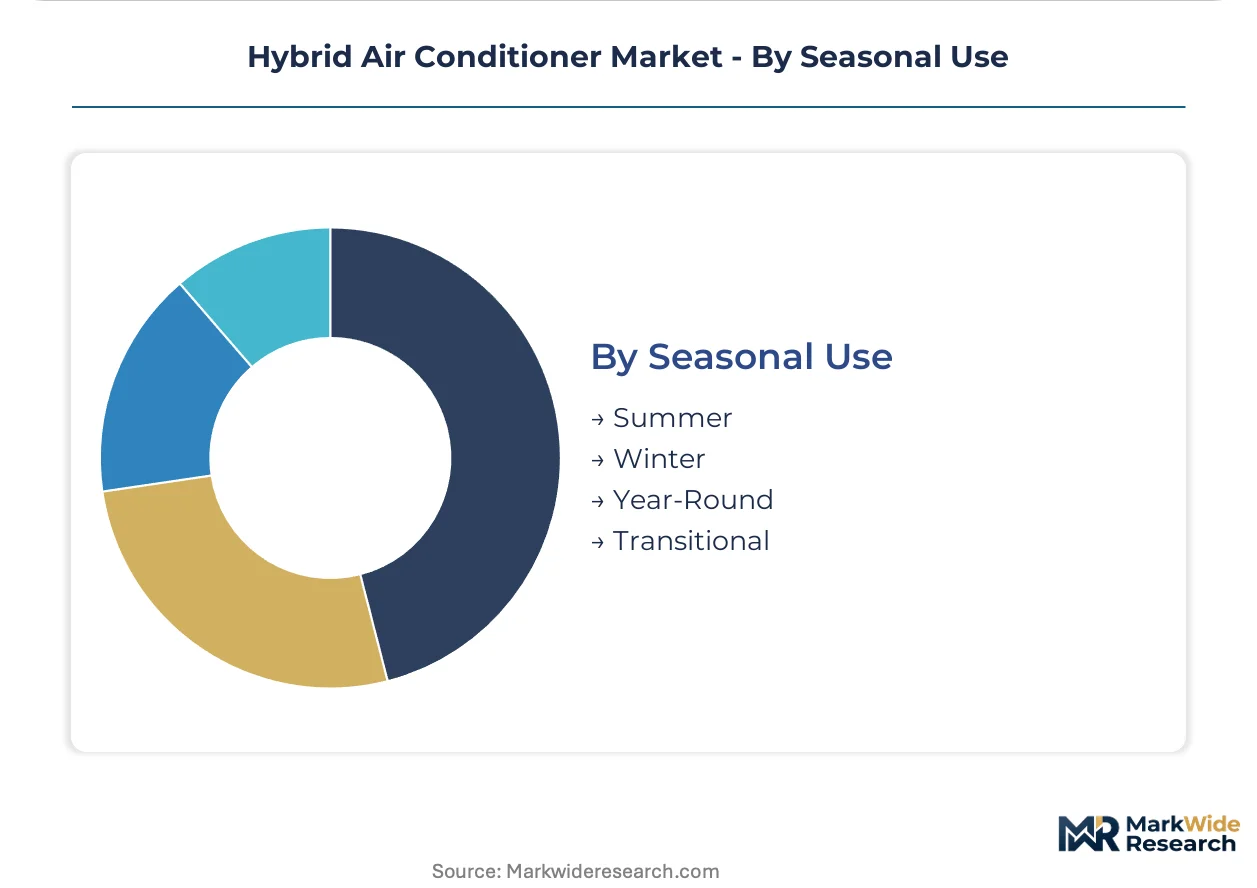
Seasonal Use:
Geography determines utilization patterns—tropical and subtropical zones sustain year-round operation, while temperate markets concentrate demand in summer peaks with emerging winter heat pump conversion.
- Summer:Peak-load cooling configurations dominate Mediterranean and continental European markets. Thermal storage integration enables load shifting away from afternoon grid stress periods.
- Winter:Heat pump operation reverses vapor-compression cycles for space heating. Northeast Asian markets expand addressable equipment utilization as dual-function specifications displace separate heating installations.
- Year-Round:Continuous operation in tropical Southeast Asia and Gulf states maximizes return on solar thermal collector capital investment. Battery buffering systems justify premium pricing through grid independence during cooling peaks.
- Transitional:Spring and autumn shoulder seasons test control algorithm sophistication in modulating between thermal and electrical energy sources. Variable-speed drive calibration expertise scarcity extends commissioning cycles in emerging installation markets.
Widest addressable market: Year-Round. Fastest specification evolution: Transitional.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper-aluminum alloy supply chains cluster in Chinese smelting corridors before dispersing to compressor fabrication hubs worldwide. This metal flow pattern shapes regional manufacturing economics and installation cost structures across cooling equipment markets.
China
GB standards for seasonal energy efficiency ratio testing drive inverter-integrated platform proliferation across residential and commercial segments. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate refrigerant phase-down schedules. Zhuhai and Qingdao host captive semiconductor partnerships stabilizing inverter control module supply for compressor manufacturers.
United States
Commercial building operators in California and Texas deploy predictive maintenance software to automate EPA AIM Act compliance documentation. The Environmental Protection Agency's Section 608 technician certification requirements create installation friction that slows retrofit velocity. Dallas-Fort Worth and Phoenix concentrate demand for phase-change material thermal storage integration in commercial rooftop units.
Germany
Facility managers specify BACnet-compatible building automation systems to avoid vendor lock-in across commercial portfolios. The EU F-Gas Regulation quota system forces migration toward hydrofluoroolefin blends and natural refrigerant alternatives. Bavaria and North Rhine-Westphalia anchor refrigerant leak detection sensor network deployment for automated compliance reporting.
India
The Bureau of Energy Efficiency mandatory star rating program expansion creates regulatory tailwind for inverter-integrated equipment penetration in residential segments. Central Electricity Authority grid stability concerns drive battery-buffered configuration interest among commercial operators. Gujarat and Tamil Nadu manufacturing clusters absorb capital flows for localized assembly capacity.
Japan
Variable-speed drive integration dominates residential split configurations as METI efficiency standards tighten. Heat pump operation for winter heating expands addressable equipment utilization in northeast prefectures. Osaka-Kobe industrial corridors concentrate compressor calibration expertise for variable-speed commissioning.
Hybrid Air Conditioner Market Competitive Landscape
Global majors compete with regional champions across inverter control module supply chains and thermal storage integration capabilities. The vendor base stratifies between captive semiconductor fabricators, refrigerant management specialists, and smart-connected control platform developers. Three archetypes dominate: integrated conglomerates with foundry partnerships, pure-play inverter technology licensors, and building automation system integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers secure alloy supply and software engineering talent.
Among integrated conglomerates, Gree Electric and Mitsubishi Electric exemplify archetypes combining captive component supply with end-product assembly. Daikin Industries occupies a position within the refrigerant management specialist tier. These three anchors illustrate how geographic clustering of semiconductor foundry access and compressor fabrication expertise concentrates competitive advantage in East Asian manufacturing corridors.
| Leading Market Players |
|---|
| Gree Electric |
| Mitsubishi Electric |
| Daikin Industries |
| Rheem Manufacturing |
| LG Electronics |
| Carrier Global |
| Trane Technologies |
| Bosch Thermotechnik |
| Lennox International |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation phase-down schedules gate qualified supply for lower-global-warming-potential refrigerant platforms and premium-tier pricing access for compliant manufacturers. This environmental mandate compresses hydrofluorocarbon availability while elevating certified equipment margins through regulatory scarcity.
Pricing Analysis
Warranty and predictive maintenance service bundling separates premium inverter-smart configurations from unbundled economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EPA Section 608 and EU F-Gas company obligations alongside after-sales software attachment depth. Cost compression in mid-tier equipment intensifies as copper-aluminum alloy volatility limits margin pass-through. Residential retrofit channels exhibit highest price sensitivity while institutional buyers absorbing compliance documentation costs show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with East Asian semiconductor foundry networks for inverter control module fabrication. Manufacturing gravity centers on China for compressor assembly, Japan for variable-speed drive calibration expertise, and South Korea for battery buffering components. Raw material dependencies span copper-aluminum heat exchanger alloys, rare earth elements for permanent magnet motors, and hydrofluoroolefin refrigerant precursors. Tariff exposure on semiconductor inputs constitutes the dominant structural risk. Distribution runs through authorized dealer networks for residential split systems and direct specification channels for commercial central configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA AIM Act refrigerant phase-down schedules erect barrier-to-entry moats for certified incumbents. The regulatory burden advantages players with captive technician training infrastructure and automated compliance documentation capabilities.
For Market Incumbents: Hedge refrigerant platform transition risk by accelerating hydrofluoroolefin blend qualification ahead of EPA quota compression. Secure captive semiconductor foundry partnerships to offset East Asian supply concentration vulnerability. Prioritize backward integration into inverter control module fabrication where variable-speed drive expertise concentrates competitive advantage.
For New Entrants and Emerging Players: Small commercial building operators in India's tier-2 cities represent the most penetrable buyer archetype underserved by incumbent service networks. Target battery-buffered split configurations for grid instability protection where Bureau of Energy Efficiency star rating expansion creates regulatory tailwind. Deploy direct-to-installer digital channels bypassing established distributor relationships.
For Investors and Strategic Acquirers: Phase-change material thermal storage patent filings accelerating beyond historical baselines is the leading indicator that load-shifting capabilities are approaching inflection. Position for long-term viability through manufacturers with integrated software-defined thermal management platforms rather than hardware-centric equipment suppliers. Monitor compressor calibration training program expansion rates as signal for installation market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Partnership | Stabilizes inverter control module supply against East Asian foundry capacity constraints. |
| Predictive Maintenance Platform Launch | Captures recurring revenue through compressor health monitoring under EPA AIM Act documentation requirements. |
| Refrigerant Management Certification Investment | Secures qualified technician pipelines for hydrofluoroolefin blend handling under EU F-Gas Regulation. |
| Phase-Change Material Integration | Enables commercial building load-shifting aligned with utility time-of-use tariff structures. |
| India Localized Assembly Expansion | Positions for Bureau of Energy Efficiency mandatory labeling program growth in residential segments. |
Research Methodology
Multi-period observation of inverter penetration rates, refrigerant platform transitions, and utility tariff restructuring anchored the trend analysis, supplemented by interviews with compressor manufacturing executives, commercial facility managers, HVAC contractor owners, and regulatory compliance officers. Secondary validation drew from EPA AIM Act filings, EU F-Gas Regulation quota tracking, China GB standards documentation, and customs trade data for copper-aluminum alloy flows. Bottom-up equipment shipment modeling triangulated against top-down building stock cooling demand estimates.
Segment-weighting applied product type, technology tier, end-use intensity, and seasonal utilization patterns across the projection horizon. CAGRs derived from slope-consistency checks against historical efficiency mandate adoption curves and refrigerant phase-down compliance timelines. Forecast inputs incorporated solar thermal collector cost trajectories and battery buffering system learning curves specific to Southeast Asian grid instability patterns.
Revisions become necessary when EPA refrigerant quota allocations deviate from scheduled phase-down trajectories or when semiconductor foundry capacity constraints trigger input cost spikes beyond historical volatility bands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Compressor Market
HVAC Equipment
Thermocompressors Market
HVAC Equipment
Japan Commercial HVAC Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
US Commercial Water Heater Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
Global Tubular Heating Elements Market
HVAC Equipment
Industrial Air Blower Market
HVAC Equipment
Commercial Refrigeration Compressor Market