
 Thermometer Market | 2026-2036
Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Thermometer Market Intelligence
The EU MDR is realigning certification requirements for clinical temperature devices sold across European member states. Omron Corporation leverages its Japanese manufacturing base to sustain cost competitiveness in digital thermometer exports. Welch Allyn anchors its position through hospital-grade calibration protocols that differentiate its professional product lines.
A thermometer measures thermal state through thermometric properties such as electrical resistance, infrared radiation emission, or liquid expansion, typically calibrated to ISO 80601 standards for clinical accuracy within ±0.1°C. Its primary purpose spans patient diagnostics, industrial process control, food safety compliance, and environmental monitoring. Digital contact thermometers dominate home healthcare spending due to low unit cost and familiar operation, while non-contact infrared segments capture faster growth in clinical triage and public health screening where speed and hygiene override precision demands. Smart wireless thermometers occupy emerging margin pools through remote patient monitoring integrations, though adoption remains concentrated among early-adopter health systems.
FDA 510(k) premarket notification and EU MDR technical documentation requirements shape product design cycles and market access timelines for thermometer manufacturers. ISO 80601-2-56 compliance for clinical thermometry and IEC 60601-1 electrical safety standards further constrain component sourcing and assembly protocols. Stakeholders must monitor evolving harmonization between FDA and EU MDR testing protocols to avoid redundant certification costs.
Market Dynamics
Hospital infection control mandates are compressing procurement cycles for non-contact infrared thermometers, forcing manufacturers to reconfigure supply chains around FDA 510(k) premarket clearance timelines rather than traditional product refresh schedules.
Growth Catalysts
- EU MDR technical documentation:The Medical Device Regulation's stricter clinical evidence requirements are filtering out marginal competitors, concentrating volume among manufacturers with established notified body relationships.
- Ambulatory care networks:United States outpatient facilities are replacing legacy mercury and glass thermometers with digital contact devices to meet Joint Commission accreditation standards.
- Remote patient monitoring:Bluetooth-enabled smart thermometers are capturing recurring revenue through platform integrations with telehealth providers and chronic disease management programs.
Market Restraints
- Semiconductor input volatility:Infrared sensor arrays and precision analog-to-digital converters face allocation constraints from automotive and consumer electronics demand, compressing gross margins on mid-tier clinical units.
- Calibration infrastructure concentration:ISO 17025-accredited temperature calibration laboratories cluster in Germany, Japan, and the United States, creating logistics bottlenecks for manufacturers in emerging production bases.
- Mercury thermometer substitution limits:WHO phase-out commitments for mercury-containing devices face implementation gaps in low-resource health systems where disposal infrastructure remains undeveloped.
Strategic Opportunities
- Home healthcare underpenetration:India's expanding Ayushman Bharat health insurance scheme creates first-time thermometer ownership demand among households previously relying on tactile fever assessment.
- Wearable temperature monitoring:Continuous skin temperature sensors are converging with sleep and fertility tracking applications, opening direct-to-consumer channels outside traditional medical device distribution.
- FDA breakthrough device designation:Novel core body temperature algorithms for wearable patches qualify for expedited review, compressing time-to-market for algorithm-centric entrants.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for probe covers and ear canal tips extend product development cycles by 8-14 months.
- Legacy health record integration:Smart thermometer APIs require HL7 FHIR compliance investments that strain engineering resources at sub-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermometer Market |
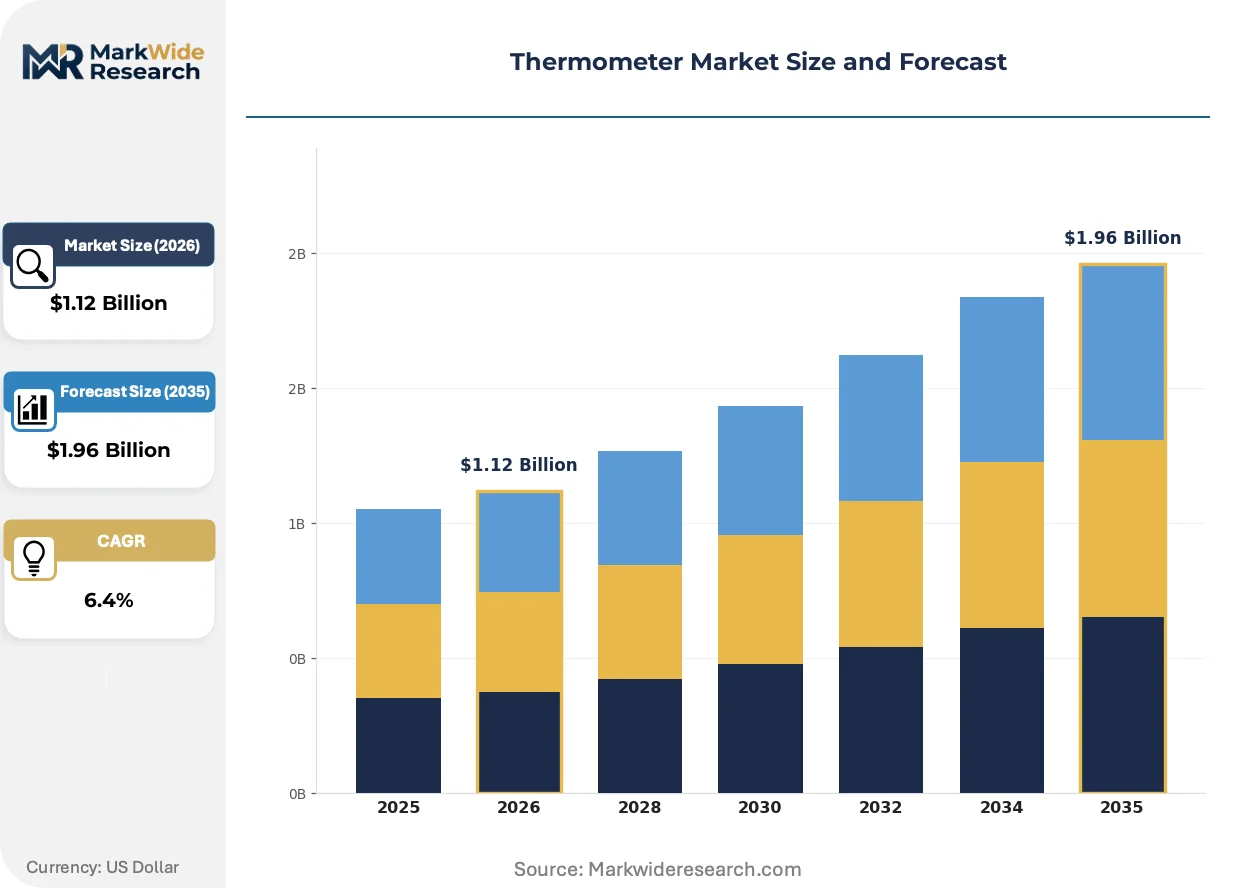
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $1.96 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Infrared, Mercury, Bimetallic End User: Healthcare Facilities, Home Users, Laboratories, Industrial Technology: Contact, Non-contact, Smart, Wireless Application: Clinical, Environmental, Food Safety, Research |
| Companies Covered | Omron Corporation, Terumo Corporation, Microlife Corporation, Braun, Welch Allyn, A&D Company, Exergen Corporation, American Diagnostic Corporation, Geratherm Medical AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermometer Market Strategic Shifts & Innovations
Multi-sensor fusion architectures are replacing single-modality temperature measurement, enabling simultaneous core body and ambient thermal tracking that supports clinical decision algorithms rather than isolated readings.
Sensor fusion platforms integrating thermopile arrays with accelerometers and galvanic skin response electrodes are unifying temperature monitoring with activity and stress biomarkers. Chronic disease management programs at United States accountable care organizations are piloting these composite devices for heart failure exacerbation prediction. The convergence is compressing the addressable market for standalone thermometers while expanding total platform value per patient.
EU MDR Article 10 post-market surveillance requirements are mandating systematic vigilance data collection across distributed device fleets. Manufacturers must now embed unique device identification and automated adverse event reporting capabilities into firmware architectures. Professional clinical segments face the steepest compliance cost increases, accelerating consolidation among notified body clients.
Hospital procurement committees are unbundling temperature monitoring from bundled capital equipment contracts, creating standalone purchasing authority for infection control departments. Group purchasing organizations are losing leverage as individual facilities negotiate directly with infrared thermometer specialists. This pattern is most pronounced in United States academic medical centers with dedicated biosafety committees.
Thermometer Market Segmentation
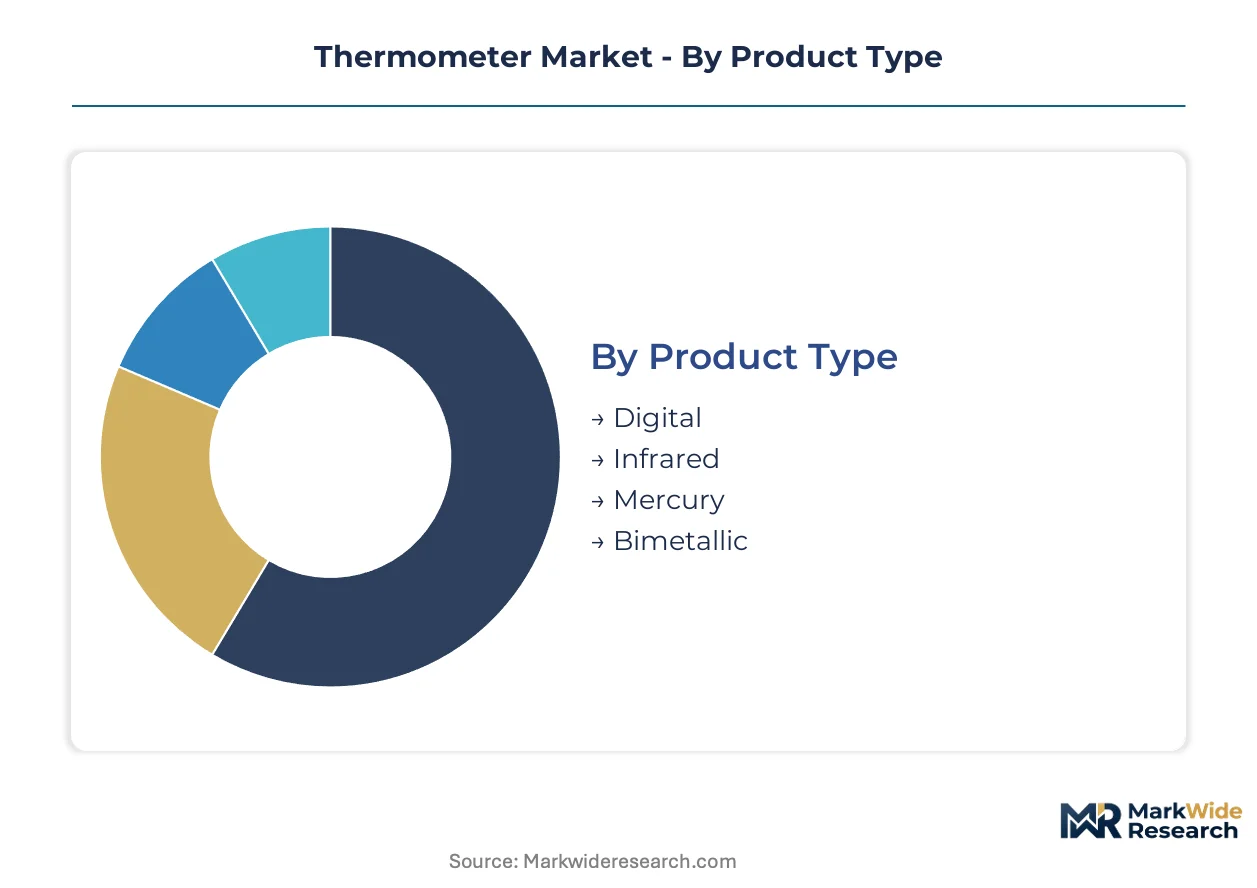
Thermometer segmentation reveals divergent margin structures across contact versus non-contact modalities. Product type and technology choices determine regulatory pathway complexity and end-user pricing power.
Product Type:
Customization intensity varies sharply across this category, from commodity digital units to precision-calibrated infrared systems requiring FDA 510(k) clearance.
- Digital:Thermistors or thermocouples convert temperature into electrical signals with ±0.1°C accuracy per ISO 80601-2-56. United States ambulatory care networks are replacing mercury inventories with these devices to satisfy Joint Commission accreditation standards.
- Infrared:Thermopile sensors detect infrared radiation emitted by surfaces, enabling sub-second readings without physical contact. Hospital infection control departments in Germany and Japan are accelerating procurement of FDA-cleared and PMDA-approved units for triage protocols.
- Mercury:Glass-enclosed liquid expansion devices face WHO-coordinated phase-out commitments.
- Bimetallic:Two bonded metals with differential expansion coefficients drive dial indicators for industrial process monitoring.
Leading the category by volume: Digital. Expanding most quickly: Infrared.
End User:
Customer sophistication determines whether procurement prioritizes unit cost or total cost of ownership including calibration and integration.
- Healthcare Facilities:Hospitals and clinics demand traceable calibration chains to ISO 17025 standards and HL7 FHIR connectivity for electronic health record integration. United States academic medical centers with dedicated biosafety committees are unbundling temperature monitoring from capital equipment contracts.
- Home Users:Retail channels favor sub-$25 digital contact devices with intuitive operation and battery longevity. India's Ayushman Bharat health insurance expansion is creating first-time ownership demand among households previously relying on tactile fever assessment.
- Laboratories:ISO 17025-accredited calibration requirements constrain supplier qualification.
- Industrial:Process control applications prioritize durability and wide measurement ranges over clinical precision.
Dominating procurement value: Healthcare Facilities. Gaining share fastest: Home Users in emerging insurance markets.
Technology:
Integration depth separates commodity hardware from platform-enabled recurring revenue models.
- Contact:Probe-based measurement requires physical placement at oral, axillary, or rectal sites. Digital contact thermometers sustain manufacturing concentration in Japan and China due to established thermistor supply chains.
- Non-contact:Infrared and thermal imaging modalities eliminate cross-contamination risk. FDA 510(k) premarket notification timelines are reshaping product development cycles for clinical entrants.
- Smart:Bluetooth-enabled devices with onboard memory and algorithmic fever detection. United States accountable care organizations are piloting these for heart failure exacerbation prediction.
- Wireless:Continuous data transmission to cloud platforms enables remote patient monitoring subscriptions.
Highest shipment volumes: Contact. Steepest expansion trajectory: Smart.
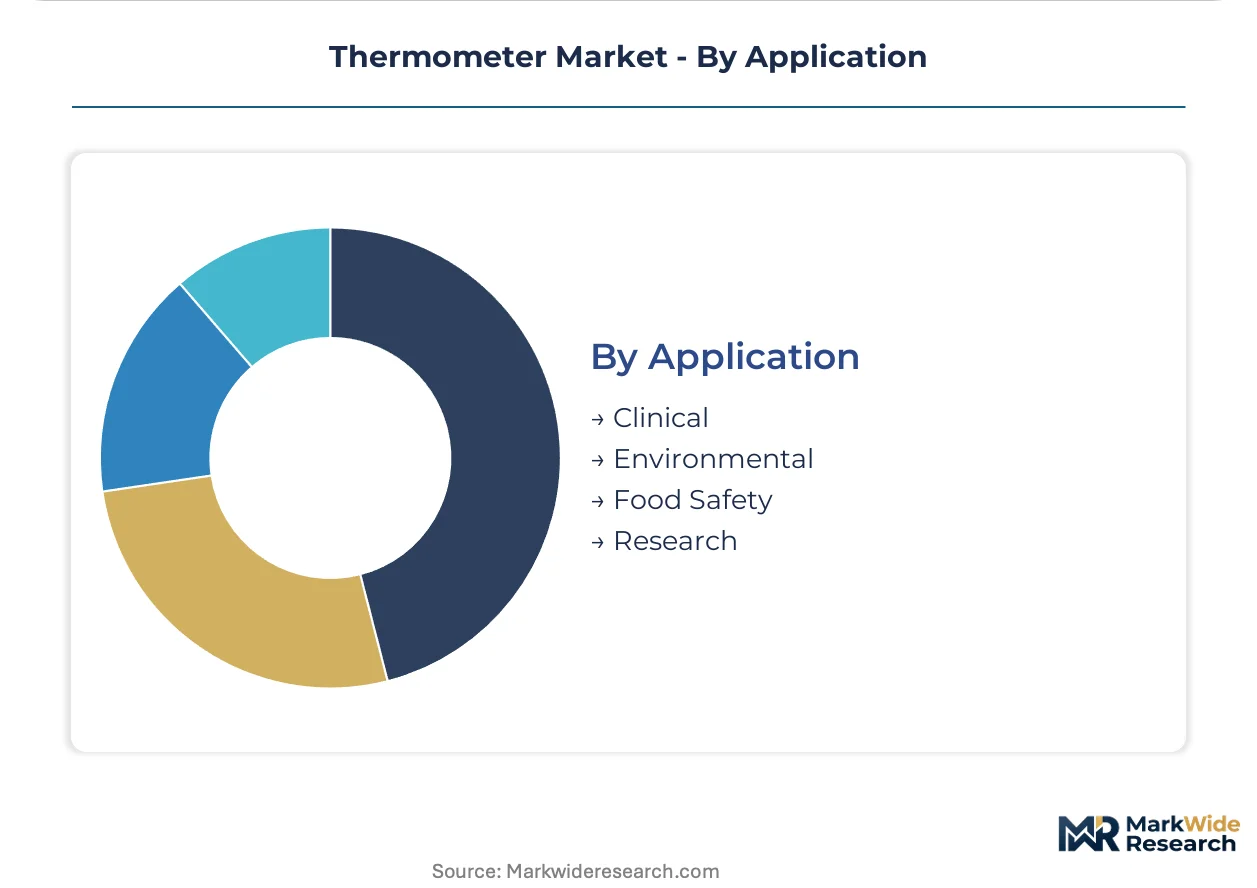
Application:
Regulatory jurisdiction and accuracy requirements fragment this category across medical, industrial, and consumer frameworks.
- Clinical:Patient diagnostics demand ±0.1°C accuracy and biocompatibility testing per ISO 10993 for probe covers. EU MDR Article 10 post-market surveillance requirements are mandating unique device identification and automated adverse event reporting in firmware.
- Environmental:Weather stations and climate monitoring networks prioritize long-term stability over rapid response. German and Japanese calibration laboratories anchor certification infrastructure for precision environmental sensors.
- Food Safety:HACCP compliance drives demand for rapid-response probe thermometers in commercial kitchens.
- Research:Scientific applications require traceable uncertainty budgets and NIST- or NMIJ-equivalent calibration certificates.
Commanding premium pricing: Clinical. Climbing the fastest: Environmental monitoring networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors infrared thermometer manufacturing through its dense electronics supply chain, while regulatory divergence across major economies fragments certification pathways and shapes regional competitive dynamics.
United States
Ambulatory care networks in Texas and Florida are replacing mercury inventories with digital contact devices to satisfy Joint Commission accreditation standards. FDA 510(k) premarket notification timelines compress product development cycles for clinical entrants. Boston's medical device corridor concentrates engineering talent for smart thermometer platform development.
Germany
Hospital infection control departments in Bavaria and North Rhine-Westphalia accelerate procurement of EU MDR-compliant infrared units for triage protocols. The Medical Device Regulation's stricter clinical evidence requirements filter out marginal competitors. ISO 17025-accredited calibration laboratories cluster around Stuttgart, creating certification infrastructure bottlenecks.
Japan
PMDA-approved non-contact devices capture procurement share in Tokyo and Osaka metropolitan hospital systems. METI standards for home healthcare equipment shape domestic product specifications. Kyoto-Osaka-Kobe manufacturing belt sustains cost competitiveness in digital thermometer exports through established thermistor supply chains.
India
Ayushman Bharat health insurance expansion creates first-time thermometer ownership demand in Maharashtra and Gujarat households previously relying on tactile fever assessment. CDSCO medical device registration requirements are tightening for imported clinical units. Bengaluru's health-tech startup ecosystem pilots Bluetooth-enabled remote patient monitoring integrations.
China
NMPA Class II medical device approvals govern clinical thermometer market access for domestic and imported products. Yangtze River Delta manufacturing bases around Shanghai supply infrared sensor arrays to global OEMs. Shenzhen's electronics corridor dominates contract manufacturing for smart wireless thermometer platforms.
Thermometer Market Key Industry Players
The competitive structure tilts toward diversified healthcare conglomerates with established regulatory affairs capabilities. Tier-one positions concentrate among Japanese and German manufacturers with deep notified body relationships and ISO 80601 calibration protocols. Three archetypes dominate: precision-calibrated clinical specialists, high-volume consumer electronics integrators, and algorithm-centric smart health platform builders. Consolidation pressure intensifies through M&A targeting calibration infrastructure and strategic partnerships for HL7 FHIR health record integration.
Within the diversified healthcare conglomerate tier, Omron Corporation and Terumo Corporation represent established regulatory navigation capabilities. Welch Allyn exemplifies the precision-calibrated clinical specialist archetype through hospital-grade differentiation. Exergen Corporation occupies a position among infrared technology specialists with FDA clearance experience.
| Leading Market Players |
|---|
| Omron Corporation |
| Terumo Corporation |
| Microlife Corporation |
| Braun |
| Welch Allyn |
| A&D Company |
| Exergen Corporation |
| American Diagnostic Corporation |
| Geratherm Medical AG |
| Others |
Cost & Logistics Intelligence
ISO 80601-2-56 certification tiering separates hospital-grade precision units from retail commodity devices, creating divergent margin pools that map directly onto supply chain configurations. Premium clinical thermometers command pricing power through FDA 510(k) clearance and traceable calibration chains to ISO 17025 laboratories, while home-use digital units compete on thermistor sourcing efficiency from Japanese and Chinese manufacturing clusters.
Pricing Analysis
Value-based pricing anchored to infection control outcomes dominates hospital procurement, with non-contact infrared devices capturing premium positioning through sub-second triage throughput and zero cross-contamination risk. Price differentiation rests on FDA clearance tier and ISO 17025 calibration pedigree for clinical units versus battery longevity and display clarity for retail segments. Pricing pressure stems from semiconductor allocation constraints on infrared sensor arrays, compressing gross margins on mid-tier clinical units. Home users in emerging insurance markets exhibit highest price sensitivity, while United States academic medical centers with dedicated biosafety committees prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Reverse-logistics flows for calibration recertification and probe cover replenishment create recurring revenue attachments that sustain distributor relationships beyond initial hardware sales. Manufacturing concentrates in China for infrared sensor array production, Japan for precision thermistor fabrication, and Germany for ISO 17025-accredited calibration infrastructure. Raw material dependencies include thermopile sensors, lithium coin cells, and medical-grade plastics for probe covers. Supply chain risk centers on single-source vulnerability for ISO 17025-accredited temperature calibration laboratories clustering in Stuttgart, Tokyo, and Chicago. Distribution runs through group purchasing organizations for healthcare facilities and retail pharmacy chains for home users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration infrastructure scarcity props pricing for ISO 17025-certified devices, as laboratory concentration in Germany, Japan, and the United States creates capacity bottlenecks that limit supply expansion.
For Market Incumbents: Lock in notified body relationships under EU MDR Article 10 requirements before clinical evidence thresholds escalate further, and secure backward integration into thermopile sensor sourcing to offset semiconductor allocation volatility from automotive demand. Defend hospital-grade positioning by embedding HL7 FHIR connectivity ahead of electronic health record integration mandates. For New Entrants and Emerging Players: Begin with algorithm-centric wearable patches qualifying for FDA breakthrough device designation, where expedited review compresses time-to-market against established calibration-dependent competitors. Target India's Ayushman Bharat expansion corridors with Bluetooth-enabled devices priced for first-time ownership demand. Pursue direct-to-consumer fertility and sleep tracking applications outside traditional medical device distribution. For Investors and Strategic Acquirers: Re-rating potential sits with calibration infrastructure owners given EU MDR post-market surveillance mandates and ISO 17025 laboratory scarcity. Long-term viability favors manufacturers with diversified regulatory approvals across FDA, PMDA, and NMPA jurisdictions. Watch for CDSCO registration tightening in India as signal for import substitution opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates hospital procurement cycles by satisfying Joint Commission infection control mandates. |
| EU MDR Notified Body Relationship | Filters marginal competitors through stricter clinical evidence and post-market surveillance requirements. |
| Hospital System Partnership | Unbundles temperature monitoring from capital equipment contracts for standalone purchasing authority. |
| Software Companion Development | Enables remote patient monitoring subscriptions through Bluetooth-enabled platform integrations. |
| Reimbursement Strategy | Positions smart thermometers for chronic disease management program adoption at accountable care organizations. |
Research Approach
Independent corroboration across hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads underwrites the qualitative findings. Primary interviews with infection control officers and calibration laboratory directors combined with secondary validation from FDA 510(k) filings, PMDA approval databases, hospital procurement contracts, and EU MDR notified body registers anchor the analysis. Bottom-up shipment estimates by product type and technology triangulate against top-down healthcare infrastructure spending patterns.
Comparable-period anchoring to historical FDA clearance timelines and EU MDR transition phases shapes the forecast window across the analysis window. Segmentation dimensions modeled include contact versus non-contact modality, clinical versus home-use application, and smart versus conventional technology tiers. CAGRs derive from hospital infection control mandate adoption curves and insurance expansion trajectories in emerging markets. Infrared sensor array supply constraints and calibration laboratory capacity limits inform industry-specific forecast inputs.
Underlying measurement precision varies by segment; clinical and laboratory applications carry tighter precision than home-use and industrial categories. Forecasts reflect assumptions about regulatory harmonization progress and semiconductor allocation normalization. Practitioners should monitor EU MDR notified body capacity expansion and CDSCO import registration enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
Microsensor Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Global Digital Electronic Thermometers Market
Sensors and Controls
Gyro Sensors Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
Aeroderivative Sensor Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
Taiwan Sensors Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
MEMS for Mobile Devices Market