
 Smart Temperature Management Market | 2026-2036
Smart Temperature Management Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Temperature Management Market Outlook
Modular sensor-controller bundles is recalibrating how commercial buyers configure smart temperature systems, shifting procurement from discrete components to integrated platforms. Honeywell International Inc. leverages its building automation portfolio to anchor premium positions in connected HVAC ecosystems. Schneider Electric SE sustains technology leadership through edge-computing controllers that reduce latency for industrial clients. Siemens AG competes on manufacturing scale, supplying precision sensors to automotive and pharmaceutical cleanroom applications across European and Asian production hubs.
Smart temperature management encompasses networked hardware and software systems that monitor, regulate, and optimize thermal conditions through IoT-enabled sensors, programmable controllers, and cloud-based analytics platforms operating across sub-zero to 300°C ranges. These systems serve primary industrial and commercial purposes including energy efficiency compliance, product quality preservation, and equipment failure prevention in climate-sensitive operations. The application dimension shows HVAC commanding the largest installed base while healthcare emerges as the fastest-expanding segment driven by biologics storage regulations and hospital digitization mandates. Technology segmentation reveals Wi-Fi dominating residential and light commercial deployments, whereas Zigbee and Thread gain traction in industrial settings where mesh-network reliability and low-power requirements outweigh bandwidth demands.
The US EPA SNAP program and the EU F-Gas Regulation are reshaping refrigerant-phaseout timelines, forcing equipment manufacturers to redesign sensor-calibration protocols and controller algorithms for alternative chemistries. FDA 21 CFR Part 11 compliance requirements in pharmaceutical cold chain applications are elevating software-validation standards and audit-trail capabilities as table-stakes for healthcare market access. Stakeholders must monitor divergence between regional refrigerant-transition schedules and emerging cybersecurity certification frameworks for IoT-enabled thermal infrastructure.
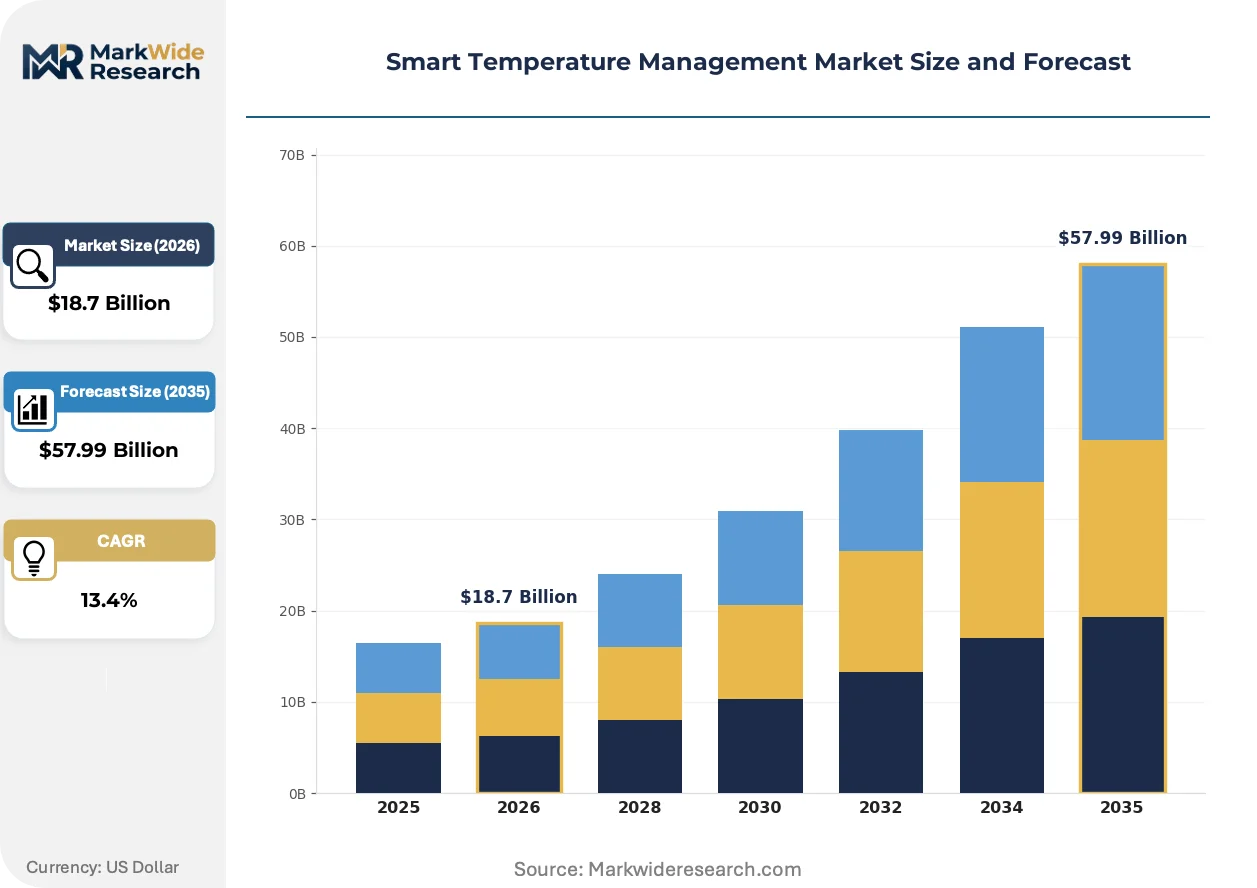
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant-phaseout timelines, forcing equipment manufacturers to redesign sensor-calibration protocols and controller algorithms for alternative chemistries across European industrial clusters.
Growth Catalysts
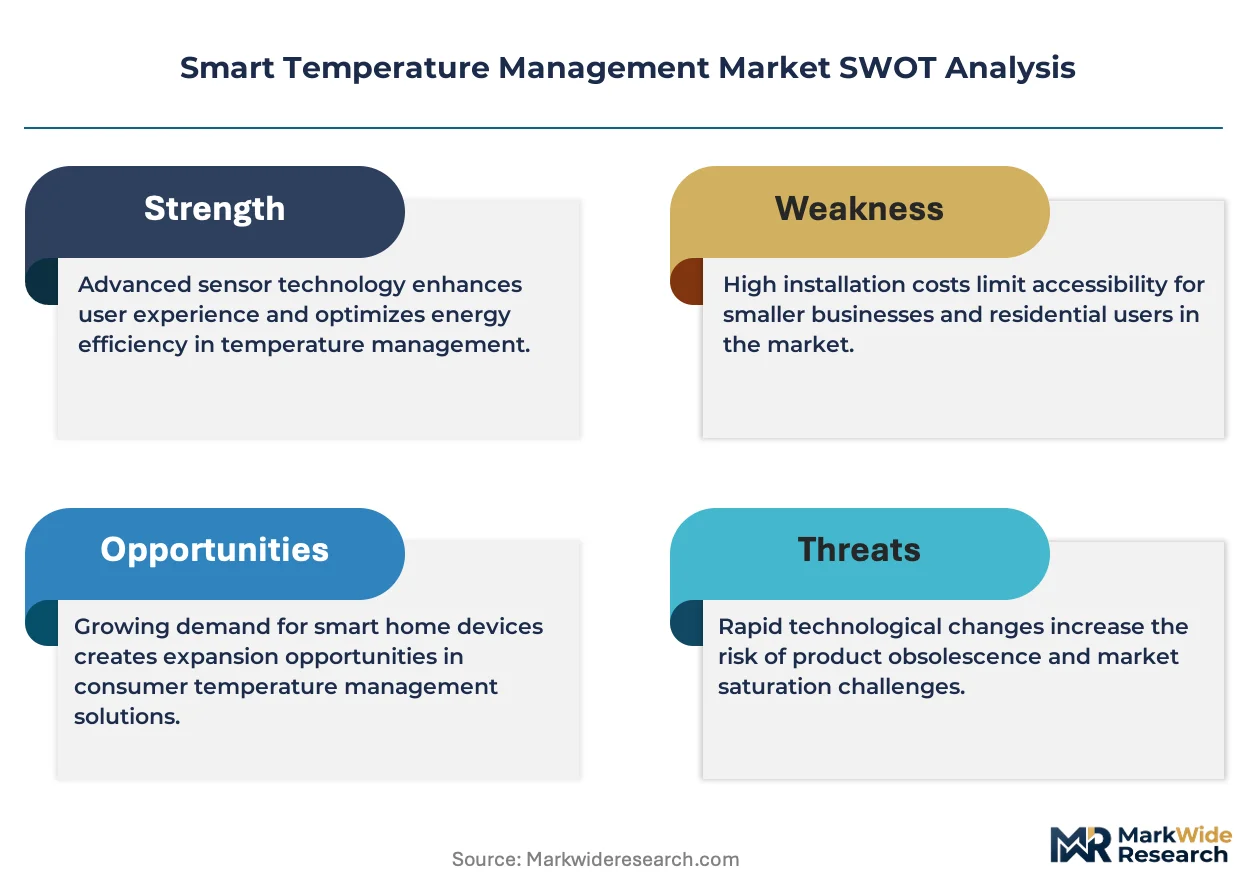
- Pharmaceutical cold chain mandates:FDA 21 CFR Part 11 compliance requirements elevate software-validation standards and audit-trail capabilities as table-stakes for healthcare market access.
- Building efficiency codes:Germany's stringent commercial real estate regulations drive sensor deployment across manufacturing facilities and office complexes.
- Biologics storage expansion:Healthcare facilities accelerate adoption of connected temperature monitoring as biologics pipelines expand and storage regulations tighten.
Market Restraints
- Sensor component concentration:Precision MEMS manufacturing concentrates in East Asian foundries, creating supply vulnerability for European and North American system integrators.
- Refrigerant chemistry transition costs:Low-global-warming-potential alternatives require complete recalibration of existing controller algorithms and hardware retrofits.
- Mesh network interoperability gaps:Zigbee and Thread protocol fragmentation complicates multi-vendor deployments in industrial settings.
Strategic Opportunities
- Edge-computing convergence:Integration of local processing with cloud analytics reduces latency for automotive cleanroom applications.
- Healthcare digitization tailwinds:Hospital digitization mandates in Germany and France expand addressable market for integrated monitoring platforms.
- Industrial automation clusters:Germany's manufacturing density creates concentrated demand for precision thermal management in pharmaceutical and automotive production.
Industry Challenges
- Cybersecurity certification complexity:Emerging IoT security frameworks for thermal infrastructure create compliance timeline uncertainty for system vendors.
- Legacy HVAC integration friction:Brownfield commercial buildings require costly gateway hardware to connect existing equipment to networked monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Temperature Management Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostats, Sensors, Controllers, Software Application: HVAC, Industrial Automation, Food Storage, Healthcare Technology: Wi-Fi, Zigbee, Bluetooth, Thread End User: Residential, Commercial, Industrial, Agricultural |
| Companies Covered | Honeywell International Inc., Schneider Electric SE, Johnson Controls International, Siemens AG, Emerson Electric Co., Trane Technologies, Daikin Industries, Carrier Global, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Temperature Management Market Strategic Shifts
Sensor-controller integration is compressing procurement cycles and reshaping competitive differentiation around platform completeness rather than component performance.
Edge-computing thermal controllers is unifying local processing with cloud analytics. Pharmaceutical manufacturers adopt these systems aggressively to meet FDA audit-trail requirements. This convergence is unifying hardware and software procurement decisions into single-vendor platform selections.
The EU F-Gas Regulation accelerates refrigerant chemistry transitions across European industrial refrigeration. Equipment manufacturers redesign sensor-calibration protocols for low-global-warming-potential alternatives. HVAC and cold chain segments in Germany and France face compressed retrofit timelines.
Platform-based procurement is displacing discrete component purchasing in commercial real estate. Facility managers now specify integrated sensor-controller bundles rather than sourcing sensors and controllers separately. This shift concentrates purchasing power with building automation specialists in German industrial clusters.
Smart Temperature Management Market Segmentation
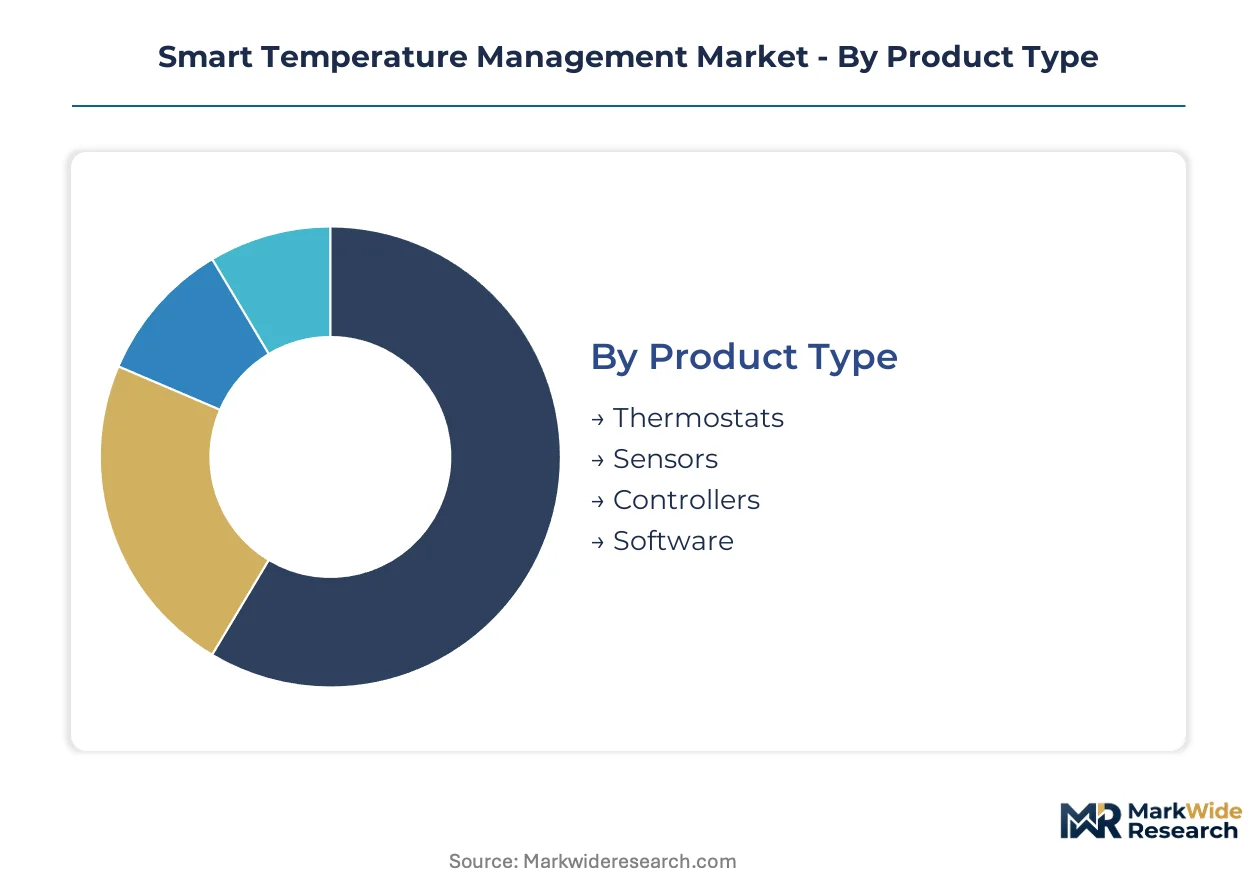
Smart temperature management systems fragment across hardware, software, and connectivity layers. Each segment carries distinct procurement logic, installation complexity, and regulatory exposure that shapes vendor strategy and buyer decision-making.
Product Type:
Buyers in this category differentiate by integration depth versus component flexibility.
- Thermostats:Wall-mounted control interfaces with programmable scheduling and occupancy sensing. Demand concentrates in German commercial real estate retrofits where building efficiency codes mandate automated climate control.
- Sensors:Precision MEMS devices measuring ambient, surface, and fluid temperatures across -40°C to 300°C ranges. Pharmaceutical cleanroom applications in Stuttgart and Munich drive specification for FDA-validated calibration protocols.
- Controllers:Edge-computing units executing local logic with cloud connectivity.
- Software:Cloud analytics platforms with audit-trail generation and predictive maintenance algorithms.
Volume sits with Sensors; growth tilts toward Software.
Application:
Regulatory intensity separates buyers by compliance burden and validation requirements.
- HVAC:Building climate systems spanning residential heat pumps to commercial district cooling. Germany's Energieeinsparverordnung (EnEV) revisions accelerate sensor deployment in Frankfurt and Hamburg office towers.
- Healthcare:Biologics storage, blood bank monitoring, and surgical suite climate control. FDA 21 CFR Part 11 mandates elevate software-validation standards as table-stakes for hospital procurement committees.
- Industrial Automation:Process thermal management in automotive paint lines and semiconductor fabrication.
- Food Storage:Cold chain monitoring from farm to retail with HACCP documentation.
Revenue concentrates in HVAC; steepest expansion trajectory belongs to Healthcare.
Technology:
Network topology choices hinge on latency tolerance, power constraints, and mesh reliability needs.
- Wi-Fi:High-bandwidth protocol dominating residential and light commercial deployments. French apartment retrofits and Italian hospitality installations favor existing infrastructure reuse.
- Zigbee:Low-power mesh standard with proven industrial track record. German automotive plants in Wolfsburg and Ingolstadt specify Zigbee for its deterministic latency in cleanroom applications.
- Bluetooth:Short-range protocol for mobile-configured point solutions.
- Thread:IP-native mesh architecture gaining traction in multi-vendor industrial settings.
Installed base favors Wi-Fi; protocol momentum shifts toward Thread.
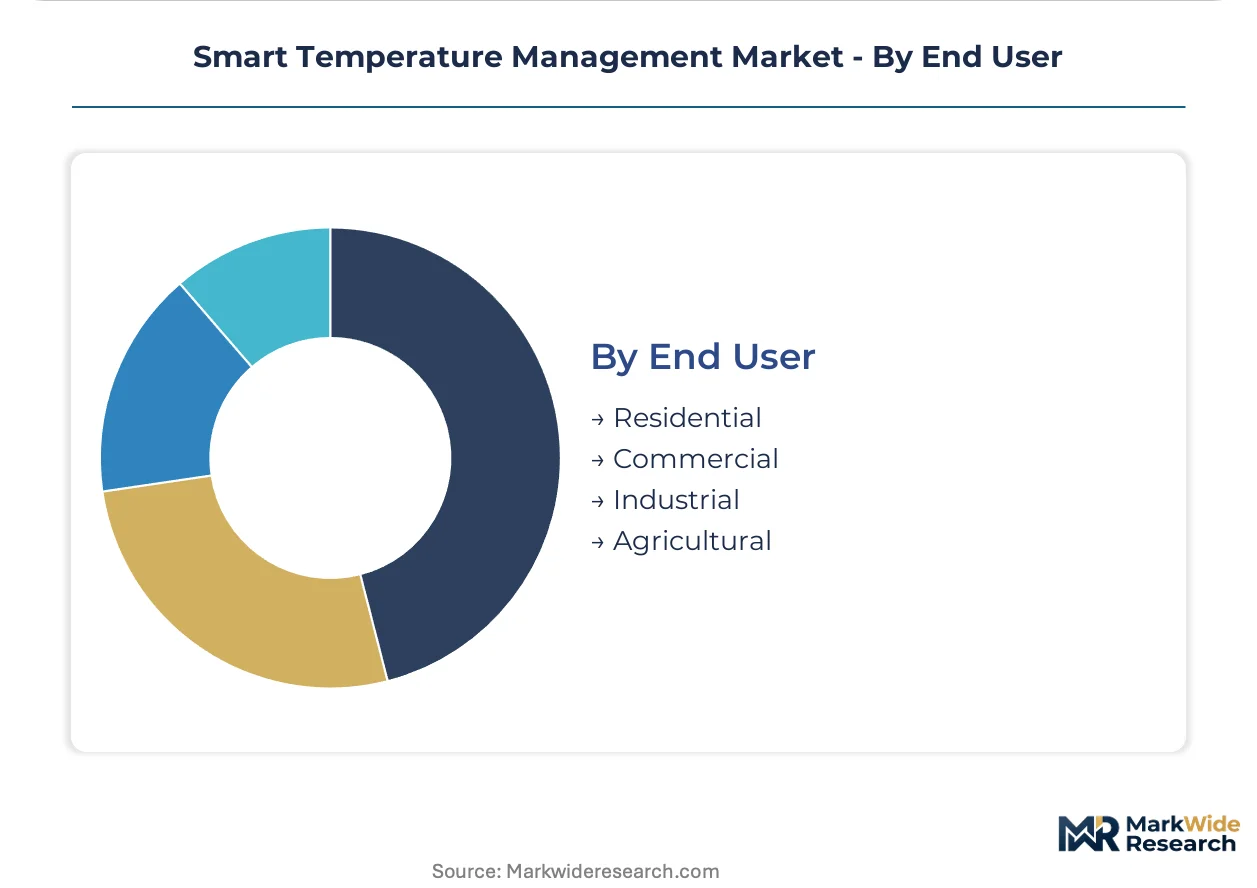
End User:
Scale economics and technical sophistication create distinct purchasing patterns across buyer types.
- Commercial:Office complexes, retail chains, and hospitality groups procuring integrated building automation. Berlin and Cologne property managers now specify sensor-controller bundles rather than discrete components.
- Industrial:Manufacturing facilities with process-critical thermal requirements. Pharmaceutical production in Basel and automotive assembly in Munich demand precision calibration and redundant sensing architectures.
- Residential:Single-family and multi-unit dwellings with app-controlled climate systems.
- Agricultural:Greenhouse and livestock operations with basic threshold alerting.
Spending concentrates in Commercial; fastest share gains accrue to Industrial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian precision MEMS foundries while consumption tilts toward German industrial clusters and US pharmaceutical corridors. This geographic split shapes procurement patterns and regulatory exposure across the value chain.
United States
Pharmaceutical cold chain expansion and hospital digitization mandates drive sensor deployment across Boston and New Jersey biotech corridors. FDA 21 CFR Part 11 compliance requirements elevate software-validation standards for healthcare market access. Chicago and Houston facility managers specify integrated sensor-controller bundles for commercial retrofits.
Germany
Industrial automation density and stringent building efficiency codes concentrate demand in Stuttgart automotive plants and Munich pharmaceutical cleanrooms. EU F-Gas Regulation accelerates refrigerant-phaseout timelines, forcing equipment recalibration for low-global-warming-potential alternatives. Frankfurt and Hamburg office towers deploy networked HVAC sensors to meet Energieeinsparverordnung revisions.
China
Semiconductor fabrication expansion and data center construction propel precision thermal management procurement in Shanghai and Shenzhen. National dual carbon goals pressure industrial facilities to retrofit legacy refrigeration systems with connected monitoring platforms. Beijing and Hangzhou pharmaceutical manufacturers adopt FDA-aligned validation protocols for export compliance.
Japan
Automotive electronics miniaturization and semiconductor packaging drive demand for sub-zero process control in Nagoya and Kyoto industrial zones. METI efficiency standards mandate connected monitoring in commercial buildings and manufacturing facilities. Osaka and Yokohama facility operators prioritize mesh-network reliability for cleanroom applications.
France
Hospital digitization mandates and biologics storage regulations expand healthcare segment demand in Paris and Lyon metropolitan areas. ANSM pharmaceutical oversight aligns with EU cold chain standards, elevating audit-trail requirements for temperature monitoring systems. Marseille and Lille commercial property managers specify Wi-Fi-enabled retrofits leveraging existing infrastructure.
Smart Temperature Management Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and integration layers. The vendor base stratifies into three tiers: building automation incumbents with cross-portfolio leverage, industrial sensor specialists with calibration expertise, and software-centric platforms with analytics differentiation. Consolidation pressure intensifies as procurement shifts toward bundled platforms. Dominant competitive moves include strategic partnerships for edge-computing integration and geographic expansion into German industrial clusters.
Within the diversified conglomerate tier, Honeywell International Inc. and Siemens AG occupy positions anchored by building automation breadth and manufacturing scale respectively. Schneider Electric SE exemplifies the edge-computing convergence archetype, sitting within the specialist tier that bridges hardware controllers with cloud analytics platforms. These three entities represent distinct strategic postures: portfolio-led platform bundling, precision manufacturing scale, and latency-optimized industrial solutions.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Schneider Electric SE |
| Johnson Controls International |
| Siemens AG |
| Emerson Electric Co. |
| Trane Technologies |
| Daikin Industries |
| Carrier Global |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
Precision MEMS engineering talent concentrates in Taiwan and South Korea, where labor-cost differentials between semiconductor-grade cleanroom technicians and standard electronics assemblers drive 40-60 point spreads between premium sensor-controller bundles and economy thermostat-only configurations.
Pricing Analysis
Margin tightening in mid-tier sensor-controller bundles reflects Zigbee and Thread protocol fragmentation forcing vendors to absorb integration engineering costs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from commercial HVAC retrofits and basic residential thermostats. Price differentiation hinges on calibration certification grade and after-sales service bundling. Industrial buyers in Stuttgart and Munich show lowest price sensitivity given process-critical thermal requirements, while French apartment retrofitters demand Wi-Fi solutions leveraging existing infrastructure to minimize hardware spend.
Supply Chain Analysis
Precision MEMS sensor supply rests on Taiwanese and South Korean foundries with secondary concentration in Japanese specialty ceramic substrate producers. Raw material dependencies include silicon wafers, platinum thin-film elements, and fluoropolymer encapsulants. Single-source vulnerability concentrates in EUV-grade cleanroom equipment required for sub-micron feature patterning. Distribution runs through German industrial distributors for European automation clusters and direct OEM relationships for pharmaceutical cleanroom integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart temperature management sits in a refrigerant-chemistry transition phase as low-global-warming-potential alternatives displace legacy hydrofluorocarbon systems across European industrial refrigeration.
For Market Incumbents: To counter edge-computing latency advantages from Schneider Electric SE and Schneider Electric SE, Honeywell International Inc. and Siemens AG should deepen backward integration into precision MEMS manufacturing through captive supply arrangements with Taiwanese foundries, while accelerating FDA 21 CFR Part 11 software-validation certification investment to defend healthcare segment positions against analytics-native entrants. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and France opens a window for refrigerant-transition retrofit specialists targeting compressed timeline mandates in Frankfurt and Hamburg commercial real estate. White-space exists in Thread-native industrial mesh networks for multi-vendor pharmaceutical cleanrooms and edge-computing controllers for automotive paint line applications. Go-to-market should anchor on hospital digitization mandates in Berlin and Paris with SaaS audit-trail platforms. For Investors and Strategic Acquirers: Re-rating potential sits with edge-computing controller specialists given healthcare digitization tailwinds and pharmaceutical cold chain expansion. Long-term viability favors vendors with simultaneous calibration expertise and cloud analytics capabilities. Watch FDA enforcement intensity on 21 CFR Part 11 software validation as inflection indicator for healthcare segment margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Controller Development | Reduces latency for Stuttgart automotive cleanroom applications below 50 milliseconds. |
| FDA 21 CFR Part 11 Software Validation | Unlocks hospital procurement committee access in Boston and New Jersey biotech corridors. |
| Refrigerant Chemistry Calibration Recertification | Enables EU F-Gas Regulation compliance for low-global-warming-potential alternatives in Munich. |
| Thread Protocol Stack Integration | Resolves multi-vendor interoperability gaps in Wolfsburg automotive mesh deployments. |
| Precision MEMS Foundry Partnership | Secures sensor supply continuity against East Asian concentration risk for European integrators. |
Study Parameters
Document review covered SEC 10-K filings from building automation conglomerates, EU F-Gas Regulation implementation guidance, and FDA 21 CFR Part 11 compliance documentation, complemented by interviews with facility managers at Frankfurt office towers, pharmaceutical cleanroom engineers in Stuttgart, and HVAC procurement leads at German automotive plants. Secondary validation drew from customs trade data for MEMS sensor imports, EnEV building code revision drafts, and Zigbee Alliance interoperability certifications. Bottom-up sensor shipment estimates triangulated against top-down building automation equipment spend.
Historical volume trends cross-referenced against expert panel input from edge-computing controller engineers and pharmaceutical validation specialists. Segmentation dimensions modeled include product type integration depth, application regulatory intensity, technology protocol topology, and end-user scale economics across the analysis window. CAGRs derived from fitted growth curves applied to hardware replacement cycles and software subscription renewal rates, with specific inputs from refrigerant-phaseout timeline acceleration and hospital digitization mandate schedules.
The model assumes a particular technology adoption path; alternative pathways for Thread versus Zigbee protocol dominance would alter the outlook for industrial mesh network vendor positioning. Forecasts reflect assumptions on EU F-Gas Regulation enforcement consistency and FDA audit-trail requirement harmonization. A small set of named triggers warrants ongoing watch: cybersecurity certification framework finalization, East Asian foundry capacity allocation shifts, and German Energieeinsparverordnung revision timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
Digital Flow Meter Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Global Temperature Sensors Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Global Battery Free RFID Sensor Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
Pressure Transmitter and Transducer Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Digital Angle Gauge Market