
 Hall-Effect Sensors Market | 2026-2036
Hall-Effect Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Hall-Effect Sensors Market Outlook
Modular sensor packaging is consolidating buyer choice around integrated Hall-effect modules that combine signal conditioning, temperature compensation, and digital output in single packages. Infineon Technologies leverages its automotive-qualified portfolio to anchor high-volume contracts with tier-one suppliers. Allegro MicroSystems specializes in current sensor ICs with integrated conductor paths, competing aggressively in electrified powertrain slots where isolation ratings matter.
Hall-effect sensors detect magnetic field strength through the transverse voltage generated when current flows through a conductor in a perpendicular magnetic field, typically operating from -40°C to 150°C with output sensitivities measured in millivolts per gauss. Their primary commercial purpose is contactless measurement of position, current, or speed in environments where mechanical wear or electrical isolation precludes resistive or capacitive alternatives. Digital sensors lead unit volume in consumer and automotive applications where binary switching suffices, while linear sensors command premium positioning in industrial servo systems requiring continuous field-to-voltage translation. Magnetic field sensing technology dominates R&D allocation as manufacturers push noise floors lower for precision current monitoring in EV inverters.
Automotive emissions regulators including NHTSA in the United States, KBA in Germany, and MIIT in China mandate increasingly precise motor control architectures that depend on Hall-effect feedback for efficiency compliance. ISO 26262 functional safety requirements force sensor suppliers to document failure modes and diagnostic coverage, raising barriers for unqualified entrants. Stakeholders must monitor how silicon carbide inverter adoption reshapes current sensing architectures and whether integrated magnetic concentrators displace discrete shunt resistor plus amplifier combinations.
Market Dynamics
Silicon carbide inverter architectures are forcing Hall-effect sensor suppliers to redesign current sensing topologies, as faster switching frequencies demand sub-microsecond response times and immunity to electromagnetic interference that legacy magnetic concentrators cannot deliver.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants mandates hermetic compressor designs that rely on contactless Hall-effect position sensing for reliability in heat pump and HVAC systems.
- China's industrial automation investments:Domestic robotics and servo motor production in Jiangsu and Guangdong provinces drives demand for linear Hall sensors with sub-millimeter accuracy in closed-loop motion control.
- Powertrain electrification:Traction motor inverters and battery management systems require galvanically isolated current sensing that shunt resistor plus amplifier combinations cannot provide at equivalent cost and board area.
Market Restraints
- Neodymium supply concentration:Rare earth magnet price volatility tied to Chinese export quotas raises bill-of-material uncertainty for Hall-effect modules requiring integrated magnetic bias.
- ISO 26262 compliance costs:Functional safety documentation and diagnostic coverage validation for ASIL-rated automotive sensors creates fixed cost barriers that exclude mid-tier suppliers from OEM qualification programs.
- AMR and TMR substitution:Anisotropic and tunnel magnetoresistance technologies offer superior sensitivity and lower power consumption in wearable and medical applications where Hall-effect sensors previously dominated.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives for electric two-wheelers and passenger vehicles create localized demand for cost-optimized Hall-effect speed and position sensors in motor control applications.
- Smart grid infrastructure:Distribution automation and renewable energy integration requires non-invasive current monitoring in medium-voltage switchgear where traditional instrument transformers prove impractical.
- 3D magnetic sensing convergence:Integration of planar Hall elements with vertical sensitivity axes enables single-chip solutions for joystick and control knob applications previously requiring multi-axis assemblies.
Industry Challenges
- ASIC design talent scarcity:Mixed-signal IC development for programmable sensitivity and temperature compensation requires analog-magnetic co-design expertise concentrated in Munich, Grenoble, and Boston metro areas.
- Legacy system integration friction:Industrial retrofit projects demand analog voltage output compatibility that conflicts with digital I2C and SENT protocol adoption in new sensor generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hall-Effect Sensors Market |
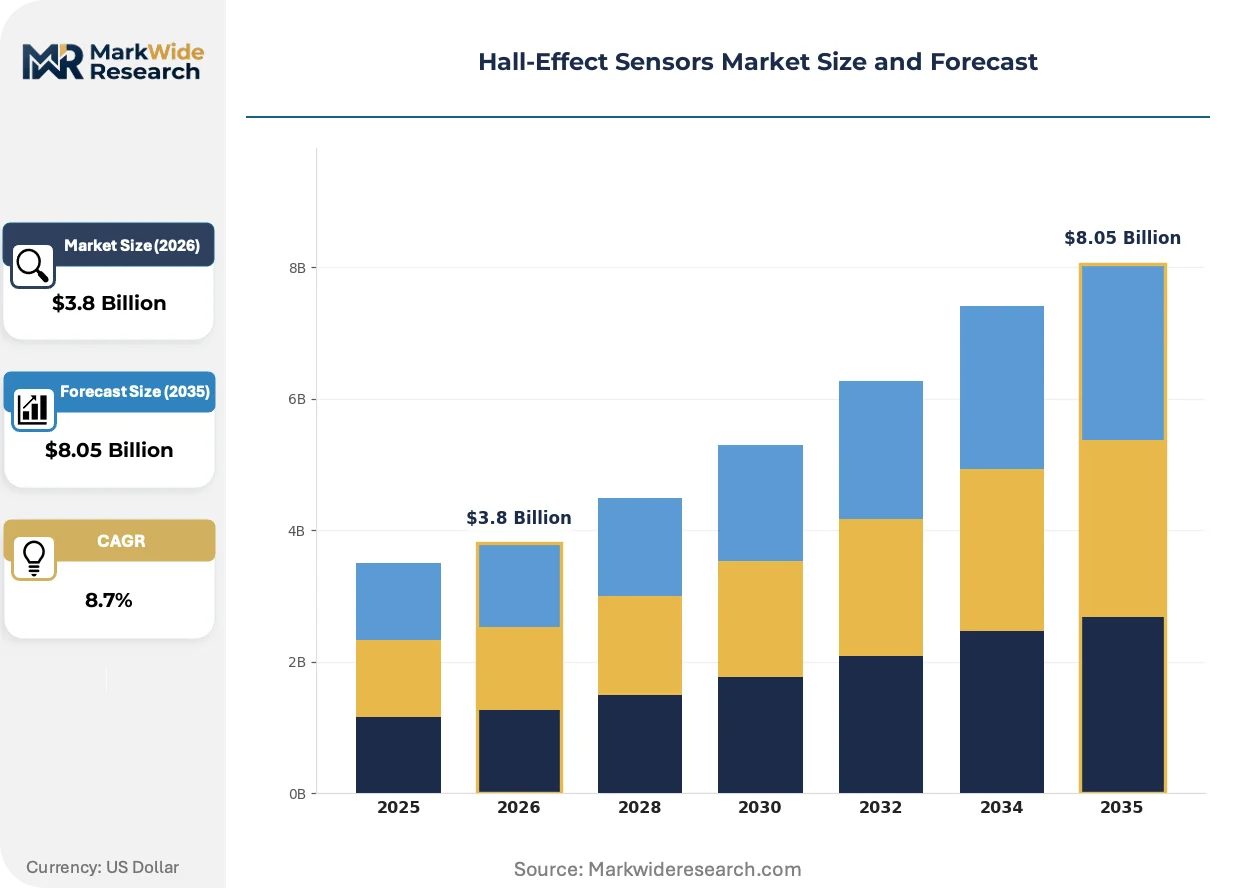
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Sensors, Digital Sensors, Linear Sensors, Position Sensors End User: Automotive, Consumer Electronics, Industrial Automation, Healthcare Technology: Magnetic Field Sensing, Current Transducer, Proximity Sensing, Motion Detection Application: Motor Control, Position Measurement, Current Sensing, Speed Detection |
| Companies Covered | Honeywell International, Infineon Technologies, Analog Devices, Allegro MicroSystems, Asahi Kasei Microdevices, TDK Corporation, NXP Semiconductors, Texas Instruments, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hall-Effect Sensors Market Strategic Shifts
Magnetic sensing architectures are compressing toward monolithic integration, eliminating external signal conditioning while embedding self-diagnostic capabilities that satisfy functional safety mandates without discrete redundancy.
Programmable linear Hall ICs with integrated EEPROM are automating end-of-line calibration for throttle position and pedal sensors, allowing tier-one suppliers to stock single part numbers across multiple vehicle platforms. Automakers in Germany and Japan are qualifying these devices for 48V mild-hybrid systems where rapid deployment cycles compress traditional 18-month validation timelines. The technology is automating supplier consolidation by collapsing discrete amplifier and compensation networks into foundry-processed silicon.
The EU F-Gas Regulation's refrigerant phase-down mandates are accelerating hermetic compressor redesigns that specify Hall-effect sensors for rotor position feedback in variable-speed drives. HVAC OEMs must demonstrate 20-year reliability in sealed environments where mechanical encoders fail, shifting specification authority from purchasing departments to system reliability engineers. Heat pump manufacturers in Poland and the Czech Republic are fastest to adopt, driven by residential heating electrification subsidies tied to efficiency performance thresholds.
Direct procurement from semiconductor suppliers is fragmenting traditional tier-one sensor module relationships, as EV powertrain engineers specify unprogrammed die for in-house calibration and encapsulation. This disintermediation concentrates in China, where BYD and CATL in-house teams validate magnetic concentrator geometries against proprietary motor designs. The shift compresses value capture at the packaged module level while rewarding foundries with automotive process qualifications.
Hall-Effect Sensors Market Segmentation
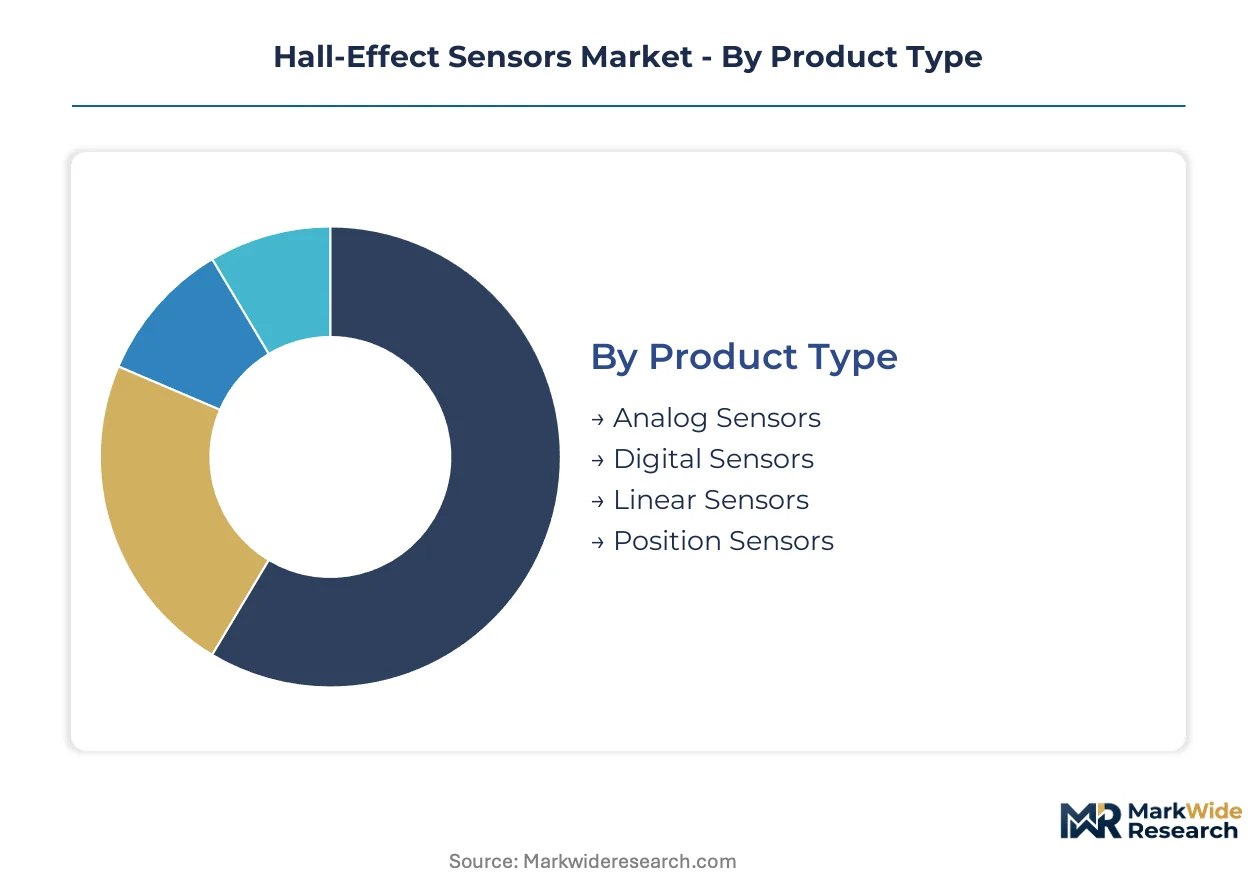
Hall-effect sensor procurement patterns diverge sharply across application contexts. Buyers prioritize response time and isolation ratings in traction inverters, while cost-per-unit dominates consumer electronics sourcing decisions.
Product Type:
Cost tier separates buyers seeking discrete components from those demanding fully integrated signal chains.
- Digital Sensors:Binary output devices eliminate external comparators through integrated threshold detection. Automotive body electronics and white goods manufacturers in China specify these for door-latch and lid-position detection where millimeter precision suffices.
- Linear Sensors:Continuous voltage output proportional to magnetic flux density enables closed-loop position feedback. Industrial servo systems in Germany and Japan demand sub-millimeter accuracy for robotics and CNC machine tools, with programmable sensitivity reducing calibration overhead.
- Analog Sensors:Raw millivolt-per-gauss outputs suit legacy industrial controllers with established ADC architectures.
- Position Sensors:Purpose-built packages for angular and linear displacement integrate magnetic concentrators for enhanced field capture.
Volume sits with Digital Sensors; growth tilts toward Linear Sensors.
End User:
Application maturity determines whether buyers accept development risk or demand automotive-qualified supply.
- Automotive:ISO 26262 ASIL ratings and AEC-Q100 qualification dominate sourcing criteria. Traction motor inverters and battery management systems require galvanic isolation that shunt-based alternatives cannot deliver at equivalent board area.
- Industrial Automation:Closed-loop motion control in Jiangsu and Guangdong province robotics clusters specifies linear Hall devices with temperature compensation for 24-hour operational stability.
- Consumer Electronics:Smartphone hinge-angle detection and laptop lid sensors prioritize sub-dollar unit economics over extended temperature ranges.
- Healthcare:Wearable device manufacturers specify low-power variants for continuous monitoring applications.
Revenue concentrates in Automotive; expansion runs fastest through Industrial Automation.
Technology:
Integration depth separates module suppliers from die-level procurement relationships.
- Magnetic Field Sensing:Foundry-processed silicon with embedded Hall plates and temperature compensation networks. R&D investment concentrates here as manufacturers push noise floors lower for precision current monitoring.
- Current Transducer:Integrated conductor paths with galvanic isolation ratings up to kilovolt levels. EV powertrain engineers in China validate unprogrammed die against proprietary magnetic concentrator geometries.
- Proximity Sensing:Threshold-based detection for presence-absence applications in security and access control systems.
- Motion Detection:Speed and direction output for rotational encoding in motor control applications.
Shipments cluster around Magnetic Field Sensing; Current Transducer climbs the fastest.
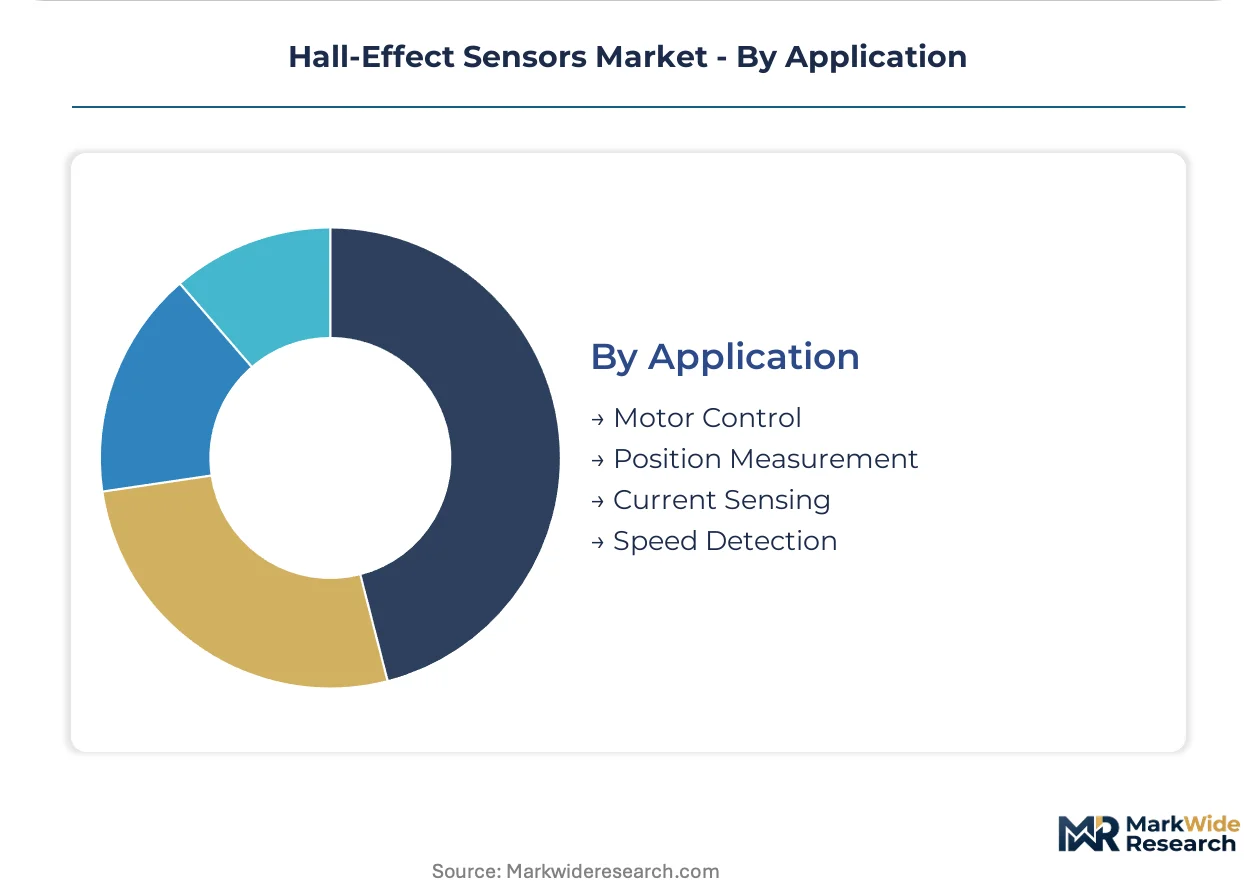
Application:
Switching frequency requirements in silicon carbide inverters are forcing architecture redesigns across sensing modalities.
- Current Sensing:Non-invasive measurement in medium-voltage switchgear and EV inverters where traditional instrument transformers prove impractical. Sub-microsecond response times are now mandatory for SiC-based power stages.
- Motor Control:Rotor position feedback for variable-speed drives in hermetic compressors and traction motors. EU F-Gas Regulation mandates are accelerating heat pump adoption in Poland and Czech Republic residential heating.
- Position Measurement:Throttle pedal and steering column angular sensing with end-of-line EEPROM calibration.
- Speed Detection:Crankshaft and wheel-speed encoding for powertrain and chassis control systems.
Deployment scale favors Motor Control; Current Sensing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate Hall-effect sensor demand through BYD and CATL battery manufacturing clusters, while Germany's automotive corridor and India's PLI automotive zones shape regional procurement patterns.
China
Domestic EV production in Jiangsu and Guangdong provinces drives demand for current transducers and position sensors in traction motor inverters. MIIT emissions standards mandate precision motor control architectures that depend on Hall-effect feedback for efficiency compliance. BYD and CATL in-house engineering teams in Shenzhen and Ningbo validate unprogrammed die against proprietary magnetic concentrator geometries, bypassing traditional tier-one module suppliers.
Germany
KBA automotive emissions regulations compel OEMs to specify magnetic sensors with wider temperature ranges and higher precision for powertrain electrification. The EU F-Gas Regulation accelerates hermetic compressor redesigns that rely on contactless position sensing in heat pump systems. Industrial automation clusters in Bavaria and Baden-Württemberg specify linear Hall devices with sub-millimeter accuracy for robotics and CNC machine tools.
United States
NHTSA efficiency mandates push automakers toward 48V mild-hybrid architectures requiring rapid sensor validation cycles. The Inflation Reduction Act's domestic content provisions incentivize localized sensor procurement for EV powertrains. Michigan and Ohio automotive engineering centers qualify programmable linear Hall ICs with integrated EEPROM for throttle position and pedal sensors across multiple vehicle platforms.
India
The PLI scheme for automotive manufacturing creates localized demand for cost-optimized Hall-effect speed and position sensors in electric two-wheeler and passenger vehicle motor control applications. CEA grid modernization initiatives require non-invasive current monitoring in distribution automation. Tamil Nadu and Maharashtra automotive clusters attract sensor suppliers seeking qualification for domestic EV production.
Japan
METI industrial efficiency programs drive adoption of closed-loop servo systems specifying linear Hall sensors with temperature compensation. Automotive manufacturers in Kansai and Chubu regions validate sensors for 20-year reliability in hermetic compressor environments. Precision equipment manufacturers in Nagoya specify devices with programmable sensitivity for end-of-line calibration automation.
Hall-Effect Sensors Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Hall-effect sensor market, creating a tiered structure where automotive qualification separates premium suppliers from commodity players. Consolidation concentrates around semiconductor foundries with automotive process certifications and magnetic sensor design expertise. Three archetypes dominate: integrated device manufacturers with captive fabs, fabless specialists licensing proprietary magnetic concentrator IP, and diversified industrial conglomerates leveraging sensor portfolios within broader automation offerings. Competitive moves center on foundry capacity reservations for automotive-qualified processes and strategic partnerships with EV powertrain engineering teams.
Among diversified semiconductor manufacturers, Infineon Technologies and Texas Instruments occupy positions anchoring high-volume automotive contracts through automotive-qualified portfolios. Allegro MicroSystems exemplifies the fabless specialist archetype, with integrated conductor path designs competing in electrified powertrain slots where isolation ratings matter. These three companies represent the competitive spectrum from broad-based silicon suppliers to magnetic sensing-focused entities, each leveraging different structural advantages in customer qualification timelines and manufacturing scale.
| Leading Market Players |
|---|
| Honeywell International |
| Infineon Technologies |
| Analog Devices |
| Allegro MicroSystems |
| Asahi Kasei Microdevices |
| TDK Corporation |
| NXP Semiconductors |
| Texas Instruments |
| STMicroelectronics |
| Others |
Value Chain & Pricing Dynamics
Foundry-backed specialists with automotive process certifications exercise pricing discipline through captive wafer capacity, while tier-one module suppliers absorb margin compression from direct die procurement by Chinese EV engineering teams. This ownership pattern concentrates supply leverage among semiconductor manufacturers with AEC-Q100 qualifications, forcing packaged module vendors to compete on calibration services rather than silicon margin.
Pricing Analysis
Cost-down pressure on standard-grade linear sensors accelerates because BYD and CATL in-house teams source unprogrammed die for proprietary magnetic concentrator validation. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer-tier devices separates buyers by ISO 26262 certification requirements and temperature range specifications. Automotive ASIL-rated sensors command premium positioning due to diagnostic coverage documentation and failure mode analysis overhead, while consumer electronics buyers prioritize sub-dollar unit economics with minimal signal conditioning. Price differentiation hinges on foundry process node and integrated EEPROM programmability, with EV powertrain engineers least sensitive to per-unit cost and white goods manufacturers most responsive to volume discounts.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific semiconductor hubs to European automotive corridors amplifies inventory carrying costs for just-in-time sensor module assembly. Manufacturing concentrates in Taiwan, South Korea, and Germany, with 200mm and 300mm wafer foundries feeding backend test and calibration facilities in Malaysia and the Philippines. Raw material dependencies include gallium arsenide substrates, copper leadframes, and neodymium magnetic bias elements subject to Chinese export quota fluctuations. Single-source vulnerability around automotive-qualified foundry capacity creates qualification bottlenecks for tier-two entrants. Distribution runs through authorized semiconductor distributors to tier-one module integrators, with direct die procurement by Chinese EV manufacturers fragmenting traditional channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hall-effect sensor market rewards backward integration into magnetic concentrator design and foundry process development, as EV powertrain engineers disintermediate packaged module suppliers for die-level relationships. Captive calibration capabilities and proprietary Hall plate geometries represent the primary levers for margin defense.
For Market Incumbents: Hedge against AMR and TMR substitution in wearable and medical applications by accelerating R&D allocation toward sub-microsecond response architectures compatible with silicon carbide inverter switching frequencies. Defensive consolidation through foundry capacity reservations for automotive-qualified processes protects qualification timelines against single-source bottlenecks. Tier-one supplier relationships require reinforcement through integrated EEPROM programming services that justify packaged module premiums against direct die procurement. For New Entrants and Emerging Players: E-commerce-enabled technical distribution offers the fastest route to qualified supplier status among mid-tier industrial automation buyers in India's Tamil Nadu and Maharashtra automotive clusters. White-space targets include cost-optimized speed sensors for electric two-wheeler motor control under India's PLI scheme and non-invasive current monitoring for CEA grid modernization initiatives. Technical specification support through online magnetic field simulation tools differentiates against established distributor relationships. For Investors and Strategic Acquirers: Foundry announcements of automotive process capacity expansion serve as the leading indicator that qualification timelines will compress and mid-tier suppliers will regain access to premium tier contracts. Long-term viability rests on magnetic sensing IP portfolios with programmable sensitivity and temperature compensation architectures. Acquisition targets include fabless specialists with integrated conductor path designs and established relationships with Chinese EV powertrain engineering teams. Watch for MIIT emissions standard revisions that mandate precision motor control architectures and expand addressable sensor content per vehicle.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Automotive process qualifications at TSMC and GlobalFoundries lock in supply security for ASIL-rated sensor production. |
| Magnetic Concentrator IP Acquisition | Proprietary flux-focusing geometries differentiate current transducer performance in EV inverter applications. |
| End-of-Line Calibration Automation | Programmable Hall ICs with integrated EEPROM reduce tier-one supplier inventory complexity across vehicle platforms. |
| SiC Inverter Compatibility Certification | Sub-microsecond response validation opens traction motor inverter slots previously served by shunt resistor architectures. |
| Direct Procurement Relationship Development | Engineering engagement with BYD and CATL teams bypasses traditional tier-one module supplier intermediation. |
Study Parameters
Multi-period observation of AEC-Q100 qualification timelines, foundry capacity utilization rates, and EV powertrain sensor content per vehicle anchored the trend analysis, supplemented by interviews with Hall-effect sensor design engineers, tier-one automotive supplier procurement managers, semiconductor foundry business development directors, and industrial automation system integrators. Secondary validation drew from MIIT vehicle efficiency filings, NHTSA regulatory dockets, EU F-Gas Regulation implementation reports, SEC 10-K semiconductor segment disclosures, and IHS Markit vehicle production databases. Bottom-up shipment estimates by sensor type and end-use application triangulated against top-down semiconductor industry revenue allocations.
Segment-weighting by propulsion architecture, certification tier, and regional production cluster shaped the analytical framework across the projection horizon. Modeled dimensions included digital versus linear output type, automotive versus industrial versus consumer end-use, and integrated versus discrete module form factor. CAGRs derived from regression analysis of historical adoption curves for comparable magnetic sensing technologies, adjusted for silicon carbide inverter penetration rates and EU F-Gas Regulation compliance deadlines. Industry-specific forecast inputs incorporated OEM platform electrification roadmaps and heat pump installation subsidies in Poland and Czech Republic residential heating markets.
The model holds under sustained EV production growth and stable rare earth magnet supply; deviation in neodymium export restrictions or silicon carbide inverter adoption slowdown would shift sensor architecture preferences and revenue trajectories. Forecasts reflect documented assumptions regarding qualification timeline compression and direct procurement trend continuation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
NB-IoT Smart Meter Market
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
Magnetic Field Sensor Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
Middle East and Africa Wireless Sensors Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
MEMS Market
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
US Digital Thermometer Market