
 Magnetic Therapy Devices Market | 2026-2036
Magnetic Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Therapy Devices Market Analytics
Chinese contract manufacturers is hardening output capacity for low-frequency electromagnetic coils, tightening supply availability for branded assemblers worldwide. Bemer Group leverages its Swiss engineering heritage to sustain premium positioning across European wellness clinics. Orthofix Medical Inc. anchors its presence through professional-grade devices distributed via rehabilitation center networks. MagnaWave competes aggressively in the North American equine and human sports recovery segments with high-intensity pulse delivery systems.
Magnetic therapy devices generate therapeutic effects through pulsed electromagnetic fields typically operating between 1-100 Hz, with static magnet variants employing neodymium or ferrite compositions arranged in bipolar or multipolar configurations; these systems modulate cellular ion transport to reduce inflammation and accelerate tissue repair in musculoskeletal applications. Wearable devices dominate unit volume as consumers seek continuous low-field exposure during daily activity, while professional devices command superior margin pools through clinical validation requirements and practitioner channel control. Portable units represent the fastest-expanding delivery mode, reflecting demand from traveling sports professionals and home-based rehabilitation protocols.
FDA classifies many magnetic therapy devices as Class II medical instruments requiring 510(k) clearance for pain relief claims, while CE marking under the EU MDR imposes stricter clinical evidence standards for electromagnetic stimulation products. ISO 13485 certification governs quality management for manufacturers targeting regulated healthcare channels, creating compliance barriers for unvalidated consumer brands. Stakeholders must monitor evolving reimbursement decisions by national health authorities, as coverage expansion for non-pharmacological pain management would reshape competitive economics across delivery modes.
Market Dynamics
Professional sports recovery protocols are pulling high-intensity pulsed electromagnetic field systems into mainstream rehabilitation, compressing the historical divide between clinical-grade and consumer-accessible devices. Teams across multiple leagues now mandate non-invasive recovery modalities, creating institutional procurement pathways that bypass traditional medical distribution.
Growth Catalysts
- CE marking under EU MDR:Stricter clinical evidence standards for electromagnetic stimulation products are filtering out unvalidated competitors, concentrating demand among ISO 13485-certified manufacturers serving European wellness clinics.
- Equine sports medicine:Professional horse racing and equestrian competition circuits in North America are adopting high-intensity pulse delivery systems for tendon and ligament recovery, opening a parallel species application with premium pricing tolerance.
- Neodymium ferrite coil arrays:Advances in bipolar and multipolar static magnet configurations are improving field uniformity across wearable form factors, enabling continuous low-field exposure during daily consumer activity.
Market Restraints
- Chinese contract manufacturer concentration:Hardening output capacity for low-frequency electromagnetic coils is tightening supply availability for branded assemblers, creating single-source vulnerability for coil winding and ferrite core fabrication.
- FDA 510(k) clearance timelines:Class II medical instrument classification for pain relief claims imposes 12-18 month regulatory review cycles, delaying market entry for novel frequency protocols and waveform innovations.
- Pharmacological pain management:Reimbursement-established opioid and NSAID protocols maintain institutional preference in acute care settings, limiting electromagnetic therapy to self-pay wellness and rehabilitation channels.
Strategic Opportunities
- German rehabilitation center networks:Wellness clinics in Bavaria and Baden-Württemberg actively prescribe pulsed electromagnetic field systems for chronic pain, creating a reference market for adjacent EU member state expansion.
- Home-based post-surgical recovery:Portable units are capturing demand from traveling sports professionals and patients discharged with continuous rehabilitation protocols, displacing clinic-dependent treatment models.
- Reimbursement policy evolution:National health authority coverage expansion for non-pharmacological pain management would reshape competitive economics, particularly in single-payer systems evaluating electromagnetic therapy for musculoskeletal conditions.
Industry Challenges
- Biomedical engineering talent scarcity:The intersection of electromagnetic field physics, cellular ion transport biology, and medical device regulatory science requires specialized expertise that concentrates in Swiss and German engineering clusters.
- Clinical validation capex:Randomized controlled trials for FDA 510(k) clearance and CE marking under EU MDR demand multi-million dollar investment in trial design, site management, and statistical analysis.
- Legacy static magnet consumer perception:Widespread availability of unvalidated neodymium bracelet products has created skepticism requiring education investment for differentiated pulsed electromagnetic field technology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Therapy Devices Market |
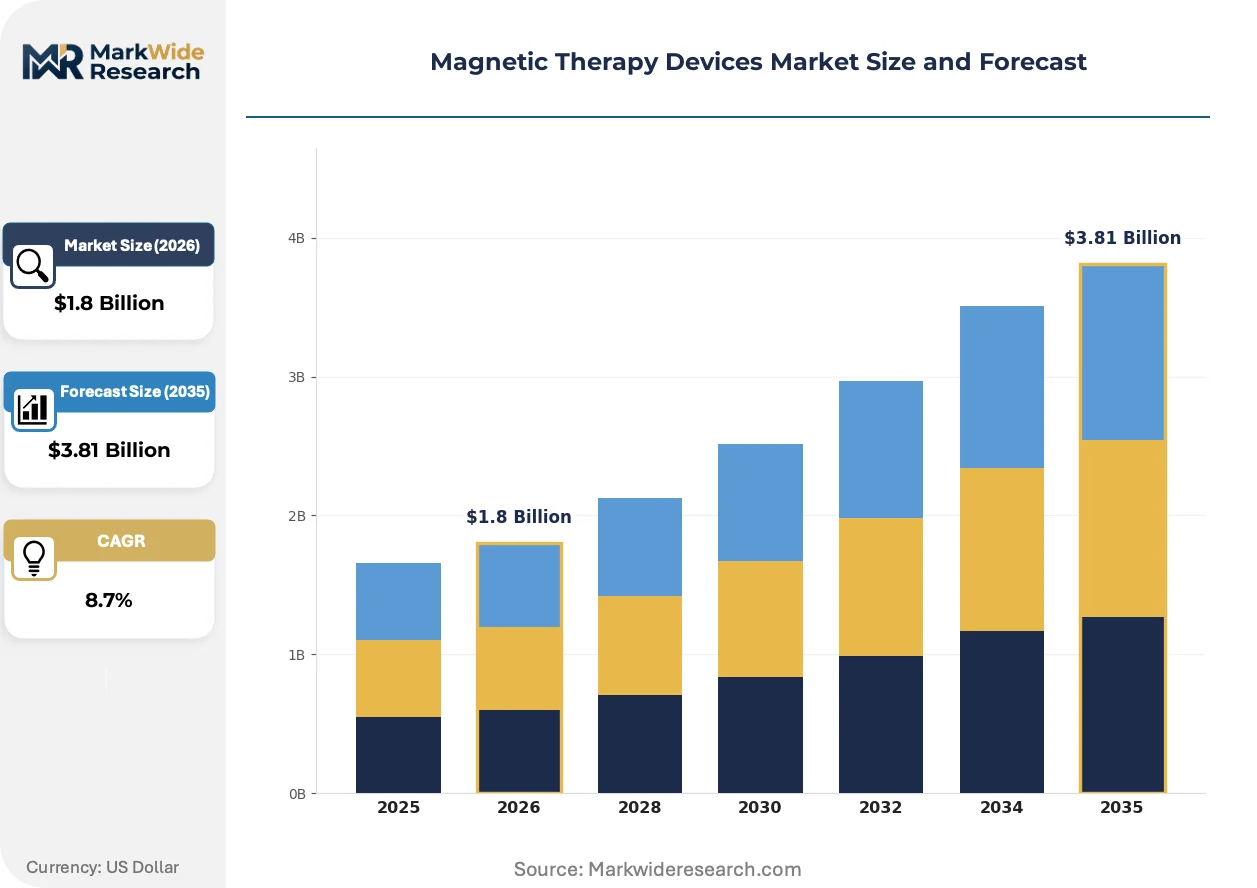
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Bracelets, Magnetic Mattresses, Magnetic Pads, Magnetic Rings Application: Pain Relief, Sports Recovery, Health Maintenance, Wellness Promotion Delivery Mode: Wearable Devices, Home Use Products, Professional Devices, Portable Units End User: Individuals, Sports Professionals, Rehabilitation Centers, Wellness Clinics |
| Companies Covered | Bemer Group, Orthofix Medical Inc., MagnaWave, Oska Pulse, Medithera GmbH, Curatronic Ltd., Swiss Bionic Solutions, I-Tech Medical Division, Nikken, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Therapy Devices Market Evolving Landscape
Device architecture is fragmenting into interoperable subsystems that separate field generation, power management, and biometric feedback, enabling rapid configuration swaps across sports, veterinary, and clinical applications without full platform redesign.
Multi-frequency waveform generators are modularizing into swappable cartridge systems that rehabilitation centers configure for specific tissue depths and injury types. Professional sports teams in Germany and Switzerland are adopting these platforms to customize recovery protocols by athlete position and injury history. The approach is compressing equipment refresh cycles from five-year capital purchases to annual cartridge subscriptions.
CE marking under the EU MDR is elevating clinical evidence requirements for electromagnetic stimulation products beyond the previous Medical Device Directive thresholds. Manufacturers must now submit post-market surveillance data and risk management files that document long-term field exposure effects. German notified bodies are processing these submissions with 18-24 month timelines, forcing smaller competitors toward consumer wellness positioning outside regulated medical channels.
Certification-driven procurement is displacing price-first selection in institutional channels. Rehabilitation centers and sports medicine clinics now require ISO 13485 quality management documentation and FDA 510(k) clearance or CE marking as table stakes for vendor qualification. This behavior concentrates contract awards among vertically integrated manufacturers with captive regulatory affairs capabilities, particularly visible in North American professional sports franchise purchasing committees.
Magnetic Therapy Devices Market Segmentation
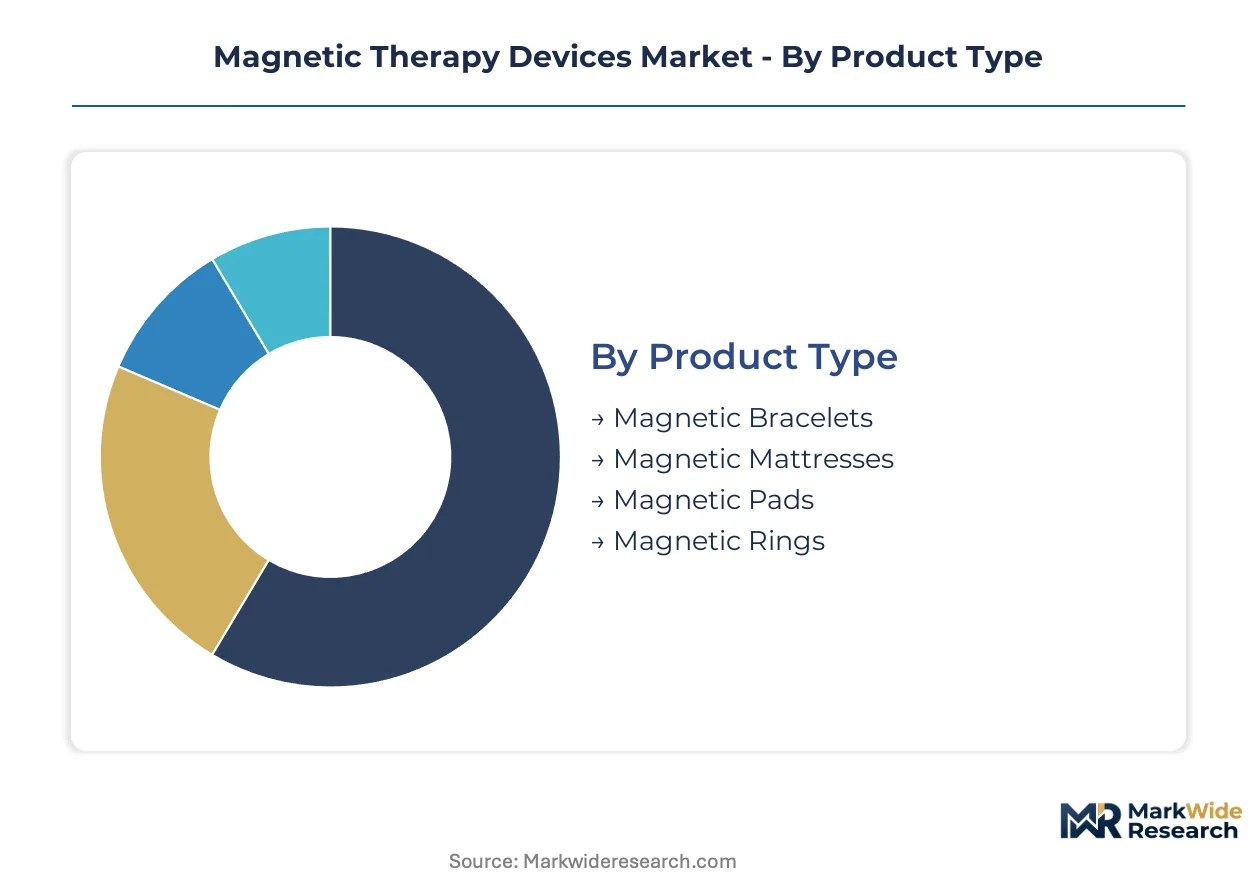
Magnetic therapy devices fragment across four intersecting dimensions that determine regulatory pathway, margin structure, and channel access. Product specifications dictate whether devices clear FDA Class II thresholds or remain in consumer wellness positioning. Application context and delivery mode together shape procurement authority and reimbursement potential.
Product Type:
Material composition and field generation mechanism separate clinically validated systems from commodity wellness accessories.
- Magnetic Mattresses:Pulsed electromagnetic field systems embedded in sleep surfaces deliver continuous low-frequency exposure across full-body contact areas. German rehabilitation centers and Austrian wellness clinics prescribe these for chronic pain patients seeking non-pharmacological alternatives to opioid protocols.
- Magnetic Pads:Localized field generators with neodymium or ferrite coil arrays target specific anatomical regions through bipolar configurations. Sports medicine facilities in Switzerland deploy these for post-surgical tissue repair protocols, compressing recovery timelines for professional athletes.
- Magnetic Bracelets:Static magnet accessories employing multipolar arrangements circulate in consumer wellness channels without clinical validation requirements.
- Magnetic Rings:Finger-worn ferrite configurations offer discrete low-field exposure for continuous daily wear applications.
Mature deployment sits with Magnetic Pads in institutional channels. Newer deployment is concentrated in Magnetic Mattresses as home-based rehabilitation protocols expand.
Application:
Clinical indication determines evidence requirements and pricing tolerance across reimbursement and self-pay channels.
- Sports Recovery:High-intensity pulsed electromagnetic field protocols accelerate tendon and ligament repair in professional athletic populations. North American equine racing circuits and human sports franchises now mandate these systems in institutional procurement guidelines, bypassing traditional medical distribution.
- Pain Relief:FDA 510(k) clearance for analgesic claims requires randomized controlled trial evidence and ISO 13485 quality management certification. Bavarian pain management clinics in Germany anchor European demand for validated electromagnetic stimulation systems.
- Wellness Promotion:General vitality claims operate outside medical device classification in most jurisdictions, enabling direct-to-consumer distribution.
- Health Maintenance:Preventive applications concentrate in consumer wearable segments without clinical endpoint validation.
Established clinical penetration centers on Pain Relief applications. Steepest expansion trajectory belongs to Sports Recovery as team-based procurement scales.
Delivery Mode:
Form factor determines use context, power requirements, and regulatory classification boundaries.
- Professional Devices:Clinical-grade systems with adjustable frequency protocols and practitioner-controlled treatment parameters command premium positioning through rehabilitation center networks. CE marking under EU MDR imposes 18-24 month approval timelines that filter out smaller competitors.
- Portable Units:Battery-powered electromagnetic field generators enable traveling sports professionals and discharged patients to maintain continuous treatment protocols outside clinical settings. These systems are climbing the fastest in unit volume as home-based care models displace facility-dependent rehabilitation.
- Wearable Devices:Continuous low-field exposure accessories dominate consumer unit shipments through daily activity integration.
- Home Use Products:Fixed installation systems target residential wellness environments with simplified operation interfaces.
Capital deployment concentrates in Professional Devices. Volume scaling is accelerating fastest in Portable Units as mobility requirements reshape patient expectations.
End User:
Procurement authority and evidence requirements diverge sharply between institutional and individual purchasers.
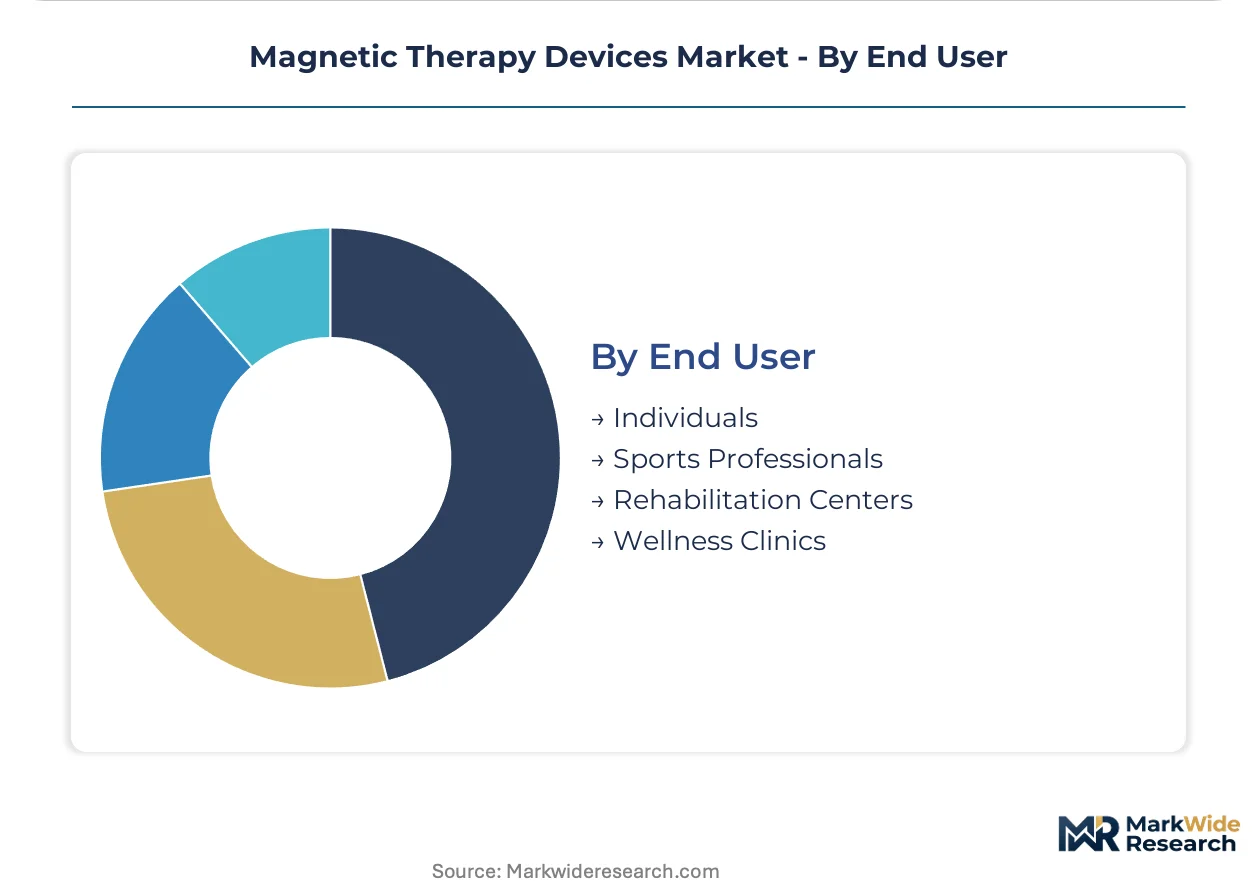
- Rehabilitation Centers:Institutional purchasers require FDA 510(k) clearance or CE marking, ISO 13485 documentation, and post-market surveillance data as mandatory vendor qualification criteria. German networks in Baden-Württemberg actively prescribe pulsed electromagnetic field systems for musculoskeletal rehabilitation.
- Sports Professionals:Team-based procurement committees across multiple leagues now mandate non-invasive recovery modalities, creating institutional purchasing pathways with premium pricing tolerance for high-intensity pulse delivery systems.
- Wellness Clinics:European facilities combine clinical environment credibility with self-pay revenue models.
- Individuals:Direct consumers select primarily on price and convenience without regulatory validation requirements.
Procurement sophistication is highest among Rehabilitation Centers. Fastest-growing demand concentration is emerging in Sports Professionals as franchise-level standardization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium mining operations in Inner Mongolia anchor raw material flows for ferrite core fabrication, concentrating coil winding capacity in Chinese contract manufacturing zones before distribution to branded assemblers across three continents.
Germany
Bavarian pain management clinics and Baden-Württemberg rehabilitation centers prescribe pulsed electromagnetic field systems for chronic musculoskeletal conditions. CE marking under the EU MDR imposes 18-24 month approval timelines that filter out unvalidated competitors. Berlin-Brandenburg hosts ISO 13485-certified engineering clusters specializing in multi-frequency waveform generators for institutional procurement channels.
United States
Professional sports franchises across multiple leagues mandate non-invasive recovery modalities in institutional procurement guidelines. FDA Class II classification requires 510(k) clearance for pain relief claims, creating 12-18 month regulatory review cycles. Greater Boston and California's Bay Area concentrate biomedical engineering talent at the intersection of electromagnetic physics and cellular biology.
Switzerland
Swissmedic oversight maintains premium positioning for wellness clinic distribution through rigorous clinical evidence standards. Zurich and Geneva engineering heritage sustains captive regulatory affairs capabilities. The Alpine corridor anchors professional-grade device manufacturing for European rehabilitation network supply.
China
Zhejiang and Guangdong provinces harden output capacity for low-frequency electromagnetic coils, tightening supply availability for branded assemblers worldwide. NMPA registration pathways for Class II medical devices impose documentation requirements distinct from export-only production. Yangtze River Delta clusters dominate ferrite core fabrication and coil winding subcontracting.
United Kingdom
London and Southeast England wellness clinics combine clinical environment credibility with self-pay revenue models for electromagnetic stimulation systems. MHRA registration requirements align with EU MDR standards post-Brexit transition. Midlands manufacturing bases serve rehabilitation center networks across England and Scotland.
Magnetic Therapy Devices Market Competitive Landscape
Global majors compete with regional champions across certification depth and channel access, creating a tiered structure where ISO 13485 documentation separates institutional suppliers from consumer wellness positioning. The vendor base concentrates among vertically integrated manufacturers with captive regulatory affairs capabilities and specialized engineering consultancies serving niche frequency protocol development. Three archetypes dominate: Swiss-German engineering heritage firms commanding premium clinic pricing, North American sports-focused specialists capturing team procurement pathways, and Chinese contract manufacturers supplying coil subsystems to branded assemblers. Competitive moves center on M&A for regulatory clearance portfolios and strategic partnerships with rehabilitation center networks to secure institutional procurement contracts.
Among Swiss-German engineering heritage firms, Bemer Group and Swiss Bionic Solutions exemplify the premium-tier positioning sustained through wellness clinic channel control and CE marking compliance. Orthofix Medical Inc. occupies a position within the North American professional-grade segment, anchoring presence through rehabilitation center network distribution. MagnaWave represents the sports-specialist archetype competing aggressively in high-intensity pulse delivery for equine and human athletic recovery applications.
| Leading Market Players |
|---|
| Bemer Group |
| Orthofix Medical Inc. |
| MagnaWave |
| Oska Pulse |
| Medithera GmbH |
| Curatronic Ltd. |
| Swiss Bionic Solutions |
| I-Tech Medical Division |
| Nikken |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FDA 510(k)-cleared institutional systems and unvalidated consumer wellness accessories manifests in pricing spreads exceeding fivefold, with ISO 13485 documentation requirements and captive regulatory affairs capabilities anchoring premium tiers while commodity coil assemblies feed economy positioning through divergent procurement channels.
Pricing Analysis
Extended warranty and field service bundling separates professional-grade device pricing from bare-hardware consumer transactions, with rehabilitation center contracts typically incorporating multi-year calibration and firmware update coverage. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with CE marking under EU MDR and FDA clearance commanding substantial premiums over wellness-channel alternatives. Pricing pressure stems from Chinese contract manufacturer consolidation in coil winding, compressing margins for branded assemblers without captive ferrite core fabrication. Sports franchise procurement committees exhibit lowest price sensitivity given performance-linked recovery protocols, while individual consumers selecting magnetic bracelets prioritize unit cost above clinical validation.
Supply Chain Analysis
Direct-to-rehabilitation-center distribution handles institutional-grade device demand, bypassing traditional medical distributor markups through manufacturer field sales organizations. Manufacturing gravity centers on China for low-frequency electromagnetic coils, Switzerland for precision waveform generators, and Germany for ISO 13485-certified system integration. Neodymium ferrite cores, copper magnet wire, and medical-grade polymer housings constitute critical input dependencies. Single-source vulnerability concentrates in Yangtze River Delta coil winding capacity, where hardening output allocation threatens supply security for branded assemblers lacking backward integration into ferrite core fabrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration imperatives dominate competitive strategy as manufacturers race to secure captive coil winding capacity and regulatory clearance portfolios, with upstream control over ferrite core fabrication emerging as the decisive margin defense mechanism.
For Market Incumbents: Anchor market position through exclusive rehabilitation center network partnerships in Germany and Switzerland, locking out competitors from reference-site procurement pathways. Deepen backward integration into neodymium ferrite core production to offset Chinese contract manufacturer pricing leverage. Defend against sports-specialist entrants by embedding multi-frequency waveform generators in franchise-level subscription contracts that compress equipment refresh cycles. For New Entrants and Emerging Players: Launch via direct-to-consumer portable units targeting traveling sports professionals and post-surgical home recovery patients, bypassing institutional certification barriers that concentrate among established ISO 13485-certified manufacturers. Exploit white-space opportunity in equine sports medicine across North American racing circuits, where premium pricing tolerance exceeds human clinical applications. Pursue wellness clinic positioning in Eastern European markets adjacent to German reference networks, leveraging CE marking reciprocity without full EU MDR compliance investment. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists possessing captive regulatory affairs capabilities given reimbursement policy evolution toward non-pharmacological pain management. Long-term viability over the next decade hinges on FDA 510(k) clearance portfolio depth and post-market surveillance data accumulation that satisfies EU MDR post-market clinical follow-up requirements. Monitor national health authority coverage decisions for electromagnetic therapy in musculoskeletal conditions as the primary inflection signal for competitive economics reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance filters unvalidated competitors from German rehabilitation center procurement. |
| Hospital System Partnership | Bavarian pain management clinics prescribe pulsed electromagnetic field systems for chronic conditions. |
| Reimbursement Strategy | National health authority coverage expansion would reshape single-payer system competitive economics. |
| Software Companion Development | Biometric feedback modules enable protocol customization for sports franchise recovery applications. |
| Backward Integration | Captive ferrite core fabrication defends margin position against Chinese contract manufacturer concentration. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineering specialist consultations, and rehabilitation center procurement director surveys underwrites the qualitative findings. Primary fieldwork engaged clinicians, GPO contracts managers, sports medicine franchise equipment coordinators, and regulatory affairs leads at electromagnetic device manufacturers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, hospital procurement databases, and CMS Medicare coverage determination filings. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition across product type, application indication, delivery mode, and end-user procurement authority generated volume and value trajectories. Segmentation dimensions incorporated field generation mechanism, clinical validation tier, form factor mobility class, and institutional versus individual purchasing channel. CAGRs were derived from weighted average growth contributions across segment-level demand curves. Forecast inputs included professional sports franchise procurement guideline adoption rates and EU MDR approval timeline compression effects on competitive entry.
Regulatory approval delays, reimbursement policy reversals, and raw material supply disruptions are the dominant revision risks. Forecasts reflect documented assumptions regarding CE marking timeline stability and coil winding capacity expansion in Chinese manufacturing zones. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market