
 Liposomal Doxorubicin Market | 2026-2036
Liposomal Doxorubicin Market Size, Share, and Industry Trends Forecast 2026-2036
Liposomal Doxorubicin Market Intelligence
EMA's tightened bioequivalence guidelines for liposomal drug products is consolidating the cost-of-entry calculus for generic developers across Europe. Cipla leverages its complex generic manufacturing infrastructure to sustain supply continuity in regulated markets. Sun Pharmaceutical Industries Ltd. anchors its position through vertically integrated active pharmaceutical ingredient production. Pfizer Inc. competes on the strength of its legacy clinical data packages and institutional prescriber relationships.
Liposomal doxorubicin is a pegylated liposome-encapsulated anthracycline chemotherapy agent with a hydrodynamic diameter of approximately 100 nanometers, engineered to prolong circulation time and preferentially accumulate in tumor tissue via enhanced permeability and retention. The liposomal formulation segment dominates current revenue as clinicians prioritize cardiotoxicity mitigation in recurrent ovarian cancer and Kaposi sarcoma protocols. The breast cancer application category represents the fastest-growing structural pocket, driven by adjuvant and neoadjuvant protocol expansions in academic medical centers.
FDA bioequivalence standards, EMA quality guidelines for nanomedicines, and WHO prequalification pathways collectively determine market access timelines and commercialization feasibility for new entrants. These frameworks elevate manufacturing consistency and analytical characterization requirements beyond conventional small-molecule generics. Stakeholders must monitor evolving regulatory convergence on liposomal characterization methods and stability testing protocols to anticipate competitive displacement risks.
Market Dynamics
FDA bioequivalence standards for complex generics are compressing competitive timelines, forcing manufacturers to demonstrate physicochemical equivalence beyond conventional small-molecule thresholds. This regulatory tightening is reshaping capital allocation across formulation development.
Growth Catalysts
- Cardiotoxicity-sparing protocols:Academic medical centers in the United States are prioritizing liposomal anthracyclines in recurrent ovarian cancer regimens to reduce long-term cardiac surveillance burden.
- Medicare reimbursement alignment:CMS policies now favor established liposomal formulations over conventional doxorubicin in metastatic breast cancer settings, directing prescribing patterns toward encapsulated agents.
- WHO prequalification pathways:The expanded access program for oncology medicines in low- and middle-income countries is creating procurement channels for quality-assured liposomal formulations.
Market Restraints
- High-purity phospholipid concentration:Supply of hydrogenated soy phosphatidylcholine concentrates among three specialized chemical suppliers, exposing manufacturers to input cost volatility and allocation constraints.
- Complex characterization requirements:EMA quality guidelines for nanomedicines mandate extensive liposomal stability testing that extends development timelines by 18-24 months relative to conventional generics.
- Biosimilar substitution pressure:Emerging antibody-drug conjugates for HER2-positive breast cancer are displacing liposomal doxorubicin in some neoadjuvant protocols.
Strategic Opportunities
- Academic medical center expansion:Brazil's unified health system is incorporating liposomal chemotherapy into Kaposi sarcoma treatment guidelines, opening procurement volumes in Latin America's largest oncology market.
- Process analytical technology convergence:Integration of real-time release testing with continuous manufacturing platforms is enabling batch-to-batch consistency improvements that satisfy FDA expectations for complex generics.
- Specialty pharmacy channel development:Direct distribution partnerships with limited-distribution networks are bypassing traditional wholesale markups and capturing margin in the United States.
Industry Challenges
- Liposomal formulation science expertise:The scarcity of process engineers trained in extrusion-based encapsulation and long-circulating liposome design is constraining manufacturing scale-up timelines.
- Legacy equipment retrofit requirements:Existing aseptic filling lines require substantial capital investment to handle temperature-sensitive liposomal suspensions without shear-induced degradation.
- Intellectual property landscape complexity:Patent thickets surrounding PEGylation chemistry and stealth liposome compositions create freedom-to-operate uncertainties for generic developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liposomal Doxorubicin Market |
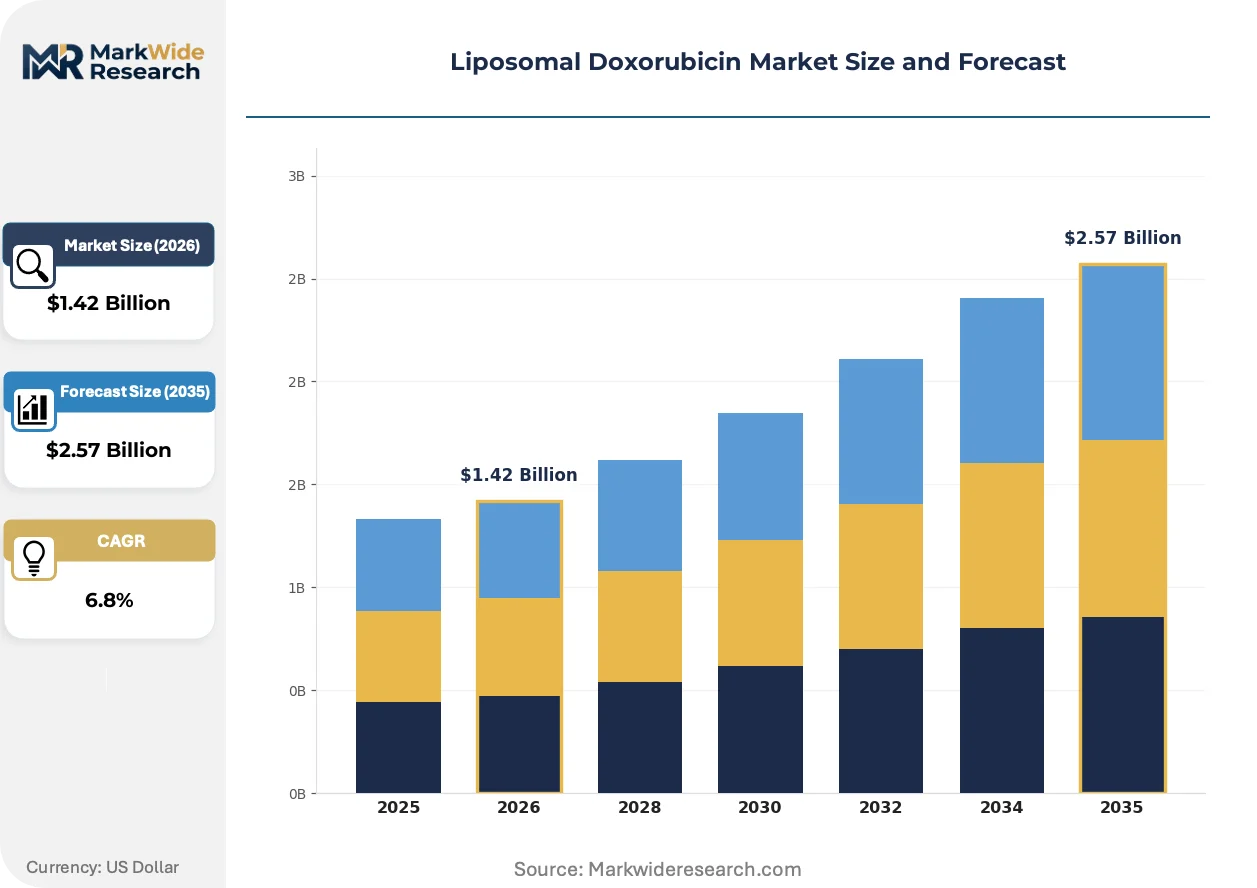
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liposomal Formulation, Conventional Doxorubicin, Nanoparticle Doxorubicin, Combination Therapy Application: Cancer Treatment, Breast Cancer, Ovarian Cancer, Sarcoma End User: Hospitals, Oncology Centers, Research Laboratories, Homecare Delivery Mode: Intravenous, Oral, Subcutaneous, Other |
| Companies Covered | Cipla, Lupin, Sun Pharmaceutical Industries Ltd., GSK plc., Cadila Pharmaceuticals, Johnson & Johnson, Shanghai Fudan-Zhangjiang Bio-Pharmaceutical Co., Ltd., Pfizer Inc., Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liposomal Doxorubicin Market Strategic Shifts & Innovations
Manufacturing technology is converging with regulatory science to redefine quality benchmarks for nanomedicine production. These developments are compressing the gap between innovator and generic product performance.
Microfluidic mixing platforms are replacing traditional thin-film hydration methods for liposome formation, enabling tighter control over particle size distribution and encapsulation efficiency. Contract development and manufacturing organizations serving North American and European markets are adopting these systems to meet FDA bioequivalence expectations. The technology is modularizing quality assurance workflows, allowing real-time adjustment of process parameters without batch interruption.
EMA's tightened guidelines on liposomal drug product characterization are mandating orthogonal analytical methods for critical quality attributes. Manufacturers must now demonstrate equivalence in drug-to-lipid ratio, particle morphology, and in vitro drug release profiles. European generic developers are responding by investing in cryo-electron microscopy and asymmetric flow field-flow fractionation capabilities.
Oncology procurement committees are consolidating purchasing decisions at the health-system level rather than individual physician discretion. Hospital networks in Germany and France are negotiating multi-year framework agreements that lock in volume commitments for liposomal chemotherapy agents. This concentration is displacing traditional distributor relationships and compressing price negotiation cycles to annual or biennial intervals.
Liposomal Doxorubicin Market Segmentation
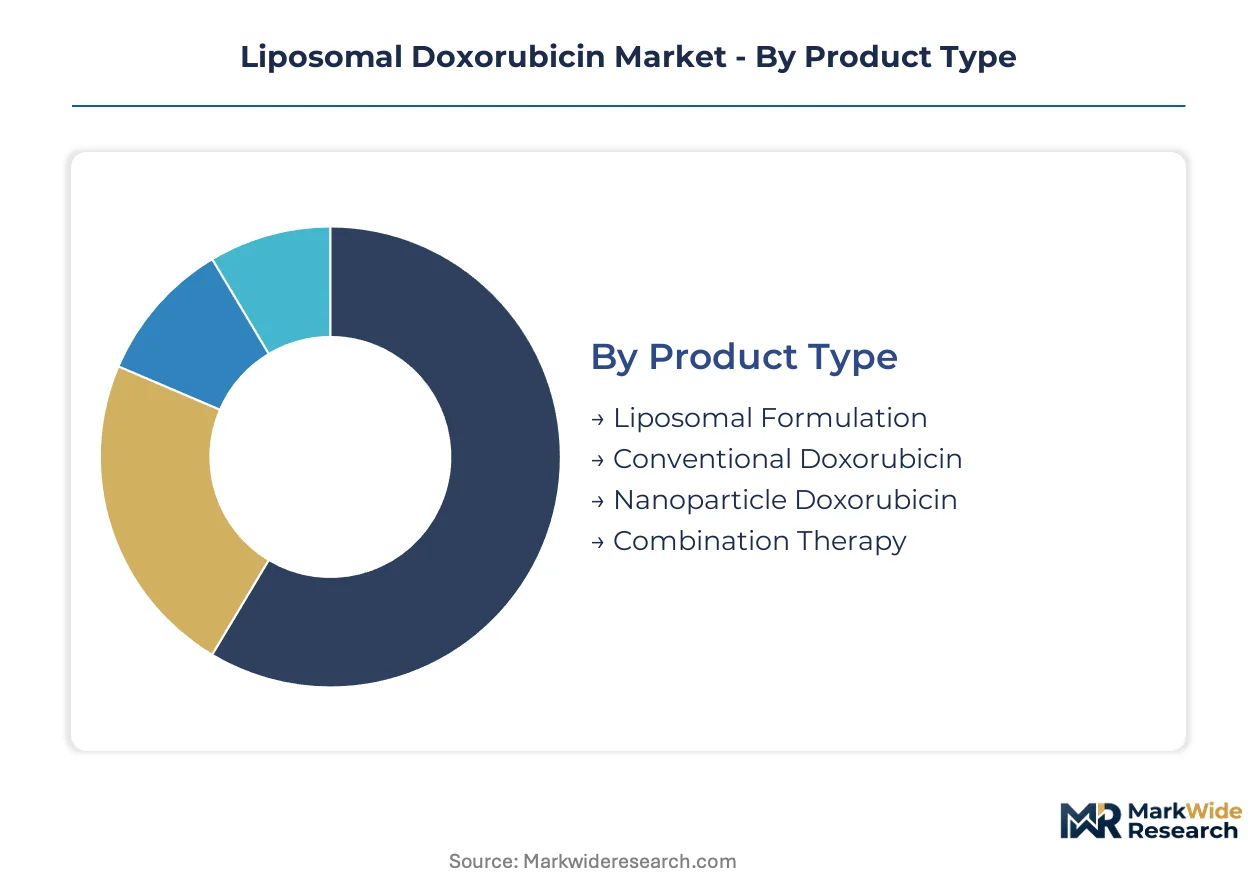
Liposomal doxorubicin segmentation reveals how formulation technology, clinical application, and care setting interact to determine commercial access. Understanding these intersections helps manufacturers align development investment with reimbursement pathways and prescriber workflows.
Product Type:
Volume concentrates in established liposomal platforms, while premium positioning shifts toward next-generation encapsulation technologies.
- Liposomal Formulation:Pegylated liposome-encapsulated anthracycline with approximately 100 nanometer hydrodynamic diameter, engineered for prolonged circulation and enhanced permeability and retention in tumor tissue. Demand concentrates in academic medical centers across the United States and Germany, driven by Medicare and statutory health insurance reimbursement policies that favor cardiotoxicity-sparing regimens in metastatic breast cancer and recurrent ovarian cancer protocols.
- Conventional Doxorubicin:Unencapsulated anthracycline hydrochloride requiring bolus or continuous infusion administration. Prescribing persists in cost-constrained markets and salvage chemotherapy protocols where liposomal cost premiums face formulary exclusion.
- Nanoparticle Doxorubicin:Albumin-bound or polymeric nanoparticle formulations offering alternative biodistribution profiles. Clinical evaluation continues in academic research networks comparing tumor penetration against pegylated liposomal benchmarks.
- Combination Therapy:Liposomal doxorubicin packaged with companion cytotoxics or targeted agents in fixed-dose regimens. Procurement interest is rising in integrated cancer networks seeking protocol standardization.
Today's leader: Liposomal Formulation. Tomorrow's challenger: Nanoparticle Doxorubicin.
Application:
Clinical indication determines pricing power, with adjuvant protocols commanding premium positioning over salvage settings.
- Cancer Treatment:Broad-spectrum oncology applications spanning solid tumors and hematologic malignancies. Volume concentrates in comprehensive cancer centers with established liposomal chemotherapy infrastructure.
- Breast Cancer:Adjuvant and neoadjuvant protocols in HER2-negative and triple-negative subtypes. Academic medical centers in the United States are expanding liposomal anthracycline use to reduce long-term cardiac surveillance burden in curative-intent regimens.
- Ovarian Cancer:Platinum-resistant and recurrent settings where cardiotoxicity-sparing properties enable re-treatment with anthracycline-containing regimens. German and French hospital networks are consolidating procurement decisions at the health-system level for this indication.
- Sarcoma:Kaposi sarcoma protocols, particularly in immunocompromised populations, and soft tissue sarcoma salvage regimens. Brazil's unified health system is incorporating liposomal chemotherapy into national treatment guidelines, opening procurement volumes in Latin America's largest oncology market.
Breast Cancer commands current premium positioning. Ovarian Cancer shows the steepest expansion trajectory as platinum resistance protocols proliferate.
End User:
Site of care shifts determine distribution economics, with infusion center consolidation reshaping channel margins.
- Hospitals:Inpatient oncology units managing acute toxicities and complex comorbidities. German hospital networks are negotiating multi-year framework agreements that lock in volume commitments for liposomal chemotherapy agents.
- Oncology Centers:Outpatient infusion facilities specializing in chemotherapy administration. United States-based centers are prioritizing liposomal formulations as CMS policies favor established liposomal agents over conventional doxorubicin in metastatic settings.
- Research Laboratories:Academic and commercial entities conducting bioequivalence studies, stability testing, and next-generation formulation development. EMA quality guidelines for nanomedicines mandate extensive liposomal characterization that extends development timelines.
- Homecare:Emerging administration setting for stable patients with established vascular access. Regulatory frameworks for home infusion of cytotoxic agents remain underdeveloped in most jurisdictions.
Oncology Centers anchor current volume. Homecare represents the longest-term structural opportunity as administration protocols simplify.
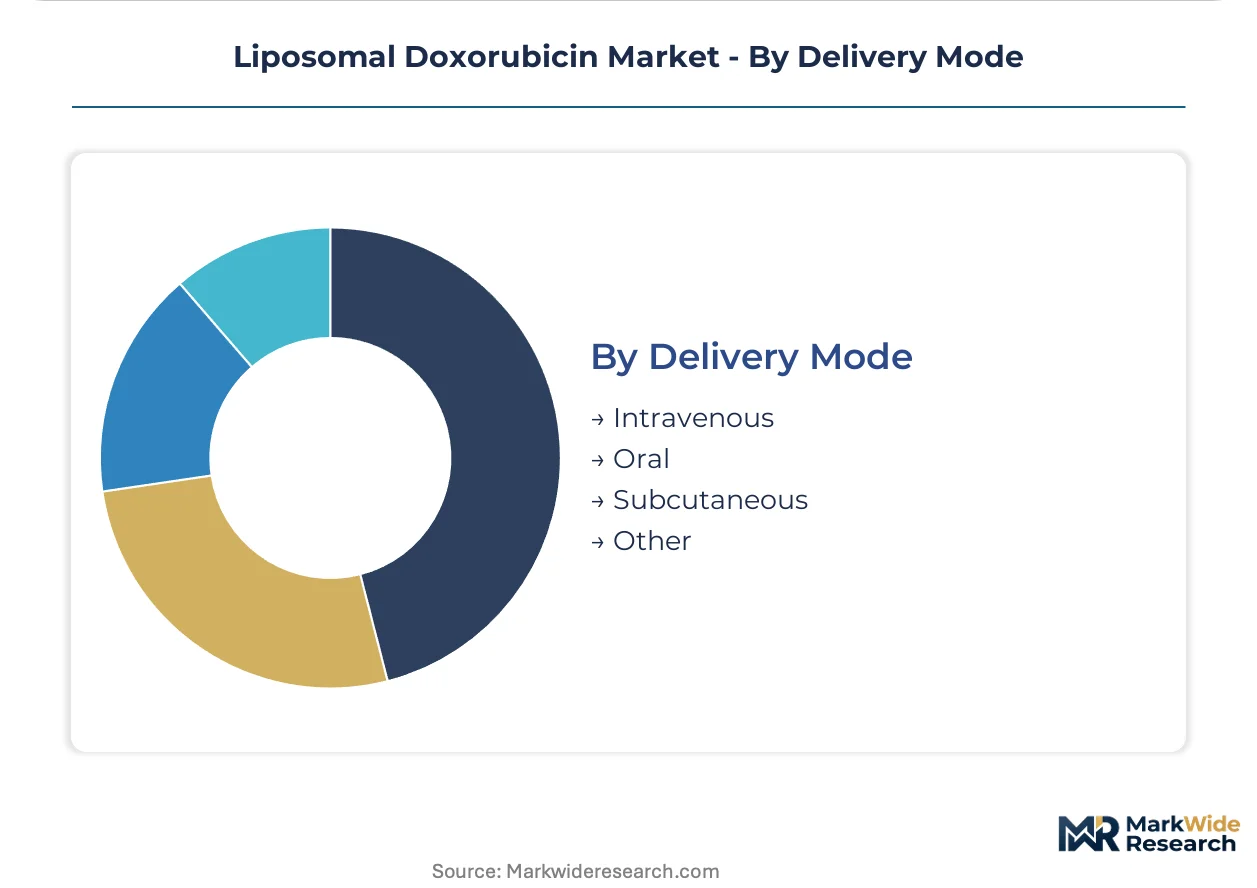
Delivery Mode:
Route of administration constrains formulation design, with intravenous dominance limiting oral bioavailability investments.
- Intravenous:Central and peripheral venous administration of liposomal suspensions requiring controlled infusion rates. All commercially available liposomal doxorubicin products utilize this route, with temperature-sensitive handling requirements constraining distribution logistics.
- Oral:No approved oral liposomal doxorubicin formulations exist due to gastrointestinal degradation and hepatic first-pass metabolism. Preclinical research continues in academic laboratories exploring protective encapsulation strategies.
- Subcutaneous:Investigational administration route for depot formulations. Clinical development faces challenges with local tissue reactions and inconsistent drug release kinetics.
- Other:Intraperitoneal and intravesical administration in specialized gynecologic and urologic oncology protocols. Regional perfusion techniques in sarcoma centers represent niche applications.
Intravenous maintains absolute dominance. Subcutaneous holds theoretical promise for administration cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology formulation scientists and liposomal process engineers concentrate in the United States, Germany, and India, anchoring regional production capabilities and clinical trial infrastructure for advanced nanomedicine development.
United States
FDA bioequivalence standards for complex generics compress development timelines for liposomal formulations. Medicare reimbursement policies favor established liposomal agents over conventional doxorubicin in metastatic breast cancer. Academic medical centers in Boston and New York expand cardiotoxicity-sparing protocols in adjuvant regimens.
Germany
Hospital networks consolidate procurement decisions at the health-system level for ovarian cancer protocols. EMA quality guidelines for nanomedicines mandate extensive liposomal stability testing. The Rhine-Ruhr metropolitan region hosts specialized contract manufacturing organizations serving European markets.
India
Complex generic manufacturing infrastructure sustains supply continuity in regulated markets. CDSCO alignment with WHO prequalification pathways accelerates oncology medicine access programs. Hyderabad and Ahmedabad clusters concentrate extrusion-based encapsulation expertise and active pharmaceutical ingredient production.
China
NMPA regulatory convergence on liposomal characterization methods shapes commercialization feasibility for domestic developers. Shanghai Fudan-Zhangjiang anchors clinical research in pegylated liposome applications. The Yangtze River Delta integrates process analytical technology platforms for real-time release testing.
Brazil
ANVISA incorporation of liposomal chemotherapy into national treatment guidelines opens procurement volumes for Kaposi sarcoma. The unified health system expands access in Latin America's largest oncology market. São Paulo academic medical centers pilot protocol standardization for platinum-resistant settings.
Liposomal Doxorubicin Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across formulation development and manufacturing scale. The vendor base organizes around three strategic archetypes: vertically integrated pharmaceutical conglomerates with legacy clinical data packages, complex generic specialists with extrusion-based encapsulation capabilities, and emerging biotechnology firms with regional market access. Competitive positioning hinges on backward integration into phospholipid supply and strategic partnerships with limited-distribution pharmacy networks.
Among Indian complex generic manufacturers, Cipla and Sun Pharmaceutical Industries Ltd. exemplify the specialist archetype with concentrated liposomal manufacturing infrastructure. Pfizer Inc. occupies a position within the diversified conglomerate tier, leveraging institutional prescriber relationships and legacy oncology portfolios. These three anchors represent distinct competitive vectors: manufacturing scale, regulatory navigation, and clinical data depth.
| Leading Market Players |
|---|
| Cipla |
| Lupin |
| Sun Pharmaceutical Industries Ltd. |
| GSK plc. |
| Cadila Pharmaceuticals |
| Johnson & Johnson |
| Shanghai Fudan-Zhangjiang Bio-Pharmaceutical Co., Ltd. |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Others |
Cost & Logistics Intelligence
Formulation-grade divergence between cardiotoxicity-sparing liposomal platforms and commodity anthracyclines manifests in both procurement premiums and phospholipid sourcing configurations across regulated markets. Medicare reimbursement alignment in the United States and statutory health insurance frameworks in Germany concentrate purchasing power with hospital networks, while hydrogenated soy phosphatidylcholine supply constraints ripple through manufacturing cost structures.
Pricing Analysis
Bundled infusion services versus unbundled drug-only procurement splits the pricing landscape between academic medical centers and cost-constrained salvage settings. Three-tier pricing structure across premium liposomal, standard generic, and economy conventional doxorubicin reflects cardiotoxicity mitigation value and bioequivalence certification depth. Price differentiation hinges on EMA quality guideline compliance and WHO prequalification status. Cost compression in conventional doxorubicin intensifies because of liposomal displacement in metastatic breast cancer protocols. Oncology centers exhibit highest price sensitivity; integrated cancer networks with multi-year framework agreements demonstrate lowest.
Supply Chain Analysis
Hydrogenated soy phosphatidylcholine supply rests on three specialized chemical producers concentrated in Germany, the United States, and India. Extrusion-based encapsulation equipment and long-circulating liposome design expertise draw from Hyderabad and Ahmedabad manufacturing clusters. Temperature-sensitive liposomal suspensions require cold-chain logistics anchored in Rhine-Ruhr and Shanghai distribution hubs. Single-source vulnerability in high-purity phospholipid inputs exposes manufacturers to allocation constraints. Distribution runs through limited-distribution specialty pharmacy networks in the United States and hospital procurement consortia in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liposomal doxorubicin market represents a late-cycle quality story as oncology procurement committees consolidate purchasing decisions and prioritize cardiotoxicity-sparing specifications in curative-intent regimens.
For Market Incumbents: Lock in multi-year framework agreements with German and French hospital networks before biosimilar antibody-drug conjugates displace liposomal anthracyclines in HER2-positive protocols. Secure backward integration into hydrogenated soy phosphatidylcholine supply through captive production or exclusive offtake arrangements with specialized chemical suppliers. Invest in cryo-electron microscopy and asymmetric flow field-flow fractionation capabilities to satisfy tightened EMA bioequivalence expectations.
For New Entrants and Emerging Players: Enter via Brazil's unified health system expansion for Kaposi sarcoma, where ANVISA guideline incorporation creates procurement volume without entrenched incumbent relationships. Target platinum-resistant ovarian cancer segments in academic medical centers seeking second-line anthracycline re-treatment options. Pursue WHO prequalification pathway alignment as the go-to-market angle for low- and middle-income country access programs.
For Investors and Strategic Acquirers: Asymmetric upside sits with complex generic specialists possessing extrusion-based encapsulation infrastructure and active pharmaceutical ingredient backward integration. Long-term viability over the projection horizon depends on regulatory navigation capabilities rather than molecule novelty alone. Acquisition target archetype: Indian manufacturers with CDSCO-aligned WHO prequalification and established liposomal process engineering teams. Watch FDA bioequivalence standard convergence on liposomal characterization methods as the inflection indicator for competitive displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Continuous manufacturing platforms with real-time release testing satisfy FDA expectations for complex generic liposomal production. |
| Regulatory Approval Pathway | WHO prequalification alignment accelerates oncology medicine access in low- and middle-income procurement channels. |
| Backward Integration | Captive hydrogenated soy phosphatidylcholine production insulates against input cost volatility from specialized chemical suppliers. |
| Hospital System Partnership | Multi-year framework agreements with German hospital networks lock in volume commitments for ovarian cancer protocols. |
| Pipeline Diversification | Microfluidic mixing platform adoption enables tighter particle size distribution control for next-generation nanomedicine development. |
Research Approach
Bottom-up oncology center modeling reconciled against top-down liposomal manufacturing capacity tracking forms the analytical core. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov entries, and formulary databases. Triangulation between stakeholder demand signals and supply-side infrastructure assessments ensures segmentation integrity.
Historical trendline analysis of liposomal chemotherapy adoption patterns across academic medical centers anchors the forecast framework. Segmentation dimensions include formulation technology, clinical indication, site of care, and regional regulatory cluster. CAGRs derive from treatment protocol expansion rates and reimbursement policy alignment trajectories. Forecast inputs incorporate CMS policy directional shifts and EMA quality guideline implementation timelines.
Inputs from FDA bioequivalence documentation and EMA nanomedicine quality guidelines were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around volume concentration estimates. Forecasts reflect documented assumptions regarding regulatory convergence velocity and phospholipid supply continuity. A small set of triggers—biosimilar antibody-drug conjugate displacement rates, WHO prequalification pathway expansion, and microfluidic platform adoption curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Hemophilia B Market
Biopharmaceuticals
Ovarian Cancer Drugs Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Bacterial Conjunctivitis Drugs Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
HIV Drugs Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
Recombinant Therapeutic Antibodies and Proteins Market