
 Global Human Recombinant Insulin Market | 2026-2036
Global Human Recombinant Insulin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Human Recombinant Insulin Market Foresight
Yeast-based expression systems are rebalancing production economics away from traditional bacterial fermentation for recombinant insulin manufacturing. Novo Nordisk A/S leverages its integrated fermentation-to-fill capabilities across Denmark and Brazil to sustain cost leadership in long-acting analogs. Eli Lilly and Company anchors North American supply through captive biologics capacity, while Biocon Ltd differentiates via contract manufacturing partnerships that extend its reach into regulated European and US markets.
Human recombinant insulin comprises biosynthetic polypeptide chains produced through recombinant DNA technology, typically expressed in Escherichia coli or Saccharomyces cerevisiae hosts, then purified and folded to achieve biological equivalence with pancreatic human insulin for glycemic control. Long-acting analogs such as glargine and degludec command the dominant share of value owing to patent-protected formulations and reduced hypoglycemia risk profiles, while rapid-acting segments see faster volume growth driven by pump-compatible formulations and post-meal glucose management protocols. Delivery mode segmentation shows insulin pens capturing the majority of outpatient volume, though pump adoption rises among Type 1 Diabetes patients seeking closed-loop integration.
The FDA's biosimilar approval framework and the EMA's scientific advice pathways for biosimilars together shape market entry timelines and interchangeability standards for recombinant insulin products. India's CDSCO and PLI scheme for active pharmaceutical ingredients are accelerating domestic insulin manufacturing scale-up, altering import dependency patterns. Stakeholders must monitor evolving interchangeability designations and biosimilar tender dynamics to calibrate portfolio investments between originator defense and biosimilar expansion strategies.
Market Dynamics
Yeast-based expression systems are displacing bacterial fermentation as the dominant production platform, compressing manufacturing costs while E. coli retains share in rapid-acting analogs where folding efficiency matters less. This technology rotation is redistributing competitive advantage toward integrated biologics manufacturers with proprietary strain development capabilities.
Growth Catalysts
- India's PLI scheme for APIs:Domestic fermentation capacity expansion is lowering import dependency for recombinant insulin raw materials. Tender volumes from government procurement programs are accelerating patient access in tier-2 and tier-3 cities.
- Pump-compatible rapid-acting formulations:Closed-loop artificial pancreas systems are driving demand for ultra-rapid analogs with modified pharmacokinetic profiles. Endocrinology practices in pediatric Type 1 Diabetes are standardizing pump therapy protocols.
- FDA biosimilar interchangeability pathway:Streamlined approval under the Biologics Price Competition and Innovation Act is reducing entry timelines for second-wave biosimilar entrants. Pharmacy-level substitution is expanding volume capture for approved interchangeable products.
Market Restraints
- High-purity water and media input costs:Pharmaceutical-grade fermentation inputs face price volatility tied to energy-intensive purification processes. Batch failure rates in early-scale manufacturing inflate effective production costs.
- Denmark-Brazil supply concentration:Integrated fermentation-to-fill operations cluster in limited geographic corridors, exposing distribution networks to single-site disruption risks. Cold chain integrity requirements compound logistics complexity.
- Immunogenicity testing bottlenecks:Extended analytical validation timelines for biosimilar immunogenicity assessment delay regulatory submissions. Reference product sourcing constraints further compress development windows.
Strategic Opportunities
- Sub-Saharan Africa government tenders:WHO prequalification pathways are opening access to pooled procurement mechanisms for low- and middle-income country health systems. Cold chain infrastructure investments by global health initiatives are enabling distribution reach.
- Continuous manufacturing adoption:Perfusion bioreactor technology convergence with real-time quality monitoring is compressing batch cycle times. Process analytical technology integration is reducing in-process testing burdens.
- Direct-to-clinic distribution models:Bypassing wholesale intermediaries through specialty pharmacy partnerships is improving margin capture for long-acting analog portfolios. Endocrinology clinic consolidation is creating anchor accounts for direct contracting.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise and regulatory CMC writing capabilities command premium compensation, constraining expansion timelines for emerging manufacturers.
- Biosimilar interchangeability study costs:Switching study design and execution for FDA interchangeability designation requires substantial clinical investment with uncertain commercial return timing.
- Legacy vial-to-pen device transition:Manufacturing line reconfiguration for pen assembly and needle safety engineering demands capital deployment ahead of volume certainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Human Recombinant Insulin Market |
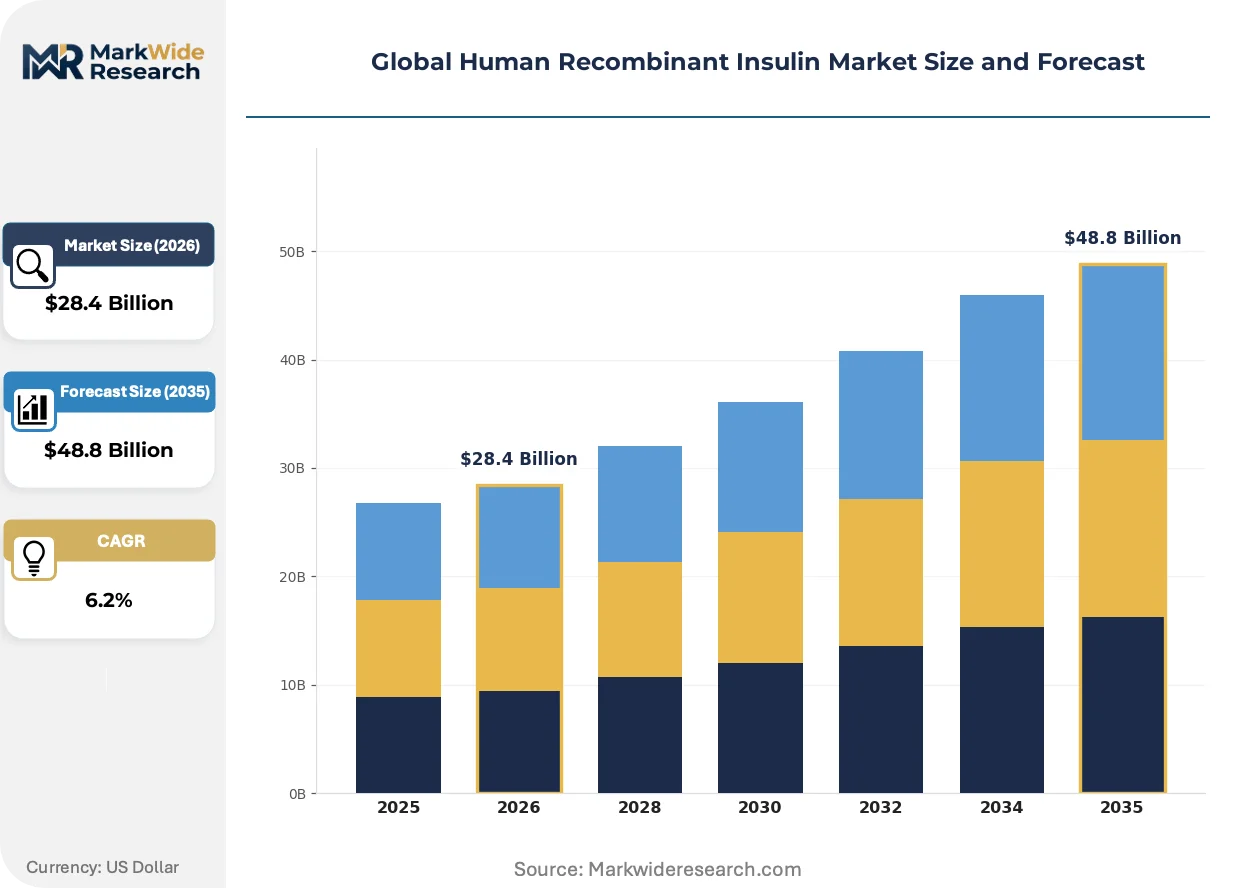
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $48.8 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting, Long-Acting, Intermediate-Acting, Mixed Insulin, Ultra-Long-Acting Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes, Diabetic Ketoacidosis End User: Outpatient Clinics, Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies Delivery Mode: Insulin Pens, Vials & Syringes, Pumps, Jet Injectors, Inhalers |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi S.A., Zhuhai United Laboratories Co., Ltd., Biocon Ltd, Gan & Lee Pharmaceuticals, Ltd., Julphar Gulf Pharmaceutical Industries, Bioton S.A., Tonghua Dongbao Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Human Recombinant Insulin Market Shifts & Advancements
Digital process control systems and modular facility designs are compressing time-to-approval for new manufacturing capacity. Real-time release testing and continuous bioprocessing are converging to redefine quality assurance economics.
Single-use bioreactor technology is automating cleaning validation and changeover procedures in multi-product facilities. Contract manufacturers in India and Eastern Europe are adopting disposable fermentation systems to reduce cross-contamination risks and accelerate product switch flexibility. This automation is enabling smaller batch sizes with faster turnaround, compressing working capital requirements for biosimilar entrants.
The EMA's scientific advice pathway for biosimilar development is clarifying immunogenicity study expectations ahead of formal submission. This regulatory transparency is reducing development program attrition and aligning reference product characterization protocols across member states. Biosimilar sponsors are front-loading EMA engagement to de-risk European market entry timelines.
Hospital procurement consolidation through group purchasing organizations is compressing supplier negotiation cycles and unbundling service components from product pricing. Integrated delivery networks in the United States are standardizing formularies around interchangeable biosimilars, displacing originator volume through pharmacy and therapeutics committee mandates. This concentration is most visible in Medicare Advantage plan coverage decisions affecting long-acting analog access.
Global Human Recombinant Insulin Market Segmentation
Segmentation in recombinant insulin markets reveals distinct technology-performance tradeoffs across molecular formulations, patient phenotypes, and administration modalities. Each axis carries different margin profiles, regulatory burdens, and competitive intensity that shape portfolio construction for manufacturers and procurement strategies for payers.
Product Type:
Molecular engineering of insulin analogs creates differentiated pharmacokinetic profiles that match physiological glucose patterns to clinical endpoints.
- Long-Acting:Glargine and degludec analogs provide basal coverage with reduced nocturnal hypoglycemia risk through modified isoelectric point and acylated side-chain modifications. Demand concentrates in Type 2 Diabetes management protocols across Medicare Advantage formularies in the United States, where once-daily dosing improves adherence metrics tied to quality ratings.
- Rapid-Acting:Lispro and aspart formulations achieve peak activity within 15 minutes through amino acid substitutions that destabilize hexameric aggregates. Pediatric endocrinology practices in Denmark and Germany are standardizing pump-compatible rapid-acting protocols for closed-loop artificial pancreas systems.
- Ultra-Long-Acting:Degludec and insulin icodec variants extend half-life beyond 42 hours via albumin-binding fatty acid acylation, enabling flexible dosing windows.
- Intermediate-Acting:NPH formulations retain cost-sensitive share in government tender programs through simpler manufacturing and no patent protection.
- Mixed Insulin:Premixed rapid-intermediate combinations serve convenience-driven segments in India and Brazil where injection frequency reduction outweighs titration precision.
Long-Acting leads on scale; Rapid-Acting leads on momentum.
Application:
Patient phenotype segmentation determines dosing intensity, complication risk profiles, and reimbursement pathway access.
- Type 2 Diabetes:Progressive beta-cell dysfunction in this population drives escalating insulin initiation rates after metformin failure. India's government procurement programs are expanding access in tier-2 and tier-3 cities through centralized tender mechanisms and cold chain infrastructure investments.
- Type 1 Diabetes:Absolute insulin deficiency mandates lifelong exogenous replacement with intensive monitoring requirements. Pediatric populations in the United States and Germany are migrating toward hybrid closed-loop pump systems that demand ultra-rapid analog compatibility.
- Gestational Diabetes:Pregnancy-specific glycemic targets favor human insulin over analogs due to limited teratogenicity data for newer molecular entities.
- Prediabetes:Early pharmacologic intervention remains controversial; insulin therapy is rarely initiated at this stage.
- Diabetic Ketoacidosis:Acute hyperglycemic crises require intravenous regular insulin in hospital settings, not subcutaneous analog formulations.
Type 2 Diabetes dominates volume capture; Type 1 Diabetes commands premium pricing power.
End User:
Institutional purchasing power and clinical decision autonomy vary sharply across delivery settings.
- Outpatient Clinics:Endocrinology practices and primary care sites generate recurring prescription volume with formulary adherence to integrated delivery network protocols. United States specialty pharmacy distribution is consolidating around interchangeable biosimilar mandates from pharmacy and therapeutics committees.
- Pharmaceutical Companies:Contract manufacturing demand from originators seeking capacity flexibility is expanding in India and Eastern Europe through single-use bioreactor adoption.
- Diagnostic Laboratories:C-peptide and autoantibody testing supports insulin initiation decisions but generates minimal direct product demand.
- Research Institutes:Academic medical centers conduct immunogenicity and pharmacokinetic studies for biosimilar development programs.
Outpatient Clinics anchor commercial volume; Pharmaceutical Companies drive manufacturing services expansion.
Delivery Mode:
Device engineering and user experience design are displacing formulation chemistry as the primary differentiation lever.
- Insulin Pens:Disposable and reusable pen systems with dose memory and needle safety features capture the majority of outpatient volume. Brazil's public health system is transitioning from vial-based distribution to pen devices through Ministry of Health procurement reforms.
- Pumps:Tethered and patch pump systems with continuous glucose monitor integration are gaining share among Type 1 Diabetes patients in Germany and the United States seeking automated insulin delivery.
- Vials & Syringes:Legacy administration persists in cost-constrained settings and hospital inpatient protocols where dose flexibility outweighs convenience.
- Jet Injectors:Needle-free pressure delivery systems serve needle-phobic patients but remain niche due to device cost and bruising risk.
- Inhalers:Pulmonary insulin delivery via Technosphere formulations has limited commercial presence following prior product withdrawals.
Insulin Pens dominate outpatient adoption; Pumps exhibit the steepest expansion trajectory among technology-intensive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's integrated fermentation-to-fill corridor anchors global recombinant insulin supply, with production clusters in Kalundborg and Hillerød feeding distribution networks across regulated markets. Manufacturing gravity concentrates in Northern Europe and select emerging economies where government tender programs and domestic capacity expansion are reshaping patient access patterns.
United States
Medicare Advantage formularies and integrated delivery network procurement are concentrating demand for interchangeable biosimilars. The FDA's biosimilar interchangeability pathway under the Biologics Price Competition and Innovation Act is accelerating pharmacy-level substitution. Indianapolis anchors North American supply through captive biologics manufacturing infrastructure serving specialty pharmacy distribution channels.
Germany
Pediatric endocrinology practices are standardizing hybrid closed-loop pump protocols that demand ultra-rapid analog compatibility. The EMA's scientific advice pathway for biosimilars is clarifying immunogenicity study expectations ahead of formal submission. The Rhine-Main region hosts regulatory consulting clusters supporting biosimilar development program design.
India
Government tender programs and the PLI scheme for active pharmaceutical ingredients are expanding patient access in tier-2 and tier-3 cities. The CDSCO is accelerating domestic insulin manufacturing scale-up through streamlined approval mechanisms. Karnataka's fermentation corridor near Bangalore is attracting contract manufacturing investments from global biosimilar sponsors.
Brazil
Ministry of Health procurement reforms are transitioning public health distribution from vial-based to pen device administration. ANVISA's alignment with WHO prequalification standards is enabling pooled procurement access for Latin American health systems. The São Paulo industrial belt hosts fill-finish operations serving Mercosur distribution networks.
China
Domestic manufacturers are scaling yeast-based expression capacity to serve government procurement volumes in provincial hospital systems. The NMPA's biosimilar guidelines are converging with ICH standards to accelerate local product registration. The Yangtze River Delta biotech corridor is consolidating fermentation expertise for recombinant protein manufacturing.
Global Human Recombinant Insulin Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and regulatory access dimensions. The market structure consolidates around integrated biologics manufacturers with captive fermentation capacity, while contract manufacturing specialists fragment the mid-tier. Three archetypes dominate: vertically integrated originators with end-to-end production control, emerging market champions leveraging domestic tender access, and specialist CDMOs offering single-use bioreactor flexibility. Competitive moves center on biosimilar interchangeability attainment and continuous manufacturing technology licensing.
Among Danish-origin integrated manufacturers, Novo Nordisk A/S exemplifies the originator archetype with fermentation-to-fill capabilities spanning multiple continents. Eli Lilly and Company occupies a position representing North American captive supply strategies. Biocon Ltd sits within the emerging market champion tier, leveraging contract manufacturing partnerships to extend regulatory reach into European and US markets.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi S.A. |
| Zhuhai United Laboratories Co., Ltd. |
| Biocon Ltd |
| Gan & Lee Pharmaceuticals, Ltd. |
| Julphar Gulf Pharmaceutical Industries |
| Bioton S.A. |
| Tonghua Dongbao Pharmaceutical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Government tender consolidation in India and Brazil is compressing supplier margins and forcing manufacturers to reconfigure fermentation scale-up economics toward cost-minimized batch processes. This procurement concentration is redistributing pricing power toward integrated biologics producers with captive strain development capabilities.
Pricing Analysis
Pharmaceutical-grade fermentation media and high-purity water purification costs pass through directly to biosimilar pricing, with energy-intensive inputs creating margin volatility for emerging manufacturers. Three-tier pricing structure across originator, interchangeable biosimilar, and non-interchangeable biosimilar levels stratifies by FDA designation status and immunogenicity certification grade. Pricing pressure stems from Medicare Advantage formulary mandates favoring interchangeable products in the United States. Government tender programs in emerging markets exhibit highest price sensitivity; pediatric closed-loop pump segments in Germany and Denmark show lowest sensitivity due to clinical protocol rigidity.
Supply Chain Analysis
India's PLI scheme for active pharmaceutical ingredients and domestic-content rules in China's provincial hospital procurement are reshaping raw material sourcing toward localized fermentation capacity. Supply concentrates in Denmark, Brazil, and India for integrated fermentation-to-fill operations, with Karnataka's corridor and Kalundborg anchoring strain development expertise. The network draws from Chinese yeast extract suppliers, Indian media component manufacturers, and European chromatography resin producers. Single-site disruption risk in Denmark-Brazil corridors compounds cold chain integrity requirements. Distribution runs through specialty pharmacy channels in regulated markets and government central medical stores in tender-driven economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recombinant insulin market functions as a geographic-arbitrage play where manufacturing cost differentials between India's fermentation corridor and Denmark's integrated sites exceed regulatory compliance cost gaps for biosimilar entrants.
For Market Incumbents: Hedge originator volume erosion by accelerating interchangeable biosimilar pipeline submissions through FDA's BPCIA pathway while securing backward integration into yeast strain development. Novo Nordisk's captive fermentation-to-fill network demonstrates how upstream control over proprietary expression systems defends margin position against second-wave biosimilar price compression. Capacity addition in Brazil's São Paulo industrial belt addresses Mercosur distribution reach without Denmark supply concentration risk. For New Entrants and Emerging Players: Enter via WHO prequalification pathways for Sub-Saharan Africa government tenders where cold chain investments by global health initiatives are enabling distribution reach previously blocked by infrastructure gaps. India's tier-2 and tier-3 cities present the most penetrable geography as CDSCO streamlines domestic manufacturing approvals and PLI scheme subsidies compress capital requirements. Contract manufacturing partnerships with European fill-finish specialists offer the fastest go-to-market angle for regulatory access without captive facility construction. For Investors and Strategic Acquirers: Asymmetric upside sits with emerging market champions possessing domestic tender relationships and single-use bioreactor flexibility for multi-product contract manufacturing. The five-to-ten year viability window favors acquisition targets with EMA scientific advice engagement history and immunogenicity study design capabilities that de-risk European entry timelines. CDSCO approval velocity for domestic manufacturers versus import dependency patterns serves as the critical inflection signal for portfolio reallocation between originator defense and biosimilar expansion strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Biosimilar Interchangeability Attainment | FDA BPCIA pathway approval enables pharmacy-level substitution against originator volume in Medicare Advantage formularies. |
| Continuous Manufacturing Adoption | Perfusion bioreactor integration with real-time quality monitoring compresses batch cycle times for cost leadership. |
| Direct-to-Clinic Distribution | Specialty pharmacy partnerships bypass wholesale intermediaries and improve margin capture for long-acting analog portfolios. |
| Yeast Strain Development Investment | Proprietary Saccharomyces cerevisiae capabilities redistribute competitive advantage away from bacterial fermentation platforms. |
| WHO Prequalification Pathway | Pooled procurement access for low- and middle-income country health systems opens volume capture in Sub-Saharan Africa tenders. |
Research Methodology
Bottom-up patient population modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads at CDSCO and ANVISA, hospital procurement managers in India's government tender programs, and payer access specialists in Medicare Advantage plans combined with secondary validation from FDA biosimilar approval databases, EMA scientific advice pathway records, ClinicalTrials.gov immunogenicity study registrations, and WHO prequalification listings. Triangulation between demand-side prescription volume analysis and supply-side bioreactor utilization data ensures segmentation integrity across molecular formulation and delivery mode dimensions.
Input-output matrices mapping insulin initiation rates by diabetes phenotype against manufacturing batch yields by expression system anchor the forecast framework. Segmentation dimensions modeled include molecular formulation type, patient phenotype, administration modality, regional regulatory cluster, and tender versus retail procurement channel. CAGRs derive from reconciling epidemiological diabetes prevalence trajectories with manufacturing capacity expansion announcements and biosimilar entry probability assessments. Forecast inputs incorporate CDSCO approval velocity metrics, PLI scheme subsidy disbursement patterns, and cold chain infrastructure investment disclosures by global health initiatives.
Inputs from primary fieldwork and disclosed regulatory filings were available through the study window; gaps in real-time biosimilar switching study outcomes and confidential tender pricing introduce uncertainty bands around interchangeability adoption curves. Forecasts reflect documented assumptions regarding FDA designation timelines, EMA scientific advice convergence, and PLI scheme continuation. Biosimilar immunogenicity assessment bottlenecks and reference product sourcing constraints constitute specific risk factors that could compress development windows or accelerate competitive entry. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Interleukin 1 Beta (IL-1β) ELISA Kit Market
Biopharmaceuticals
North America and Europe Pegylated Drugs Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Typhoid Vaccines Market
Biopharmaceuticals
Somatostatin Analogs Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
HIV Drugs Market