
 Theodolite Market | 2026-2036
Theodolite Market Size, Share, and Industry Trends Forecast 2026-2036
Theodolite Market Outlook
Precision-grade instrument specifications is redrawing competitive boundaries in the theodolite landscape. Hexagon AB leverages its integrated sensor software ecosystem to dominate high-accuracy positioning workflows. Topcon Corporation anchors its position through deep R&D intensity in robotic measurement automation. Trimble Inc. specializes in GNSS-integrated field solutions that extend its reach across construction and agricultural surveying verticals.
A theodolite is a precision optical instrument for measuring horizontal and vertical angles in triangulation networks, typically resolving to one arc-second or finer through graduated glass circles and micrometer readers. Its primary commercial purpose centers on establishing geodetic control points, boundary delineation, and structural alignment verification across civil engineering projects. Electronic theodolites with integrated data collectors currently occupy the largest value share as manual optical units retreat to educational and backup applications. Total stations represent the fastest-expanding product category, driven by their convergence of angle measurement, electronic distance measurement, and onboard computation in single-operator workflows. Government agencies constitute the most concentrated end-user segment by contract value, though surveying firms generate higher unit velocity through equipment refresh cycles.
ISO 17123 standards for geodetic instrument field testing shape manufacturer calibration protocols and procurement specifications across public infrastructure tenders. In the United States, FAA survey guidelines for airport obstruction analysis mandate specific angular accuracy classes that filter vendor eligibility. China's GB standards for geospatial instrumentation, administered by SAMR, enforce electromagnetic compatibility and environmental sealing requirements that raise compliance costs for imported equipment. Stakeholders must monitor whether robotic and imaging technology integration triggers reclassification under emerging autonomous measurement equipment regulations.
Market Dynamics
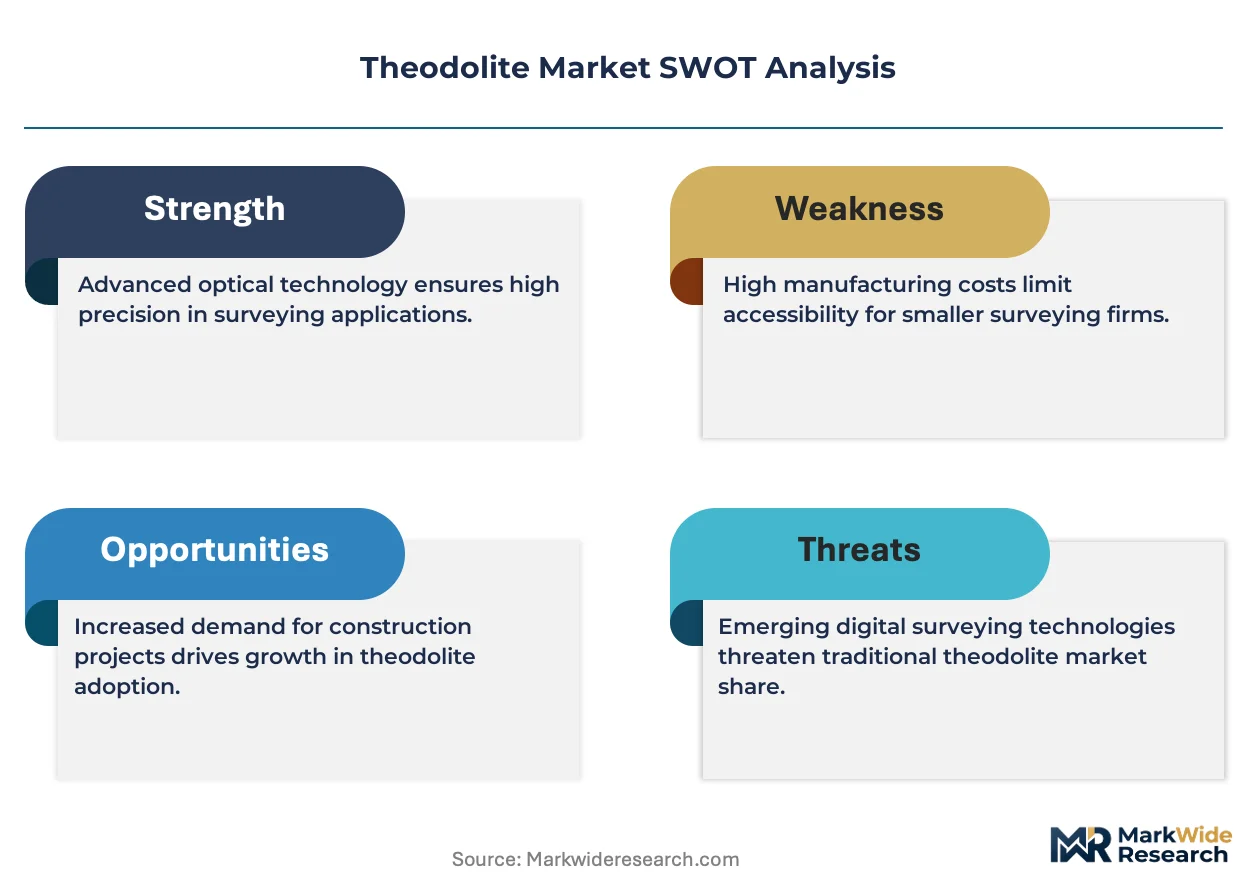
Robotic total station technology is compressing operator skill requirements while expanding single-operator survey coverage, fundamentally restructuring labor economics across geodetic service providers and construction contractors.
Growth Catalysts
- National infrastructure corridors:India's highway and rail expansion programs are generating concentrated demand for precision alignment verification across multiple simultaneous mega-projects.
- ISO 17123 field testing protocols:Standardized calibration requirements are filtering vendor eligibility in public tenders, advantaging certified equipment manufacturers.
- Sensor fusion architectures:Integration of angle encoders with electronic distance measurement modules is collapsing setup times and expanding daily survey throughput.
Market Restraints
- Precision-grade glass circle supply:German and Japanese optical component specialists control critical graduated circle manufacturing, creating single-source vulnerability for arc-second resolution instruments.
- GB standards compliance costs:China's SAMR electromagnetic compatibility and environmental sealing requirements impose testing burdens that extend import certification timelines.
- GNSS-RTK substitution pressure:Satellite-based positioning systems are displacing optical angle measurement in open-sky boundary and topographic applications where centimeter accuracy suffices.
Strategic Opportunities
- Drone photogrammetry convergence:Mounting total stations on UAV platforms for control point densification creates hybrid aerial-terrestrial survey workflows.
- Educational institution refresh cycles:Manual optical theodolites retain replacement demand in university surveying programs across Southeast Asia.
- FAA airport obstruction mandates:Specific angular accuracy classes for runway approach analysis create captive demand for certified instrument procurement.
Industry Challenges
- Geodetic surveyor training pipelines:Robotic automation is reducing field crew sizes while raising demand for software-competent operators capable of coordinate system management.
- Multi-vendor data interoperability:Proprietary data formats from competing total station ecosystems complicate integrated project delivery across mixed-fleet survey contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Theodolite Market |
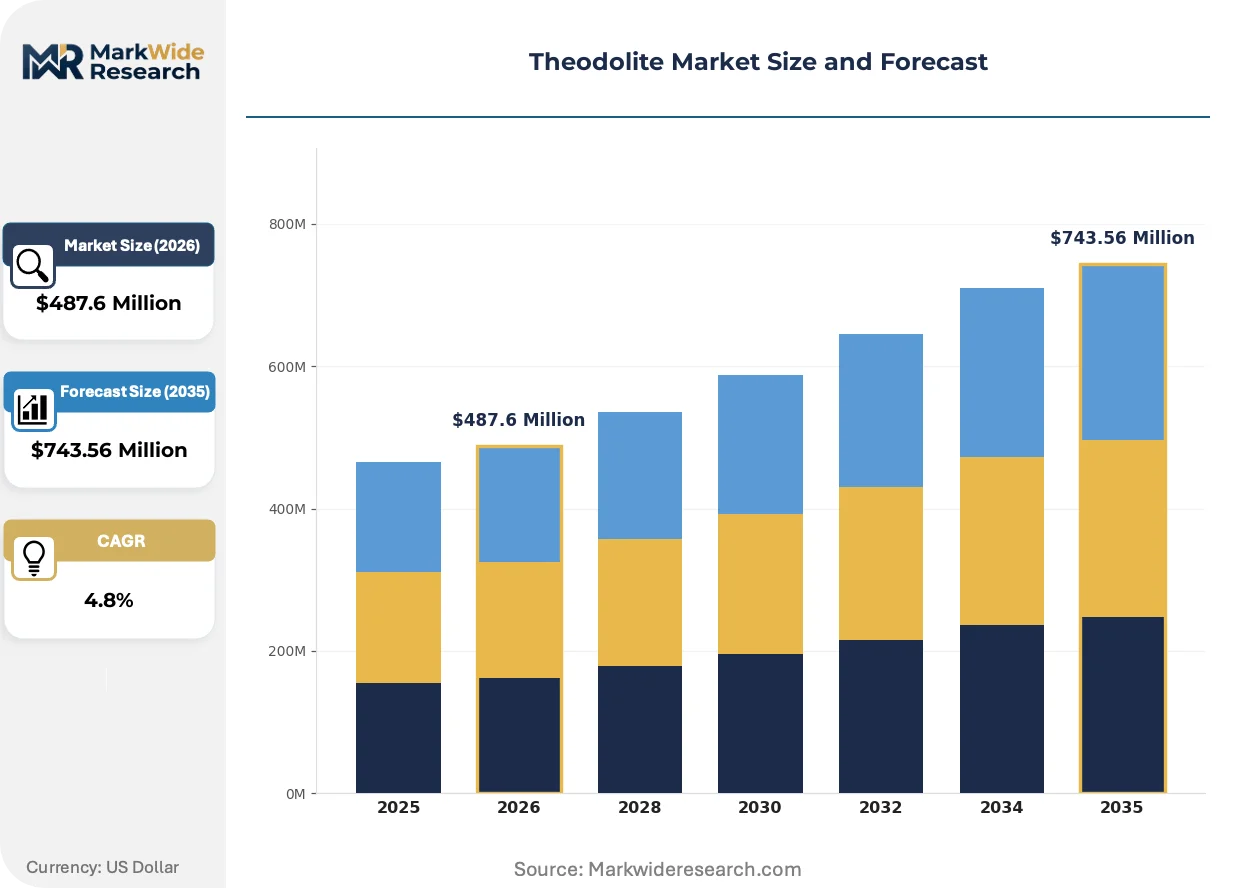
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Theodolites, Optical Theodolites, Electronic Theodolites, Total Stations Application: Construction, Surveying, Engineering, Mining End User: Government Agencies, Surveying Firms, Construction Companies, Educational Institutions Technology: GNSS Integration, Laser Scanning, Robotics, Imaging |
| Companies Covered | Hexagon AB, Topcon Corporation, Trimble Inc., Leica Geosystems AG, Hilti Group, South Surveying & Mapping Technology Co., Ltd., FOIF Co., Ltd., Beijing Bofei Instrument Co., Ltd., Sokkia Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Theodolite Market Strategic Shifts
Measurement automation is compressing field crew sizes while expanding daily data capture volumes, reshaping how survey contractors structure labor and equipment deployment across infrastructure projects.
Integrated imaging technology is embedding high-resolution cameras within total station telescopes for visual documentation of surveyed points. Road and rail alignment contractors in Germany are adopting these units for as-built verification workflows. The convergence of photogrammetric capture with angular measurement is miniaturizing separate instrument payloads into unified field kits.
China's MIIT precision standards for geospatial equipment are tightening certification thresholds for angular resolution and repeatability. Domestic manufacturers are accelerating R&D investment to meet indigenous content preferences in state-funded infrastructure tenders. Imported equipment vendors face extended type-approval timelines as SAMR expands electromagnetic interference testing protocols.
Equipment-as-a-service arrangements are displacing capital purchase models among mid-sized surveying firms facing cash flow constraints from delayed public sector payments. Rental and lease-to-own channels are capturing share from traditional distributor sales in India's fragmented contractor base. This financing flexibility is most visible in highway project clusters where survey duration uncertainty discourages outright ownership commitments.
Theodolite Market Segmentation
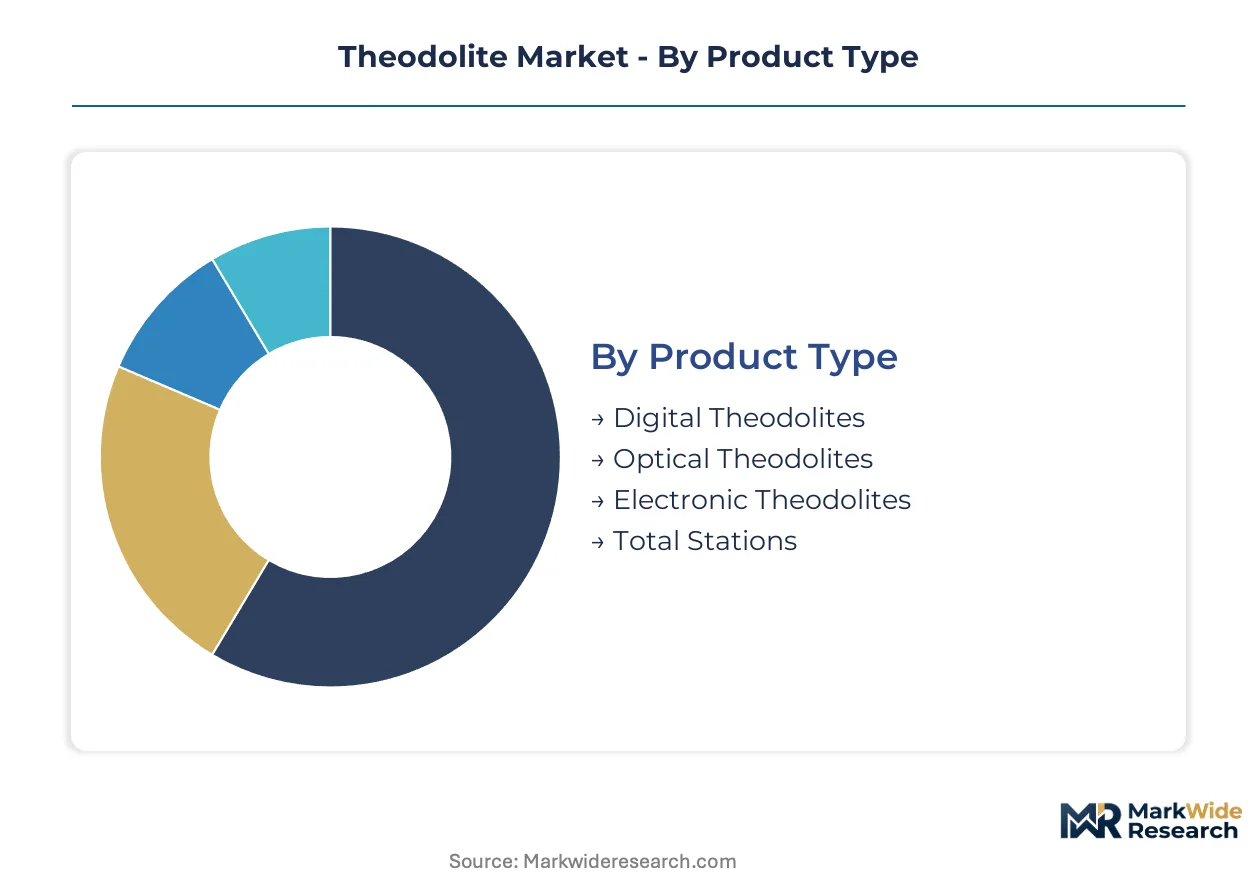
Theodolite procurement patterns diverge sharply across product architectures and operational contexts. Understanding these fault lines clarifies where GNSS substitution poses existential threat versus where optical precision retains irreplaceable value.
Product Type:
Electronic theodolites and total stations face divergent substitution pressures from satellite positioning systems, while manual optical units occupy defensive niches where automation delivers no marginal utility.
- Digital Theodolites:Microprocessor-driven angle encoders replace glass-circle micrometer readers with digital displays and onboard data storage. German construction contractors specify these units for structural alignment verification where centimeter-grade precision suffices and setup speed outweighs arc-second resolution. Demand concentrates in mid-tier civil engineering workflows balancing accuracy against crew productivity.
- Total Stations:Converged instruments integrate electronic distance measurement, angle encoding, and coordinate computation in single-operator robotic platforms. India's highway corridor projects generate concentrated procurement for these units as survey contractors compress crew sizes across simultaneous mega-project sites. The convergence of multiple measurement functions collapses equipment payloads and accelerates daily survey throughput.
- Electronic Theodolites:Transitional architecture combining optical telescopes with electronic angle readout and basic data logging. Retains relevance in budget-constrained surveying operations across Southeast Asian markets.
- Optical Theodolites:Manual micrometer-reading instruments with graduated glass circles. Survives exclusively in educational and regulatory backup applications where electronic failure modes are unacceptable.
Total stations retain volume leadership; total stations hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive infrastructure verticals from cyclical extractive operations where equipment utilization rates dictate procurement economics.
- Construction:Structural alignment, foundation positioning, and as-built verification across building and civil infrastructure projects. Japanese contractors deploy robotic total stations for automated machine guidance in tunneling and bridge construction where millimeter-grade precision prevents costly rework.
- Surveying:Geodetic control network establishment, boundary delineation, and topographic mapping. FAA airport obstruction analysis mandates in the United States create captive demand for certified angular accuracy classes that filter vendor eligibility.
- Engineering:Deformation monitoring, structural health assessment, and industrial installation alignment. Requires highest-precision instrumentation with long-term stability specifications.
- Mining:Pit wall stability monitoring, stockpile volumetrics, and haul road alignment. Cyclical commodity pricing compresses capital budgets and extends equipment replacement cycles.
Construction commands the largest equipment deployment base; surveying generates the highest unit velocity through refresh cycles.
End User:
Customer type determines procurement modality, with government tenders emphasizing certification compliance and private contractors prioritizing financing flexibility.
- Government Agencies:Public infrastructure owners and regulatory bodies specifying equipment for in-house survey operations or contractor compliance verification. ISO 17123 field testing protocols filter vendor eligibility in tender specifications.
- Surveying Firms:Specialized geodetic service providers operating mixed-fleet equipment across project-based contracts. Equipment-as-a-service arrangements displace capital purchases among mid-sized operators facing cash flow constraints.
- Construction Companies:General and specialty contractors deploying instruments for self-performed layout and verification. India's fragmented contractor base drives rental channel penetration.
- Educational Institutions:University surveying programs requiring manual optical units for fundamental training in angle measurement principles. Southeast Asian institutions sustain replacement demand as programs expand.
Government agencies concentrate contract value; surveying firms drive equipment refresh frequency.
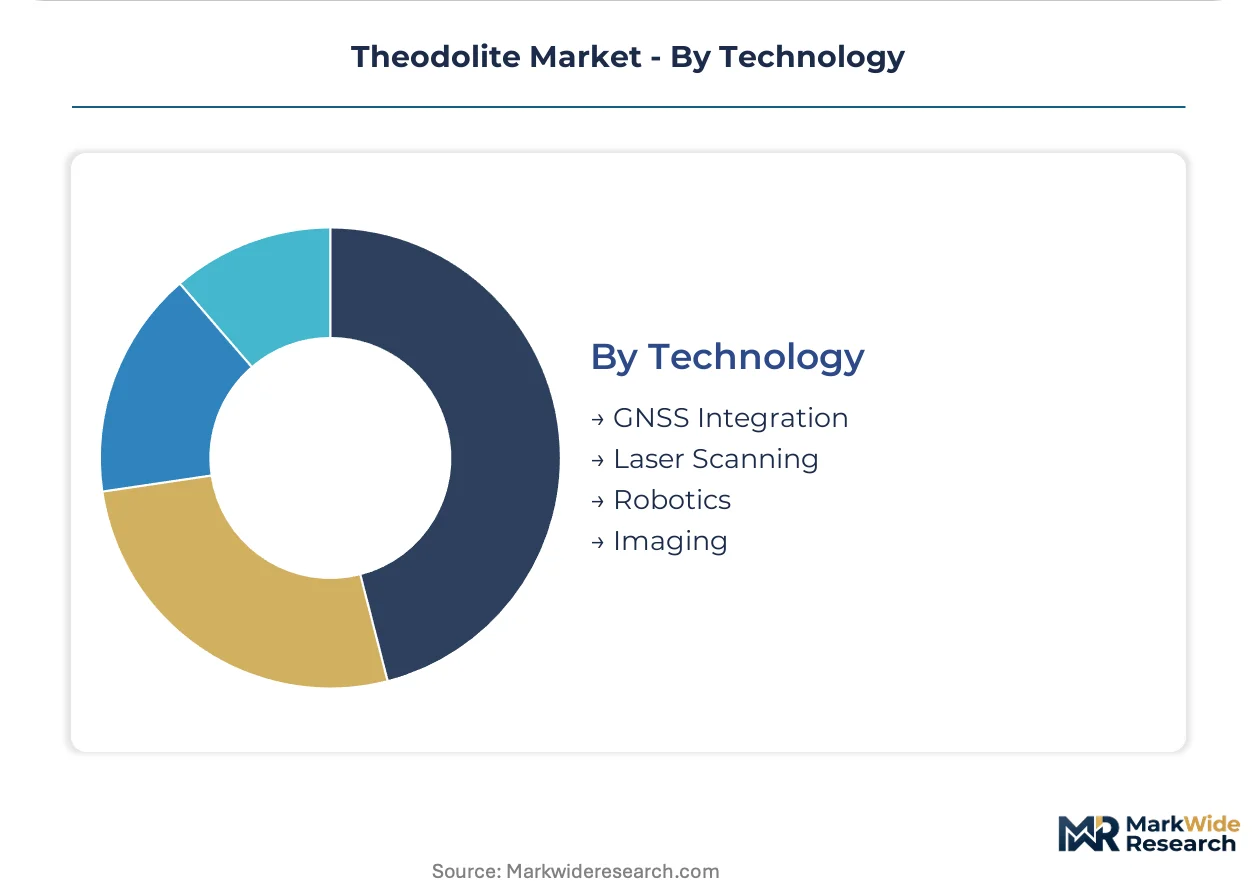
Technology:
Integration maturity separates proven sensor fusion architectures from emerging autonomous measurement modalities facing regulatory ambiguity.
- Robotics:Motorized instrument platforms with automated target recognition and tracking enabling single-operator survey workflows. German and Japanese construction firms expand adoption for infrastructure digitization projects.
- Imaging:Embedded high-resolution cameras within total station telescopes for visual point documentation. Road and rail contractors adopt these for as-built verification workflows.
- GNSS Integration:Combined optical and satellite positioning receivers for hybrid measurement redundancy. Extends operational utility in partially obstructed environments.
- Laser Scanning:High-speed point cloud capture for dense spatial documentation. Convergence with total station platforms creates hybrid terrestrial survey solutions.
Robotics dominates current procurement volumes; imaging gains share fastest in documentation-intensive verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Graduated glass circle manufacturing concentrates in German and Japanese optical component specialists, creating single-source vulnerability for arc-second resolution instruments while demand clusters accelerate across infrastructure corridors in India, China, and the United States.
United States
FAA airport obstruction analysis mandates filter vendor eligibility through specific angular accuracy classes for runway approach surveys. State transportation departments specify ISO 17123-certified instruments in highway construction tenders. Surveying contractors in Texas and California deploy robotic total stations for automated machine guidance in expanding renewable energy and transportation infrastructure projects.
Germany
Construction firms accelerate adoption of robotic total stations for infrastructure digitization and tunneling automation where millimeter-grade precision prevents costly rework. KBA road construction standards and DIN geodetic instrument specifications shape procurement requirements in public tenders. Industrial clusters in Bavaria and Baden-Württemberg host precision optics manufacturers supplying graduated circles to global instrument assemblers.
China
MIIT precision standards for geospatial equipment tighten certification thresholds for angular resolution and repeatability in state-funded infrastructure tenders. SAMR electromagnetic compatibility and environmental sealing requirements extend import certification timelines for foreign equipment vendors. Domestic manufacturers in Beijing and Shanghai accelerate R&D investment to meet indigenous content preferences in national highway and rail corridor projects.
India
National highway and rail corridor mega-projects generate concentrated demand for precision alignment verification across multiple simultaneous construction sites. CEA infrastructure quality standards and BIS certification requirements filter equipment eligibility in government contracts. Surveying services firms in Maharashtra and Gujarat shift toward equipment-as-a-service arrangements to manage cash flow constraints from delayed public sector payments.
Japan
Construction contractors deploy robotic total stations for automated machine guidance in bridge construction and urban tunneling projects. METI industrial standards and JIS geodetic instrument specifications establish calibration protocols for public infrastructure procurement. Precision optics manufacturers in Tokyo and Osaka supply critical graduated circle components to global instrument manufacturers.
Theodolite Market Competitive Environment
Concentration sits with integrated sensor-software ecosystems and precision optics specialists. The vendor base stratifies across three tiers: multinational conglomerates with geospatial divisions, dedicated surveying instrument manufacturers, and regional fabricators serving price-sensitive markets. Dominant competitive moves include R&D intensity in robotic measurement automation and strategic partnerships for drone photogrammetry convergence.
Among Swedish-origin diversified technology groups, Hexagon AB exemplifies the integrated ecosystem archetype. Within Japanese precision instrument specialists, Topcon Corporation and Sokkia Co., Ltd. occupy positions emphasizing measurement automation. Trimble Inc. represents the GNSS-integrated field solutions segment among United States-based positioning technology providers. Chinese surveying equipment fabricators including South Surveying & Mapping Technology Co., Ltd. and Beijing Bofei Instrument Co., Ltd. anchor the regional supply tier serving indigenous content preferences.
| Leading Market Players |
|---|
| Hexagon AB |
| Topcon Corporation |
| Trimble Inc. |
| Leica Geosystems AG |
| Hilti Group |
| South Surveying & Mapping Technology Co., Ltd. |
| FOIF Co., Ltd. |
| Beijing Bofei Instrument Co., Ltd. |
| Sokkia Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Project-based procurement contracts with equipment-as-a-service clauses lock in supply access for surveying firms while capping upfront capital exposure across India's delayed-payment infrastructure corridors. This financing structure feeds back into manufacturer pricing power by fragmenting buyer concentration and extending vendor credit risk.
Pricing Analysis
ISO 17123 field testing protocols dictate the pricing tier structure by filtering vendor eligibility in public tenders and creating certification-premium separation between accredited and non-accredited equipment. Three-tier pricing structure across premium robotic platforms, standard electronic units, and economy manual instruments stratifies by angular resolution grade and after-sales calibration bundling. Pricing pressure stems from GNSS-RTK substitution in open-sky boundary applications where centimeter accuracy displaces optical measurement. Government agencies exhibit lowest price sensitivity due to compliance mandates, while mid-sized surveying firms in India face acute cash-flow constraints driving rental channel preference.
Supply Chain Analysis
Strategic stockpiling of precision-grade glass circles dominates inventory strategy as German and Japanese optical component specialists control arc-second resolution graduated circle manufacturing. Component sourcing concentrates in Germany, Japan, and China, with raw material dependencies spanning optical glass substrates, angle encoder sensors, and electromagnetic shielding alloys. Single-source vulnerability for critical graduated circles creates supply chain risk amplified by SAMR import certification delays. Distribution runs through authorized dealer networks and emerging rental platforms serving fragmented contractor bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The theodolite market tracks infrastructure investment cycles, with national corridor programs in India and China currently compressing replacement timelines and supporting equipment refresh velocity.
For Market Incumbents: Compound defensive positioning through backward integration into precision optics manufacturing to reduce graduated circle supply vulnerability, while accelerating R&D intensity in robotic target recognition to outpace GNSS-RTK substitution threats in high-precision alignment applications. For New Entrants and Emerging Players: Lead with equipment-as-a-service financing models targeting mid-sized surveying firms in India's highway corridor clusters, where cash-flow constraints from delayed public payments create white-space penetration opportunity absent from established vendor relationships. For Investors and Strategic Acquirers: Regional fabricators with indigenous certification pathways in China offer acquisition exposure to state-funded infrastructure preference policies; watch SAMR type-approval timeline compression as inflection signal for import substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Measurement Automation | Compresses crew sizes for German tunneling contractors facing skilled labor shortages. |
| Drone Photogrammetry Convergence | Creates hybrid aerial-terrestrial workflows for India's highway control point densification. |
| Indigenous Certification Investment | Secures MIIT eligibility for domestic vendors in China's state-funded rail tenders. |
| Equipment-as-a-Service Expansion | Captures rental channel share among Maharashtra surveying firms with payment delays. |
| Precision Optics Backward Integration | Reduces single-source dependency on Japanese glass circle manufacturers. |
Study Parameters
A spread of perspectives from surveying firm operations directors, construction contractor equipment managers, geodetic instrument calibration technicians, and public infrastructure procurement officers converged on the working assumptions underlying demand projections. Primary interview insights triangulated against secondary validation from ISO 17123 field testing documentation, FAA airport obstruction survey guidelines, SAMR electromagnetic compatibility filings, and customs trade records for optical instrument imports. Bottom-up equipment deployment estimates across application verticals reconciled with top-down infrastructure investment allocations.
Segmentation dimensions modeled span product architecture, application vertical, end-user procurement modality, and technology integration maturity across the projection horizon. CAGRs derived from historical replacement cycle analysis, infrastructure pipeline visibility, and substitution elasticity between optical and satellite positioning systems. Industry-specific forecast inputs incorporated BIS certification timeline data and CEA quality standard revision schedules.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure commitment levels or accelerated GNSS accuracy improvements would require recalibration. Forecasts reflect documented assumptions regarding regulatory certification stability and precision optics supply continuity. Revision becomes warranted when SAMR import approval timelines or Indian public sector payment cycles cross volatility thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Industrial Ladder Market
Tools
Hand Saw Market
Tools
Floor Saw Market
Tools
Power Tools Market
Tools
Portable Grinders Market
Tools
Cordless Fillet Weld Grinder Market
Tools
Cordless Impact Wrench Market
Tools
Global Cutting Discs Market
Tools
Aluminum Folding Ladders Market
Tools
Tool Pliers Market
Tools
Foldable Ladder Market
Tools
Digital Levels Market
Tools
Adjustable Gripping Hand Tools Market
Tools
Log Splitters Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Spray Painting Machine Market