

Cordless Fillet Weld Grinder Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Fillet Weld Grinder Market Insights
German power tool manufacturing is expanding cordless platform capacity to serve precision metalworking demand. Metabo leverages its Stuttgart engineering base to dominate European distribution of fillet-specific grinding systems. Makita sustains competitive pressure through battery ecosystem compatibility across its cordless portfolio. DeWalt anchors North American positioning with construction-grade durability ratings and channel control through industrial supply chains.
A cordless fillet weld grinder is a battery-powered abrasive finishing tool engineered with narrow-profile heads and variable speed control to clean and shape concave weld joints in restricted access zones. Lithium-ion cell chemistry dominates the power source category due to energy density advantages and fade-free discharge curves during extended grinding cycles. Angle grinder configurations occupy the largest product type share for heavy stock removal in shipbuilding applications, while die grinder variants represent the fastest-growing segment as aerospace manufacturers adopt pencil-style tools for turbine component finishing. Metal fabrication workshops drive baseline volume, though military equipment assembly commands premium pricing through MIL-SPEC certification requirements.
FCC electromagnetic emission standards govern battery management system design for cordless tools sold in the United States, while EU REACH restrictions on cobalt and nickel compounds reshape cell chemistry sourcing for European market access. OSHA lockout/tagout provisions and silica exposure limits further constrain product design parameters for workplace deployment. Stakeholders must monitor evolving battery recycling mandates and cordless platform interoperability standards as these regulatory vectors increasingly determine competitive viability.
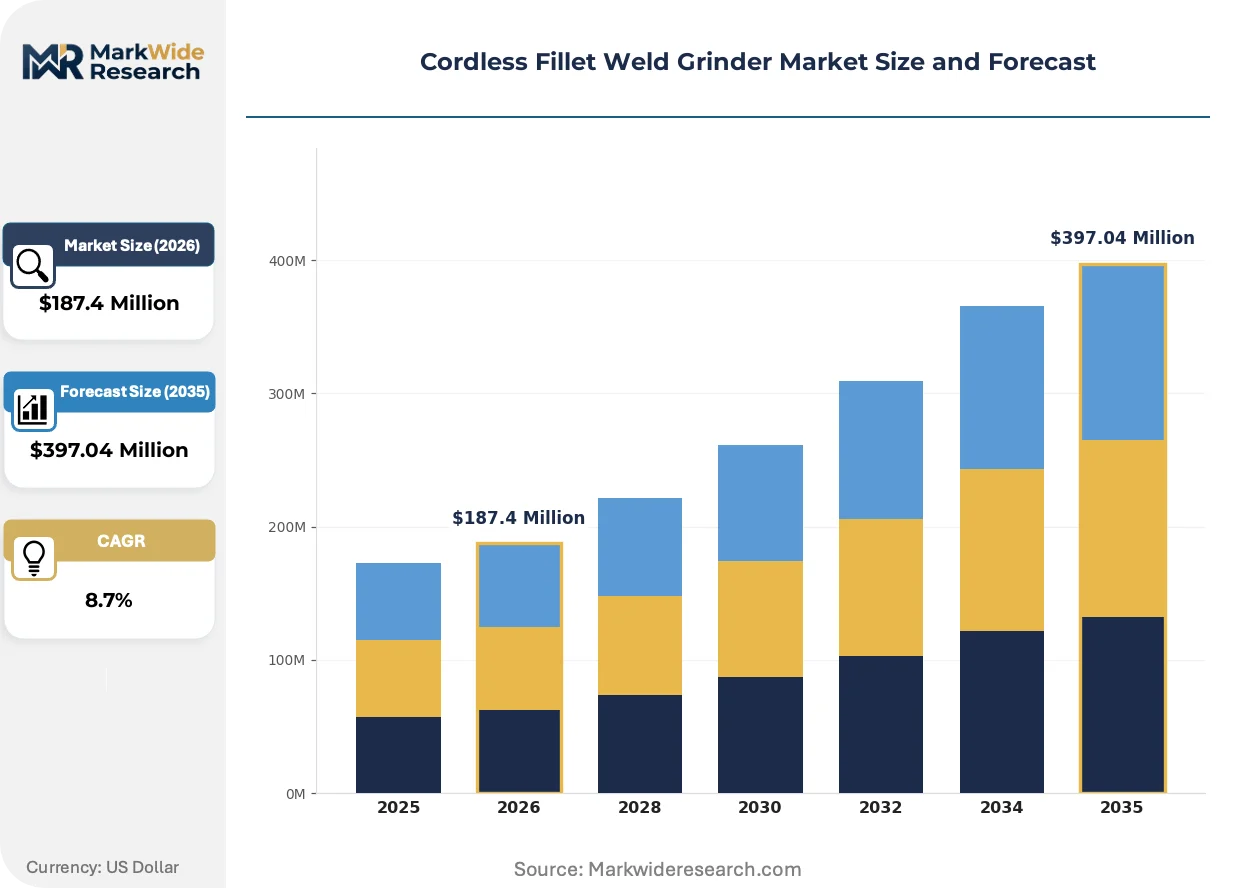
Market Dynamics
Battery platform consolidation is compressing vendor margins as professional buyers demand cross-tool compatibility across their cordless fleets, forcing grinder specialists to integrate with dominant battery ecosystems or surrender procurement access.
Growth Catalysts
- EU REACH cobalt restrictions:Cell chemistry reformulation is accelerating solid-state battery pilot programs for industrial tools, creating first-mover advantages for compliant suppliers.
- Shipbuilding automation:South Korean naval yards are standardizing cordless tool fleets to eliminate pneumatic hose hazards in confined hull compartments.
- Lithium-ion energy density gains:Fade-free discharge curves now sustain 45-minute continuous grinding cycles, matching corded performance for weld-finishing operations.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress gross margins for battery pack integrators unable to pass through costs.
- Brushless motor supply concentration:Precision wound stator production clusters in Shenzhen and Dongguan, exposing procurement to single-region disruption risk.
- Pneumatic tool residual base:Mature fabrication shops in Rust Belt manufacturing zones delay cordless conversion due to sunk infrastructure investment.
Strategic Opportunities
- US Inflation Reduction Act domestic content credits:Battery cell assembly localization incentives reward North American pack manufacturing for federal contractor procurement.
- Aerospace turbine maintenance:Pencil-style die grinders penetrate MRO facilities for blade root fillet finishing where access geometry prohibits angle grinder geometry.
- Tool-as-a-service rental channels:Industrial equipment leasing platforms reduce capital barriers for small fabrication shops entering cordless platforms.
Industry Challenges
- MIL-SPEC certification timelines:Defense contractor qualification protocols extend product launch cycles by 18-24 months for military-grade cordless tools.
- Cross-platform battery interoperability:Proprietary connector standards fragment fleet standardization, forcing procurement teams to manage multiple charging ecosystems.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Fillet Weld Grinder Market Trends and Innovations
Connected tool telemetry and predictive maintenance algorithms are redefining asset management in professional metalworking environments, shifting value capture from hardware sales to uptime guarantees.
Brushless DC motor architectures with integrated Hall-effect sensors are overtaking brushed designs in premium cordless fillet grinders. Aerospace manufacturers in Stuttgart and Toulouse specify sensor-equipped motors for real-time load monitoring during turbine component finishing. This precision feedback capability is compressing warranty claim rates and enabling usage-based service contracts.
OSHA silica exposure limits are mandating integrated vacuum shrouds on all portable grinding equipment deployed in US metal fabrication facilities. The rule forces redesign of narrow-profile fillet heads to accommodate extraction ports without compromising access geometry. California and Texas construction authorities are enforcing the standard earliest, creating regional product specification divergence.
Professional buyers now bundle cordless grinder procurement with fleet management software subscriptions, unbundling after-sales service from hardware transactions. Industrial supply distributors in Germany's Ruhr region and Japan's Kansai corridor are piloting predictive battery replacement programs based on cycle-count telemetry. This consumption-pattern shift transfers inventory risk from end-users to channel partners.
Cordless Fillet Weld Grinder Market Segmentation
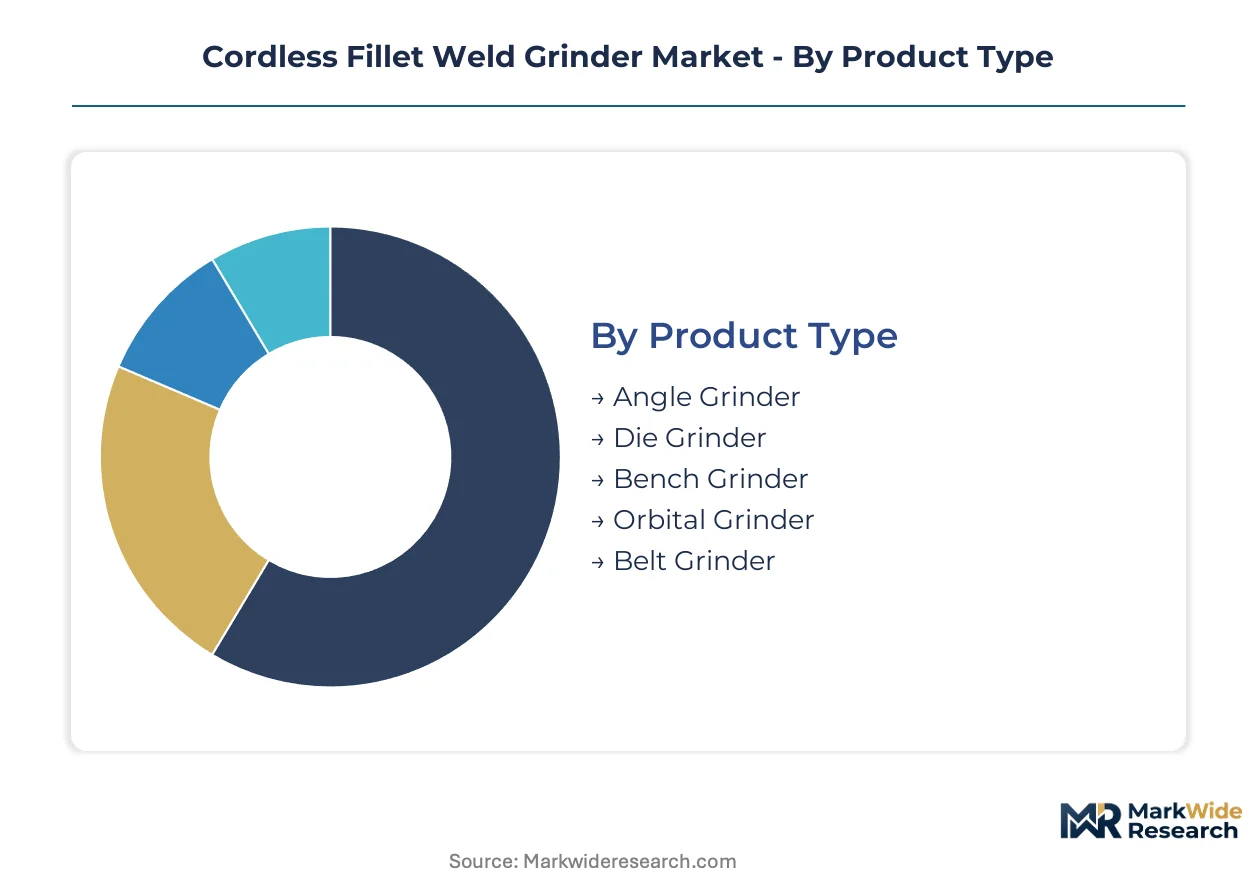
Segmentation in cordless fillet weld grinders reveals how tool specifications align with distinct operational constraints across metalworking environments. Upgrade cycles vary dramatically by product category and end-use intensity, with naval yards replacing fleets faster than job-shop fabricators.
Product Type:
Replacement cycles accelerate where tool geometry directly determines access capability in confined weld zones.
- Angle Grinder:Heavy-duty configurations with 4.5-inch to 5-inch disc capacity dominate shipbuilding hull compartments for rapid stock removal. South Korean naval construction programs are standardizing these units across cordless fleets to eliminate pneumatic hose trip hazards.
- Die Grinder:Pencil-style narrow heads with collet sizes from 1/8-inch to 1/4-inch enable turbine blade root finishing where angle grinder geometry cannot penetrate. Aerospace MRO facilities in Toulouse and Stuttgart specify these units for precision fillet work on nickel superalloy components.
- Bench Grinder:Stationary cordless variants serve mobile repair stations in field construction environments where permanent installation is impractical.
- Orbital Grinder:Random-orbit heads with integrated extraction ports address OSHA silica compliance in California metal fabrication shops.
- Belt Grinder:Narrow belt configurations clean longitudinal weld seams in structural steel applications where disc geometry leaves witness marks.
Angle Grinder sits at the top of the volume ranking, with Die Grinder climbing the fastest.
Power Source:
Cell chemistry selection tracks energy density requirements against regulatory constraints on hazardous material content.
- Battery Lithium-ion:18650 and 21700 cylindrical cells with nickel-manganese-cobalt cathodes deliver fade-free discharge curves sustaining 45-minute continuous grinding cycles. EU REACH cobalt restrictions are forcing cathode reformulation toward nickel-rich chemistries with reduced cobalt dependence.
- Battery Nickel-Cadmium:Legacy cylindrical cells retain residual demand in Eastern European fabrication shops with sunk charging infrastructure investments, though cadmium content faces tightening disposal regulations.
- Battery Nickel-Metal Hydride:Intermediate energy density chemistry serves price-sensitive procurement in developing industrial markets where lithium-ion premiums compress margins.
- Solar Powered:Photovoltaic charging stations support remote pipeline maintenance crews operating beyond grid access in Australian outback and Saudi desert environments.
- Capacitor Powered:Supercapacitor banks enable rapid charge-discharge cycles for intermittent spot-grinding applications where battery weight penalizes operator fatigue.
Battery Lithium-ion commands the dominant procurement share, while Solar Powered gains traction fastest in off-grid infrastructure segments.
Application:
End-use specifications diverge sharply between volume-driven fabrication and certification-intensive defense procurement.
- Metal Fabrication:General-purpose workshops in Germany's Ruhr region and Japan's Kansai corridor drive baseline volume through standardized 18V platform adoption.
- Shipbuilding:Hyundai Heavy Industries and DSME yards in South Korea are converting entire cordless fleets to eliminate pneumatic distribution systems in double-hull compartments.
- Aerospace Manufacturing:Safran and Rolls-Royce turbine divisions specify MIL-SPEC-certified die grinders with Hall-effect sensor feedback for blade root finishing operations.
- Heavy Machinery Production:Caterpillar and Komatsu assembly lines integrate cordless grinders into lean manufacturing cells to reduce work-in-process handling time.
- Military Equipment Assembly:Defense contractor qualification protocols extend product launch cycles by 18-24 months, but command 40-60% price premiums over commercial equivalents.
Metal Fabrication generates the highest unit volume, with Military Equipment Assembly expanding most quickly through federal procurement mandates.
End User:
Customer scale determines whether procurement prioritizes capital efficiency or fleet standardization across tool categories.
- Fabrication Workshops:Small and mid-sized job shops in Texas and Ohio adopt tool-as-a-service rental models to reduce cordless platform entry costs.
- Aircraft Manufacturers:Airbus and Boeing tier-one suppliers mandate cross-platform battery compatibility to simplify charging infrastructure across mixed fleets.
- Shipbuilders:South Korean and Chinese naval yards specify angle grinder dominance for hull construction, with die grinder penetration growing in superstructure finishing.
- Heavy Equipment Manufacturers:Deere and CNH Industrial procurement teams bundle cordless grinder orders with fleet management software subscriptions.
- Defense Contractors:Lockheed Martin and BAE Systems facilities require MIL-SPEC certification and domestic content compliance under US Inflation Reduction Act provisions.
Fabrication Workshops represent the broadest customer base, with Defense Contractors posting the steepest expansion trajectory through security-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial belt concentrates precision metalworking demand, while South Korean shipyards drive naval procurement volumes at contrasting scale and specification intensity.
United States
Defense contractor procurement through Lockheed Martin and BAE Systems facilities commands MIL-SPEC certification premiums. OSHA silica exposure limits and lockout/tagout provisions constrain cordless grinder deployment parameters in metal fabrication shops. Texas and Ohio job-shop clusters adopt tool-as-a-service rental models to reduce cordless platform entry barriers.
Germany
Automotive subcontractors in Stuttgart and metal fabrication clusters across the Ruhr region prioritize cordless mobility for confined weld-finishing operations. EU REACH restrictions on cobalt and nickel compounds reshape cell chemistry sourcing for European market access. Metabo leverages its Stuttgart engineering base to dominate regional distribution of fillet-specific grinding systems.
South Korea
Hyundai Heavy Industries and DSME naval yards are converting entire cordless fleets to eliminate pneumatic distribution hazards in double-hull compartments. The country's national industrial safety regulator tightens ergonomic standards for portable grinding equipment in shipbuilding environments. Busan-Ulsan shipbuilding corridors standardize angle grinder configurations for hull construction acceleration.
Japan
Kansai corridor fabrication workshops drive standardized 18V platform adoption through industrial supply distributors. METI battery recycling mandates and cordless platform interoperability standards determine competitive viability for tool manufacturers. Osaka-based metalworking clusters pilot predictive battery replacement programs based on cycle-count telemetry.
China
Brushless motor supply concentration in Shenzhen and Dongguan exposes procurement to single-region disruption risk for international tool assemblers. MIIT industrial equipment standards and dual carbon goals accelerate domestic battery cell capacity expansion. Yangtze River Delta manufacturing hubs integrate cordless grinders into lean production cells for heavy machinery assembly.
Cordless Fillet Weld Grinder Market Competitive Landscape
German producers anchor one tier; Japanese specialists hold another through battery ecosystem dominance. The vendor base stratifies between consolidated power tool conglomerates with multi-category cordless platforms and focused grinding equipment specialists serving niche industrial segments. Three archetypes define competitive positioning: battery ecosystem integrators leveraging cross-tool compatibility, precision engineering houses dominating aerospace-specification segments, and construction-grade durability specialists controlling industrial distribution channels. Geographic expansion through regional distribution partnerships and portfolio diversification into connected tool telemetry represent the dominant competitive vectors.
Within the battery ecosystem tier, Makita and DeWalt exemplify platform consolidation strategies that compress specialist margins through fleet standardization demands. Among German precision engineering houses, Metabo occupies a position reflecting Stuttgart-based metalworking heritage. These three anchors represent divergent responses to professional buyer demands for cross-tool battery compatibility, with each sitting within distinct geographic and application-specialization coordinates that shape their competitive exposure to platform interoperability pressures.
| Leading Market Players |
|---|
| Metabo |
| FLEX |
| C. & E. FEIN |
| Aerotech Abrasives |
| Suhner |
| 3M |
| Makita |
| Bosch |
| DeWalt |
| Others |
Pricing and Supply Chain Analysis
Solid-state battery pilot programs for industrial tools are simultaneously elevating R&D cost burdens and concentrating procurement leverage among first-mover suppliers with EU REACH-compliant cathode formulations. This technology transition compresses margins for battery pack integrators unable to secure long-term lithium carbonate offtake agreements while rewarding vertically integrated cell manufacturers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta cell manufacturing zones are reshaping price floors for lithium-ion packs serving cordless grinder OEMs. Three-tier pricing structure across premium, standard, and economy levels separates MIL-SPEC-certified defense contractors from automotive subcontractors and general fabrication workshops. Pricing pressure stems from raw material input swings in lithium carbonate markets that compress gross margins for non-integrated pack assemblers. Fabrication workshops in Texas and Ohio exhibit highest price sensitivity, while aerospace turbine divisions at Safran and Rolls-Royce accept premium positioning for sensor-equipped die grinder configurations.
Supply Chain Analysis
Workforce availability constraints in Shenzhen and Dongguan precision winding facilities are tightening brushless motor lead times for international tool assemblers. Supply concentrates in China for stator production, South Korea for cathode active materials, and Japan for battery management system semiconductors. Raw material dependencies span lithium carbonate from Chilean and Australian extraction operations, cobalt from DRC refining streams, and nickel from Indonesian processing hubs. Single-source vulnerability in Guangdong motor manufacturing clusters exposes procurement continuity to regional disruption risk. Distribution runs through industrial supply distributors in Germany's Ruhr region, Japan's Kansai corridor, and North American construction equipment rental channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between South Korean shipbuilding procurement at volume scale and German precision metalworking at specification intensity, with EU REACH compliance costs creating divergent margin profiles across European and Asian manufacturing footprints.
For Market Incumbents: Hedge against battery platform consolidation by securing cross-tool compatibility certifications with dominant 18V and 36V ecosystems or risk procurement exclusion from fleet standardization mandates. Deepen backward integration into cell assembly through US Inflation Reduction Act domestic content incentives to defend margin position against raw material volatility. Prioritize MIL-SPEC certification investment to capture defense contractor premiums that offset commercial pricing softness. For New Entrants and Emerging Players: Capture tool-as-a-service rental channel penetration in Rust Belt fabrication zones where sunk pneumatic infrastructure delays cordless conversion. Target aerospace MRO facilities in Toulouse and Stuttgart with pencil-style die grinder configurations purpose-built for turbine blade root access geometry. Pursue fleet management software bundling as the primary go-to-market angle to differentiate from hardware-only incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among German precision engineering houses with aerospace-specification heritage and proprietary narrow-profile head designs. Long-term viability over the coming decade hinges on successful navigation of solid-state battery transition timelines and cordless platform interoperability standardization. Monitor EU battery recycling mandate implementation velocity as the critical inflection indicator for competitive repositioning requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Assembly | US Inflation Reduction Act credits reward North American pack manufacturing for federal contractor access. |
| MIL-SPEC Certification Investment | Defense contractor qualification protocols extend launch cycles but command substantial price premiums. |
| Connected Tool Telemetry Development | Predictive maintenance algorithms shift value capture from hardware sales to uptime guarantee subscriptions. |
| Cross-Platform Battery Compatibility | Fleet standardization demands from professional buyers compress margins for non-integrated specialists. |
| Integrated Vacuum Shroud Redesign | OSHA silica exposure limits in California and Texas force narrow-profile head geometry accommodation. |
Research Methodology
Direct dialogue with maintenance directors at metal fabrication facilities, OEM procurement teams at shipbuilders and aerospace manufacturers, aftermarket service heads at industrial supply distributors, and battery pack engineering leads grounded qualitative findings. Secondary validation drew from SEC filings of power tool conglomerates, OSHA regulatory dockets on silica exposure limits, EU REACH substance restriction updates, and customs data on lithium-ion cell trade flows. Bottom-up and top-down triangulation reconciled channel inventory estimates with production capacity disclosures.
Bottom-up modeling built from product-level unit economics across angle grinder, die grinder, and specialty configurations, while top-down analysis anchored aggregate demand to shipbuilding output indices and aerospace MRO spending patterns. Segmentation dimensions spanned product geometry, cell chemistry tier, end-use certification intensity, and regional regulatory cluster. CAGRs were derived from elasticity-calibrated demand curves incorporating replacement cycle acceleration in naval yards and platform conversion delays in mature fabrication shops. Forecast inputs included lithium carbonate price trajectory assumptions and cordless fleet penetration rates by end-use vertical.
Underlying measurement precision varies by segment; military equipment assembly and aerospace manufacturing carry tighter precision than dispersed fabrication workshop demand. Forecasts reflect documented assumptions on battery energy density improvement curves and regulatory compliance timeline enforcement. Material deviation in EU cobalt restriction implementation or South Korean naval procurement acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.